
 Global Carbon-Neutral Fuels Market | 2026-2036
Global Carbon-Neutral Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon-Neutral Fuels Market Analysis
Long-term offtake contracting between renewable fuel producers and hard-to-abate industrial buyers is reconfiguring how carbon-neutral molecules reach end markets. Shell Plc leverages its integrated trading infrastructure to secure pipeline access for synthetic fuels across European ports. Carbon Engineering anchors its position through direct air capture paired with Fischer-Tropsch synthesis, controlling feedstock purity from atmospheric CO2. TotalEnergies S.E. competes by extending its existing biorefinery footprint into e-fuel coproduction at French industrial sites.
Carbon-neutral fuels are energy carriers manufactured to net-zero carbon intensity through biological or electrochemical processes, typically requiring lifecycle emissions verification below 20 gCO2e/MJ for certification in advanced markets. Their primary purpose is displacing fossil-derived gasoline, diesel, jet fuel, and natural gas in applications where electrification remains technically constrained. Synthetic fuels produced via electrolysis and Fischer-Tropsch synthesis command premium positioning due to scalability and compatibility with existing combustion infrastructure, while biomass conversion through fermentation sustains cost advantages in ethanol supply for light-duty transportation. Hydrogen as a fuel type occupies a transitional role, with demand concentrating where pipeline retrofitting and salt cavern storage already exist.
The EU Green Deal and its delegated acts on renewable fuels of non-biological origin shape product standards and offtake eligibility across European ports. EPA's Renewable Fuel Standard and California's Low Carbon Fuel Standard create parallel compliance markets that determine which production methods qualify for credits in US distribution. Stakeholders must monitor how certification schemes for carbon accounting evolve, as divergent lifecycle methodologies between jurisdictions will determine which production pathways secure long-term offtake financing.
Market Dynamics
Long-term offtake contracting between renewable fuel producers and hard-to-abate industrial buyers is reconfiguring how carbon-neutral molecules reach end markets. Shell Plc leverages its integrated trading infrastructure to secure pipeline access for synthetic fuels across European ports.
Growth Catalysts
- EU Green Deal Delegated Acts:Binding renewable fuels of non-biological origin mandates in maritime and aviation sectors create guaranteed demand floors for e-fuel producers scaling Fischer-Tropsch synthesis.
- Electrolyzer cost curves:Alkaline and solid oxide electrolysis capital costs are declining, compressing levelized production costs for green hydrogen feedstock in German and Dutch industrial clusters.
- Aviation decarbonization deadlines:International Air Transport Association net-zero commitments by 2050 force long-haul carriers to procure synthetic kerosene where battery-electric propulsion remains technically unviable.
Market Restraints
- Biomass feedstock competition:Agricultural residues and energy crops face competing demand from biochemicals and animal feed, constraining fermentation-based ethanol expansion in Brazilian and US Corn Belt supply basins.
- Grid carbon intensity variance:Electrolytic hydrogen production in coal-heavy electricity markets fails to meet EU Taxonomy thresholds, disqualifying output from premium certification schemes.
- Carbon capture scale limits:Direct air capture deployment remains concentrated in Iceland and Texas due to geothermal and stranded gas advantages, creating geographic supply bottlenecks for synthetic fuel carbon feedstock.
Strategic Opportunities
- US Inflation Reduction Act hydrogen hubs:$7 billion in DOE funding for regional clean hydrogen networks creates offtake infrastructure for e-fuel producers targeting California Low Carbon Fuel Standard compliance markets.
- Maritime ammonia fuel conversion:Two-stroke engine retrofits for ammonia combustion open a new addressable segment for green ammonia producers serving container shipping routes between Rotterdam and Singapore.
- Power-to-liquid coproduction:Integration of electrolysis with existing refinery hydrogen networks allows synthetic kerosene and naphtha output from shared infrastructure in French and Spanish petrochemical complexes.
Industry Challenges
- Lifecycle emissions verification:Divergent carbon accounting methodologies between EU Renewable Energy Directive and California LCFS create certification friction for cross-border fuel shipments.
- Electrolyzer engineering talent scarcity:Specialized skills in solid oxide cell manufacturing and high-pressure hydrogen handling concentrate in German and Danish industrial clusters, constraining global deployment velocity.
- Pipeline injection standards:Hydrogen embrittlement risks in existing natural gas networks require material upgrades or dedicated hydrogen infrastructure, complicating distribution economics for blended fuel gases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon-Neutral Fuels Market |
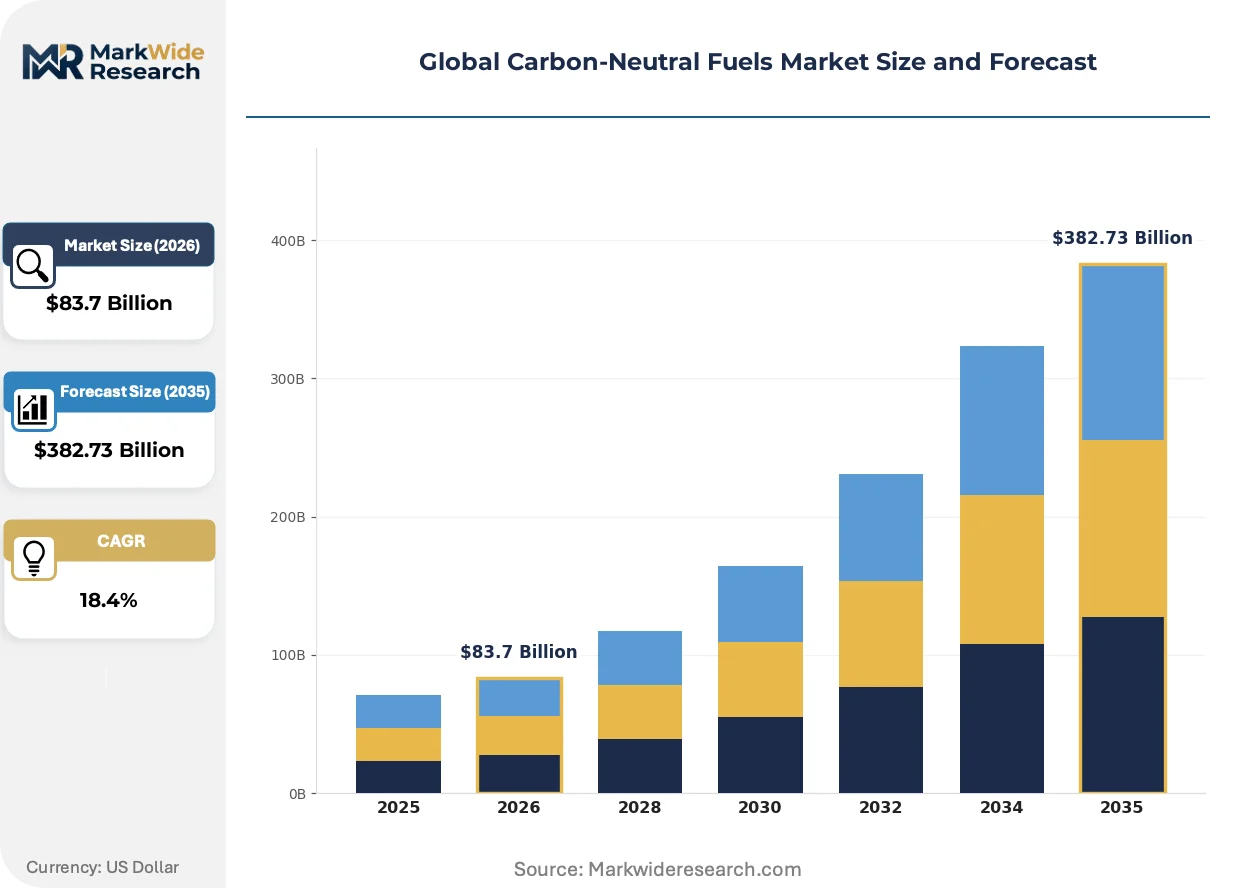
| Market Size in 2026 | $83.7 Billion |
| Market Size in 2035 | $382.73 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Biodiesel, Ethanol, Hydrogen, Renewable Natural Gas Production Method: Synthetic Fuels, Biomass Conversion, Electrolysis, Fermentation End User: Transportation, Power Generation, Industrial, Residential Distribution Channel: Retail, Wholesale, Direct Supply, Online Sales |
| Companies Covered | Carbon Engineering, Shell Plc, ExxonMobil Corporation, TotalEnergies S.E., Archer Daniels Midland Company, POET, LLC, Raízen S.A., Enerkem, Ørsted, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon-Neutral Fuels Market Emerging Trajectories
Synthetic fuel production pathways are fragmenting as certification schemes harden carbon intensity thresholds and end-users demand molecule-level traceability. Three convergent developments are compressing technology adoption cycles and reshaping competitive positioning.
Power-to-liquid synthesis via solid oxide electrolysis coupled with Fischer-Tropsch upgrading is migrating from demonstration pilots to commercial-scale modules. Aviation fuel buyers in Germany and the Netherlands are contracting 10-year offtake agreements for synthetic kerosene ahead of EU ReFuelEU Aviation mandates. This technology migration is compressing the cost gap between e-fuels and fossil-derived sustainable aviation fuel from hydrotreated esters.
California's Low Carbon Fuel Standard credit banking reforms and EPA Renewable Fuel Standard pathway approvals for renewable natural gas are tightening qualification criteria for imported biofuels. Industrial buyers must now document feedstock origin and land-use change impacts to maintain credit eligibility. The US compliance market is responding by concentrating procurement on domestic biogas upgrading facilities with verified manure and wastewater feedstock chains.
Maritime fuel buyers are unbundling bunker procurement from vessel chartering contracts to access certified e-methanol and ammonia supplies. Container lines operating Asia-Europe routes through the Port of Rotterdam are establishing direct supplier relationships with electrolytic fuel producers, bypassing traditional oil major intermediaries. This channel disintermediation is most visible in Northern European port clusters where EU FuelEU Maritime regulations impose escalating greenhouse gas intensity limits.
Global Carbon-Neutral Fuels Market Segmentation
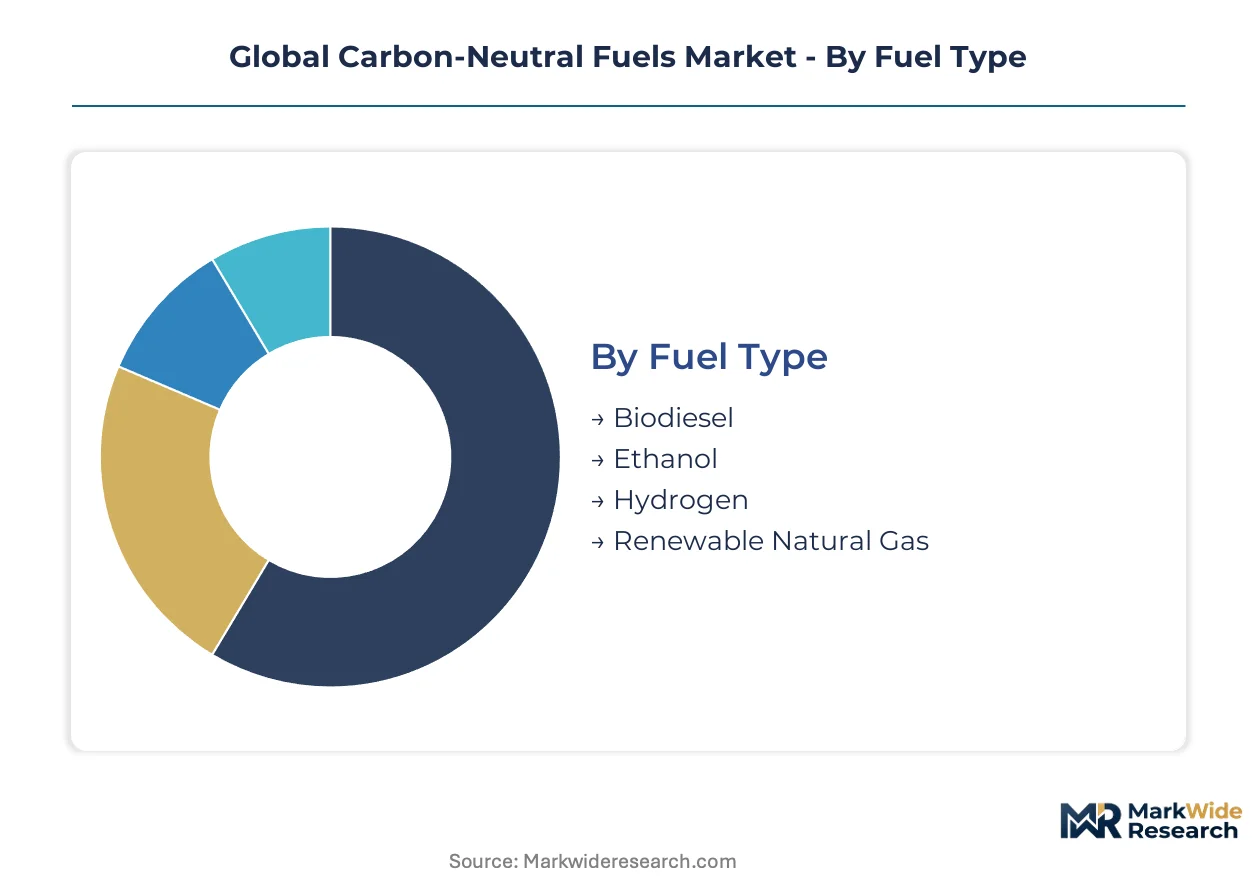
Carbon-neutral fuel procurement patterns diverge sharply across end-use applications and production pathways, with certification requirements and infrastructure compatibility determining which segments command premium pricing. Understanding these divides reveals where capital deployment concentrates and which molecule types face scaling constraints.
Fuel Type:
After-sales service intensity varies dramatically across fuel categories, with hydrogen requiring specialized handling protocols and continuous purity monitoring that biodiesel and ethanol markets simply do not demand.
- Synthetic Fuels:Produced via Fischer-Tropsch synthesis or methanol-to-gasoline processes, these drop-in replacements achieve full compatibility with existing combustion engines and aviation turbines without infrastructure modification. Demand concentrates in German aviation clusters and Rotterdam maritime corridors where EU ReFuelEU mandates enforce escalating blending quotas, though electrolyzer capacity bottlenecks constrain near-term supply expansion.
- Biodiesel:Fatty acid methyl ester derived from vegetable oils and animal fats serves as the most mature carbon-neutral liquid fuel, with established cold-flow property management for temperate climates. Procurement in US Midwest agricultural belts and Brazilian soy processing regions leverages existing crushing infrastructure, yet feedstock competition from food and oleochemical markets limits volume growth.
- Ethanol:Fermentation-based alcohol fuel dominates light-duty vehicle compliance markets in Brazil and US Corn Belt states, with anhydrous and hydrous grades differentiated by water content specifications.
- Hydrogen:Gaseous and liquid forms serve industrial feedstock and emerging heavy transport applications where salt cavern storage and pipeline retrofits already exist in Netherlands and Germany.
By volume, ethanol leads. By growth pace, synthetic fuels are expanding most quickly.
Production Method:
Capital intensity and feedstock security define competitive positioning across production pathways, with electrolysis requiring the steepest upfront investment but offering the most defensible carbon accounting.
- Synthetic Fuels:Power-to-liquid processes combining electrolytic hydrogen with captured carbon dioxide yield fully specified drop-in fuels for aviation and maritime compliance. German industrial clusters around Hamburg and Rotterdam port authorities anchor offtake contracting for these molecules, with direct air capture feedstock sourcing concentrated in Iceland and Texas due to geothermal and stranded gas cost advantages.
- Biomass Conversion:Thermochemical processing of lignocellulosic feedstocks through gasification and pyrolysis pathways produces intermediate syngas for subsequent fuel synthesis. US Department of Energy loan guarantee programs and Brazilian agricultural research corporation Embrapa pilot facilities drive technology maturation, though feedstock logistics costs erode margins at scale.
- Electrolysis:Alkaline and solid oxide cell technologies split water into hydrogen and oxygen using renewable electricity, with stack degradation rates and precious metal catalyst loadings determining operational economics.
- Fermentation:Microbial conversion of sugars and starches into ethanol remains the lowest-cost pathway for carbon-neutral liquid fuels, with Brazilian sugarcane mills achieving the most favorable energy balance ratios globally.
By installed capacity, fermentation dominates. By capital deployment velocity, electrolysis is gaining share fastest.
End User:
Regulatory compliance deadlines and electrification feasibility boundaries segment demand across sectors, with hard-to-abate applications commanding sustained premium pricing.
- Transportation:Aviation and maritime sectors face binding EU mandates on renewable fuel of non-biological origin content, with long-haul trucking following California Low Carbon Fuel Standard credit market dynamics. Shell Plc and TotalEnergies S.E. structure ten-year offtake agreements with German flag carriers and Rotterdam container lines to secure synthetic kerosene and e-methanol volumes ahead of regulatory enforcement dates.
- Industrial:Steel, cement, and ammonia producers procure hydrogen and synthetic methane as process heat and feedstock substitutes where direct electrification remains thermodynamically impractical. German chemical complexes in Ludwigshafen and Leuna anchor demand clusters with existing pipeline hydrogen networks.
- Power Generation:Peaking plants and grid balancing services utilize renewable natural gas and hydrogen blending to maintain dispatchable capacity under EU Taxonomy sustainability criteria.
- Residential:District heating networks in Nordic countries and Netherlands incorporate biomethane injection where building stock retrofit rates lag decarbonization targets.
By current offtake volume, transportation leads. By contract tenor extension, industrial buyers are moving ahead.
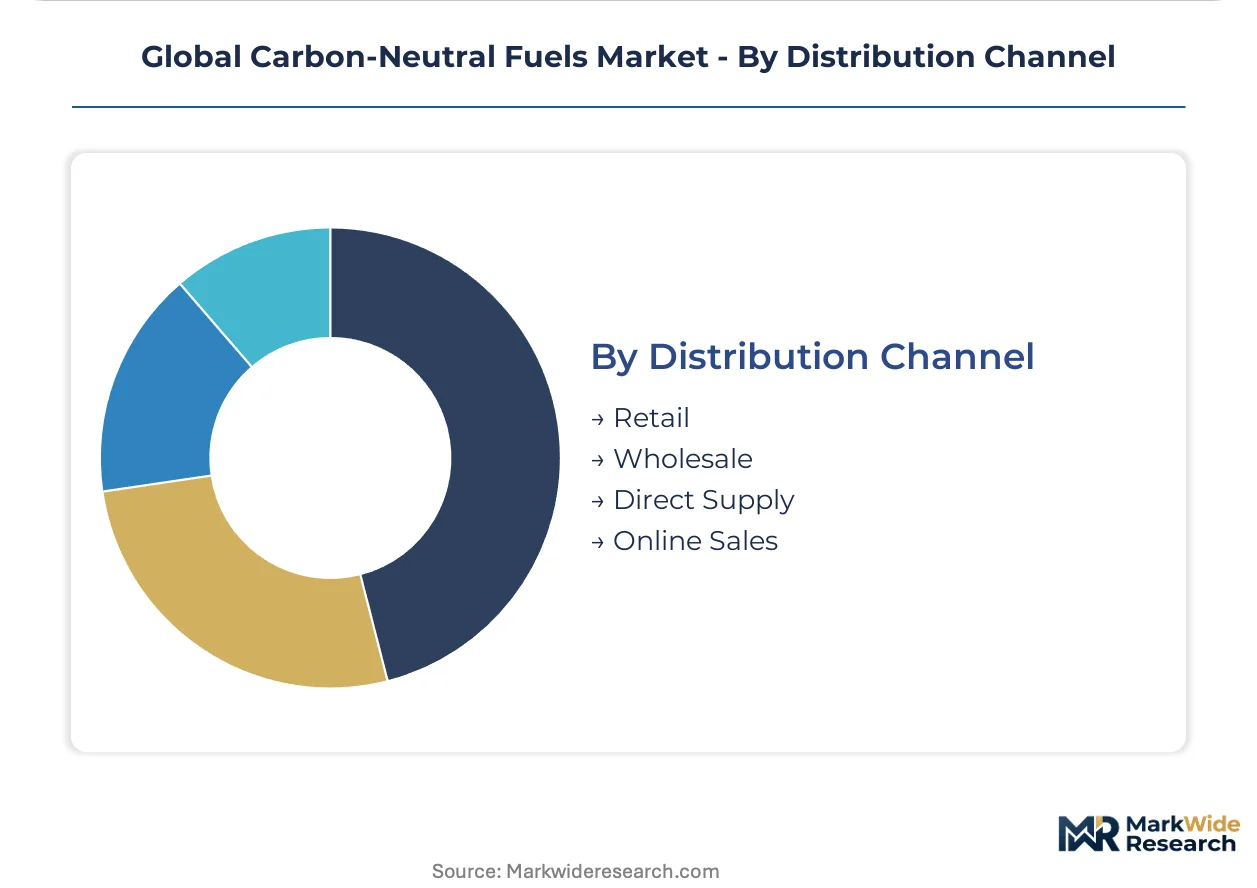
Distribution Channel:
Channel selection reflects molecule type, buyer scale, and certification complexity, with direct supply relationships proliferating where traceability requirements intensify.
- Direct Supply:Long-term offtake contracting between producers and hard-to-abate industrial buyers bypasses traditional intermediaries, with Rotterdam and Singapore port authorities facilitating direct supplier relationships for certified e-methanol and ammonia. Carbon Engineering and European electrolyzer developers negotiate bilateral agreements with aviation fuel procurement desks to secure pipeline access and storage terminal capacity.
- Wholesale:Aggregators and trading houses manage molecular blending and certification documentation for mid-scale buyers lacking dedicated procurement infrastructure, with EU Renewable Energy Directive compliance verification bundled into supply contracts.
- Retail:Branded fuel stations and bunkering services deliver blended products to light-duty vehicle and small vessel operators with standardized certification tiers.
- Online Sales:Digital procurement platforms emerge for carbon credit verification and certificate-of-origin trading separate from physical molecule delivery.
By transaction count, wholesale leads. By margin retention, direct supply is pulling ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in carbon-neutral fuels concentrates where EU Green Deal mandates enforce binding quotas, while US producers compete on tax credit arbitrage without equivalent demand floors. Germany commands premium offtake terms for synthetic kerosene. Texas and Louisiana capture cost advantages in renewable natural gas through existing biogas infrastructure.
Germany
Aviation decarbonization deadlines drive synthetic kerosene procurement from Frankfurt and Munich airport hubs. The EU ReFuelEU Aviation mandate enforces escalating blending quotas from 2025 onward. Industrial clusters around Hamburg and Leuna anchor electrolyzer deployment for e-fuel production, with pipeline hydrogen networks feeding Fischer-Tropsch synthesis facilities.
United States
California Low Carbon Fuel Standard credit markets concentrate demand for renewable natural gas and ethanol in Midwest agricultural supply basins. EPA Renewable Fuel Standard pathway approvals determine which production methods qualify for compliance credits. Gulf Coast petrochemical complexes in Texas and Louisiana leverage stranded gas assets for blue hydrogen feedstock in early-phase e-fuel pilots.
Netherlands
Rotterdam port authority certification schemes for e-methanol and ammonia attract maritime fuel buyers operating Asia-Europe container routes. EU FuelEU Maritime regulations impose greenhouse gas intensity limits on bunker fuels from 2025. Industrial zones in the Port of Rotterdam and Chemelot cluster house electrolyzer capacity serving ammonia-to-fuel conversion projects.
Brazil
Sugarcane ethanol maintains cost leadership in light-duty vehicle compliance markets through favorable energy balance ratios. National biofuel policy RenovaBio establishes carbon intensity targets for fuel distributors. São Paulo state milling complexes dominate anhydrous and hydrous ethanol output, with pipeline corridors feeding coastal export terminals.
China
Dual carbon goals accelerate green hydrogen pilot projects in Inner Mongolia and Xinjiang where renewable electricity curtailment is highest. National Energy Administration guidelines prioritize electrolyzer manufacturing scale-up through 2025. Yangtze River Delta industrial parks near Shanghai test methanol-to-gasoline synthesis for heavy transport applications.
Global Carbon-Neutral Fuels Market Vendor Landscape
Integrated energy majors and specialized synthetic fuel developers split the market along capital intensity and technology control vectors. The vendor base concentrates around three strategic archetypes: legacy oil majors repurposing refinery infrastructure, pure-play e-fuel developers controlling direct air capture feedstock chains, and agricultural processors leveraging fermentation expertise for ethanol supply. Competitive moves center on long-term offtake contracting for aviation and maritime compliance markets, plus electrolyzer manufacturing partnerships to secure stack supply.
Within the integrated major tier, Shell Plc and TotalEnergies S.E. exemplify players repositioning trading infrastructure and biorefinery footprints for synthetic fuel coproduction. Carbon Engineering occupies a distinct position as a pure-play developer anchoring project economics through captive direct air capture carbon feedstock. Among agricultural processors, Archer Daniels Midland Company and POET, LLC represent established ethanol suppliers facing margin pressure from e-fuel competition in road transport segments.
| Leading Market Players |
|---|
| Carbon Engineering |
| Shell Plc |
| ExxonMobil Corporation |
| TotalEnergies S.E. |
| Archer Daniels Midland Company |
| POET, LLC |
| Raízen S.A. |
| Enerkem |
| Ørsted |
| Others |
Supply Flow & Price Mechanics
Electrolyzer stack supply bottlenecks from German and Danish manufacturing clusters determine both the premium spread for certified e-fuels and the geographic clustering of Fischer-Tropsch synthesis facilities. This single-source dependency for solid oxide cell production compresses margins for synthetic kerosene buyers while concentrating pricing power with integrated energy majors controlling captive hydrogen networks.
Pricing Analysis
Configured-to-order pricing for synthetic kerosene certified under EU ReFuelEU Aviation mandates commands spreads of 40-60 percent above standard renewable diesel tiers, with differentiation driven by lifecycle carbon intensity verification and direct air capture feedstock provenance. Long-term offtake contracting dominates the pricing model, though spot market liquidity is emerging in Rotterdam bunker corridors. Pricing pressure stems from electrolyzer capital cost compression as Chinese alkaline stack manufacturers enter European supply chains. Aviation fuel procurement desks at Frankfurt and Munich airport hubs exhibit the lowest price sensitivity, while regional road fuel distributors in Eastern European markets resist premium tiers without blending mandates.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk for electrolyzer stack imports, with German customs authorities scrutinizing origin documentation for green hydrogen equipment. Manufacturing gravity centers on Germany, Denmark, and China for electrolyzer assembly, while direct air capture feedstock sourcing concentrates in Iceland and Texas due to geothermal and stranded gas cost advantages. Raw material dependencies include iridium catalysts from South African mining operations, nickel alloy membranes from Russian metallurgical complexes, and polymer electrolyte membranes from Japanese chemical producers. Distribution runs through Rotterdam and Hamburg port authorities for maritime e-methanol, with pipeline injection into German hydrogen networks serving industrial clusters in Ludwigshafen and Leuna.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German aviation carriers and Rotterdam container lines executing ten-year offtake agreements, fragmenting procurement leverage for mid-scale industrial users without dedicated supply infrastructure.
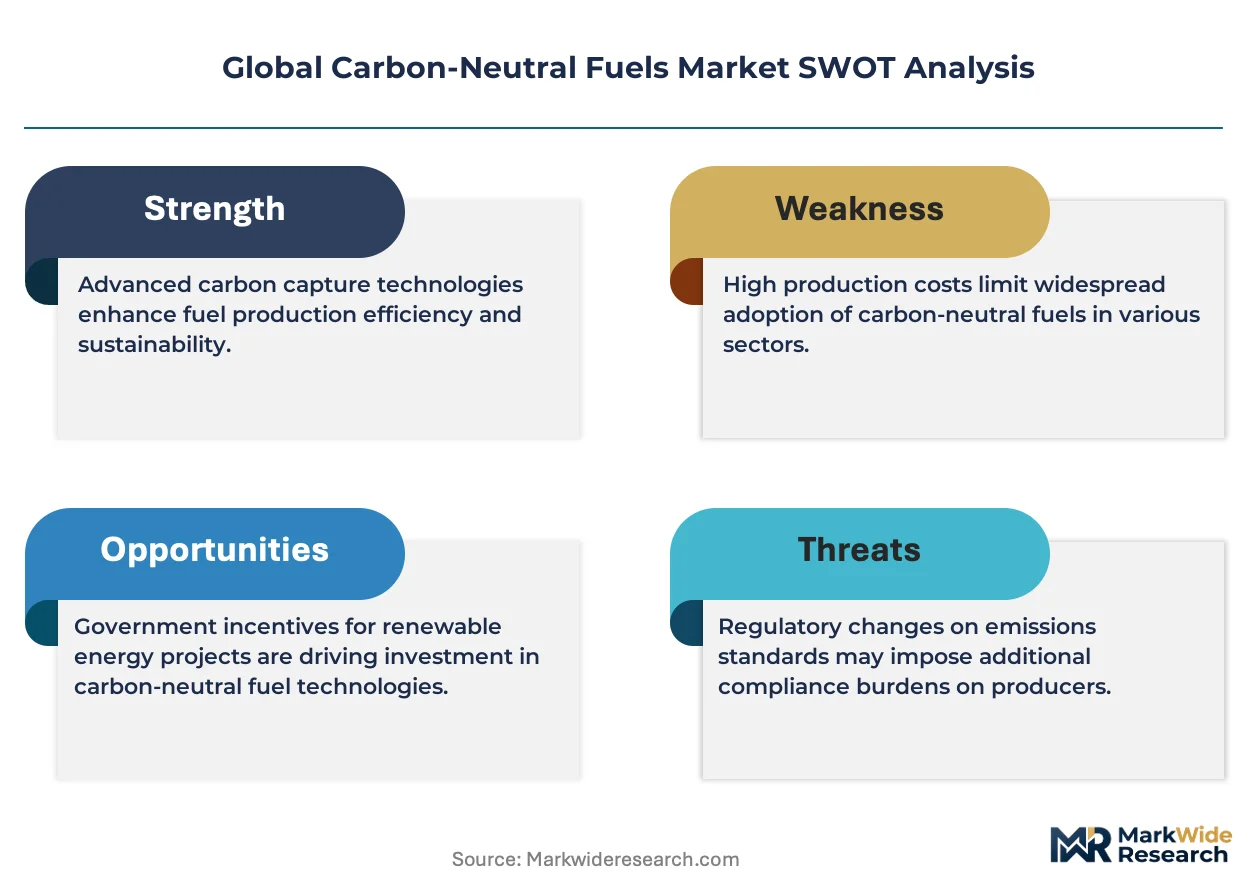
For Market Incumbents: Harden certification moats by securing EU Renewable Energy Directive Part B verification for direct air capture feedstock chains before Chinese electrolyzer manufacturers achieve comparable carbon accounting rigor. Expand backward integration into Icelandic geothermal-powered capture facilities to defend margin position against pure-play developers. Prioritize pipeline access negotiations with German network operators over spot market participation. For New Entrants and Emerging Players: Maritime ammonia fuel conversion projects in Singapore represent the most penetrable entry point, with two-stroke engine retrofits creating demand visibility absent in saturated aviation kerosene contracting. Brazilian sugarcane ethanol producers face feedstock competition pressure, opening acquisition opportunities for fermentation expertise applied to lignocellulosic pathways. Lead with digital certificate-of-origin platforms that bypass incumbent trading infrastructure. For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors pure-play e-fuel developers with captive carbon feedstock over integrated majors burdened by legacy refinery asset rationalization. Five-to-ten year viability hinges on electrolyzer manufacturing scale-up velocity rather than fossil fuel price arbitrage. Watch for EU Taxonomy threshold revisions on grid carbon intensity as the signal for which production pathways secure long-term offtake financing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Ten-year offtake contracts with Frankfurt aviation clusters secure pipeline access ahead of ReFuelEU mandates. |
| Backward Integration | Captive direct air capture facilities in Iceland eliminate feedstock price volatility for Fischer-Tropsch synthesis. |
| Capacity Expansion | Rotterdam electrolyzer deployment targets maritime ammonia output for Asia-Europe container routes. |
| Technology Licensing | Solid oxide cell patents from Danish developers accelerate Chinese manufacturing scale-up. |
| Green Certification Program | EU Renewable Energy Directive Part B verification unlocks premium pricing in German industrial clusters. |
Methodological Framework
The analysis maps synthetic fuel production pathways, biomass conversion technologies, and electrolyzer deployment clusters, each validated through fuel procurement officers at German aviation hubs, electrolyzer manufacturing engineers in Danish industrial zones, and carbon accounting specialists at Rotterdam port authorities. Primary interviews with long-term offtake contract negotiators, Fischer-Tropsch synthesis plant operators, and maritime fuel bunkering coordinators combined with secondary validation from EIA hydrogen production databases, IEA renewable fuel outlooks, EU delegated act filings, and SEC disclosures from integrated energy majors. Bottom-up capacity build-out modeling triangulated against top-down regulatory mandate analysis.
Assumption sets held electrolyzer cost decline trajectories and EU Green Deal enforcement timelines fixed while varying Chinese manufacturing penetration rates and direct air capture scale-up velocity across the projection horizon. Segmentation dimensions modeled include fuel type, production method, end-use application, and distribution channel complexity, with regional regulatory framework clusters as an industry-specific overlay. CAGRs derived from installed capacity pipelines and offtake contract tenors rather than historical price series, incorporating renewable electricity curtailment patterns and carbon credit banking dynamics as fuel-specific forecast inputs.
Practitioners should monitor EU Taxonomy threshold revisions and Chinese electrolyzer export tariff developments for early signals of production pathway viability shifts. Forecasts reflect assumptions about regulatory enforcement consistency and technology cost curves that industry stakeholders should validate against operating reality. Continuous validation against electrolyzer deployment announcements and offtake contract execution is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Alternate Marine Power Market