
 Bio-Methane Market | 2026-2036
Bio-Methane Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Methane Market Intelligence
The distinction between raw biogas and pipeline-grade biomethane is collapsing as upgrading technologies become standard, enabling direct injection into existing natural gas grids. This critical development expands market access beyond localized power generation. Major energy firms like TotalEnergies leverage their global infrastructure to scale production, while Shell Biogas focuses on integrating biomethane into its established gas supply chains. Specialized firms such as EnviTec Biogas AG differentiate through advanced plant engineering and operational services.
Bio-methane is a renewable natural gas produced by upgrading biogas, which is generated from the anaerobic digestion of organic matter. The upgrading process removes CO2 and other impurities to achieve a methane concentration typically exceeding 95%, making it chemically interchangeable with fossil natural gas. Agricultural residues and municipal solid waste constitute primary feedstock sources, valued for their low cost and consistent availability. While power generation remains a significant application, its use as a transportation fuel represents the fastest-growing segment due to decarbonization mandates in logistics and shipping.
Regulatory frameworks like the EU's Renewable Energy Directive and the US EPA's Renewable Fuel Standard program create binding targets for renewable gas consumption. In India, the SATAT initiative promotes compressed biogas as an alternative fuel, further stimulating production. These policies establish credit systems and mandates that directly support project bankability and offtake agreements. Stakeholder success depends on securing long-term feedstock supply chains and optimizing upgrading technology to meet stringent grid-injection specifications.
Market Dynamics
The central force shaping the bio-methane market is the global mandate for decarbonization, which positions upgraded biogas as a direct, drop-in replacement for fossil natural gas, particularly in the hard-to-abate transportation and industrial heat sectors.
Growth Catalysts
- Supportive Regulatory Frameworks:Policies like the EU's Renewable Energy Directive and the US EPA's Renewable Fuel Standard create guaranteed demand and credit systems, which significantly improve the financial viability and bankability of new bio-methane production projects.
- Decarbonization of Heavy Transport:The heavy-duty trucking and logistics industries are adopting bio-methane as a pragmatic, low-emission fuel, as it utilizes existing compressed natural gas (CNG) and liquefied natural gas (LNG) infrastructure, avoiding massive fleet and refueling network overhauls.
- Feedstock Availability:The consistent and widespread availability of low-cost organic feedstocks, primarily agricultural waste, manure, and municipal solid waste, provides a stable and economically attractive input for anaerobic digestion and subsequent upgrading.
Market Restraints
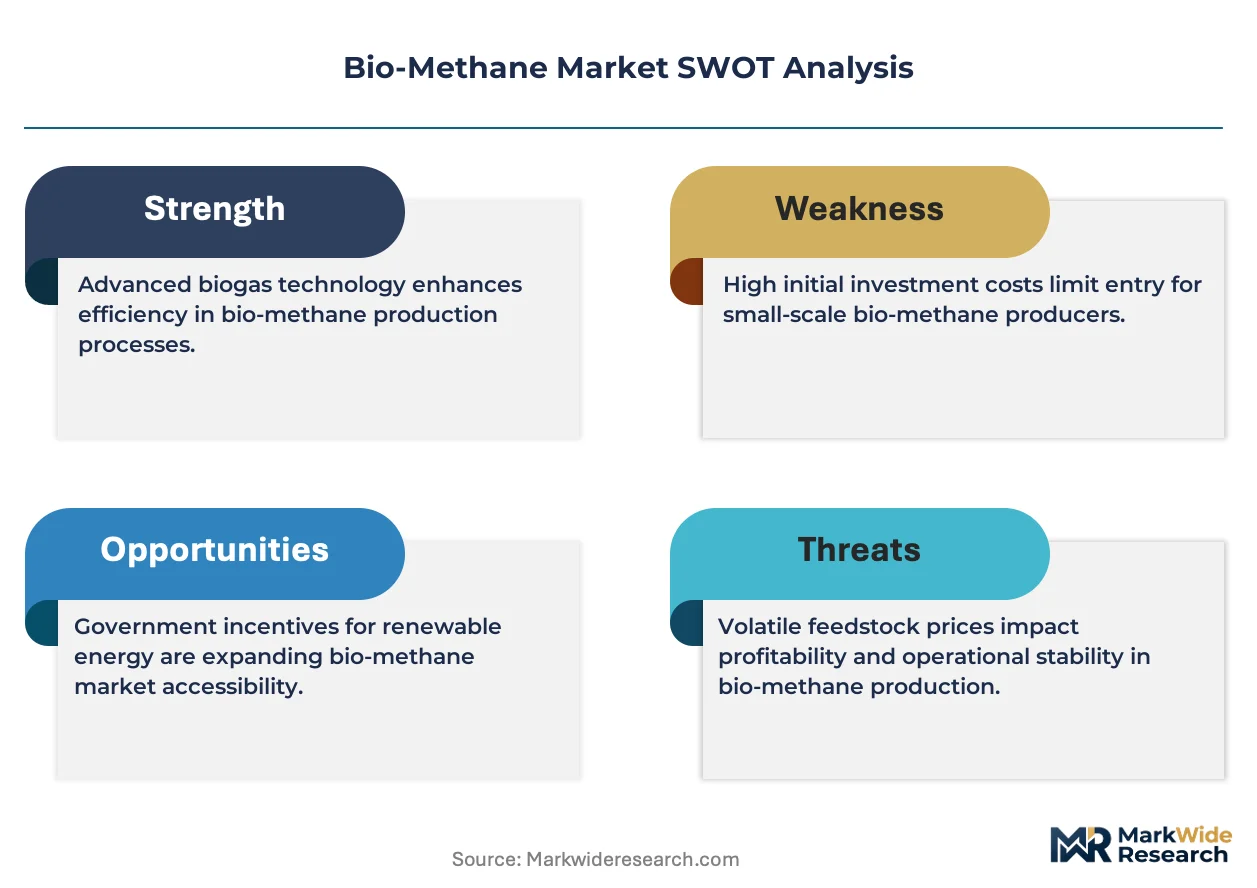
- High Capital Intensity:The significant upfront investment required for constructing anaerobic digestion plants and sophisticated gas upgrading facilities presents a substantial financial barrier to entry, particularly for smaller-scale agricultural producers or municipalities.
- Feedstock Logistics Complexity:The collection, transport, and storage of geographically dispersed and often heterogeneous organic waste streams create logistical hurdles and can lead to inconsistent feedstock supply, impacting plant operational efficiency.
- Stringent Grid Injection Standards:Meeting the precise and rigorous purity specifications for methane content and the removal of contaminants like CO2 and H2S for pipeline injection requires advanced, reliable, and costly upgrading technology.
Strategic Opportunities
- Emerging Geographic Markets:India's SATAT initiative, which promotes the use of compressed biogas (CBG), creates a significant opportunity for market entry and investment in a region with vast untapped agricultural feedstock potential and strong government support.
- Expansion into Maritime Fuel:The production of bio-LNG offers a pathway to decarbonize the maritime shipping sector, which faces stringent emissions regulations and is actively seeking sustainable alternative fuels for its global fleet.
- Carbon-Negative Fuel Production:Integrating bio-methane plants with carbon capture, utilization, and storage (CCUS) technologies enables the production of a carbon-negative energy source, creating a premium product for entities with aggressive net-zero targets.
Industry Challenges
- Feedstock Contract Security:Securing stable, long-term supply contracts for organic waste is a critical operational challenge, as competition for high-quality, low-cost feedstock intensifies with the build-out of new production capacity.
- Navigating Subsidy Mechanisms:The complexity of qualifying for and monetizing renewable fuel credits under programs like the US Renewable Fuel Standard requires specialized legal and administrative expertise, posing a hurdle for new market participants.
- Grid Access Limitations:In many developing regions, the lack of extensive natural gas pipeline infrastructure restricts the distribution of bio-methane, confining its use to localized power generation or vehicle fueling stations near the production site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Methane Market |
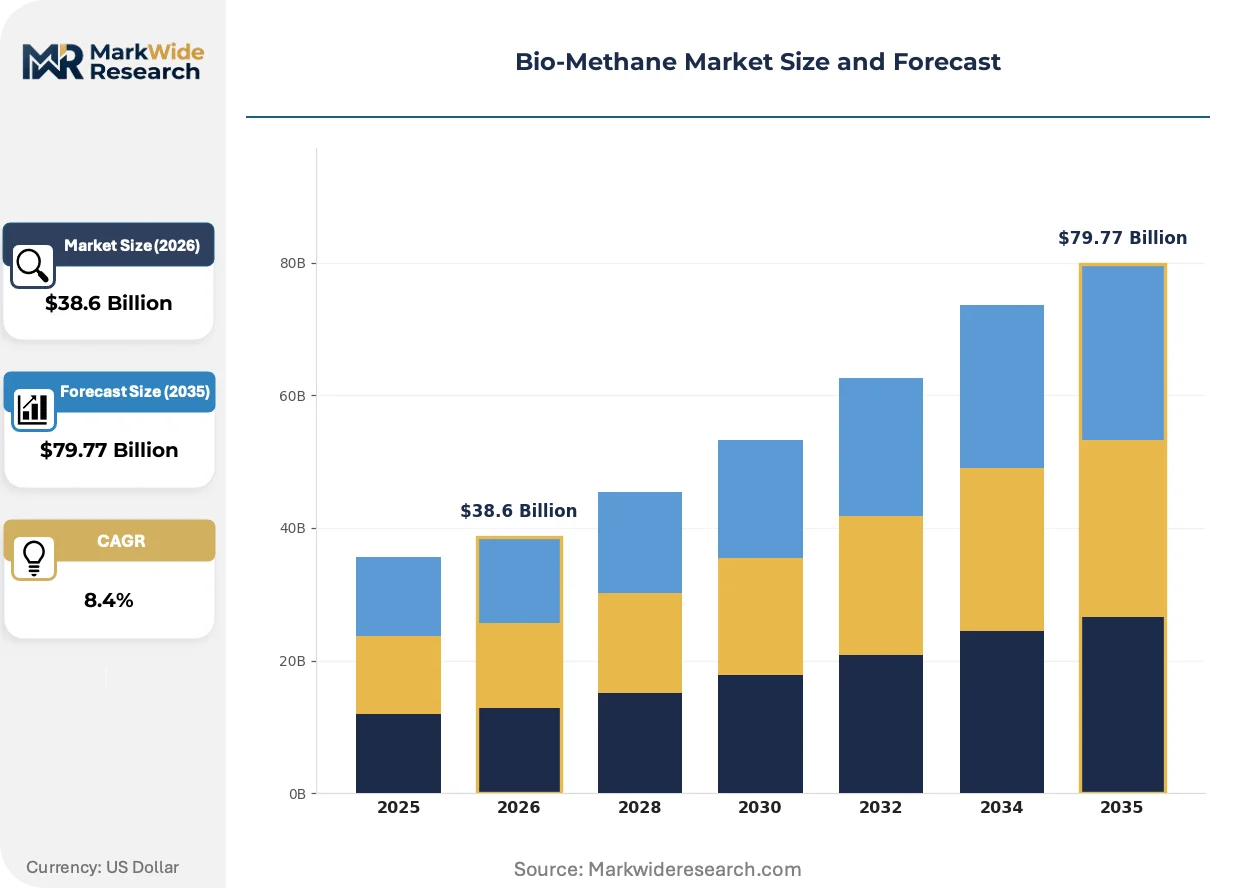
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Energy Crops, Agricultural Residues, Industrial Waste, Landfill Waste, Municipal Solid Waste Technology: Anaerobic Digestion, Gasification, Pyrolysis, Upgrading, Biogas Cleaning Application: Transportation Fuel, Power Generation, Heating Solutions, Industrial Processes, Cooking Fuel End User: Transport Operators, Electricity Producers, Commercial Establishments, Agricultural Enterprises, Residential Consumers |
| Companies Covered | Shell Biogas, Air Liquide, Engie, TotalEnergies, BP, Archaea Energy, EnviTec Biogas AG, PlanET Biogas Global GmbH, Gasum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Methane Market Strategic Shifts & Innovations
Technological maturation in gas upgrading and a formalization of bio-methane’s role within the circular economy are defining the market’s evolution. This shift moves production from large, centralized facilities toward more distributed and integrated models that connect waste sources directly to energy consumers.
Modular upgrading systems, utilizing technologies like membrane separation and pressure swing adsorption (PSA), provide the core function of purifying raw biogas into pipeline-grade bio-methane. Small-to-medium scale agricultural operations and municipal waste facilities are increasingly adopting these systems. This trend is miniaturizing the production footprint, enabling decentralized bio-methane generation that is sited closer to feedstock sources, thereby reducing transportation logistics and costs.
Legislation like the US Inflation Reduction Act (IRA) is providing significant, long-term tax credits for the production of renewable natural gas. This policy creates unprecedented investment certainty, directly de-risking the high capital costs associated with new plant construction. Project developers and investors in the United States are the most affected, with the IRA's incentives accelerating final investment decisions on a new wave of bio-methane facilities.
A notable behavioral shift is occurring as large corporations move from spot-market purchases to securing long-term, direct offtake agreements with bio-methane producers. This disrupts the conventional utility-centric procurement model, as companies in logistics, food and beverage, and manufacturing seek to lock in supply to meet internal sustainability goals. This trend is most pronounced in Europe, where firms are proactively securing renewable gas to comply with CSRD reporting mandates.
Bio-Methane Market Segmentation
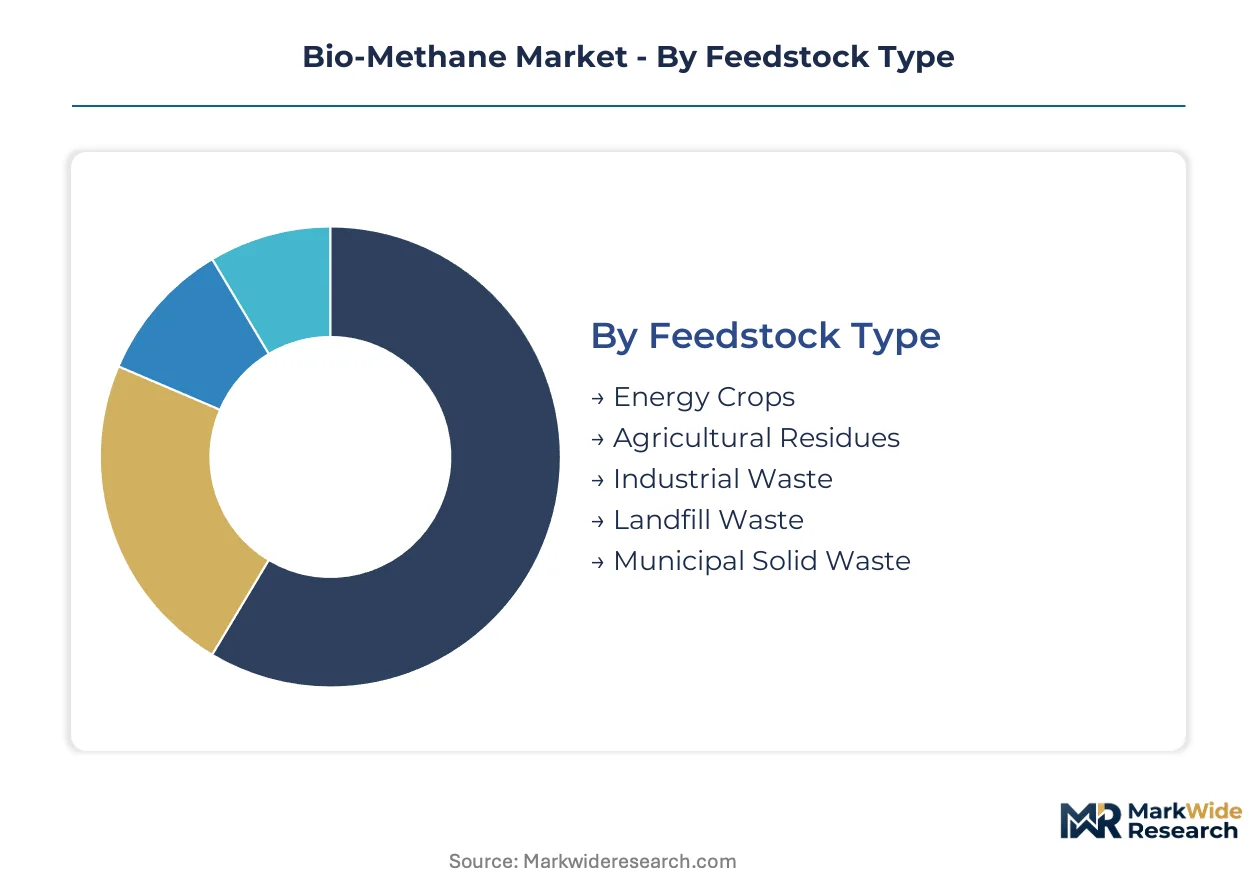
Segmentation in the bio-methane market clarifies diverse production pathways and end-use applications. Understanding these distinct segments helps stakeholders identify specific investment opportunities and regulatory impacts. This granular view reveals where innovation in feedstock sourcing and upgrading technology creates value.
Feedstock Type:
The feedstock type segment faces significant substitution pressure from alternative organic waste streams and evolving agricultural practices.
- Agricultural Residues:Organic materials remaining after crop harvesting, such as straw, stover, and manure, provide a sustainable and widely distributed source for biogas production. Demand concentrates in regions with intensive farming, such as Germany and the United States, driven by circular economy mandates and nutrient recycling initiatives.
- Municipal Solid Waste:Heterogeneous waste from households and commercial activities undergoes anaerobic digestion to produce biogas, reducing landfill volume and generating renewable energy. Demand is significant in urban centers globally, supported by waste management policies and carbon reduction targets.
- Energy Crops:Crops cultivated specifically for energy production, like corn silage or switchgrass, offer dedicated and consistent biomass supply.
- Industrial Waste:Organic byproducts from manufacturing processes, including food processing and pulp and paper industries, are utilized for biogas generation.
- Landfill Waste:Decomposing organic matter in landfills generates methane-rich gas, which can be captured and upgraded to bio-methane.
Municipal Solid Waste anchors the volume base while Agricultural Residues gains share at the steepest rate.
Technology:
Technology segments exhibit varying levels of commercial maturity, influencing adoption rates and capital expenditure requirements across the market.
- Anaerobic Digestion:A biological process where microorganisms break down organic matter in the absence of oxygen, producing raw biogas primarily composed of methane and carbon dioxide. Demand is fundamental for all bio-methane production, with significant deployment in agricultural settings and wastewater treatment plants.
- Upgrading:This process purifies raw biogas by removing carbon dioxide, hydrogen sulfide, and other trace contaminants, yielding pipeline-grade bio-methane with over 95% methane content. Demand is critical for grid injection and transportation fuel applications, particularly in Europe and North America where stringent quality standards prevail.
- Gasification:A thermochemical process that converts biomass or organic waste into a syngas, which can then be further processed to produce bio-methane.
- Pyrolysis:Thermal decomposition of organic materials at high temperatures in an inert atmosphere, yielding bio-oil, char, and syngas, which can be upgraded.
- Biogas Cleaning:Initial treatment steps to remove impurities like moisture and hydrogen sulfide from raw biogas before further upgrading or direct use.
Anaerobic Digestion technology forms the foundational step, while Upgrading processes enable market expansion into high-value applications.
Application:
Application segments demonstrate distinct cost tiers, reflecting infrastructure investments and regulatory incentives for specific end-uses.
- Transportation Fuel:Bio-methane is compressed (CNG) or liquefied (LNG) for use in heavy-duty vehicles, buses, and maritime shipping, directly replacing fossil natural gas. Demand is expanding most quickly in logistics and public transport sectors in the EU and US, driven by decarbonization mandates.
- Power Generation:Bio-methane fuels internal combustion engines or turbines to produce electricity, often co-generated with heat, contributing to renewable energy grids. Demand remains substantial in decentralized energy systems and industrial facilities, particularly where grid access is limited.
- Heating Solutions:Bio-methane provides renewable heat for residential, commercial, and industrial buildings, displacing fossil natural gas in existing infrastructure.
- Industrial Processes:Used as a direct fuel source or chemical feedstock in various industrial operations requiring high-temperature heat or specific chemical reactions.
- Cooking Fuel:Bio-methane offers a clean and sustainable alternative to traditional cooking fuels, particularly in rural and developing regions.
Transportation Fuel applications are experiencing the steepest expansion trajectory, while Power Generation maintains a consistent, large-scale demand.
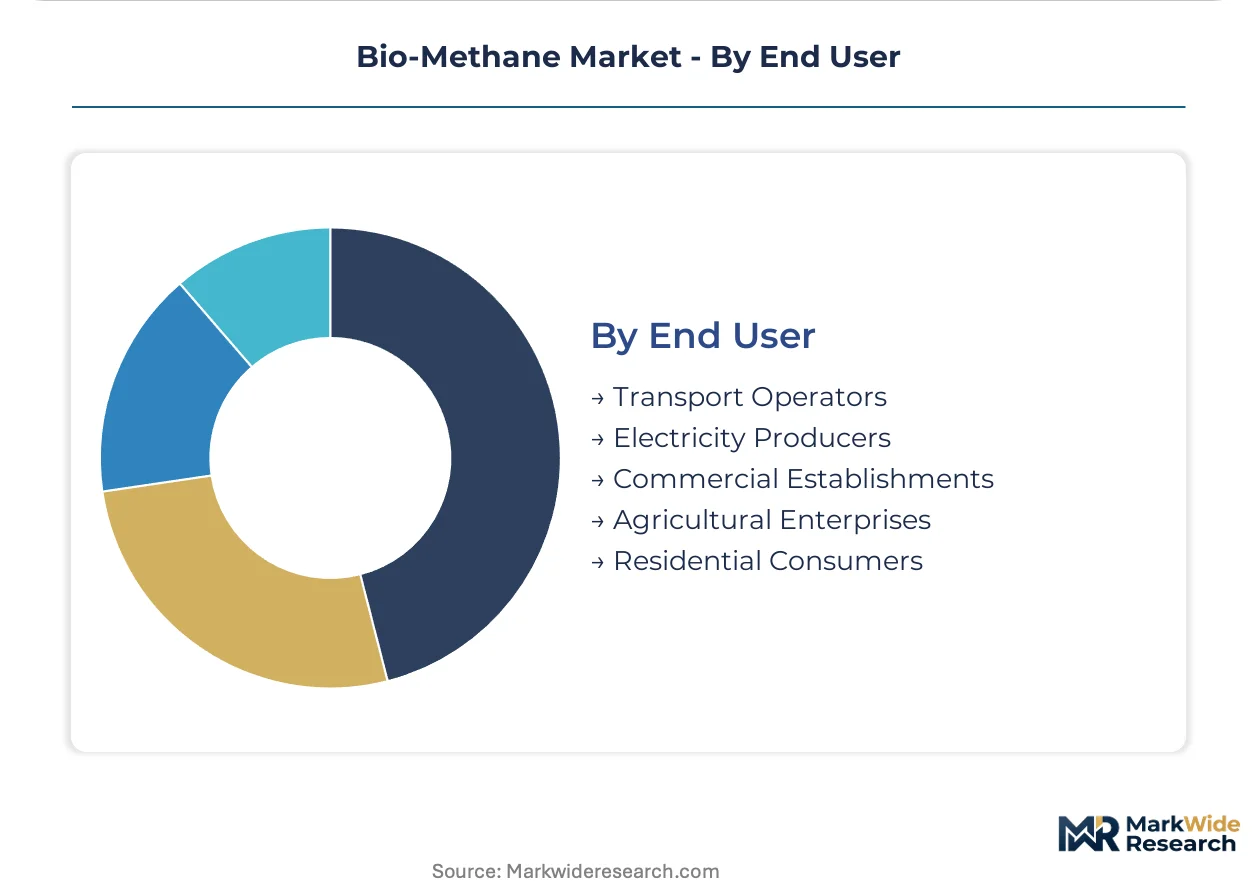
End User:
End user segments influence supply concentration, as their procurement strategies shape the scale and location of bio-methane production facilities.
- Transport Operators:Fleets of heavy-duty trucks, buses, and maritime vessels consume bio-methane as a direct replacement for fossil fuels, reducing greenhouse gas emissions. Demand from these operators is concentrated in regions with established natural gas vehicle infrastructure, such as Germany and California.
- Electricity Producers:Utilities and independent power producers integrate bio-methane into their energy mix, either directly in power plants or through grid injection, to meet renewable energy quotas. Demand from these entities is strong in countries with robust renewable portfolio standards, including the United States and several EU member states.
- Commercial Establishments:Businesses like hotels, hospitals, and retail centers utilize bio-methane for heating, cooling, and on-site power generation.
- Agricultural Enterprises:Farms and agricultural cooperatives use bio-methane for on-site energy needs, including heating barns, drying crops, and powering farm machinery.
- Residential Consumers:Households access bio-methane through the natural gas grid for heating, cooking, and water heating, often via green gas tariffs.
Transport Operators are increasingly driving new project developments, while Electricity Producers continue to represent a stable, large-volume off-taker.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade-flow of investment and technology from established European markets to rapidly expanding Asian economies is reshaping the global bio-methane landscape. This dynamic accelerates capacity development and regulatory alignment across continents. Key regions demonstrate unique growth trajectories.
United States
The United States market sees demand from heavy-duty trucking fleets and industrial processes. The US EPA's Renewable Fuel Standard and the Inflation Reduction Act provide significant investment incentives. California, with its stringent environmental mandates, leads in bio-methane adoption for transportation.
Germany
Germany's demand for bio-methane stems from its robust circular economy mandates and industrial heat requirements. The EU Green Deal and national support schemes accelerate project development. Bavaria, a region with intensive agriculture, hosts numerous advanced biogas facilities.
India
India's bio-methane demand is propelled by its energy security goals and agricultural waste management needs. The SATAT initiative actively promotes compressed biogas as a clean transportation fuel. Punjab, a major agricultural state, shows significant potential for new CBG plants.
Netherlands
The Netherlands exhibits strong demand for bio-methane due to its advanced gas grid and ambitious renewable energy targets. EU Renewable Energy Directive policies support grid injection and industrial use. The Groningen region benefits from existing gas infrastructure for bio-methane integration.
France
French demand for renewable gas arises from agricultural residue utilization and decarbonization efforts in industrial sectors. National renewable energy targets, aligned with the EU Green Deal, drive project financing. Brittany, known for its livestock farming, is a key area for biogas production.
Bio-Methane Market Key Industry Players
Listed leaders compete with private specialists across investment capacity and technological innovation in the bio-methane market. The landscape includes global energy conglomerates, specialized plant engineering firms, and regional project developers. Major energy firms leverage existing infrastructure for scale and market access, while technology specialists focus on developing and deploying advanced upgrading solutions. Capacity expansion, strategic partnerships, and geographic diversification remain dominant competitive moves across the sector.
Specialists in integrated energy solutions and biogas technology shape the competitive dynamics. TotalEnergies, a global energy major, exemplifies the strategy of leveraging existing infrastructure to scale bio-methane production. Similarly, Shell Biogas focuses on integrating renewable gas into established supply chains for transportation and industrial applications. EnviTec Biogas AG, a German-based firm, occupies a distinct position by specializing in advanced plant engineering and operational services for anaerobic digestion and upgrading facilities.
| Leading Market Players |
|---|
| Shell Biogas |
| Air Liquide |
| Engie |
| TotalEnergies |
| BP |
| Archaea Energy |
| EnviTec Biogas AG |
| PlanET Biogas Global GmbH |
| Gasum |
| Others |
Cost & Logistics Intelligence
Bio-methane’s substitution for fossil natural gas as a transportation fuel simultaneously reshapes supply geography towards decentralized production and influences pricing economics through regulatory incentives. This dynamic shifts focus from traditional commodity pricing to value-based contracts.
Pricing Analysis
The pricing gap between current-generation bio-methane and the commodity price of fossil natural gas reflects higher production costs and value-added attributes. The dominant pricing structure involves contract-based long-term offtake agreements, often supported by regulatory credit mechanisms. Price differentiation stems from feedstock quality, stringent grid injection specifications, and the certified carbon intensity score of the produced gas. Upward pricing pressure arises from high capital intensity for new facilities and the consistent demand driven by decarbonization mandates. Transport operators, facing strict emissions targets, exhibit lower price sensitivity, while electricity producers in competitive power markets remain more price-sensitive.
Supply Chain Analysis
Inbound logistics costs for feedstock collection, particularly for geographically dispersed agricultural residues, create significant supply chain complexity. Supply concentration for bio-methane production is emerging in countries like Germany, the United States, and India due to abundant feedstocks and supportive policies. Raw material dependencies include agricultural residues, municipal solid waste, and specialized upgrading membranes. Feedstock logistics complexity and the volatility of organic waste availability represent a structural supply chain risk. Distribution primarily runs through direct injection into existing natural gas grids or via dedicated compressed natural gas (CNG) and liquefied natural gas (LNG) fueling stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is witnessing a significant buyer-power shift as large corporations increasingly secure long-term, direct offtake agreements, fragmenting the conventional utility-centric procurement model.
For Market Incumbents: Compound existing global infrastructure by integrating bio-methane production into established gas supply chains. Invest in advanced upgrading technologies and carbon capture, utilization, and storage (CCUS) solutions to produce carbon-negative fuel, mitigating the threat from fluctuating fossil natural gas prices. Leverage global infrastructure to scale production capacity in regions with strong regulatory support and abundant feedstock.
For New Entrants and Emerging Players: Anchor in niche geographic markets with vast untapped agricultural feedstock potential, such as India, supported by national initiatives like SATAT. Target decentralized agricultural operations and municipal waste facilities using modular upgrading systems for localized production. A go-to-market angle focusing on turnkey bio-methane solutions for heavy-duty trucking fleets can penetrate the most receptive segments.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized plant engineering firms or feedstock aggregation companies that enhance supply chain security and operational efficiency. Long-term viability is assured by global decarbonization mandates and the need for drop-in renewable fuels. The expansion of natural gas grid infrastructure into new regions serves as a critical signal to watch for inflection points in market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production facilities in key regions like Germany and the United States enhances market presence. |
| Green Manufacturing Transition | Adopting sustainable production methods attracts environmentally conscious investors and consumers. |
| Long-term Supply Agreement | Securing stable feedstock sources reduces operational risk and ensures consistent bio-methane output. |
| Joint Venture | Partnering with local waste management firms or agricultural cooperatives optimizes feedstock logistics. |
| Technology Licensing | Monetizing proprietary upgrading technologies accelerates market adoption and generates new revenue streams. |
Research Approach
The analysis maps bio-methane production pathways, upgrading technologies, and end-use applications, each validated through primary interviews with plant operators, energy utility procurement managers, feedstock suppliers, and regulatory advisors. This approach combines qualitative insights from industry stakeholders with quantitative analysis derived from secondary data. Bottom-up and top-down triangulation ensures data consistency across the market.
Outputs were validated against external benchmarks to ensure consistency and reliability across the analysis window. The analytical framework modeled segmentation dimensions including feedstock type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected policy impacts, with industry-specific forecast inputs including projected organic waste generation and renewable energy target updates.
Decision-makers should treat outputs as directional under current policy stability and technological advancement assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions on regulatory continuity and feedstock availability, acknowledging that unforeseen shifts in energy prices or major policy changes could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Green Ammonia Market