
 Synthetic Fuel Market | 2026-2036
Synthetic Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Fuel Market Intelligence
The increasing use of long-term project finance models for large-scale production facilities is reconfiguring the competitive landscape for synthetic fuels. This capital-intensive structure favors established energy majors with strong balance sheets and offtake agreements. For example, Shell Plc leverages its extensive global infrastructure and logistics network to de-risk new synthetic fuel projects. Meanwhile, Sasol Limited specializes in its proprietary Fischer-Tropsch technology, anchoring its entire strategy on decades of operational expertise.
Synthetic fuels are liquid or gaseous hydrocarbons produced from feedstocks like green hydrogen and captured carbon dioxide, not from crude oil. The Fischer-Tropsch process is a common catalytic pathway to create these drop-in fuels, designed to directly replace conventional fuels in existing engines without modification. Within the various fuel types, synthetic kerosene for the aviation sector represents the fastest-growing category. Heavy equipment and maritime vessels in the application segment also show significant uptake due to stringent decarbonization pressures.
Regulatory frameworks are critical to market formation, with the European Union's ReFuelEU Aviation initiative and the US Inflation Reduction Act (IRA) providing powerful demand signals. These policies establish clear mandates and substantial tax incentives that make large-scale synthetic fuel projects economically viable. Securing long-term access to low-cost renewable electricity and green hydrogen feedstock will ultimately determine the long-term cost competitiveness and profitability of individual producers.
Market Dynamics
The market's structure is being defined by a powerful regulatory pull, with mandates like the EU's ReFuelEU Aviation initiative creating guaranteed demand that justifies the high capital investment required for new production facilities.
Growth Catalysts
- Regulatory Mandates:The European Union's ReFuelEU Aviation initiative establishes a firm offtake requirement for sustainable aviation fuels, providing a clear demand signal for producers and investors.
- End-Use Decarbonization:Stringent decarbonization pressures in the global maritime and heavy equipment sectors are driving exploration of synthetic diesel and methanol as viable drop-in fuel alternatives.
- Process Maturity:Advances in the Fischer-Tropsch synthesis process allow for the reliable production of high-quality drop-in fuels, increasing confidence among engine manufacturers and end-users.
Market Restraints
- Feedstock Cost:The high production cost of green hydrogen, a primary feedstock, remains a significant barrier to achieving price parity with conventional fossil fuels.
- Energy Infrastructure:Limited availability of large-scale, low-cost renewable electricity needed for electrolysis presents a major bottleneck for scaling green hydrogen and synthetic fuel production.
- Capital Intensity:The immense upfront capital required to construct and commission synthetic fuel plants creates high barriers to entry for companies without strong balance sheets.
Strategic Opportunities
- Geographic Expansion:Regions with abundant renewable resources, such as Australia and Chile, present opportunities for developing export-oriented synthetic fuel production hubs.
- US Policy Incentives:The US Inflation Reduction Act (IRA) provides substantial tax credits for green hydrogen and SAF production, creating a highly attractive investment environment.
- Niche Applications:Developing specialized synthetic fuel blends for high-performance sectors like professional motorsport or specialty chemicals offers pathways to high-margin markets.
Industry Challenges
- Project Execution Risk:Managing complex, multi-year timelines for large-scale facilities amid supply chain and labor disruptions is a primary operational challenge.
- Feedstock Competition:Securing long-term supply of green hydrogen and captured CO2 is increasingly competitive as multiple industries vie for limited resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Fuel Market |
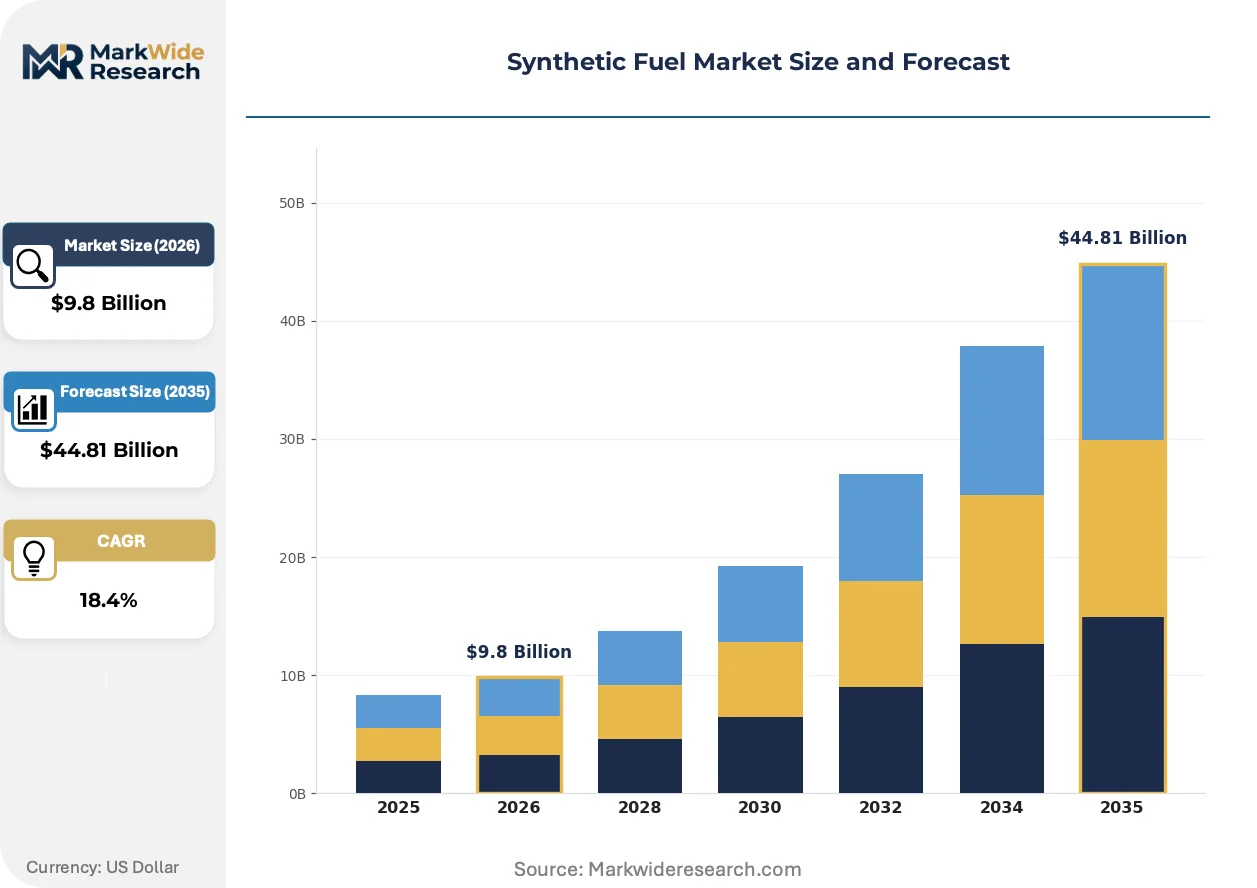
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $44.81 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Fischer-Tropsch Diesel, Methanol, Dimethyl Ether, Bio-synthetic Gasoline, Synthetic Kerosene Technology: Gasification, Pyrolysis, Hydrothermal Liquefaction, Catalytic Conversion, Carbon Capture & Utilization Application: Heavy Equipment, Maritime Vessels, Aviation, Power Generation, Industrial Machinery End User: Logistics Providers, Airlines, Mining Operations, Marine Operators, Power Producers |
| Companies Covered | Chevron Corporation, Neste Oyj, Shell Plc, Phillips 66 Company, Repsol S.A., Sasol Limited, TotalEnergies SE, Johnson Matthey Plc, ExxonMobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Fuel Market Strategic Shifts & Innovations
A fundamental shift from pilot-scale experimentation to industrial-scale production is defining the synthetic fuel sector. This transition is propelled by process innovations, binding policy frameworks, and evolving procurement models across key end-use industries.
Advanced catalytic systems for the Fischer-Tropsch process improve selectivity and conversion efficiency. New project developers are adopting these systems to maximize output from a given feedstock volume. This continuous improvement in catalyst performance is rendering obsolete older, less efficient formulations and challenging the economics of facilities unable to upgrade.
The European Union’s ReFuelEU Aviation regulation creates a binding blending mandate for sustainable aviation fuels. This policy translates into guaranteed demand for products like synthetic kerosene from all airlines operating in the EU. The aviation sector is most affected, compelling carriers to secure long-term supply through offtake agreements for compliance.
Movement toward long-term offtake agreements is replacing traditional spot-market fuel purchasing. This change disrupts the role of fuel procurement departments, elevating contracting to a strategic planning function. This pattern is most visible within the global aviation industry, especially among carriers in Germany and the Netherlands planning fleet operations years in advance.
Synthetic Fuel Market Segmentation
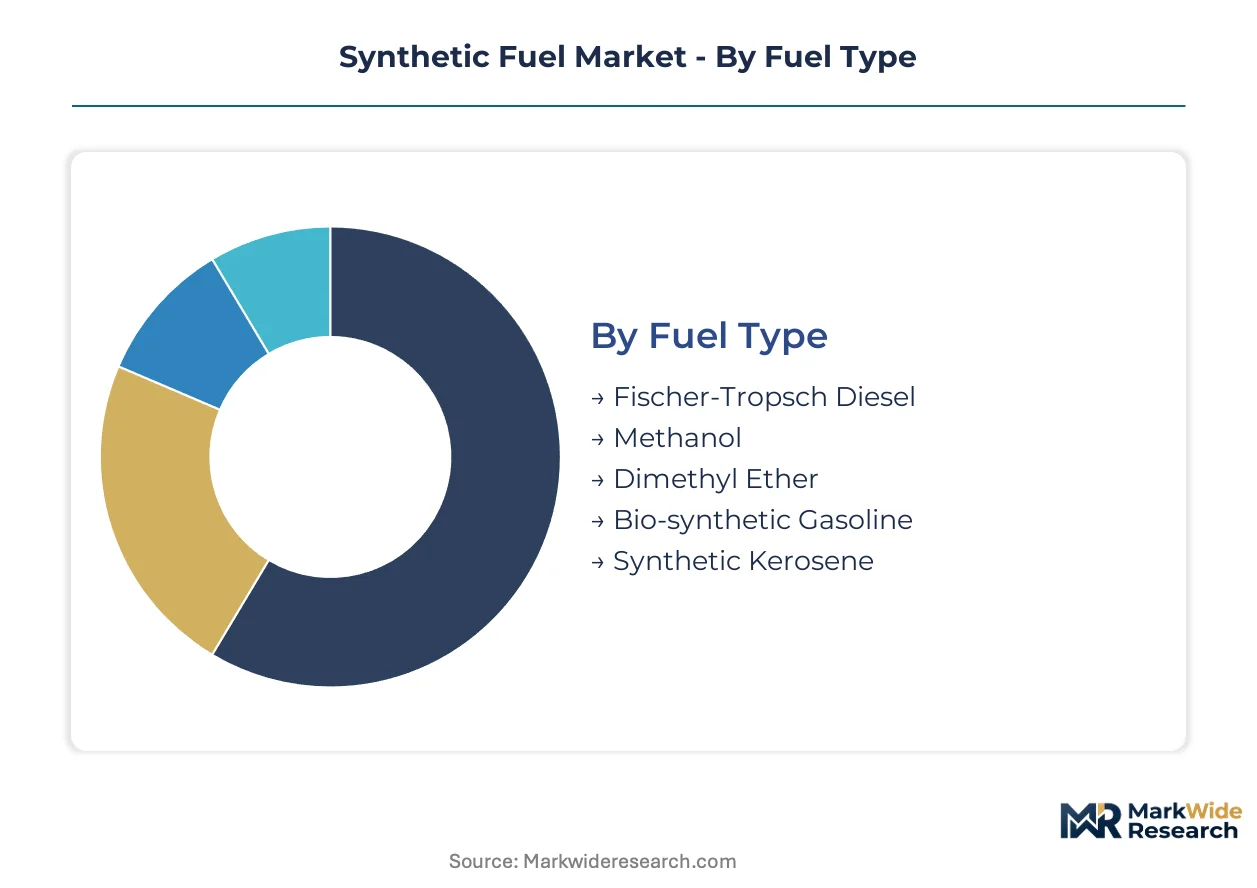
The synthetic fuel market serves diverse industrial applications, requiring precise categorization to understand demand drivers and technological adoption. This segmentation highlights the various fuel types, production technologies, end-use applications, and primary end-users shaping market dynamics. Each segment reflects distinct operational requirements and regulatory influences.
Fuel Type:
The use-case spectrum for synthetic fuels extends across multiple energy carriers, each tailored for specific engine types or industrial processes.
- Synthetic Kerosene:This drop-in fuel is chemically identical to conventional jet fuel, enabling direct use in existing aircraft engines without modification. Demand concentrates in the European aviation sector, driven by the ReFuelEU Aviation mandate for sustainable aviation fuels.
- Fischer-Tropsch Diesel:Produced via the Fischer-Tropsch process, this synthetic diesel offers high cetane numbers and ultra-low sulfur content, making it a premium alternative to fossil diesel. Uptake is significant in global maritime shipping and heavy equipment due to stringent decarbonization targets.
- Methanol:Synthetic methanol serves as a chemical feedstock and a marine fuel, particularly for new dual-fuel vessels.
- Dimethyl Ether:DME is a versatile fuel that can replace LPG in various applications and is explored as a diesel substitute.
- Bio-synthetic Gasoline:This fuel offers a renewable alternative to traditional gasoline for light-duty vehicles and specialized engines.
The dominant share belongs to Synthetic Kerosene, while Fischer-Tropsch Diesel is closing the gap fastest.
Technology:
Supply concentration in synthetic fuel production is heavily influenced by the maturity and scalability of underlying conversion technologies.
- Catalytic Conversion:This technology, exemplified by the Fischer-Tropsch process, uses catalysts to convert syngas into liquid hydrocarbons, forming the backbone of established synthetic fuel production. Efficiency improvements in catalytic systems directly impact the economic viability of large-scale facilities.
- Carbon Capture & Utilization:Essential for producing carbon-neutral synthetic fuels, this technology involves capturing CO2 from industrial emissions or direct air capture for use as a feedstock. Policy incentives like the US Inflation Reduction Act significantly accelerate investments in CCU infrastructure.
- Gasification:Gasification converts solid or liquid carbonaceous feedstocks into syngas, a crucial intermediate for subsequent fuel synthesis.
- Pyrolysis:Pyrolysis involves the thermal decomposition of organic materials in the absence of oxygen to produce bio-oils and syngas.
- Hydrothermal Liquefaction:This process converts wet biomass into bio-crude under high temperature and pressure conditions, offering a pathway for diverse feedstocks.
Catalytic Conversion technologies currently hold the largest share, with Carbon Capture & Utilization climbing the fastest.
Application:
Customer type dictates the specific fuel properties and regulatory compliance requirements for synthetic fuel integration.
- Aviation:The aviation sector is a primary demand driver for synthetic kerosene, seeking to meet ambitious decarbonization targets and regulatory mandates like the EU's ReFuelEU Aviation. Airlines are actively pursuing long-term offtake agreements to secure future supply.
- Maritime Vessels:Decarbonization pressures are compelling global shipping companies to explore synthetic diesel and methanol as alternatives to traditional bunker fuels. The International Maritime Organization's emissions reduction goals are a major catalyst for this transition.
- Heavy Equipment:Construction and mining operations are exploring synthetic diesel to reduce their carbon footprint and comply with local emissions standards.
- Power Generation:Synthetic fuels can provide dispatchable power generation, complementing intermittent renewable energy sources.
- Industrial Machinery:Various industrial processes utilize synthetic fuels for specific heating or power needs, offering a pathway to lower process emissions.
The Aviation sector represents the largest application, while Maritime Vessels are gaining share fastest.
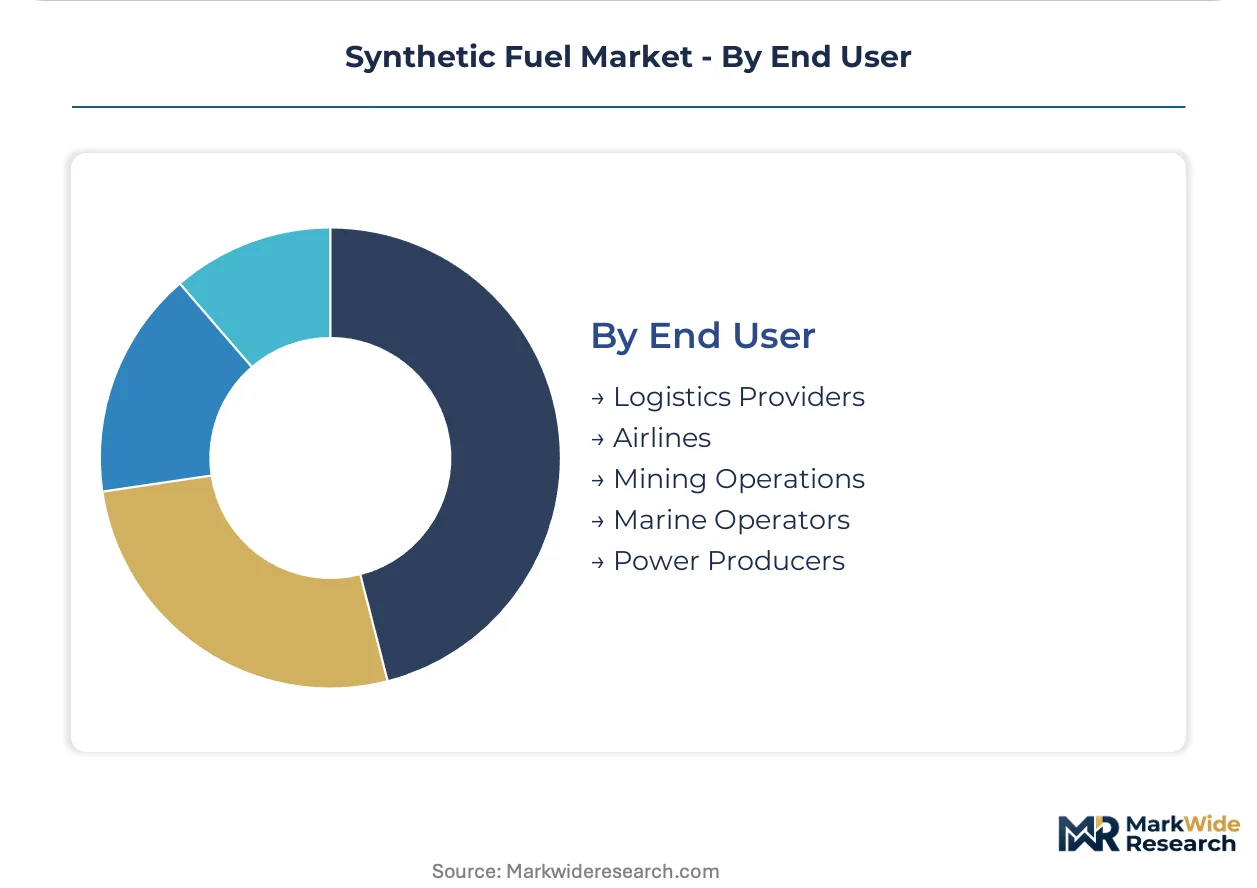
End User:
Market maturity in the synthetic fuel sector is reflected in the readiness of key end-users to integrate these new energy sources into their operations.
- Airlines:Global airlines, particularly those operating in Europe, are mandated to incorporate sustainable aviation fuels, including synthetics, into their fuel mix. This creates a guaranteed demand signal for synthetic kerosene producers.
- Marine Operators:Large shipping lines and fleet owners are investing in new vessels capable of running on synthetic methanol or diesel to meet future emissions regulations. This shift is driven by both regulatory compliance and corporate sustainability goals.
- Logistics Providers:These companies are evaluating synthetic fuels for their road and rail fleets to decarbonize supply chains.
- Mining Operations:Mining firms are exploring synthetic diesel to power heavy machinery and reduce Scope 1 emissions at remote sites.
- Power Producers:Utilities are considering synthetic fuels for flexible power generation, especially in conjunction with renewable energy projects.
Airlines constitute the largest end-user segment, with Marine Operators showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for synthetic fuels heavily influences regional investment patterns. This focus on specific end-user demand shapes the geographic distribution of production facilities and infrastructure development. Policy frameworks and resource availability further guide these strategic placements.
Germany
Demand for sustainable aviation fuels drives investment in Germany. The ReFuelEU Aviation mandate creates a firm offtake requirement for airlines operating in the region. Production investments concentrate within Northern European logistics hubs, particularly around Hamburg, to serve the aviation sector.
United States
Strong policy incentives from the US Inflation Reduction Act stimulate synthetic fuel production. The IRA provides substantial tax credits for green hydrogen and sustainable aviation fuel. New facilities are emerging in states with abundant renewable energy resources, such as Texas, leveraging these financial benefits.
Netherlands
The European Union's ReFuelEU Aviation mandate compels airlines to secure synthetic kerosene in the Netherlands. The country's strategic port infrastructure supports large-scale import and distribution of these fuels. Rotterdam's industrial cluster is a focal point for new production projects, connecting supply chains.
Australia
Abundant renewable energy resources position Australia as a future export hub for synthetic fuels. The country's national energy policies support green hydrogen development for industrial applications. Western Australia is exploring large-scale production for export markets, capitalizing on its vast solar and wind potential.
Chile
Significant solar and wind resources make Chile attractive for green hydrogen production and conversion to synthetic fuels. The national government promotes green hydrogen initiatives for both domestic use and export. Patagonia is developing projects focused on synthetic fuel production, aiming for cost-competitive output.
Synthetic Fuel Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in synthetic fuels. The market is consolidating around established energy majors and technology providers, reflecting the high capital intensity. Strategic archetypes include integrated energy giants, specialized technology licensors, and emerging pure-play producers. Capacity expansion and strategic partnerships are dominant competitive moves across the industry, alongside technology licensing.
Scale-driven energy companies like Shell Plc and TotalEnergies SE leverage extensive global infrastructure for new synthetic fuel projects. These integrated players often control feedstock supply and distribution channels, aiming for full value chain integration. Sasol Limited, a prominent technology licensor, anchors its strategy on proprietary Fischer-Tropsch technology, specializing in the conversion process. These firms exemplify distinct archetypes within the synthetic fuel market, from large-scale project developers to specialized technology providers. Their strategies reflect the capital-intensive nature of synthetic fuel production and the need for secure offtake agreements.
| Leading Market Players |
|---|
| Chevron Corporation |
| Neste Oyj |
| Shell Plc |
| Phillips 66 Company |
| Repsol S.A. |
| Sasol Limited |
| TotalEnergies SE |
| Johnson Matthey Plc |
| ExxonMobil Corporation |
| Others |
Cost & Logistics Intelligence
Feedstock cost volatility, particularly for green hydrogen, determines pricing tier spreads and shapes the synthetic fuel supply chain. This input cost directly impacts the economic viability of production and subsequent fuel prices.
Pricing Analysis
Long-term offtake agreements often feature cost-plus pricing indexed to renewable electricity or green hydrogen prices. This contract-based pricing model dominates, reflecting the high capital intensity of synthetic fuel production. Price differentiation stems from certification levels, such as ReFuelEU Aviation compliance, and the volume scale of commitments. Upward pricing pressure originates from escalating green hydrogen production costs, making heavy equipment operators highly sensitive to fuel costs, while airlines show less sensitivity due to mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are crucial for supporting the capital-intensive synthetic fuel ecosystem. Supply concentration occurs in Germany, the Netherlands, and the United States, driven by policy incentives and logistics. The industry relies heavily on green hydrogen and captured CO2, creating single-source vulnerability for low-cost green hydrogen. Distribution runs through existing port infrastructure and conventional fuel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic fuel market is undergoing a significant buyer-power shift, driven by the consolidation of long-term offtake agreements among major airlines. This centralizes procurement influence and reshapes supplier relationships.
For Market Incumbents: Pre-empt emerging competitive threats by securing long-term renewable energy and green hydrogen supply agreements. Incumbents must invest in advanced catalytic R&D to improve conversion efficiency and reduce production costs, mitigating margin pressure from new pure-play producers. Expanding production capacity in strategic Northern European hubs reinforces market share. This proactive approach defends against regulatory shifts favoring new technologies.
For New Entrants and Emerging Players: Geographic underpenetration in regions with abundant, low-cost renewable resources, such as Australia and Chile, offers significant market entry opportunities. New entrants should target export-oriented production hubs for synthetic kerosene, leveraging US IRA tax credits for project financing. A go-to-market angle focusing on specialized fuel blends for high-performance niche applications can provide higher margins. This strategy avoids direct competition with established majors in core markets.
For Investors and Strategic Acquirers: The market sits at a nascent industrialization phase that favors integrated energy majors and technology licensors. Long-term viability hinges on sustained policy support and a dramatic reduction in green hydrogen costs over the next decade. Investors should target specialized technology providers with proprietary Fischer-Tropsch processes or strong carbon capture IP. The signal to watch is the consistent commissioning of large-scale facilities and falling green hydrogen prices.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Increases production volume of synthetic fuels to meet growing aviation demand. |
| Technology Licensing | Accelerates market penetration of advanced Fischer-Tropsch processes globally. |
| Long-term Offtake Agreements | Secures guaranteed demand for synthetic kerosene from major airlines. |
| Joint Ventures with Renewable Energy Developers | Ensures stable, low-cost green hydrogen supply for synthetic fuel plants. |
| Carbon Capture Infrastructure Investment | Enables production of carbon-neutral synthetic fuels, meeting regulatory requirements. |
Research Approach
A spread of perspectives from production executives, procurement heads, regulatory advisors, and R&D directors converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were rigorously combined with secondary validation from IEA reports, government energy policies, corporate financial filings, and patent databases. This approach utilized both bottom-up and top-down triangulation to ensure data accuracy.
The demand-supply balance framework underpinned the quantitative modeling across the analysis window. This framework integrated segmentation dimensions including fuel type, technology, application, end-user, and regional policy environment. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Key forecast inputs included green hydrogen availability and sustainable aviation fuel blending mandates.
Practitioners should monitor feedstock cost fluctuations and evolving policy changes for early signals impacting market trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Jatropha Biodiesel Market