
 Corn-Based Renewable Fuel Market | 2026-2036
Corn-Based Renewable Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Corn-Based Renewable Fuel Market Insights
Cellulosic ethanol conversion technology is rewriting the economics of corn stover utilization across the fuel value chain. POET-DSM leverages pilot-scale cellulosic operations in Iowa to sustain technology leadership in next-generation pathways. Cargill anchors its position through backward integration into corn origination and wet milling infrastructure. Green Plains competes on manufacturing scale, operating multiple biorefineries with optimized enzyme efficiency.
Corn-based renewable fuel denotes ethanol, biobutanol, and derived bioproducts manufactured through fermentation of corn starch or cellulose, typically achieving 113 octane ratings in finished gasoline blends while reducing lifecycle carbon intensity versus petroleum gasoline. The product serves primarily as a transportation fuel oxygenate and gasoline extender in internal combustion engines. Ethanol dominates volume within product type segments, though biobutanol commands premium positioning for higher energy density and pipeline compatibility. Aviation fuels application represents the fastest-expanding demand pool as sustainable aviation fuel mandates tighten across regulated jurisdictions.
The US EPA administers Renewable Fuel Standard volume obligations that mandate annual biofuel blending quotas, while California Air Resources Board enforces Low Carbon Fuel Standard carbon intensity scoring that rewards lower-emission corn ethanol pathways. Brazil's ANP regulates RenovaBio carbon intensity certification for imported ethanol, shaping international trade flows. Stakeholders must monitor evolving lifecycle assessment methodologies, as regulatory acceptance of carbon capture and sequestration at biorefineries will determine future compliance credit values and capital allocation priorities.
Market Dynamics
The US EPA Renewable Fuel Standard volume obligations are compressing compliance timelines while California's Low Carbon Fuel Standard carbon intensity scoring is forcing biorefineries to capture and sequester emissions or lose credit value.
Growth Catalysts
- California LCFS carbon intensity thresholds:The scoring system rewards ethanol pathways with lower lifecycle emissions, pulling investment toward carbon capture retrofits at Iowa and Illinois processing clusters.
- Aviation fuel mandates:Sustainable aviation fuel procurement obligations across regulated US and EU jurisdictions are opening offtake contracts for corn-derived alcohol-to-jet pathways.
- Enzyme efficiency gains:Next-generation cellulase cocktails are reducing fermentation cycle times and lifting starch-to-ethanol yields at dry-grind facilities.
Market Restraints
- Feedstock cost volatility:Corn price swings tied to USDA crop yield reports and weather patterns in the US Midwest directly compress biorefinery margin structures.
- Blend wall constraints:The US gasoline pool's physical absorption limit near E10 saturation restricts volume growth without infrastructure investment in E15 or flex-fuel retail networks.
- Cellulosic conversion economics:Pretreatment energy intensity and enzyme loading rates for corn stover remain above commercial breakeven without policy support.
Strategic Opportunities
- Brazil RenovaBio certification:Carbon intensity scoring for imported ethanol creates arbitrage potential for US producers with verified low-CI supply chains.
- Carbon capture and sequestration:45Q tax credit eligibility for biogenic CO2 capture at fermentation stacks offers new revenue streams independent of fuel sales.
- Biobutanol pipeline compatibility:Higher energy density and existing hydrocarbon infrastructure compatibility position biobutanol for marine and heavy-duty segments.
Industry Challenges
- Lifecycle assessment methodology uncertainty:Evolving GREET model updates from Argonne National Laboratory create compliance credit volatility and capital planning risk.
- Specialized process engineering talent:Scarce expertise in simultaneous saccharification and co-fermentation systems limits scale-up velocity for next-generation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn-Based Renewable Fuel Market |
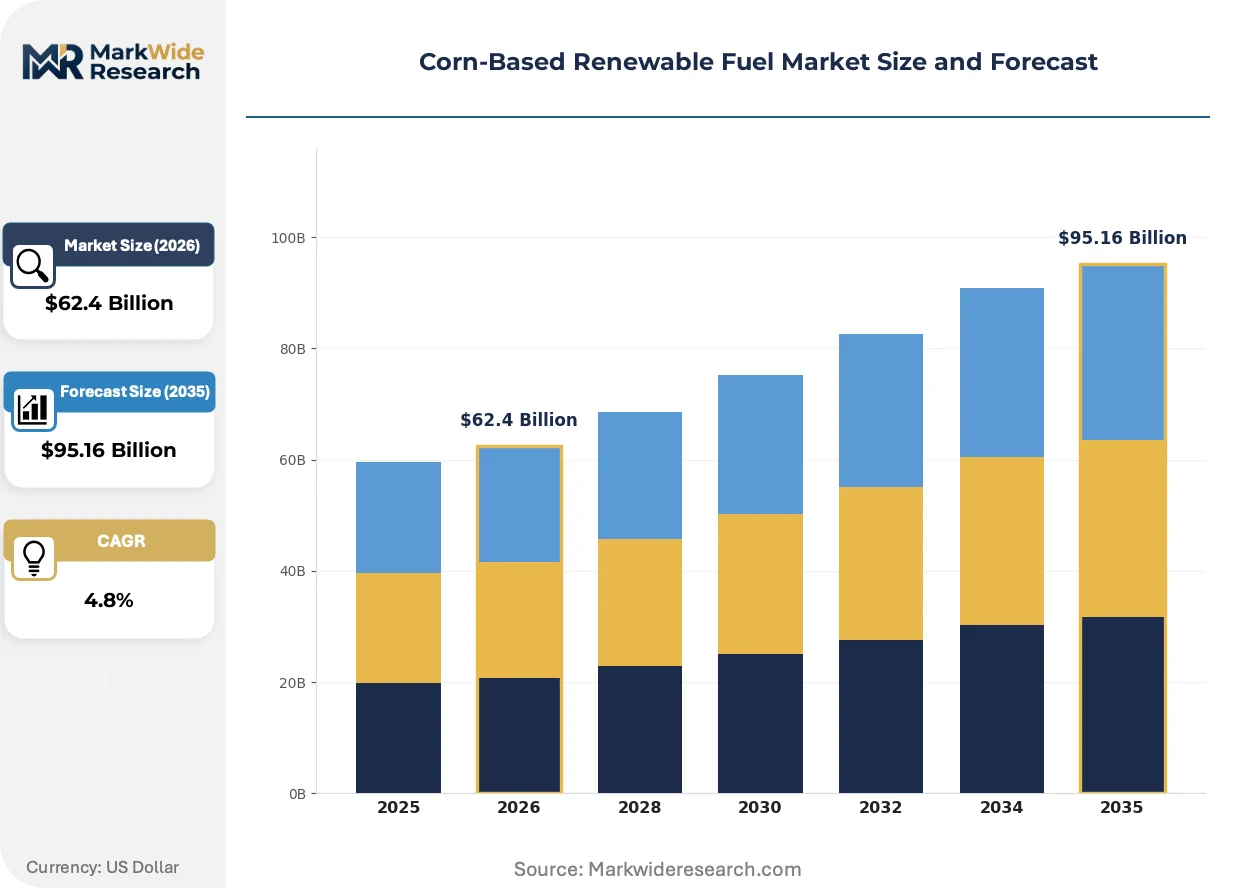
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $95.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Biobutanol, Acetone, Biodiesel End User: Transportation, Industrial, Agriculture, Power Generation Application: Fuel Cells, Internal Combustion, Aviation Fuels, Marine Fuels Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | ADM, Cargill, POET-DSM, Green Plains, Neste Oil, Verbio, Infinita Renovables, Biopetrol, Ital Green Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn-Based Renewable Fuel Market Trends and Innovations
Digital process control and advanced analytics are penetrating biorefinery operations, compressing energy intensity while regulatory carbon accounting tightens across multiple jurisdictions.
Precision fermentation monitoring is digitizing yield optimization across dry-grind ethanol facilities. Real-time spectroscopic analysis of mash composition lets operators adjust enzyme dosing and temperature profiles dynamically. Major biorefinery operators in Iowa and Nebraska are retrofitting plants with distributed sensor networks that feed machine-learning models predicting fermentation completion times.
The US EPA is finalizing Renewable Fuel Standard volume obligations for advanced biofuel categories that explicitly credit carbon capture and sequestration at point-source emitters. This regulatory revision forces biorefineries to evaluate pipeline injection partnerships or face credit discounting. Facilities with access to saline aquifer storage geology in Illinois and North Dakota hold structural advantage.
Airline procurement departments are unbundling sustainable aviation fuel from traditional jet fuel supply contracts, creating direct offtake negotiations with ethanol producers rather than through petroleum intermediaries. Delta, United, and American Airlines sustainability teams now source corn-derived alcohol-to-jet volumes through bilateral agreements. This channel shift concentrates in US Midwest production corridors with rail access to coastal refineries.
Corn-Based Renewable Fuel Market Segmentation
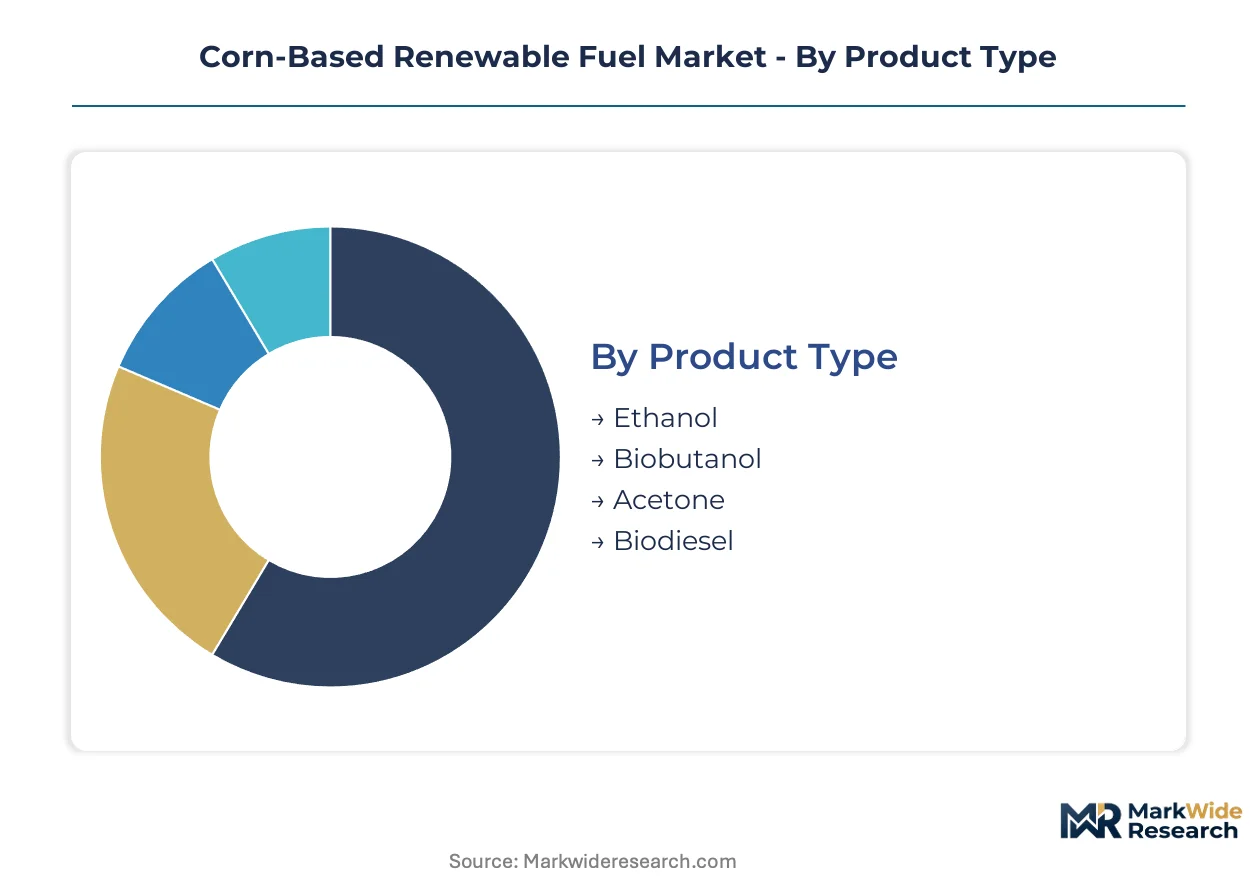
Segmentation reveals how corn-based renewable fuel producers allocate capital across divergent margin structures. Product chemistry, end-use specifications, and channel economics each dictate distinct operational footprints and compliance requirements.
Product Type:
Cost tier differentiation separates commodity oxygenates from specialty bioproducts with premium pricing power.
- Ethanol:Fermentation-derived alcohol achieving 113 octane ratings in finished gasoline blends. Iowa and Illinois processing clusters absorb the majority of US corn starch feedstock, driven by EPA Renewable Fuel Standard volume obligations that mandate annual blending quotas.
- Biobutanol:Four-carbon alcohol with 25% higher energy density than ethanol and direct pipeline compatibility. Aviation and marine offtake contracts are concentrating demand for biobutanol as a sustainable aviation fuel precursor, with alcohol-to-jet pathways gaining procurement traction from Delta and United Airlines.
- Acetone:Solvent byproduct from ABE fermentation with industrial chemical applications. Chemical manufacturers source acetone for coatings and adhesives production.
- Biodiesel:Fatty acid methyl ester from corn oil extraction at wet milling facilities. Biodiesel serves diesel engine oxygenate markets with distinct cold-flow property requirements.
Ethanol holds installed capacity across the US Midwest. Biobutanol is rotating up the share rankings as aviation fuel mandates tighten.
End User:
Application maturity varies sharply across customer categories, with transportation fleets commanding volume and industrial buyers extracting chemical value.
- Transportation:Fleet operators and gasoline blenders absorbing E10, E15, and flex-fuel volumes. California LCFS carbon intensity scoring rewards ethanol pathways with verified lifecycle emissions reductions, pulling low-carbon supply chains toward West Coast terminals.
- Industrial:Chemical processors and solvent manufacturers purchasing ethanol and acetone for manufacturing inputs. Industrial buyers prioritize specification consistency over carbon intensity attributes.
- Agriculture:Farm operations consuming ethanol-blended fuels and dried distillers grains for livestock feed. Agricultural demand clusters around processing facilities with captive feed distribution.
- Power Generation:Utility operators testing ethanol-gasoline blends in stationary engines and turbines. Power sector offtake remains experimental with limited commercial scale.
Transportation dominates volume absorption. Industrial buyers are expanding fastest on chemical substitution trends.
Application:
Technology readiness separates established internal combustion markets from emerging aviation and marine pathways requiring certification investment.
- Internal Combustion:Established gasoline blending for passenger vehicles and light trucks. The US gasoline pool's physical absorption limit near E10 saturation restricts volume growth without E15 infrastructure expansion.
- Aviation Fuels:Alcohol-to-jet processing for sustainable aviation fuel mandates across regulated US and EU jurisdictions. American Airlines and other carriers now source corn-derived volumes through direct bilateral agreements rather than petroleum intermediaries.
- Fuel Cells:Experimental ethanol reforming for hydrogen production in stationary and mobile applications. Fuel cell developers evaluate corn ethanol as a liquid hydrogen carrier.
- Marine Fuels:Biobutanol and ethanol blends for vessel propulsion under International Maritime Organization decarbonization pressure. Marine operators test biobutanol for compatibility with existing hydrocarbon infrastructure.
Internal Combustion holds mature market position. Aviation Fuels is climbing the fastest on regulatory procurement mandates.
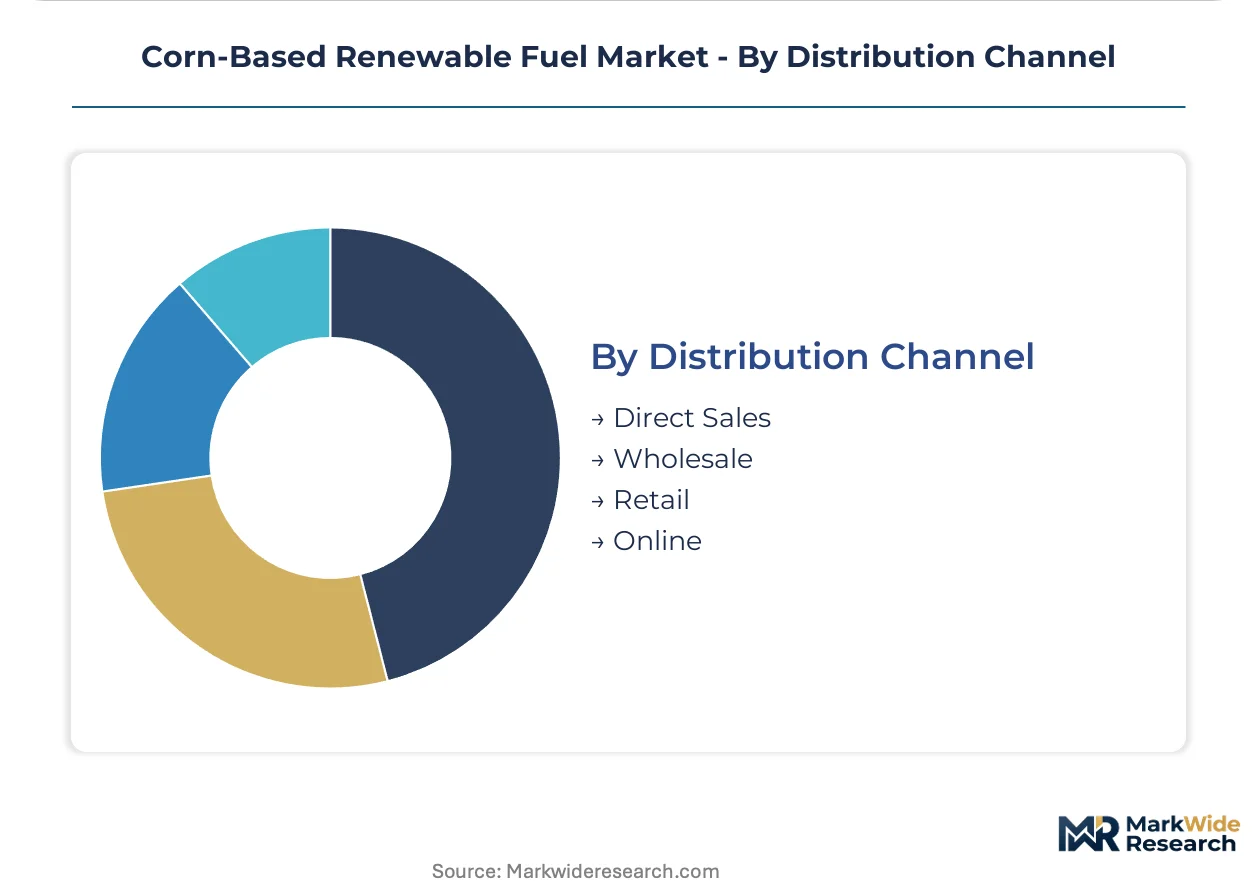
Distribution Channel:
Channel economics reflect bulk commodity handling requirements versus specialty product technical service needs.
- Wholesale:Terminal rack sales to gasoline blenders and fuel distributors. Wholesale channels aggregate volume from Iowa and Nebraska biorefineries for rail shipment to coastal demand centers.
- Direct Sales:Long-term offtake contracts with airline procurement departments and industrial chemical buyers. Direct negotiations concentrate around sustainable aviation fuel specifications and carbon intensity verification.
- Retail:Branded fuel stations offering E85 and flex-fuel pumps. Retail networks require dedicated infrastructure investment in blender pumps and storage tanks.
- Online:Digital procurement platforms for industrial chemical and solvent buyers. Online channels serve small-volume acetone and specialty bioproduct purchasers.
Wholesale channels command volume throughput. Direct Sales is gaining share fastest as airlines unbundle sustainable aviation fuel procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian ethanol exports flow primarily to United States and European Union markets under carbon intensity certification schemes. United States producers supply domestic transportation fleets and emerging sustainable aviation fuel offtakers. European Union demand pulls low-carbon supply chains through renewable energy directive compliance mechanisms.
United States
Transportation fleets and airline procurement departments absorb the majority of ethanol volumes. EPA Renewable Fuel Standard volume obligations mandate annual biofuel blending quotas that compress compliance timelines. Iowa and Illinois processing clusters concentrate production infrastructure around corn origination assets.
Brazil
Sugar-ethanol mills and corn ethanol plants serve both domestic flex-fuel vehicle pools and export markets. ANP administers RenovaBio carbon intensity certification for exported ethanol, shaping international trade arbitrage. São Paulo state biorefineries leverage established port infrastructure for Atlantic shipping routes.
Germany
Chemical processors and transportation blenders purchase ethanol for industrial solvent and fuel applications. EU Renewable Energy Directive sustainability criteria govern feedstock eligibility and greenhouse gas savings thresholds. Bavaria and North Rhine-Westphalia host biorefinery capacity integrated with regional chemical complexes.
China
State fuel ethanol blending mandates in designated provinces create planned demand absorption. National Energy Administration coordinates strategic reserve and blending ratio targets across pilot regions. Jilin and Henan provinces concentrate corn processing capacity near northeastern grain production belts.
Canada
Transportation fuel distributors blend ethanol under provincial renewable fuel requirements. Environment and Climate Change Canada enforces Clean Fuel Regulations with carbon intensity reduction obligations. Ontario and Saskatchewan biorefineries source feedstock from prairie corn and wheat production zones.
Corn-Based Renewable Fuel Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agribusiness conglomerates with captive corn origination networks. Mid-scale biorefinery operators compete on enzyme efficiency and carbon capture retrofit timing. Strategic archetypes separate starch-ethanol commodity producers, cellulosic technology licensors, and oilseed-ethanol diversifiers. Dominant competitive moves include backward integration into grain handling infrastructure and carbon capture partnership formations with pipeline operators.
Among North American agribusiness conglomerates, ADM and Cargill occupy positions anchored by wet milling infrastructure and origination scale. POET-DSM exemplifies the cellulosic technology tier through pilot-scale operations. Green Plains represents the pure-play biorefinery archetype focused on manufacturing optimization. European specialists including Verbio and Neste Oil sit within the renewable diesel and advanced biofuel diversification segment.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| POET-DSM |
| Green Plains |
| Neste Oil |
| Verbio |
| Infinita Renovables |
| Biopetrol |
| Ital Green Oil |
| Others |
Pricing and Supply Chain Analysis
Iowa and Illinois processing clusters concentrate over sixty percent of US ethanol capacity, granting operators leverage over regional basis differentials and terminal rack pricing. This geographic density compresses logistics costs for corn origination while amplifying margin pressure on peripheral facilities lacking pipeline access or carbon capture geology.
Pricing Analysis
First-generation starch ethanol trades at commodity benchmarks tied to gasoline futures and RIN credit values, while cellulosic pathways command modest premiums for lower carbon intensity scores under California LCFS protocols. Three-tier pricing structure across low-CI certified, standard RFS-compliant, and spot-market ethanol separates compliance buyers from speculative blenders. Pricing pressure stems from corn cost volatility transmitted through USDA yield reports and weather-driven crop conditions. Fleet operators and independent refiners exhibit highest price sensitivity, whereas airline procurement departments prioritize carbon intensity verification over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with ADM, Cargill, and Green Plains operating integrated wet milling and dry-grind facilities across the US Midwest. Geographic supply concentration centers on the United States, Brazil, and China, with Brazilian mills serving Atlantic export routes and Chinese state enterprises fulfilling provincial blending mandates. Raw material dependencies draw from corn starch, specialized cellulase enzymes, and natural gas for thermal processing. Supply chain risk hinges on single-source vulnerability for pipeline injection partnerships securing 45Q tax credit eligibility. Distribution runs through wholesale terminal racks aggregating rail shipments to coastal demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture retrofit services and ongoing LCFS credit verification represent recurring revenue layers expanding faster than base ethanol production, transforming capital equipment vendors into long-term service partners.
For Market Incumbents: Entrench through carbon capture retrofit timing and pipeline injection partnerships securing 45Q eligibility, while backward integration into grain handling infrastructure defends against margin compression from corn price volatility. Prioritize enzyme efficiency R&D to sustain yield advantages as cellulosic conversion economics mature. For New Entrants and Emerging Players: Build out sustainable aviation fuel offtake relationships with airline procurement departments unbundling from petroleum intermediaries, targeting alcohol-to-jet pathways as the most penetrable segment. Leverage direct bilateral contracting and carbon intensity certification to bypass wholesale terminal competition. For Investors and Strategic Acquirers: Long-term, this sits as a policy-anchored infrastructure play because EPA RFS and California LCFS mandates create durable offtake visibility regardless of commodity cycles. Target biorefinery operators with saline aquifer access for sequestration and existing rail spurs to coastal refineries. Monitor RenovaBio certification arbitrage signals between US and Brazilian supply chains as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | 45Q tax credit eligibility transforms fermentation stacks into revenue-generating assets independent of fuel margins. |
| Pipeline Injection Partnership | Saline aquifer access in Illinois and North Dakota secures permanent sequestration geology for compliance credit premiums. |
| Enzyme Efficiency Investment | Next-generation cellulase cocktails reduce fermentation cycle times and lift starch-to-ethanol yields at dry-grind facilities. |
| Aviation Fuel Certification | ASTM D7566 approval for alcohol-to-jet pathways opens direct procurement contracts with Delta and United sustainability teams. |
| Grain Handling Integration | Captive corn origination networks in Iowa and Nebraska buffer margin compression from USDA crop yield volatility. |
Research Methodology
Operator-level perspectives from biorefinery plant managers, enzyme procurement leads at processing facilities, airline sustainability officers, and carbon capture project developers anchored the qualitative base. Secondary validation drew from EPA RFS compliance filings, California Air Resources Board LCFS credit transaction data, USDA crop production reports, and SEC disclosures from publicly traded agribusiness conglomerates. Bottom-up capacity modeling triangulated against top-down demand projections from transportation fleet operators and industrial chemical buyers.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product chemistry, end-use application, carbon intensity certification tier, and regional regulatory cluster. CAGRs were derived from installed capacity trajectories, policy mandate enforcement timelines, and technology cost curves for cellulosic conversion pathways. Forecast inputs incorporated enzyme loading rate improvements, fermentation yield trends, and carbon capture retrofit adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cellulosic technology licensors or pipeline operators securing exclusive sequestration geology would shift outcomes. Regulatory revision to GREET lifecycle assessment methodologies or RFS volume obligation resets represent specific revision risks. Quarterly review of LCFS credit pricing, RenovaBio certification flows, and EPA enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
E-Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Hydrotreated Vegetable Oil Market