
 Sustainable Marine Fuel Market | 2026-2036
Sustainable Marine Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Marine Fuel Market Analytics
Bunkering infrastructure is reconfiguring around dual-fuel compatibility and green methanol storage. A.P. Moller-Maersk A/S anchors its fleet decarbonization through long-term methanol offtake contracts and vessel orders. Neste Corporation leverages its renewable diesel expertise to extend supply into marine distillates. TotalEnergies SE dominates European port-based bunkering through integrated production and terminal assets.
Sustainable marine fuel comprises renewable or low-carbon alternatives to conventional heavy fuel oil and marine gas oil, including fatty acid methyl ester biodiesel, hydrotreated vegetable oil, biomethanol, and ammonia synthesized from green hydrogen, typically requiring flash points above 60°C and sulfur content below 0.1% mass to meet ISO 8217 specifications. These fuels power commercial vessel propulsion and auxiliary engines while reducing well-to-wake carbon dioxide, sulfur oxide, and particulate emissions. Methanol leads fuel type development due to existing engine compatibility and established safety protocols, while biodiesel sustains near-term volume through drop-in blending with conventional distillates. Cargo ships anchor application demand given their aggregate fuel consumption and route predictability, whereas tankers present a growing segment as crude carriers face charterer-imposed carbon intensity clauses.
The International Maritime Organization's revised GHG strategy targets net-zero emissions by mid-century, while the EU FuelEU Maritime regulation enforces well-to-wake carbon intensity reductions on vessels at European Economic Area ports. Classification societies including DNV and Lloyd's Register now issue fuel-ready notations that dictate newbuild specifications and retrofit timelines. Stakeholders must monitor ammonia bunkering safety protocols and green hydrogen cost curves to time infrastructure commitments.
Market Dynamics
The Sustainable Marine Fuel Market pivots on bunkering infrastructure reconfiguration around dual-fuel compatibility, as vessel operators face compliance deadlines under the EU FuelEU Maritime regulation and the International Maritime Organization's revised GHG strategy.
Growth Catalysts
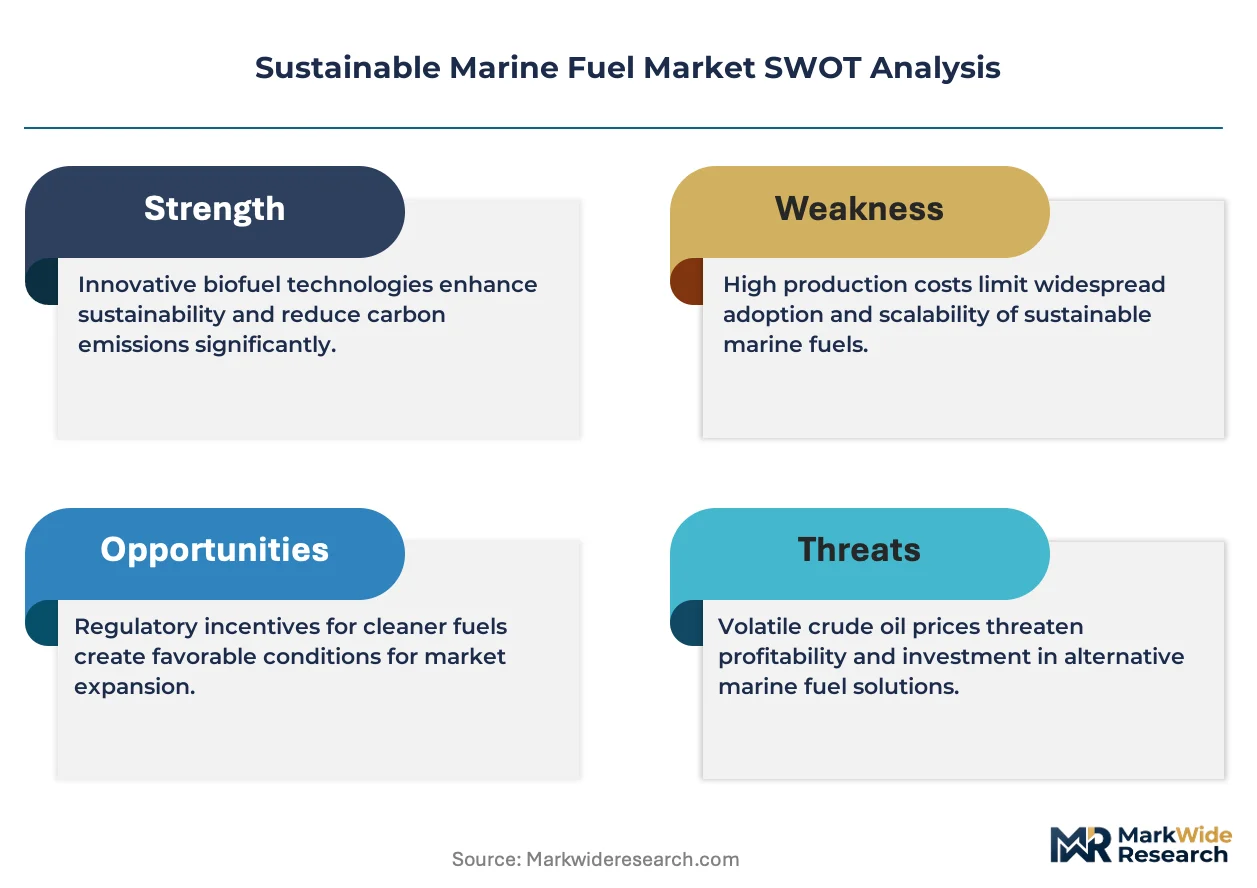
- EU FuelEU Maritime Regulation:The phased greenhouse-gas intensity reduction mandate for vessels calling at European Economic Area ports creates binding demand for certified low-carbon fuels and accelerates fleet renewal cycles.
- Engine Retrofit Compatibility:Methanol-compatible dual-fuel engines from MAN Energy Solutions and WinGD enable existing vessels to transition without full replacement, lowering adoption barriers for container shipping lines.
- Port Infrastructure Investment:Singapore, Rotterdam, and Shanghai are installing dedicated green methanol and ammonia storage terminals, concentrating supply-side capacity at primary bunkering hubs.
Market Restraints
- Green Hydrogen Cost Volatility:Electrolyzer capacity constraints and renewable electricity price fluctuations keep green methanol and ammonia production costs above fossil parity, compressing fuel supplier margins.
- Bunkering Infrastructure Gaps:Secondary ports outside Singapore, Rotterdam, and Shanghai lack certified storage and handling facilities, forcing vessels to deviate from optimal routes for refueling.
- ISO 8217 Certification Bottlenecks:Extended testing protocols for novel fuels delay commercial deployment timelines and strand capital in pre-certification inventory.
Strategic Opportunities
- Brazilian Deepwater Ports:Pre-salt oil field logistics and iron ore export volumes position Santos and Rio de Janeiro for ammonia bunkering infrastructure serving tanker and bulk carrier segments.
- Carbon Intensity Indicator Compliance Services:Fuel suppliers can bundle verified well-to-wake emissions data with physical delivery, capturing premium pricing from charterers facing IMO CII rating pressure.
- Power-to-X Convergence:Integration of offshore wind with electrolyzer arrays at port complexes enables localized green hydrogen production, reducing transport costs for synthetic marine fuels.
Industry Challenges
- Ammonia Handling Certification:Crew training programs for toxic fuel management lag behind vessel delivery schedules, creating operational readiness gaps for first-mover operators.
- Supply Chain Reconfiguration Friction:Conventional fuel oil traders lack expertise in renewable certificate tracking and mass-balance accounting, complicating procurement for ship operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Marine Fuel Market |
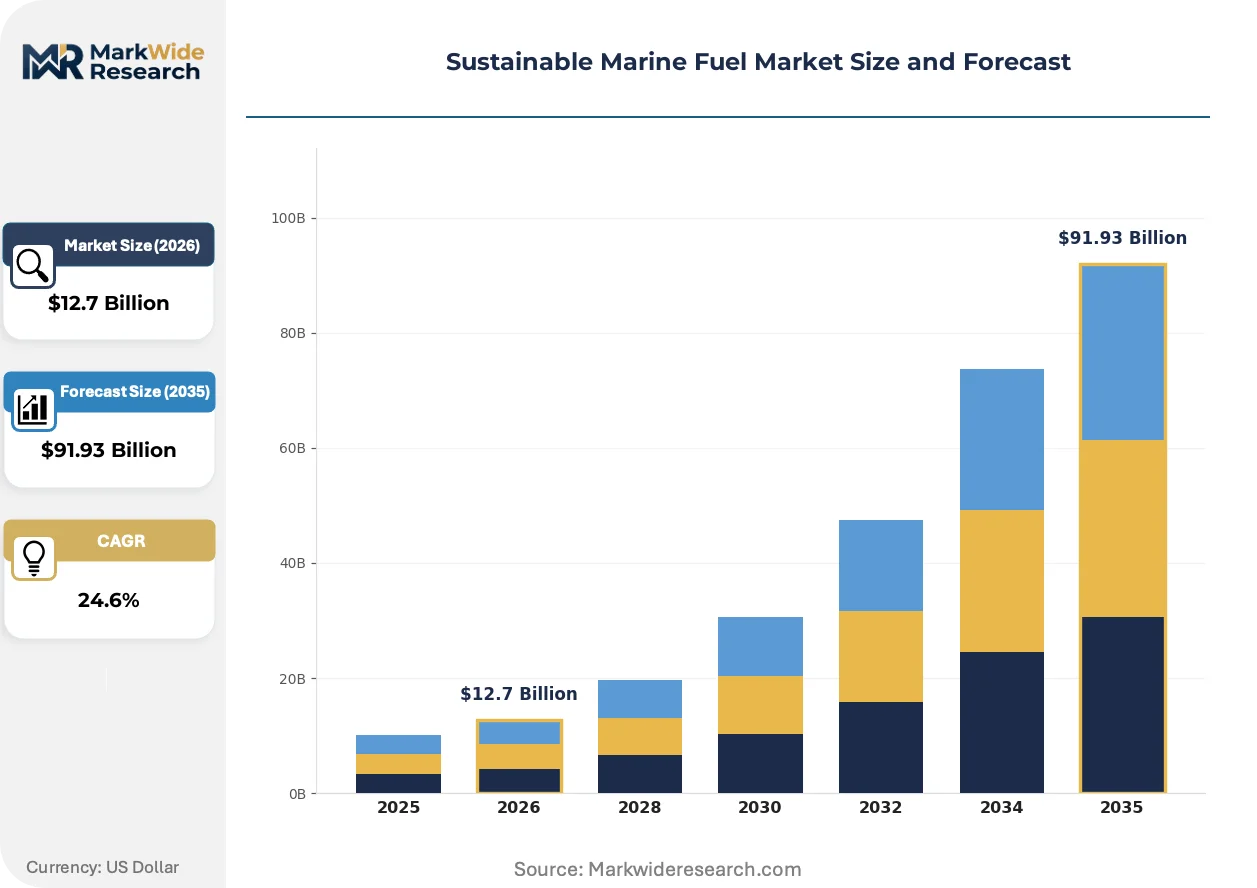
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $91.93 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
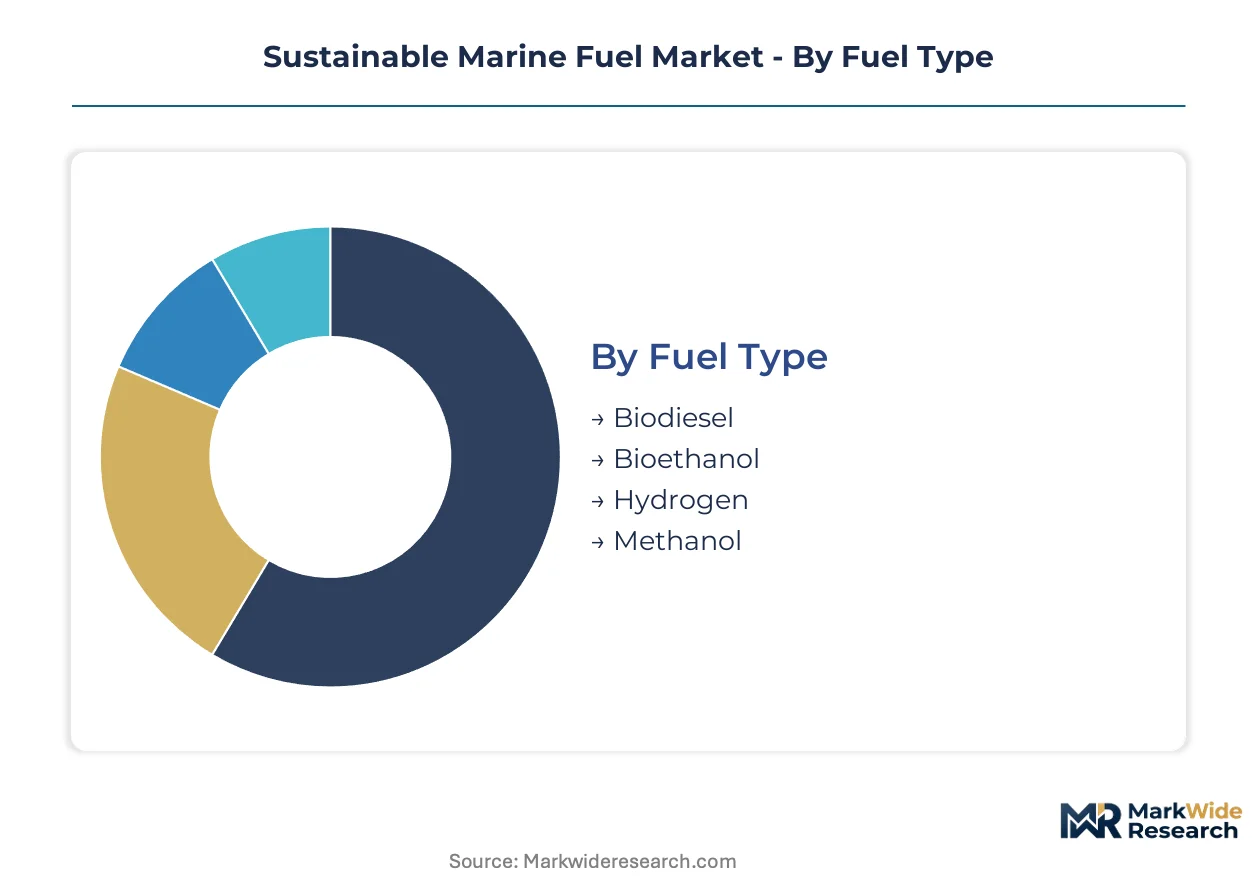
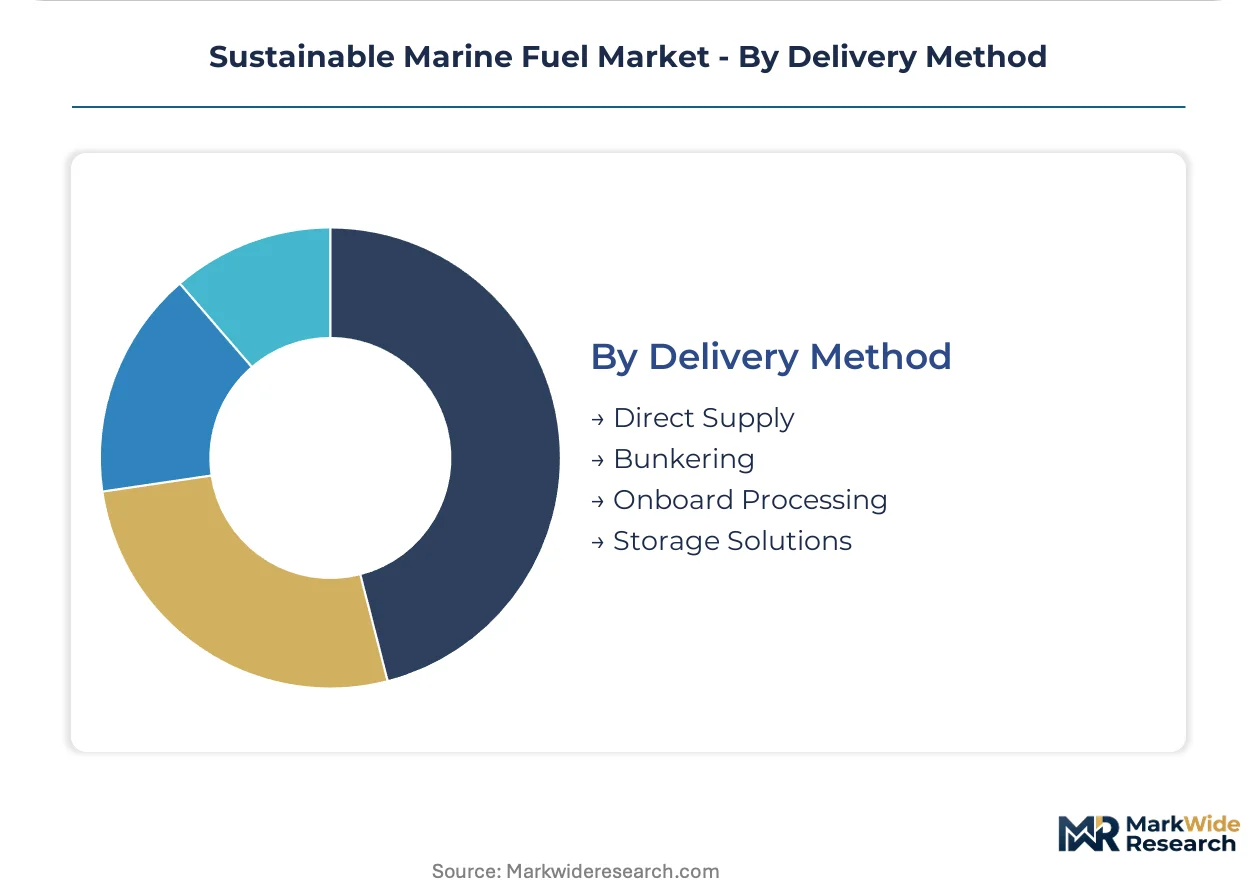
| Segmentation | Fuel Type: Biodiesel, Bioethanol, Hydrogen, Methanol Application: Cargo Ships, Ferries, Fishing Vessels, Tankers Supplier Type: Independent Suppliers, Major Oil Companies, Refineries, Technology Providers Delivery Method: Direct Supply, Bunkering, Onboard Processing, Storage Solutions |
| Companies Covered | Exxon Mobil Corporation, A.P. Moller-Maersk A/S, Neste Corporation, Gevo Inc., Chevron Corporation, TotalEnergies SE, BP plc, FincoEnergies, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Marine Fuel Market Evolving Landscape
Technology trajectories in marine propulsion are compressing the viable window for conventional heavy fuel oil, as regulatory compliance costs and charterer preferences restructure fleet economics around zero-carbon alternatives.
Dual-fuel methanol engines are rendering obsolete single-fuel diesel architectures in newbuild contracts. Container shipping lines now specify methanol-ready specifications for majority fleet orders, compressing the order book for conventional two-stroke designs and shifting shipyard capacity toward cryogenic fuel system integration.
The EU FuelEU Maritime regulation enforces well-to-wake carbon intensity reductions on vessels at European Economic Area ports, forcing fuel suppliers to document renewable provenance through certified mass-balance chains. Container lines calling at Rotterdam and Hamburg are restructuring procurement contracts around verified emissions scores rather than volumetric pricing alone.
Charterers now impose carbon intensity clauses in voyage contracts that penalize vessels with poor IMO CII ratings, shifting risk to shipowners and accelerating demand for drop-in biofuel blends. This preference compression is most visible in crude oil and iron ore trades, where cargo interests face Scope 3 disclosure pressure from European and North American institutional investors.
Sustainable Marine Fuel Market Segmentation
Sustainable marine fuel procurement varies sharply by vessel operating profile, fuel handling infrastructure, and contractual risk allocation. Segmentation reveals where capital deployment concentrates and which supply configurations match specific compliance pathways.
Fuel Type:
Cost tier stratification separates drop-in compatible fuels from synthetic alternatives requiring engine modification or dual-fuel systems.
- Methanol:Synthesized from natural gas or biomass with established IMO safety guidelines and flash point above 60°C. Container shipping lines at Rotterdam and Singapore anchor demand as dual-fuel engine orders from MAN Energy Solutions and WinGD accelerate. Methanol holds installed capacity. Hydrogen is rotating up the share rankings.
- Biodiesel:Fatty acid methyl esters and hydrotreated vegetable oils blend seamlessly with conventional marine gas oil under ISO 8217 specifications. Tanker operators plying EU ports favor biodiesel for immediate FuelEU Maritime compliance without vessel modification. Biodiesel sustains near-term volume through existing supply chains.
- Bioethanol:Fermentation-derived alcohol requiring engine calibration adjustments for marine use. Brazilian port authorities evaluate ethanol bunkering protocols for iron ore export routes.
- Hydrogen:Compressed or liquefied H2 for fuel cell or dual-fuel internal combustion applications. Norwegian coastal ferry operators pilot hydrogen systems under local zero-emission mandates.
Biodiesel leverages existing infrastructure. Methanol is climbing the fastest as shipyards retool for cryogenic fuel systems.
Application:
Vessel category determines fuel consumption scale, route predictability, and charterer carbon intensity exposure.
- Cargo Ships:Container vessels and bulk carriers with predictable liner schedules and aggregate fuel demand exceeding 10,000 tonnes annually. Maersk and MSC methanol offtake agreements concentrate at Singapore and Rotterdam where storage terminals scale to match. Cargo ships command procurement volume leadership.
- Tankers:Crude oil and product carriers facing charterer-imposed carbon intensity clauses from European cargo interests. Greek and Singapore-flagged tanker owners trial biodiesel blends to defend CII ratings on Middle East-Europe routes.
- Ferries:Short-sea and coastal passenger vessels with fixed schedules enabling shore-side charging or hydrogen refueling infrastructure. Scandinavian operators lead electrification and hydrogen pilots under national decarbonization programs.
- Fishing Vessels:Smaller displacement craft with fragmented ownership and limited capital for engine retrofit. Spanish and Portuguese fleet cooperatives aggregate biodiesel procurement to achieve volume pricing.
Cargo ships anchor fleet renewal investment. Tankers are gaining share fastest as crude charterers harden emissions clauses.
Supplier Type:
Supply concentration varies by integration depth, from integrated oil majors controlling terminal assets to technology licensors capturing margin through process licensing.
- Major Oil Companies:Integrated producers with captive refining, storage terminals, and marine fuel trading desks. TotalEnergies leverages European port infrastructure to bundle physical supply with certified mass-balance documentation.
- Refineries:Hydrotreatment facilities upgrading renewable feedstocks into marine distillates. Neste's Rotterdam refinery anchors renewable diesel supply expansion into bunkering markets.
- Independent Suppliers:Traders and distributors without production assets, relying on third-party certification and spot procurement. Singapore-based independents face margin compression as oil majors integrate downstream.
- Technology Providers:Electrolyzer manufacturers, e-fuel synthesis licensors, and fuel cell system integrators. ThyssenKrupp and Topsoe license ammonia and methanol production technology to project developers.
Major oil companies control terminal access. Technology providers are expanding most quickly as project developers seek licensed process packages.
Delivery Method:
Logistics configuration determines where capital efficiency concentrates and where operational risk transfers between supplier and vessel operator.
- Bunkering:Ship-to-ship or shore-to-ship fuel transfer at dedicated marine terminals. Rotterdam's Maasvlakte and Singapore's Tuas installations anchor green methanol bunkering capacity expansion.
- Storage Solutions:Terminals and tank farms with cryogenic or ambient storage for methanol, ammonia, or hydrogen. Project developers evaluate ammonia storage at Brazilian deepwater ports for iron ore export routes.
- Direct Supply:Long-term offtake contracts linking production facilities to specific vessel operators. Maersk's methanol supply agreements with European and US producers bypass spot market volatility.
- Onboard Processing:Vessel-mounted systems for fuel treatment, blending, or reforming. Methanol-to-hydrogen reformers for fuel cell auxiliary power remain pre-commercial for deep-sea applications.
Bunkering commands infrastructure investment. Direct supply is steepening its expansion trajectory as container lines lock in decade-long offtake security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power concentrates at Rotterdam and Singapore terminals, while secondary ports from Durban to Valparaíso absorb supply premiums of 15-40 percent above hub benchmarks. This asymmetry reshapes fleet deployment patterns and bunkering stopover economics.
Singapore
Container transshipment volumes exceeding 37 million TEU annually anchor methanol demand from Maersk and MSC fleets. The Maritime and Port Authority of Singapore mandates shore power and alternative fuel readiness for new terminal licenses. Tuas Port's Phase 2 expansion incorporates dedicated green methanol storage and ship-to-ship bunkering infrastructure.
Netherlands
Rotterdam's 14 million tonne marine fuel throughput attracts integrated suppliers seeking EU FuelEU Maritime compliance premiums. The Dutch government allocates €3.4 billion through the National Growth Fund for hydrogen import and e-fuel synthesis capacity. Maasvlakte terminals now host biomethanol storage alongside conventional fuel oil tanks.
United States
Gulf Coast methanol production from natural gas feedstock supplies coastal container routes, though green hydrogen cost gaps persist. The Inflation Reduction Act's clean fuel production credits reduce renewable marine fuel cost penalties versus fossil parity. Houston Ship Channel operators trial biodiesel blends for tanker fleets serving European crude importers.
China
Shanghai's Yangshan Port handles over 47 million TEU, driving demand for ammonia-compatible dual-fuel vessels on order at domestic shipyards. The Ministry of Transport's 14th Five-Year Plan for Green Transportation prioritizes methanol and hydrogen marine fuel pilots. Ningbo-Zhoushan port cluster develops bonded storage for imported biomethanol.
Brazil
Iron ore export volumes from Santos and Itaguaí position southeastern ports for ammonia bunkering serving Capesize bulk carriers. The Brazilian National Agency of Petroleum, Natural Gas and Biofuels (ANP) evaluates marine fuel quality standards for methanol and hydrogen derivatives. Pre-salt logistics operations create concentrated demand for low-carbon fuels on shuttle tanker routes.
Sustainable Marine Fuel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fuel synthesis and engine technology licensing. The supplier base stratifies between integrated oil majors with terminal assets and technology licensors capturing margin through process packages. Two archetypes dominate: vertically integrated energy conglomerates bundling physical supply with certified emissions documentation, and project developers relying on licensed e-fuel synthesis technology. Competitive moves concentrate on long-term offtake contracting and port terminal access negotiations.
Within the integrated supplier tier, Exxon Mobil Corporation and TotalEnergies SE occupy positions anchored by captive refining and bunkering infrastructure. Shell plc exemplifies the trading-and-terminals archetype, while Neste Corporation represents renewable refinery specialists extending hydrotreatment expertise into marine distillates. These named entities illustrate how supply-side positioning varies by upstream integration depth and geographic terminal concentration.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| A.P. Moller-Maersk A/S |
| Neste Corporation |
| Gevo Inc. |
| Chevron Corporation |
| TotalEnergies SE |
| BP plc |
| FincoEnergies |
| Shell plc |
| Others |
Value Network & Pricing Analysis
Undercapacity at Rotterdam's Maasvlakte and Singapore's Tuas terminals drives supplier behavior toward long-term offtake contracting and pricing posture anchored to green hydrogen cost curves rather than fossil parity benchmarks. Vessel operators face binding EU FuelEU Maritime compliance deadlines that compress procurement timelines and amplify premiums for certified low-carbon fuels.
Pricing Analysis
Certification-premium spreads separate ISO 8217-compliant methanol from uncertified blends by margins reflecting mass-balance documentation costs and renewable provenance verification. Contract-based long-term offtake structures dominate container shipping procurement, with Maersk and MSC locking in decade-long supply security at Rotterdam and Singapore. Price differentiation hinges on well-to-wake emissions scores and FuelEU Maritime compliance certification, with European cargo interests least price-sensitive due to Scope 3 disclosure pressure. Cost compression in biodiesel blending is intensifying as Neste and TotalEnergies expand hydrotreatment capacity.
Supply Chain Analysis
Extended payment terms from Singapore-based traders to Brazilian iron ore exporters are emerging as supply-chain finance facilities that bridge green methanol production cycles. Geographic supply concentration centers on Singapore, Rotterdam, and Shanghai where bonded storage and ship-to-ship bunkering infrastructure clusters. Raw material dependencies draw from natural gas reforming, biomass gasification, and electrolyzer-produced green hydrogen. Single-source vulnerability runs through Chinese electrolyzer manufacturing for ammonia synthesis projects. Distribution feeds from integrated oil major terminals to independent bunker suppliers at secondary ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel suppliers face substitution defense against battery-electric coastal shipping and hydrogen fuel cell ferries that capture short-sea routes under national zero-emission mandates. Incumbents must navigate charterer-imposed carbon intensity clauses that reallocate voyage contract risk toward vessel owners.
For Market Incumbents: Pre-empt technology provider encroachment by securing exclusive terminal access at Santos and Rio de Janeiro before ammonia bunkering infrastructure crystallizes. Backward integration into electrolyzer capacity at port complexes captures margin from green hydrogen production. Certification investment in IMO safety protocols for ammonia handling defends against first-mover operational readiness gaps.
For New Entrants and Emerging Players: Brazilian deepwater port underpenetration offers white-space targeting for ammonia bunkering serving Capesize bulk carriers on iron ore export routes. Scandinavian hydrogen ferry segments present the most penetrable application given fixed schedules and shore-side infrastructure feasibility. Go-to-market execution should anchor on power-to-X convergence partnerships with offshore wind developers at port complexes.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across e-fuel synthesis technology licensing as project developers seek turnkey process packages from ThyssenKrupp and Topsoe. Long-term viability favors vertically integrated energy conglomerates with captive terminal assets and certified mass-balance documentation capabilities. The signal to monitor is electrolyzer capacity expansion announcements at Rotterdam and Singapore that would compress green methanol cost premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Methanol Offtake Contracting | Maersk's supply agreements with European and US producers bypass spot market volatility. |
| Green Hydrogen Import Terminal Development | Dutch National Growth Fund allocations accelerate Maasvlakte e-fuel synthesis capacity buildout. |
| Ammonia Bunkering Safety Certification | DNV and Lloyd's Register fuel-ready notations dictate newbuild specifications and retrofit timelines. |
| Dual-fuel Engine Technology Licensing | MAN Energy Solutions and WinGD methanol-compatible systems lower adoption barriers for container lines. |
| Power-to-X Port Complex Integration | Offshore wind-electrolyzer arrays at Singapore's Tuas Port enable localized synthetic fuel production. |
Research Methodology
Desk research of IMO regulatory filings, EU FuelEU Maritime delegated acts, and classification society technical guidelines preceded structured interviews with marine fuel procurement managers, shipyard newbuild specification engineers, port authority infrastructure planners, and electrolyzer project developers. Secondary validation drew from Lloyd's List intelligence, DNV maritime forecast databases, and customs trade data for renewable feedstock flows. Bottom-up vessel fleet modeling and top-down bunkering throughput estimates were triangulated against supplier capacity announcements.
Assumptions around EU FuelEU Maritime enforcement stringency and green hydrogen cost reduction trajectories were held fixed across baseline scenarios while varying electrolyzer capacity deployment rates and ammonia engine commercialization timelines in sensitivity cases. Segmentation dimensions modeled encompassed fuel type synthesis pathway, vessel application category, supplier integration depth, and delivery method logistics configuration. CAGRs were derived from compound growth trajectory analysis of bunkering volume buildouts at Rotterdam, Singapore, and Shanghai terminals. Industry-specific forecast inputs incorporated MAN Energy Solutions and WinGD dual-fuel engine order backlogs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology licensors or independent project developers would shift outcomes through accelerated electrolyzer deployment. Macroeconomic deviation in renewable electricity pricing, regulatory enforcement delays, or breakthroughs in solid-oxide fuel cell marine applications would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
United States Propane Market