
 Green Ammonia Gas Market | 2026-2036
Green Ammonia Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Green Ammonia Gas Market Insights
The EU Green Deal is restructuring capital deployment across European green ammonia corridors. Siemens Energy leverages its proton exchange membrane electrolyzer portfolio to anchor large-scale project development in Northern Europe. Yara International sustains its position through backward integration into renewable hydrogen sourcing and captive offtake agreements with agricultural distributors. Nel ASA competes on modular electrolyzer scalability, enabling distributed production nodes near port facilities.
Green ammonia gas denotes anhydrous NH3 synthesized from nitrogen and hydrogen derived entirely from renewable energy sources, typically via water electrolysis powered by wind or solar, with specifications requiring carbon intensity below 0.3 kg CO2 equivalent per kilogram of ammonia. Its primary commercial purpose centers on decarbonizing hard-to-abate sectors where direct electrification proves technically or economically unfeasible. Electrolysis technology dominates current project pipelines, while energy storage applications represent the fastest-expanding demand pool as grid operators seek long-duration seasonal buffers. Fertilizers remain the most mature application segment, though margin pools increasingly migrate toward shipping fuel certification premiums.
The EU's F-Gas Regulation and REACH framework shape product purity standards and cross-border trade compliance for ammonia destined for European ports. EPA rules under the US Inflation Reduction Act channel production tax credits toward projects meeting strict lifecycle emissions thresholds, redirecting developer attention to domestic offtake. Japan's METI has established import certification protocols that buyers must navigate for supply contract eligibility. Stakeholders must monitor how divergent national hydrogen strategies reconcile around harmonized green ammonia certification before committing to multi-billion dollar production assets.
Market Dynamics
The maritime sector's bunker fuel transition is compressing project timelines for electrolysis-based ammonia synthesis, as port operators and shipping lines negotiate long-term offtake contracts ahead of infrastructure deployment.
Growth Catalysts
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive ammonia are redirecting capital toward electrolysis projects in Northern Europe. German industrial clusters now co-locate renewable generation with ammonia synthesis to secure compliance margins.
- Maritime shipping decarbonization:International Maritime Organization targets are forcing fleet operators to secure zero-carbon bunker fuel supply chains. Rotterdam and Hamburg port authorities are prioritizing green ammonia storage and bunkering infrastructure.
- Proton exchange membrane electrolyzers:Modular stack designs are reducing minimum viable plant scale, enabling distributed production nodes near wind farms in Denmark and solar installations in Spain.
Market Restraints
- Renewable electricity cost volatility:Intermittent wind and solar output in the North Sea region creates input cost uncertainty that undermines project financing terms for baseload ammonia production.
- Electrolyzer supply concentration:Stack manufacturing capacity concentrates in Germany and Norway, creating equipment delivery bottlenecks for developers outside established supplier relationships.
- Hydrogen transport economics:Ammonia cracking efficiency losses and dedicated infrastructure requirements limit cost-competitive radius from production sites to coastal demand centers.
Strategic Opportunities
- US Inflation Reduction Act production tax credits:EPA lifecycle emissions thresholds are attracting developer attention toward domestic offtake markets with guaranteed price premiums for certified low-carbon ammonia.
- Long-duration grid storage:Power utilities in Japan and South Korea are piloting ammonia combustion for seasonal electricity generation, creating demand outside traditional fertilizer and shipping segments.
- Backward integration by agricultural distributors:Fertilizer cooperatives are securing captive hydrogen supply through equity stakes in electrolysis projects, capturing margin pools previously held by commodity traders.
Industry Challenges
- Electrolyzer engineering talent scarcity:Specialized stack design and systems integration expertise concentrates with incumbent suppliers, constraining new entrant project execution timelines.
- Green certification fragmentation:Divergent national hydrogen strategies between the EU, Japan's METI protocols, and emerging frameworks in Australia create compliance complexity for multi-jurisdictional offtake contracts.
- Legacy ammonia infrastructure retrofit costs:Existing storage and handling facilities require material compatibility upgrades for high-purity electrolysis-derived product, extending commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Ammonia Gas Market |
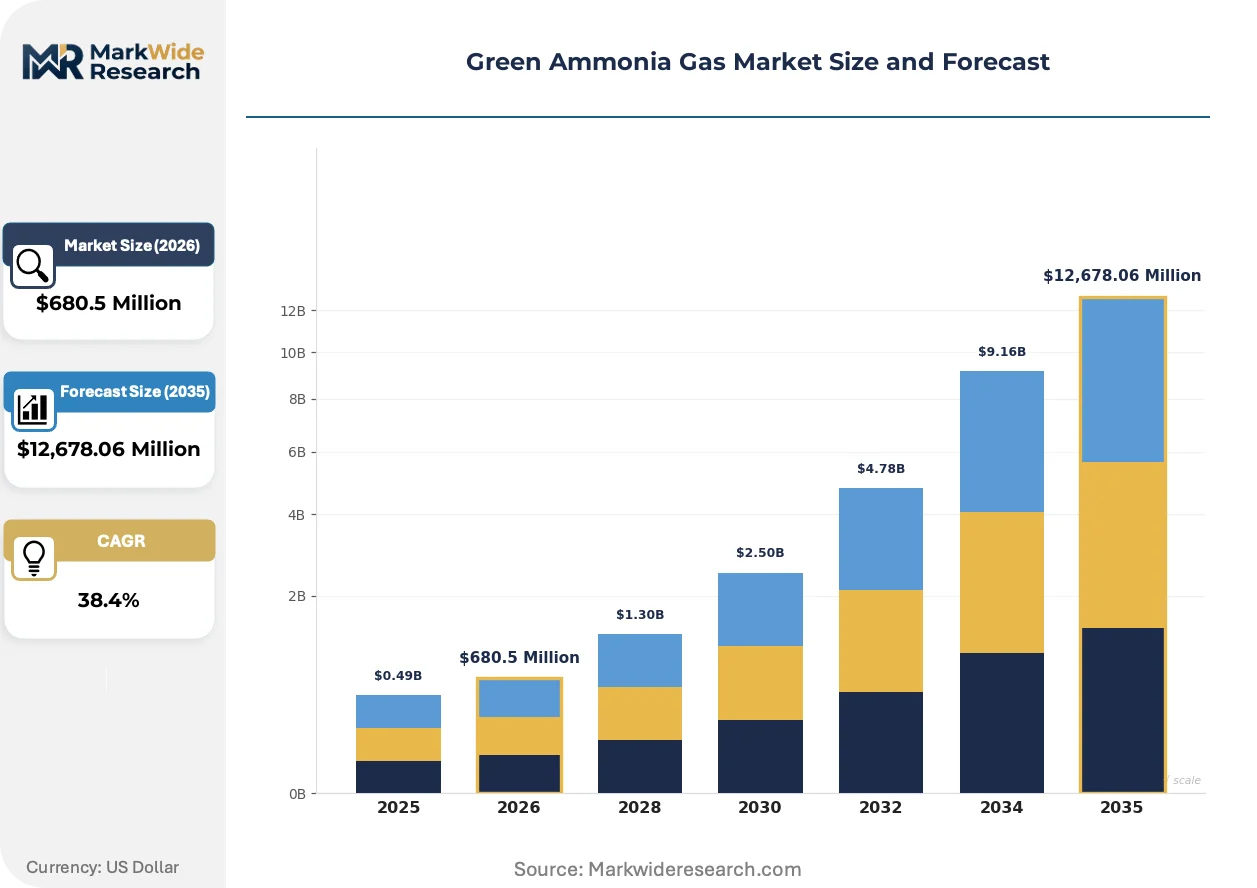
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $12,678.06 Million |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Biomass Gasification, Methane Pyrolysis, Solar Thermochemical Application: Fertilizers, Energy Storage, Shipping Fuel, Chemical Feedstock End User: Agriculture, Power Generation, Marine, Industrial Distribution Channel: Direct Sales, Distributors, Online Retail, Merchants |
| Companies Covered | Siemens Energy, ACME Group, ThyssenKrupp AG, Nel ASA, Yara International, CF Industries Holdings, Ørsted, Iberdrola, ITM Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Ammonia Gas Market Trends and Innovations
Solid oxide electrolysis technology is compressing energy intensity benchmarks for ammonia synthesis, while regulatory frameworks in major economies are hardening carbon intensity thresholds for import eligibility.
Solid oxide electrolysis cells are integrating with high-temperature industrial heat sources to achieve conversion efficiencies above alkaline and PEM alternatives. Steel producers in Sweden and cement manufacturers in Poland are piloting co-located ammonia synthesis to utilize waste heat from clinker and blast furnace operations. This thermal integration is enabling project economics that standalone renewable configurations cannot match in Northern European climates.
The EU F-Gas Regulation and REACH framework are tightening purity specifications for ammonia destined for European ports, with ECHA documentation requirements extending to supply chain due diligence. Industrial gas distributors are restructuring procurement contracts to include certified low-carbon provenance clauses. Fertilizer blenders in the Netherlands and Germany are now requiring third-party verification of electrolysis electricity origin to maintain product registration.
Shipping lines are consolidating bunker fuel procurement through dedicated ammonia trading desks, displacing fragmented spot-market purchasing for conventional marine fuels. Maersk and MSC are negotiating direct supply agreements with electrolysis project developers, bypassing traditional commodity traders. This vertical contracting is most visible in Singapore and Rotterdam, where port infrastructure investments are aligning with carrier fleet renewal timelines.
Green Ammonia Gas Market Segmentation
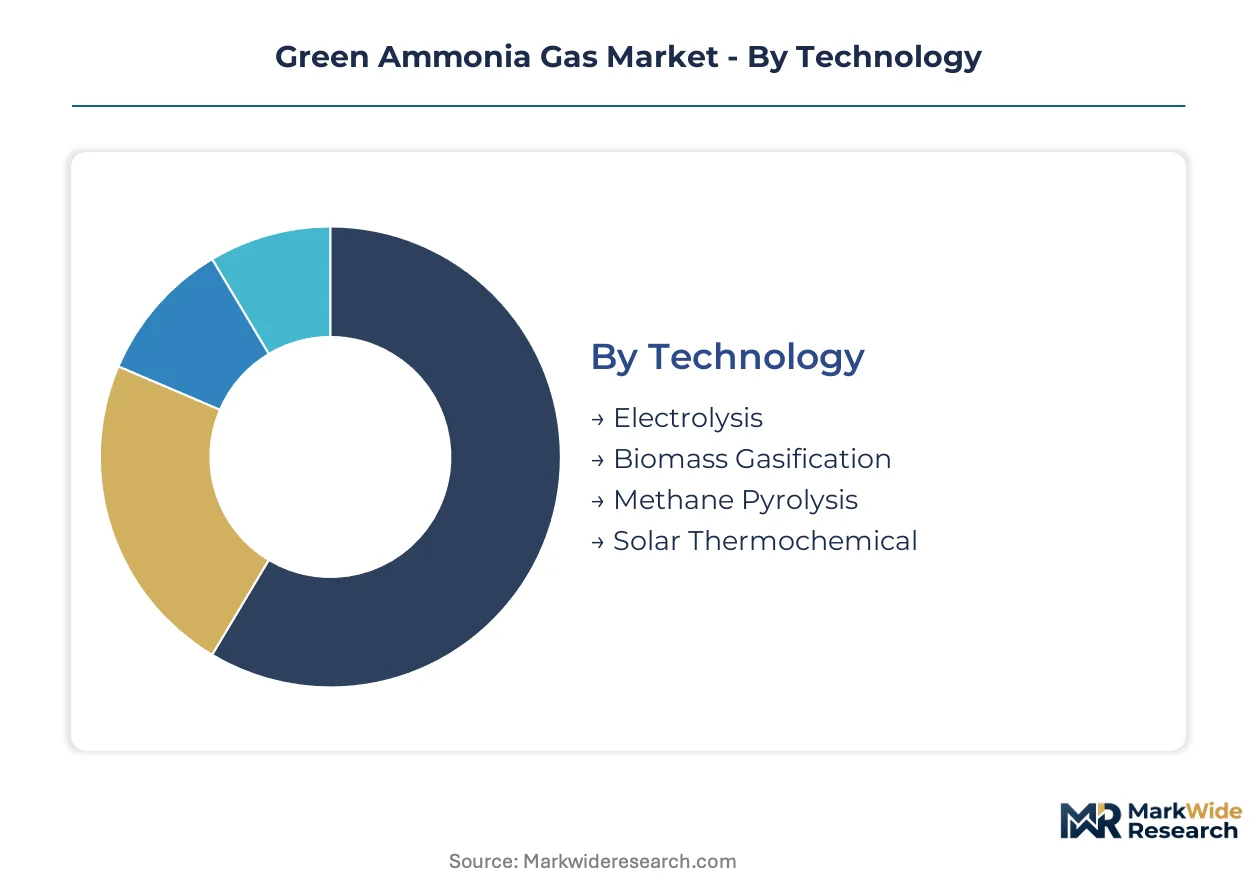
Green ammonia gas markets fragment across production pathways and end-use specifications that determine carbon intensity certification, infrastructure requirements, and offtake contract structures. Technology choice locks in capital intensity and renewable electricity sourcing strategy for project developers.
Technology:
Electrolyzer chemistry dictates renewable hydrogen production efficiency and project scalability across European wind corridors and Southern European solar installations.
- Electrolysis:Water splitting via proton exchange membrane or alkaline systems powered by dedicated renewable generation delivers sub-0.3 kg CO2e/kg ammonia specifications required by EU carbon border adjustments. German industrial clusters co-locate PEM stacks with North Sea offshore wind to secure compliance premiums for fertilizer and shipping fuel offtake.
- Biomass Gasification:Thermochemical conversion of agricultural residues and forestry waste into syngas for ammonia synthesis offers dispatchable production independent of renewable electricity intermittency. Developers in Poland and the Baltic states leverage existing biomass supply chains from district heating networks to anchor project economics.
- Methane Pyrolysis:Thermal cracking of natural gas yields hydrogen and solid carbon, with renewable electricity powering the endothermic reaction to meet green certification thresholds.
- Solar Thermochemical:Concentrated solar thermal drives high-temperature water splitting cycles, achieving conversion efficiencies above conventional electrolysis in Iberian and Italian solar resource zones.
Electrolysis leads on scale; solar thermochemical leads on momentum.
Application:
End-use specifications diverge sharply on purity requirements, delivery pressure, and carbon intensity verification protocols.
- Fertilizers:Ammonia for nitrogen fertilizer production constitutes the most mature demand pool, with European blenders requiring third-party verification of electrolysis electricity origin under REACH framework documentation. Dutch and German agricultural cooperatives are securing captive hydrogen supply through equity stakes in electrolysis projects.
- Shipping Fuel:Maritime bunker fuel applications command certification premiums as International Maritime Organization targets force fleet operators to contract zero-carbon supply chains ahead of Rotterdam and Hamburg infrastructure deployment.
- Energy Storage:Power utilities in Japan and South Korea pilot ammonia combustion for seasonal electricity generation, creating demand outside traditional segments.
- Chemical Feedstock:Industrial gas distributors restructure procurement contracts to include certified low-carbon provenance clauses for nitric acid and caprolactam production.
Fertilizers anchor current volume; shipping fuel commands expanding margin pools.
End User:
Customer scale and contracting sophistication determine project financing structures and offtake security.
- Agriculture:Fertilizer cooperatives and agricultural distributors represent the largest contracted demand base, with backward integration strategies capturing margin pools previously held by commodity traders through direct equity in electrolysis assets.
- Power Generation:Grid operators in Japan pilot long-duration seasonal storage applications, while European utilities evaluate ammonia co-firing for dispatchable renewable backup.
- Marine:Container shipping lines consolidate bunker procurement through dedicated ammonia trading desks, negotiating direct supply agreements that bypass traditional commodity traders.
- Industrial:Steel and cement producers in Sweden and Poland pilot co-located synthesis to utilize waste heat from blast furnace and clinker operations.
Agriculture dominates contracted offtake; marine is climbing the fastest.
Distribution Channel:
Channel structure reflects customer concentration, delivery infrastructure requirements, and certification custody chain complexity.
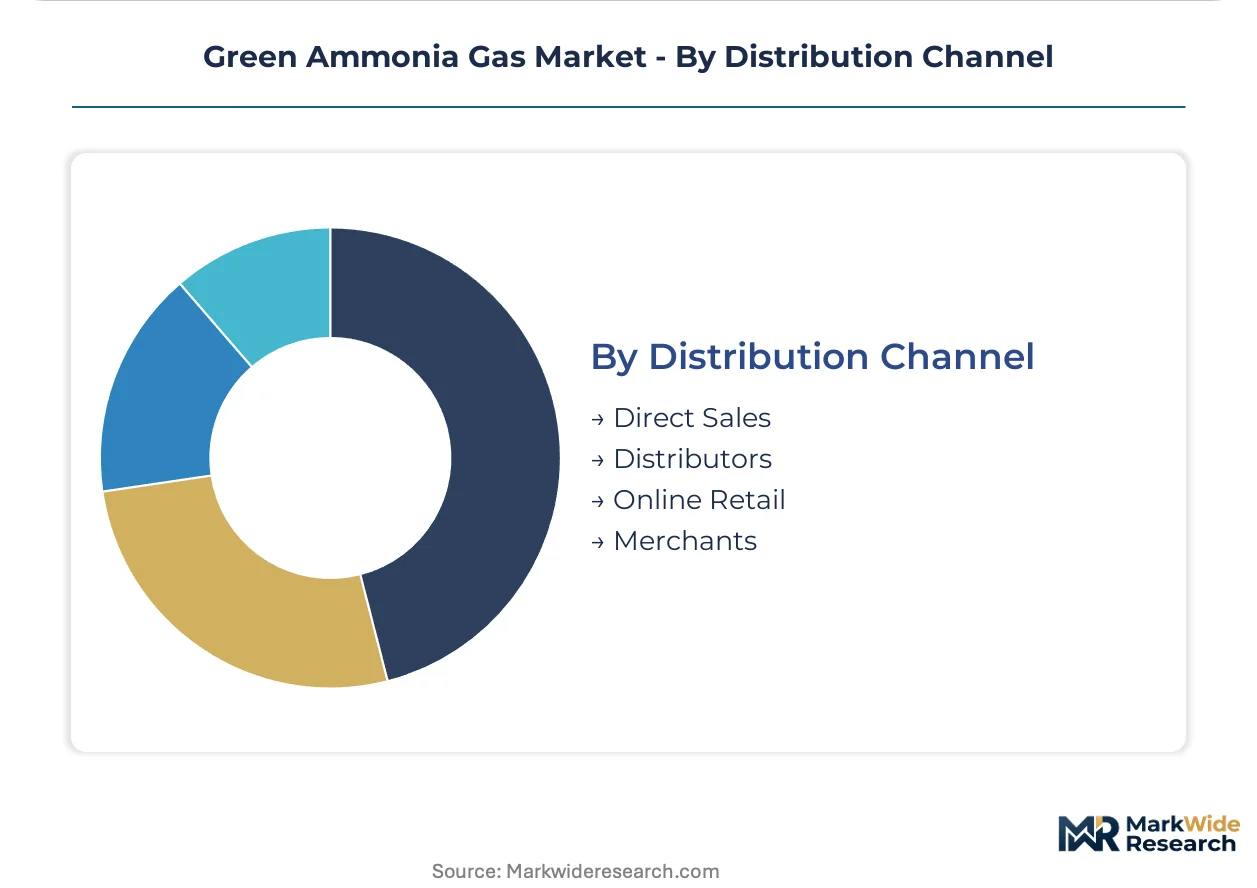
- Direct Sales:Long-term offtake contracts between electrolysis project developers and large-scale consumers—shipping lines, fertilizer cooperatives, industrial gas distributors—secure project financing by eliminating intermediary margin extraction and ensuring carbon provenance documentation integrity.
- Distributors:Industrial gas distributors restructure procurement to include certified low-carbon provenance clauses, managing storage and last-mile delivery for fragmented agricultural and chemical processing customers.
- Online Retail:Digital platforms emerge for spot-market transactions and certification trading in pilot European hydrogen exchange frameworks.
- Merchants:Commodity traders adapt traditional ammonia trading desks to handle green certification premiums and renewable electricity origin verification.
Direct sales concentrate value capture; distributors maintain reach breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolyzer engineering talent clusters in Germany and Norway anchor project development across Northern European wind corridors, while port infrastructure investments concentrate in Rotterdam and Hamburg.
Germany
Industrial demand from fertilizer cooperatives and steel producers drives electrolysis project pipelines. The EU Green Deal's carbon border adjustments redirect capital toward North Sea offshore wind co-location. The Hamburg industrial cluster now hosts multiple gigawatt-scale ammonia synthesis facilities under construction.
Netherlands
Rotterdam port authorities prioritize green ammonia bunkering infrastructure to capture maritime fuel switching. REACH framework documentation requirements tighten purity specifications for import eligibility. The Port of Rotterdam Authority coordinates storage and handling upgrades with shipping line fleet renewal timelines.
United States
EPA production tax credits under the Inflation Reduction Act attract developer attention toward domestic offtake markets. Gulf Coast petrochemical corridors evaluate retrofit pathways for electrolysis integration. Texas wind and solar installations anchor pilot projects targeting fertilizer and chemical feedstock demand.
Japan
METI import certification protocols shape supply contract eligibility for power utilities piloting seasonal ammonia combustion. Long-duration grid storage applications create demand outside traditional segments. The Chubu region concentrates pilot facilities evaluating ammonia co-firing for dispatchable renewable backup.
Australia
Solar resource abundance in Western Australia and Queensland drives solar thermochemical pilot development. Export-oriented project developers target Asian offtake markets with dedicated shipping corridors. The Pilbara region co-locates renewable generation with ammonia synthesis for bulk commodity export.
Green Ammonia Gas Market Competitive Landscape
The competitive structure tilts toward industrial conglomerates with captive hydrogen demand and specialized electrolyzer fabricators. Market concentration remains moderate, with distinct capability tiers separating gigawatt-scale project developers from modular equipment suppliers. Two strategic archetypes dominate: integrated energy majors leveraging renewable generation portfolios, and pure-play electrolyzer specialists competing on stack efficiency metrics. Dominant competitive moves include backward integration into renewable hydrogen sourcing and strategic partnerships between stack manufacturers and port operators.
Within the integrated energy tier, Siemens Energy and Ørsted exemplify project development archetypes anchored by renewable generation control. Among specialized electrolyzer fabricators, Nel ASA occupies a position representing modular stack scalability, while ITM Power sits within the proton exchange membrane specialization cluster. Yara International and CF Industries Holdings represent agricultural and chemical incumbents securing captive supply through equity participation in production assets. ThyssenKrupp AG and ACME Group anchor engineering and project development capabilities across European and Asian corridors respectively. Iberdrola exemplifies utility-led vertical integration into ammonia synthesis for industrial offtake.
| Leading Market Players |
|---|
| Siemens Energy |
| ACME Group |
| ThyssenKrupp AG |
| Nel ASA |
| Yara International |
| CF Industries Holdings |
| Ørsted |
| Iberdrola |
| ITM Power |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed project developers in Northern Europe and state-supported consortia in East Asia anchor supply capacity, creating pricing discipline that reflects long-dated offtake security rather than spot-market volatility. Their financing structures reward carbon intensity certification premiums while penalizing developers without guaranteed renewable electricity offtake.
Pricing Analysis
Bundled long-term offtake contracts dominate over unbundled spot transactions, with electrolysis project developers packaging renewable hydrogen production, ammonia synthesis, and carbon certification into unified supply agreements. Price differentiation rests on certification grade—EU carbon border adjustment compliance commands substantial premiums over uncertified product—and volume scale, with gigawatt-scale facilities securing preferential terms against modular pilot plants. Cost compression in the standard tier is intensifying because electrolyzer manufacturing capacity bottlenecks in Germany and Norway are extending delivery timelines and inflating capital costs. Fertilizer cooperatives exhibit highest price sensitivity due to thin agricultural commodity margins, while maritime shipping lines absorb premiums to secure IMO-compliant bunker fuel supply chains.
Supply Chain Analysis
Certification and qualification gating through EU REACH documentation, Japan's METI import protocols, and EPA lifecycle emissions thresholds fragments supplier eligibility and concentrates procurement relationships. Manufacturing draws from Germany, Norway, and Denmark for electrolyzer stack production, with China emerging for balance-of-plant components. Raw material dependencies center on iridium and platinum group metals for PEM catalysts, specialized polymer membranes, and high-purity nickel for alkaline systems. Single-source vulnerability in iridium sourcing from South African mines creates supply chain risk. Distribution runs through dedicated ammonia trading desks at Rotterdam and Singapore, displacing traditional commodity merchant structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon border adjustment compliance premiums and US Inflation Reduction Act production tax credit yields, with developers optimizing project location based on regulatory differential magnitude.
For Market Incumbents: To counter modular electrolyzer specialists encroaching on distributed production nodes, Siemens Energy and Ørsted should deepen backward integration into renewable generation portfolios while locking exclusive port infrastructure access at Rotterdam and Hamburg through long-term concession agreements.
For New Entrants and Emerging Players: Launch via direct sales to agricultural cooperatives in Poland and the Baltic states, where biomass gasification pathways offer dispatchable production independent of renewable intermittency and existing district heating supply chains reduce feedstock procurement risk.
For Investors and Strategic Acquirers: Valuations sit cheapest among engineering-procurement-construction contractors without captive offtake, presenting acquisition targets with project development capabilities but lacking financing scale. Long-term viability hinges on electrolyzer stack efficiency convergence with solid oxide alternatives. The signal to watch is harmonization progress between EU, Japanese, and Australian certification frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Generation | Siemens Energy secures electricity cost predictability for North Sea electrolysis projects. |
| Port Infrastructure Concession Lock-Up | Rotterdam Authority aligns storage deployment with Maersk fleet renewal timelines. |
| Biomass Gasification Pathway Development | Polish developers leverage existing district heating feedstock supply chains. |
| Long-Duration Grid Storage Pilot Expansion | Chubu Electric evaluates ammonia co-firing for seasonal renewable backup. |
| Green Certification Program Harmonization | Stakeholders bridge EU REACH and Japan METI protocol divergence. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolyzer engineering directors, port authority infrastructure planners, fertilizer cooperative procurement leads, and maritime fuel trading desk heads with secondary validation from EIA project databases, IEA hydrogen reports, EU ETS carbon price series, and FERC interconnection queue filings. Bottom-up capacity buildout modeling triangulated against top-down demand absorption forecasts.
Segment-weighting applied technology pathway splits across electrolysis, biomass gasification, and emerging thermochemical routes, crossed with application dimensions spanning fertilizer, shipping fuel, energy storage, and chemical feedstock end uses. CAGRs were derived from installed capacity ramp rates, learning curve cost reductions, and regulatory mandate enforcement schedules. Forecast inputs incorporated EU carbon border adjustment phase-in timing and IMO marine fuel carbon intensity target stringency.
Forecast precision tightens around the base case; tail outcomes carry wider variance under electrolyzer supply chain disruption or certification framework fragmentation scenarios. Projections reflect documented assumptions about renewable electricity cost trajectories and electrolyzer efficiency gains. A model refresh is warranted upon material change in EU-Japan certification harmonization negotiations or IRA credit extension decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Aviation Alternative Fuel Market