
 Refuse Derived Fuel Market | 2026-2036
Refuse Derived Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Refuse Derived Fuel Market Outlook
The long-term supply contract channel is fragmenting as cement producers and independent power generators compete for consistent refuse derived fuel volumes. Veolia leverages integrated waste collection networks across France and Belgium to secure captive feedstock streams. Renewi anchors its position through mechanical biological treatment assets that upgrade municipal solid waste into specification-grade fuel. Biffa competes aggressively in the United Kingdom spot market while building dedicated offtake partnerships with Lafarge and HeidelbergCement facilities.
Refuse derived fuel comprises processed municipal, commercial, and industrial waste streams shredded, screened, and dried to achieve calorific values typically between 15 and 25 megajoules per kilogram, serving as a direct coal substitute in cement kilns and power boilers. Municipal solid waste feedstock dominates volume throughput across European processing plants due to gate fee economics and collection infrastructure maturity. Pyrolysis technology commands premium margins in niche applications where contaminant removal specifications exceed standard incineration thresholds. Cement manufacturing absorbs the largest share of high-specification output because kiln operators require consistent calorific content and low chlorine fractions to protect refractory linings.
The European Commission's Waste Framework Directive and Industrial Emissions Directive together mandate landfill diversion targets and set air emission ceilings for co-incineration facilities. EPA standards in the United States govern maximum achievable control technology for solid waste combustion units, shaping stack emission limits and feedstock pre-processing requirements. Stakeholders must monitor evolving carbon border adjustment mechanisms and national renewable energy certificate schemes that will determine whether refuse derived fuel qualifies for green power subsidies or incurs carbon leakage penalties.
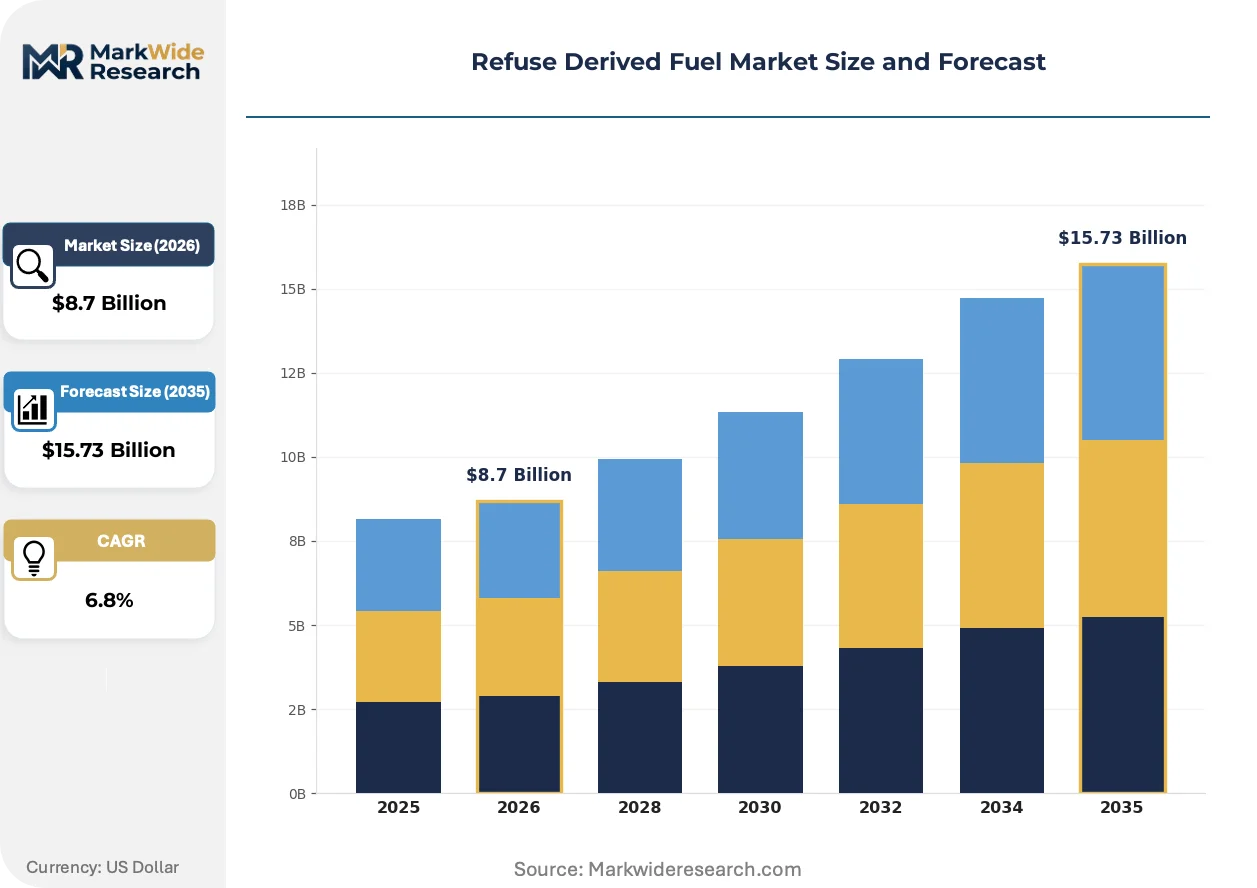
Market Dynamics
The EU landfill diversion mandate is compressing waste supply chains toward energy recovery, forcing cement manufacturers to secure long-term offtake contracts before municipal competitors lock up feedstock volumes. This regulatory pressure is fragmenting procurement channels and elevating fuel specification requirements across European processing infrastructure.
Growth Catalysts
- EU Waste Framework Directive:Binding landfill diversion targets in Germany, the United Kingdom, and the Netherlands are redirecting municipal solid waste streams toward RDF processing facilities, tightening gate fee economics in favor of energy recovery.
- Cement kiln substitution:High-temperature cement manufacturing operations require consistent calorific content between 15 and 25 megajoules per kilogram, creating durable demand for specification-grade refuse derived fuel as direct coal replacement.
- Mechanical biological treatment:Advanced sorting and drying technologies are upgrading lower-quality municipal waste into export-grade fuel, expanding addressable feedstock pools beyond traditional commercial and industrial sources.
Market Restraints
- Chlorine contamination thresholds:Cement kiln refractory protection requirements impose strict sub-0.5% chlorine limits on RDF input, forcing costly pre-processing or rejecting entire municipal waste batches with seasonal contamination spikes.
- Feedstock competition:Independent power generators and district heating operators in Scandinavia and Benelux are bidding up spot market prices for consistent calorific volumes, compressing margin structures for long-term contract holders.
- Air emission ceilings:The EU Industrial Emissions Directive mandates continuous stack monitoring and selective catalytic reduction systems, adding capital intensity to co-incineration facility permitting and operations.
Strategic Opportunities
- Pyrolysis technology convergence:Thermal decomposition systems combined with advanced flue gas treatment are opening premium market segments where contaminant removal specifications exceed standard grate incineration capabilities.
- Eastern European processing gap:Poland, Romania, and Bulgaria maintain higher landfill dependency rates than Western European benchmarks, creating first-mover advantages for integrated waste-to-energy infrastructure development.
- Carbon border adjustment positioning:Early alignment with emerging EU carbon leakage frameworks may qualify RDF-derived thermal output for green certificate schemes, differentiating compliant suppliers in procurement tenders.
Industry Challenges
- Feedstock quality variance:Seasonal shifts in municipal solid waste composition—particularly moisture content and plastic film contamination—require continuous process calibration to maintain specification-grade output consistency.
- Refractory damage risk:Chlorine and alkali metal excursions in kiln fuel supply can trigger unplanned shutdowns, forcing cement operators to implement costly real-time fuel testing protocols and supplier penalty clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refuse Derived Fuel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Municipal Solid Waste, Commercial Waste, Industrial Waste, Biomass Technology: Gasification, Pyrolysis, Incineration, Anaerobic Digestion End User: Energy Generation, Cement Manufacturing, Transportation, Industrial Heating Distribution Channel: Direct Sales, Online Platforms, Distributors, Waste Management Companies |
| Companies Covered | Renewi, FCC Environment, Covanta, Jinjiang Environment, Indaver, Veolia, Biffa, TPI Polene Power, SUEZ Recycling and Recovery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refuse Derived Fuel Market Strategic Shifts
Processing technology is converging with emission control systems to produce higher-specification fuel outputs, while regulatory frameworks increasingly tie waste diversion compliance to carbon accounting methodologies. These forces are elevating technical barriers to entry and rewarding integrated operators with captive collection networks.
Advanced mechanical biological treatment is hybridizing traditional shredding and screening with optical sorting and eddy current separation to remove non-combustible fractions. Cement manufacturers in Germany and the Netherlands are adopting these upgraded fuel streams for kiln co-firing at 15-30% substitution rates. The technology is hybridizing quality thresholds across the supplier base, compressing margins for basic processors while rewarding integrated treatment asset operators.
REACH chemical registration requirements and the EU F-Gas Regulation are tightening material traceability for plastic-derived fuel fractions, particularly PVC and halogenated flame retardants. Industrial emissions monitoring now extends to persistent organic pollutant screening, forcing RDF producers to document feedstock provenance. Cement facilities in Belgium and northern France are responding by requiring supplier certifications that exclude specific polymer categories from municipal waste streams.
Long-term offtake contracting is displacing spot market procurement as cement groups prioritize supply security over price optimization. Lafarge and HeidelbergCement facilities are locking in five-to-ten-year fuel supply agreements with dedicated processing partners, bypassing merchant market volatility. This pattern concentrates most visibly in the United Kingdom, where landfill tax escalation has compressed waste disposal alternatives and elevated RDF to baseline fuel status for kiln operations.
Refuse Derived Fuel Market Segmentation
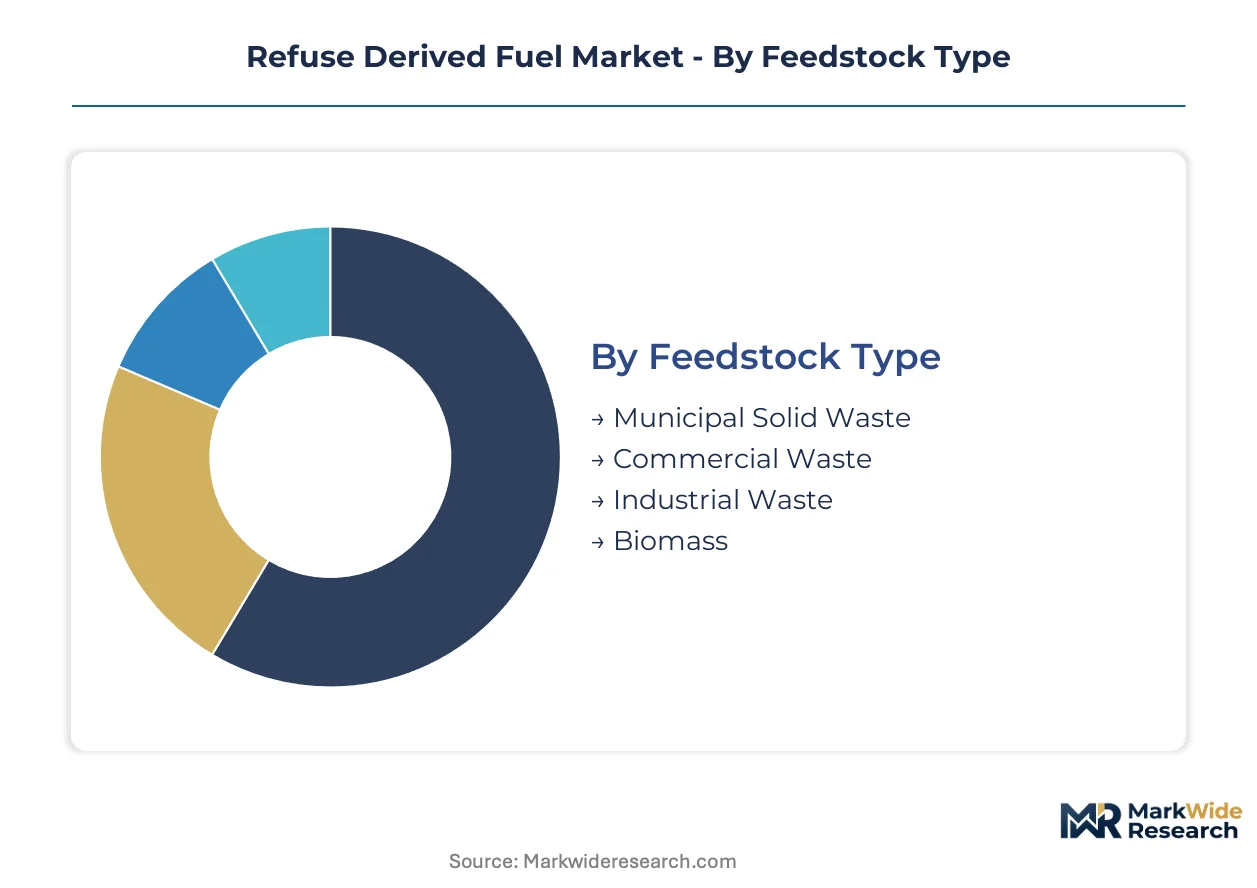
Segmentation in refuse derived fuel markets reveals how feedstock quality tiers, technology sophistication, and end-user specification requirements fragment procurement channels. Understanding these dimensions exposes where margin pools concentrate and which infrastructure investments align with regulatory trajectories.
Feedstock Type:
Cost tier differentiation across feedstock categories determines processing intensity, gate fee economics, and final fuel specification grades achievable.
- Municipal Solid Waste:Comprises household and small commercial refuse streams with variable moisture content and contaminant loads. Demand concentrates in Germany, the United Kingdom, and the Netherlands where landfill diversion mandates tighten gate fee structures and collection infrastructure maturity supports consistent volumetric throughput.
- Commercial Waste:Consists of retail, hospitality, and office-generated refuse with higher calorific density and lower seasonal variance than municipal streams. Cement manufacturers in Belgium and northern France prioritize these streams for kiln co-firing due to more predictable chlorine and alkali metal profiles that protect refractory linings.
- Industrial Waste:Manufacturing by-products and process residues with homogeneous composition and elevated energy content per unit mass.
- Biomass:Organic fractions including wood waste, agricultural residues, and sewage sludge contributing renewable carbon credentials.
Municipal Solid Waste holds installed capacity. Commercial Waste is rotating up the share rankings.
Technology:
Application maturity across thermal and biological processing routes determines capital intensity, emission control requirements, and output specification ceilings.
- Incineration:Grate-based combustion systems dominate installed European capacity, processing unsorted refuse streams at scale. Energy Generation facilities in Scandinavia and Benelux absorb the largest volumes, though air emission ceilings under the EU Industrial Emissions Directive add selective catalytic reduction capital burdens.
- Pyrolysis:Thermal decomposition in oxygen-starved environments produces syngas and char fractions with superior contaminant removal. Cement Manufacturing operations in Germany adopt pyrolysis-upgraded fuel for high substitution rates where chlorine thresholds must stay below 0.5% to prevent unplanned kiln shutdowns.
- Gasification:Partial oxidation converting solid feedstock into synthetic gas for power or chemical synthesis applications.
- Anaerobic Digestion:Biological breakdown of organic fractions producing biogas and digestate rather than solid fuel output.
Incineration holds installed capacity. Pyrolysis is climbing the fastest as specification requirements tighten.
End User:
Customer type diversity across thermal energy applications creates divergent fuel quality demands and contract duration preferences.
- Cement Manufacturing:High-temperature kiln operations requiring consistent 15-25 megajoule per kilogram calorific content and sub-0.5% chlorine limits. Demand concentrates in the United Kingdom where Lafarge and HeidelbergCement facilities are locking five-to-ten-year offtake agreements to secure supply before municipal competitors capture feedstock volumes.
- Energy Generation:Power boilers and combined heat and power plants accepting broader fuel specifications in exchange for lower delivered costs. Independent power generators in Scandinavia are bidding up spot market prices for consistent calorific volumes, compressing margin structures for long-term contract holders.
- Industrial Heating:Process heat applications in manufacturing facilities with moderate temperature requirements.
- Transportation:Emerging demand for refuse-derived synthetic fuels in heavy-duty and maritime applications.
Energy Generation holds installed capacity. Cement Manufacturing is rotating up the share rankings.
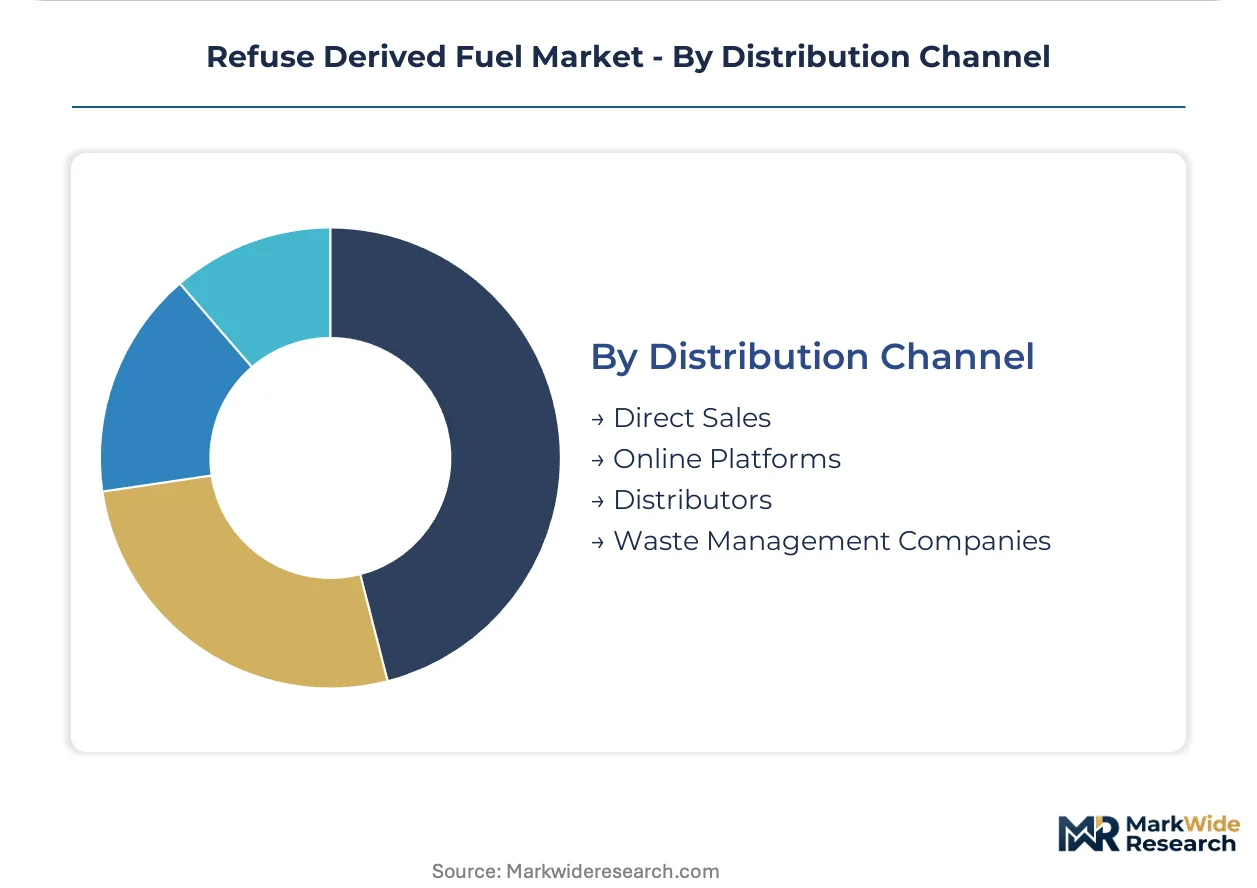
Distribution Channel:
Supply concentration patterns across procurement intermediaries determine price transparency, contract enforceability, and feedstock traceability capabilities.
- Waste Management Companies:Integrated operators controlling collection, sorting, and processing assets under unified ownership. Demand concentrates in France and Belgium where Veolia leverages captive collection networks to secure feedstock streams and bypass merchant market volatility.
- Direct Sales:Processor-to-end-user contracting eliminating intermediary margins and enabling specification customization. Cement facilities in Germany and the Netherlands favor this channel for long-term supply security as landfill tax escalation compresses disposal alternatives.
- Distributors:Merchant intermediaries aggregating volumes from multiple processors for spot market resale.
- Online Platforms:Digital marketplaces for standardized fuel grade spot trading with limited quality assurance.
Waste Management Companies hold installed capacity. Direct Sales is gaining share fastest as procurement shifts toward supply security prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Waste Framework Directive anchors regulatory pressure across Germany, where landfill diversion mandates are tightest and processing infrastructure is most mature. Cement manufacturers and power generators compete for consistent refuse derived fuel volumes as gate fee economics favor energy recovery over disposal.
Germany
Cement kiln operators in North Rhine-Westphalia and Bavaria drive specification-grade fuel demand, requiring sub-0.5% chlorine content to protect refractory linings. The Federal Immission Control Act enforces strict air emission ceilings for co-incineration facilities. Mechanical biological treatment clusters around Cologne and the Ruhr region upgrade municipal waste into export-grade fuel for domestic and cross-border supply.
United Kingdom
Landfill tax escalation has elevated refuse derived fuel to baseline fuel status for cement manufacturing. The Environment Agency permits govern stack emission limits and feedstock pre-processing requirements. Lafarge and HeidelbergCement facilities in the Midlands and Yorkshire are locking five-to-ten-year offtake agreements to secure supply before municipal competitors capture feedstock volumes.
Netherlands
High waste-to-energy infrastructure density supports consistent feedstock supply for both domestic consumption and export markets. The National Waste Management Plan implements EU landfill diversion targets through binding regional quotas. Processing plants in Rotterdam and Amsterdam harbor zones serve as consolidation hubs for specification-grade fuel shipments to German cement manufacturers.
France
Integrated waste collection networks in the Île-de-France and Hauts-de-France regions secure captive feedstock streams for major processors. REACH chemical registration requirements tighten material traceability for plastic-derived fuel fractions. Veolia leverages unified collection and treatment assets across Lille and Paris metropolitan areas to bypass merchant market volatility.
Belgium
Cement facilities in Flanders require supplier certifications that exclude specific polymer categories from municipal waste streams under the F-Gas Regulation. The Flemish Waste Agency enforces landfill diversion targets exceeding EU minimums. Processing infrastructure concentrates around Antwerp and Ghent, serving both domestic kilns and cross-border shipments to northern France.
Refuse Derived Fuel Market Competitive Environment
Integrated waste management groups and independent power specialists split the market along feedstock control and end-user access vectors. Three strategic archetypes dominate: captive collection network operators, mechanical biological treatment asset owners, and spot market merchant processors. Consolidation pressure is elevating as landfill diversion mandates compress available waste supply. Competitive moves center on long-term offtake contracting and upstream collection asset acquisition.
Among European-integrated operators, Veolia, Renewi, and Biffa exemplify divergent strategic positioning. Veolia represents the captive network archetype through unified collection and treatment ownership. Renewi anchors the mechanical biological treatment specialization with upgrading assets that expand addressable feedstock pools. Biffa occupies the merchant-processor tier, competing in spot markets while building dedicated partnerships with cement manufacturers. SUEZ Recycling and Recovery and FCC Environment sit within similar integrated configurations across overlapping geographies. Covanta and Indaver represent the power generator archetype, bidding against cement manufacturers for consistent calorific volumes. Jinjiang Environment and TPI Polene Power exemplify Asian-market positioning where waste-to-energy infrastructure is scaling rapidly.
| Leading Market Players |
|---|
| Renewi |
| FCC Environment |
| Covanta |
| Jinjiang Environment |
| Indaver |
| Veolia |
| Biffa |
| TPI Polene Power |
| SUEZ Recycling and Recovery |
| Others |
Value Chain & Pricing Dynamics
Germany's mechanical biological treatment clusters around Cologne and the Ruhr region concentrate specification-grade fuel production, anchoring margin pools with cement manufacturers in North Rhine-Westphalia and Bavaria who lock in long-term offtake agreements to bypass merchant market volatility.
Pricing Analysis
Price spreads between the United Kingdom spot market and German contract channels reflect diverging buyer structures. Pricing stratifies across premium pyrolysis-upgraded fuel, standard mechanical biological treatment output, and economy-grade incineration feedstock. Cost compression in the standard tier is intensifying because independent power generators in Scandinavia and Benelux are bidding up spot volumes. Cement manufacturers show least price sensitivity due to refractory protection requirements and supply security priorities, while district heating operators demonstrate highest sensitivity to delivered cost fluctuations.
Supply Chain Analysis
Extended payment terms from cement manufacturers to waste management companies stretch working capital requirements across the supplier base. Feedstock supply concentrates in Germany, the United Kingdom, and the Netherlands where landfill diversion mandates tighten gate fee economics. Processing infrastructure draws from municipal solid waste collection networks, commercial waste broker arrangements, and industrial residue streams. Single-source vulnerability runs through integrated collection network operators who control upstream feedstock access. Distribution runs through waste management companies holding unified collection and treatment assets, direct processor-to-end-user contracting, and spot market merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cement manufacturer consolidation around Lafarge and HeidelbergCement facilities in the United Kingdom and Germany has shifted procurement leverage toward buyers who prioritize five-to-ten-year supply security over price optimization.
For Market Incumbents: Insulate specification-grade output margins by acquiring mechanical biological treatment assets in Poland, Romania, and Bulgaria where landfill dependency rates exceed Western European benchmarks. Lock in captive collection network control before municipal competitors capture feedstock volumes. Invest in pyrolysis technology convergence to serve chlorine-sensitive cement kiln operators requiring sub-0.5% contamination thresholds. For New Entrants and Emerging Players: Establish a beachhead in Eastern European processing infrastructure where first-mover advantages persist in Poland, Romania, and Bulgaria. Target commercial waste streams in Belgium and northern France where REACH chemical registration requirements tighten material traceability and incumbent certification gaps create entry pathways. Lead with direct sales channel positioning that bypasses waste management company intermediaries and enables specification customization for cement manufacturers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mechanical biological treatment specialists holding upgrading technology and regional collection contracts. Five-to-ten year viability hinges on landfill diversion mandate enforcement trajectory and carbon border adjustment mechanism alignment. Watch EU renewable energy certificate scheme rulings on RDF qualification for green power subsidies as the inflection indicator separating premium-tier from commodity-tier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Biological Treatment Capacity Expansion | Upgrading lower-quality municipal waste expands addressable feedstock pools beyond traditional commercial sources. |
| Pyrolysis Technology Licensing | Thermal decomposition systems serve chlorine-sensitive cement kilns requiring sub-0.5% contamination thresholds. |
| Long-term Offtake Agreement | Lafarge and HeidelbergCement facilities lock five-to-ten-year contracts to secure supply before municipal competitors intervene. |
| Backward Integration into Collection Networks | Veolia leverages unified collection and treatment assets across France and Belgium to bypass merchant market volatility. |
| Carbon Border Adjustment Alignment | Early qualification for EU green certificate schemes differentiates compliant suppliers in procurement tenders. |
Study Parameters
Two parallel data streams informed the analysis: primary engagement with waste management executives, cement kiln procurement directors, mechanical biological treatment plant managers, and EU regulatory affairs specialists; and secondary validation through EPA standards documentation, EU Waste Framework Directive filings, Industrial Emissions Directive compliance records, and national waste management plan disclosures. Bottom-up triangulation across processing facility throughput estimates and top-down reconciliation against cement manufacturing fuel substitution rates anchored volume and value outputs.
Forecast inputs considered feedstock type segmentation across municipal solid waste, commercial waste, industrial waste, and biomass fractions; technology differentiation across incineration, pyrolysis, gasification, and anaerobic digestion routes; end-user concentration across cement manufacturing, energy generation, industrial heating, and transportation applications; and distribution channel structure across waste management companies, direct sales, distributors, and online platforms. CAGRs were derived from regression analysis against landfill diversion mandate enforcement timelines and gate fee escalation trajectories. EU carbon border adjustment mechanism development and renewable energy certificate scheme rulings were modeled as scenario-dependent demand shifters.
Stress conditions across chlorine contamination threshold enforcement, feedstock competition intensity from independent power generators, and pyrolysis technology cost curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and infrastructure investment pacing. Macroeconomic contraction, landfill diversion mandate delay, or breakthrough alternative fuel technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Compressed Natural Gas Market
Fuels
Electric Fuel Heater Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
LPG Gas Cylinder Market
Fuels
LNG Fueling Station Market
Fuels
Gas Hydrates Market
Fuels
China Coal Market
Fuels
India Coal Market
Fuels
North America LNG Bunkering Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Global Charcoal Market