
 Green Hydrogen Market | 2026-2036
Green Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Green Hydrogen Market Analysis
Aftermarket service revenue for electrolyzer stacks is fragmenting across third-party maintenance networks and original equipment service contracts. Siemens Energy anchors its position through captive servicing of its proton exchange membrane installations across Northern Europe. Nel ASA competes by extending its refurbishment capabilities to non-proprietary alkaline systems, broadening addressable unit volume.
Green hydrogen denotes hydrogen gas produced via water electrolysis powered by renewable electricity, yielding purity levels exceeding 99.9 percent with oxygen as the sole byproduct; the process typically operates at pressures between 30 and 80 bar for direct industrial feedstock integration. Electrolysis dominates installed production capacity while photoelectrochemical pathways attract R&D capital for their theoretical efficiency advantages. Ammonia production applications command the largest current offtake volumes, though fuel cell deployments in heavy transport represent the fastest-expanding demand segment.
The EU Green Deal and F-Gas Regulation shape equipment standards and cross-border pipeline certification requirements across European jurisdictions, while METI in Japan coordinates national hydrogen supply chain roadmaps through subsidized demonstration projects. The US IRA production tax credits alter project finance structures for electrolyzer developers targeting export markets. Stakeholders must track how divergent certification schemes for carbon intensity thresholds affect interregional trade flows and equipment sourcing decisions.
Market Dynamics
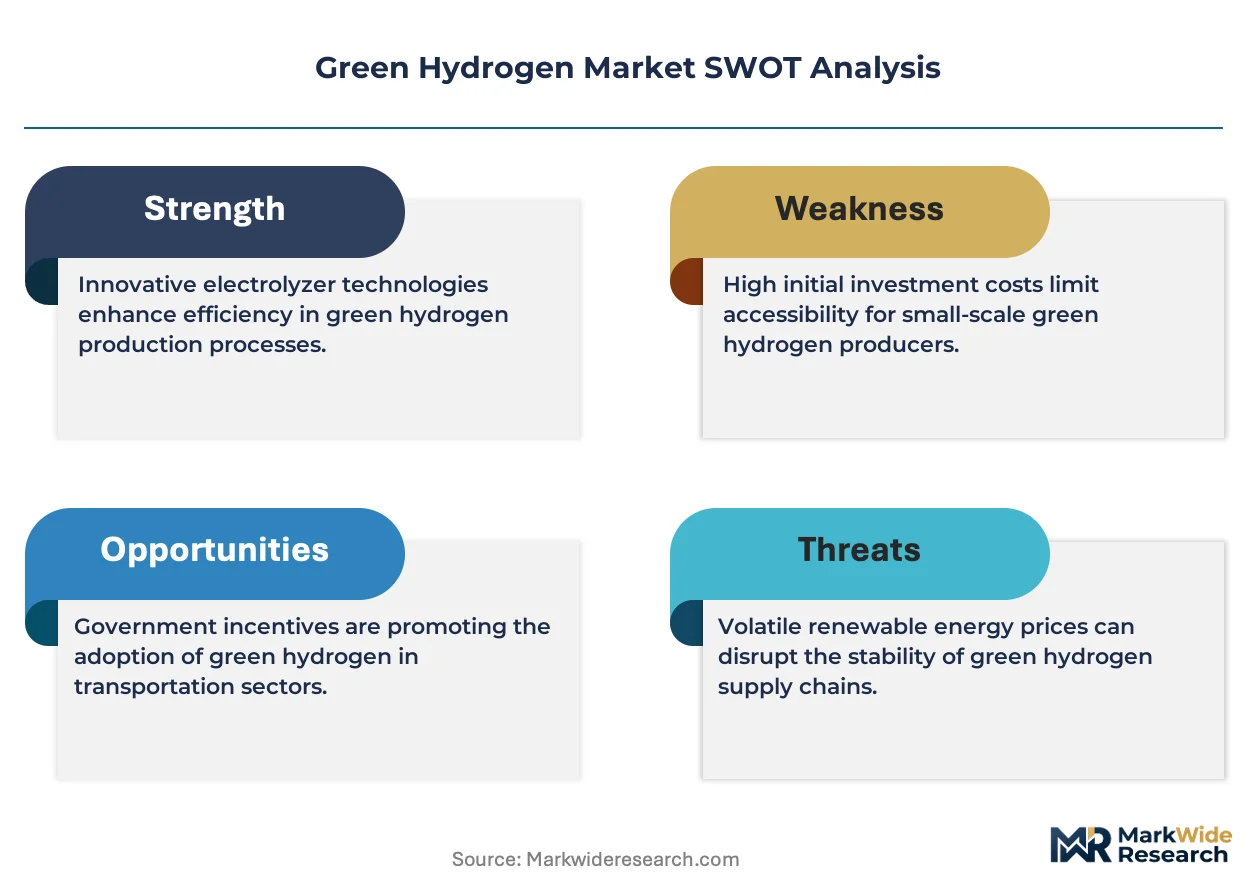
Electrolyzer stack supply chains are consolidating around captive manufacturing in Germany and Japan, compressing lead times for industrial-scale installations while locking in long-term service dependencies for steel and ammonia producers.
Growth Catalysts
- EU Green Deal carbon border adjustments:German steelmakers accelerate electrolyzer procurement to avoid carbon tariffs on exported finished goods.
- Alkaline electrolysis cost curves:Stack manufacturing scale-up in China reduces unit capex for utility-scale hydrogen production facilities.
- Offshore wind corridor clustering:North Sea installations co-locate electrolyzers with generation assets, eliminating transmission losses and hydrogen transport costs.
Market Restraints
- Platinum group metal supply concentration:Proton exchange membrane stacks depend on South African and Russian palladium, creating input cost volatility and sanctions exposure.
- Grid interconnection queues:Renewable project approval delays in the US and Germany postpone electrolyzer offtake contracts.
- Natural gas price arbitrage:Gray hydrogen from steam methane reforming undercuts green hydrogen pricing in markets without carbon pricing mechanisms.
Strategic Opportunities
- Middle East solar-hydrogen export hubs:Saudi Arabia and UAE leverage low-cost photovoltaic generation to supply European and Asian offtakers.
- Heavy transport fuel cell retrofit:Long-haul trucking and maritime shipping create demand for high-pressure hydrogen dispensing infrastructure.
- Power-to-liquid aviation fuels:Synthetic kerosene from green hydrogen and captured carbon secures offtake from airlines facing EU ReFuelEU mandates.
Industry Challenges
- Electrolyzer stack refurbishment technician shortages:Specialized welding and membrane replacement skills outpace vocational training program output in Northern Europe.
- Cross-border hydrogen pipeline certification timelines:Divergent national safety standards between Germany, Netherlands, and Belgium delay corridor completion.
- Legacy industrial burner retrofit complexity:Steel and cement facilities face extended downtime integrating hydrogen-ready equipment with existing furnaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Hydrogen Market |
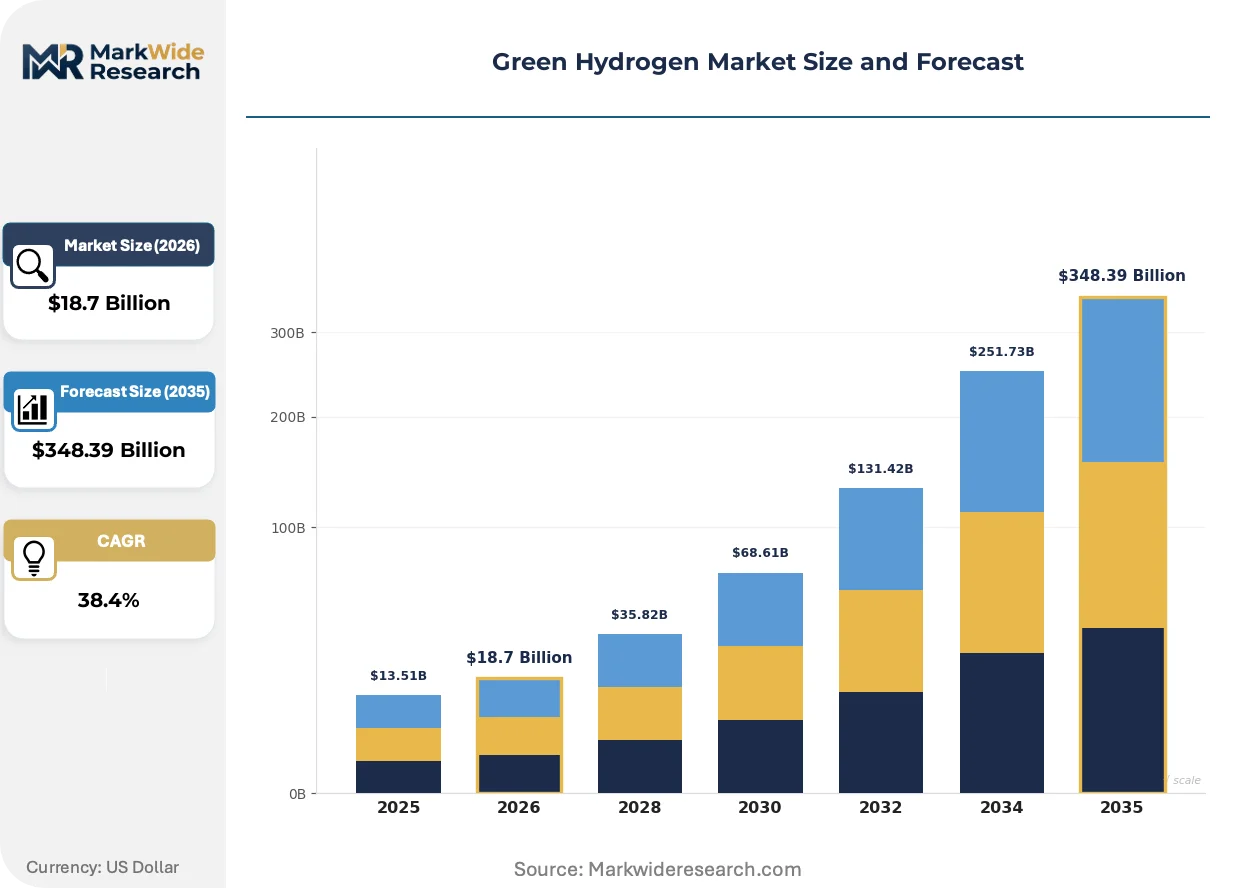
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $348.39 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Electrolysis, Steam Methane Reforming, Biomass Gasification, Photoelectrochemical Application: Fuel Cells, Ammonia Production, Power Generation, Refining End User: Transportation, Industrial, Power Sector, Agriculture Distribution Channel: Pipeline, Truck, Rail, Shipping |
| Companies Covered | Siemens Energy, Air Liquide, Linde, Plug Power, Air Products and Chemicals, Nel ASA, ITM Power, ENGIE, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Hydrogen Market Emerging Trajectories
Technology convergence between electrolyzer manufacturing and renewable project development is collapsing traditional equipment procurement cycles, compressing the path from financing to hydrogen offtake.
Solid oxide electrolysis is collapsing the efficiency gap between high-temperature industrial heat integration and ambient-pressure hydrogen production. Chemical producers in the Netherlands and Germany pilot these systems adjacent to ammonia and methanol synthesis loops. The technology compresses electrical input requirements by 15-20 percent versus alkaline alternatives when waste heat is available.
The US IRA production tax credit structure is reshaping project finance for electrolyzer developers targeting export markets. Developers now structure ownership vehicles to capture credits while selling hydrogen to European buyers under certification schemes. This regulatory arbitrage concentrates development activity in Texas and Louisiana port corridors with existing ammonia terminal infrastructure.
Steel mill procurement teams now require electrolyzer suppliers to bundle 15-year service contracts with initial equipment sales, displacing spot maintenance markets. ThyssenKrupp and Nippon Steel mandate this structure for new installations. The shift locks in aftermarket revenue for OEMs while raising barriers for third-party service entrants in the Ruhr and Chiba industrial clusters.
Green Hydrogen Market Segmentation
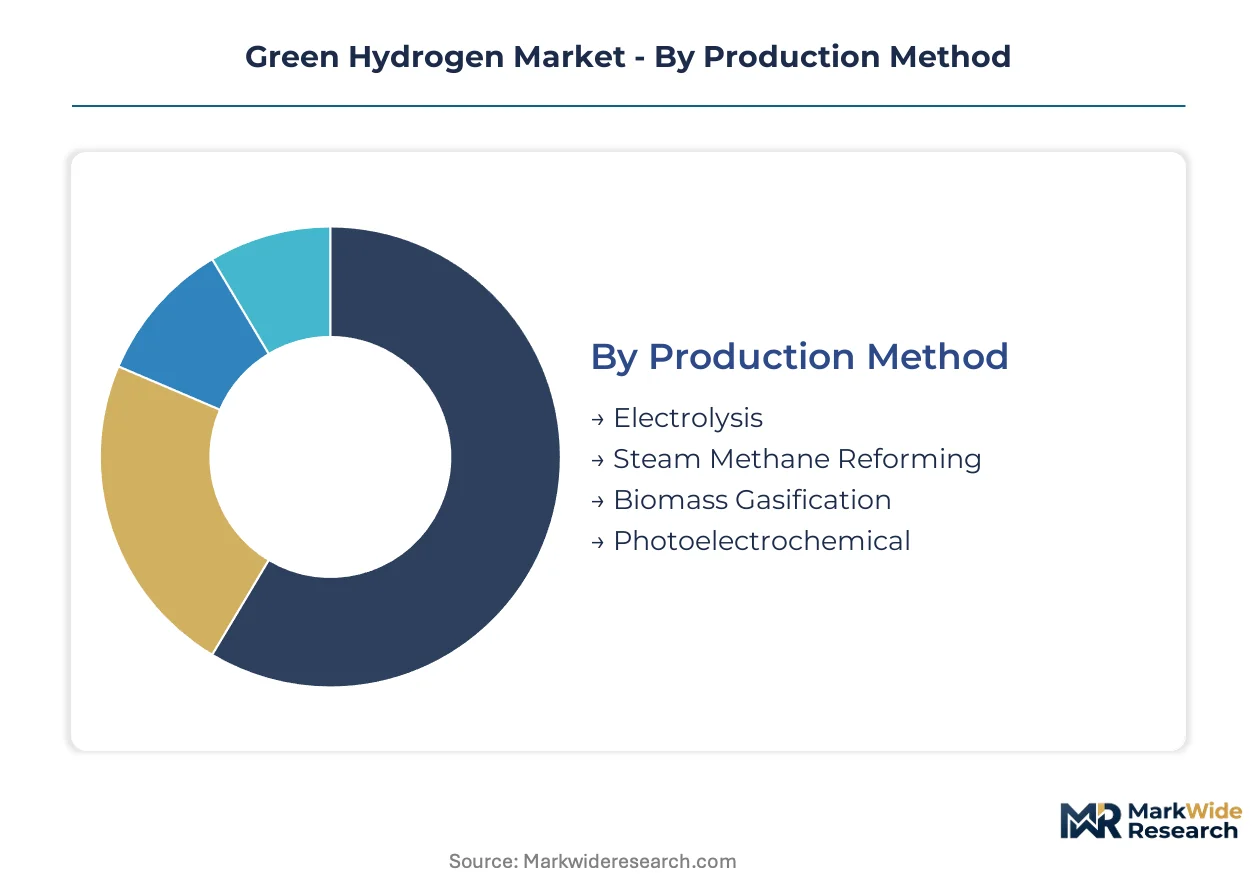
Segmentation reveals how production methods, transport modes, and end-use applications create distinct commercial ecosystems with divergent margin profiles and regulatory exposure. Each dimension carries unique capex intensity, certification requirements, and offtake contract structures that shape supplier positioning.
Production Method:
The use-case spectrum spans from grid-connected industrial electrolysis to distributed biomass conversion, with each pathway commanding different carbon intensity certifications and equipment depreciation schedules.
- Electrolysis:Water splitting via proton exchange membrane or alkaline stacks powered by renewable electricity yields 99.9 percent purity hydrogen. German steelmakers and Dutch ammonia producers anchor demand through EU Green Deal-linked procurement contracts requiring sub-2 kg CO2e per kg H2 certification.
- Steam Methane Reforming:Natural gas reforming with carbon capture retrofits dominates existing hydrogen supply to refineries and chemical plants. Gulf Coast facilities in Texas and Louisiana leverage IRA production tax credits to offset carbon capture equipment costs while serving export markets.
- Biomass Gasification:Agricultural residue conversion produces hydrogen with negative carbon intensity scores under certain lifecycle accounting frameworks.
- Photoelectrochemical:Direct solar-to-hydrogen conversion remains pre-commercial, attracting R&D capital from Japanese and Australian national laboratories.
The dominant share belongs to Electrolysis, while Photoelectrochemical is closing the gap fastest on patent filing velocity.
Application:
Cost tier differentiation separates commodity chemical feedstock from premium mobility fuel, with certification premiums widening spreads between adjacent segments.
- Ammonia Production:Haber-Bosch synthesis loops consume hydrogen at massive scale for fertilizer and maritime fuel applications. Rotterdam and Hamburg terminals cluster electrolyzer capacity adjacent to ammonia export infrastructure, with EU F-Gas Regulation dictating equipment leak-rate standards.
- Fuel Cells:Proton exchange membrane and solid oxide systems convert hydrogen to electricity for heavy transport and backup power. California and South Korea mandate fuel cell truck deployment through fleet purchase incentives and zero-emission vehicle credits.
- Power Generation:Gas turbine blending and dedicated hydrogen turbines serve grid balancing and industrial heat applications.
- Refining:Hydrocracker and desulfurization units consume hydrogen for transportation fuel upgrading.
Ammonia Production commands the largest current offtake volumes, though Fuel Cells is expanding most quickly on transport sector mandates.
End User:
Customer type determines contract duration, with industrial offtakers preferring 15-year supply agreements versus transport sector spot purchasing.
- Industrial:Steel, cement, and chemical facilities integrate hydrogen for process heat and feedstock substitution. ThyssenKrupp and Nippon Steel mandate bundled service contracts from electrolyzer suppliers, locking in aftermarket revenue streams across Ruhr and Chiba clusters.
- Transportation:Long-haul trucking, maritime shipping, and aviation create demand for high-pressure or liquid hydrogen logistics. Port authorities in Rotterdam, Singapore, and Los Angeles coordinate bunkering infrastructure buildout.
- Power Sector:Grid operators procure hydrogen for seasonal storage and peaking generation capacity.
- Agriculture:Fertilizer producers and farm cooperatives consume hydrogen-derived ammonia for crop nutrition.
Industrial offtakers anchor current demand, while Transportation is gaining share fastest on regulatory deadlines for fleet decarbonization.
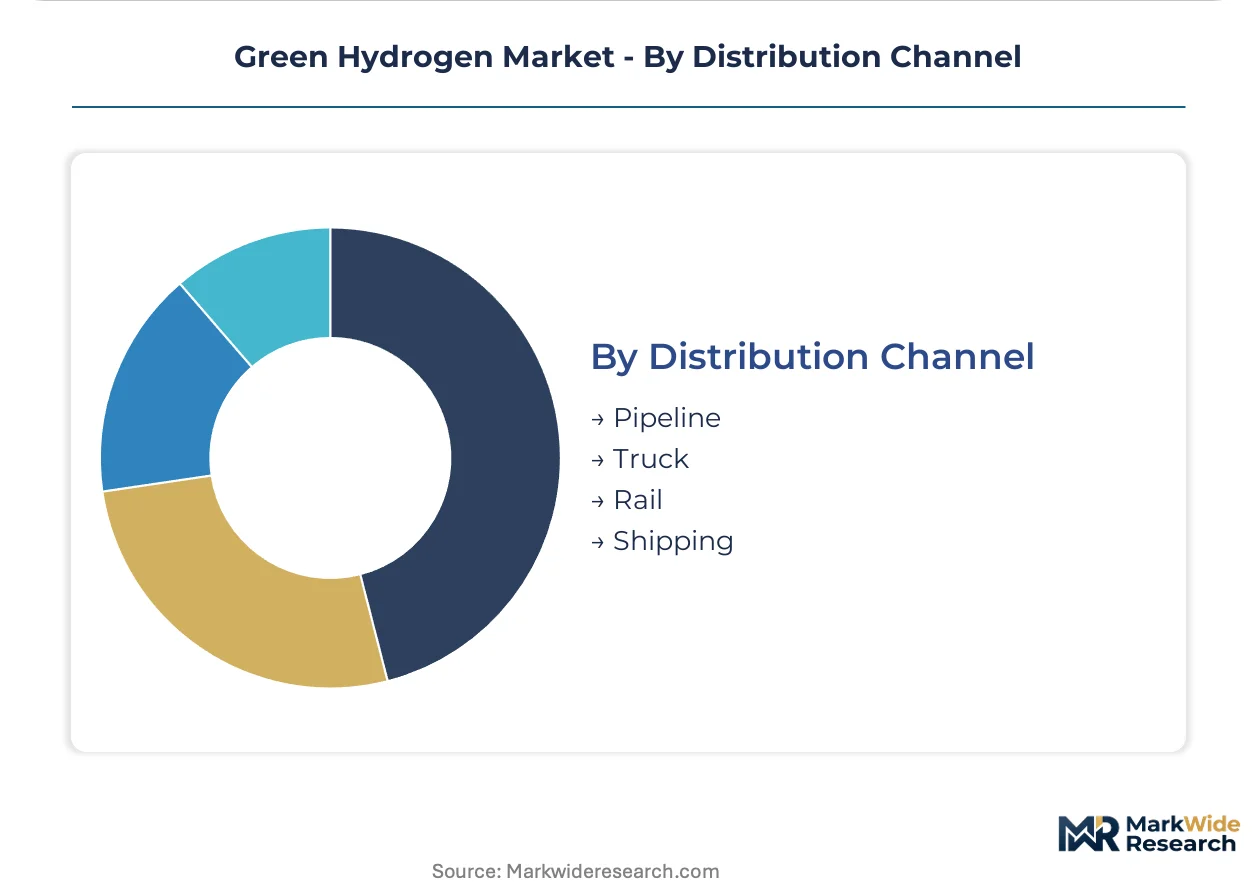
Distribution Channel:
Volume and geography dictate transport mode selection, with pipeline economics favoring continuous large-scale flow versus batch shipment for distributed demand.
- Pipeline:Dedicated hydrogen and repurposed natural gas pipelines serve industrial corridors with continuous demand. Cross-border certification delays between Germany, Netherlands, and Belgium postpone North Sea hydrogen backbone completion.
- Shipping:Liquid hydrogen and ammonia carriers enable intercontinental trade from Middle East production hubs to European and Asian offtakers. Saudi Arabia and UAE leverage low-cost solar generation to supply Rotterdam and Tokyo terminals.
- Truck:Tube trailers and liquid tankers serve dispersed industrial and transport refueling demand.
- Rail:Specialized tank cars move hydrogen to inland industrial zones lacking pipeline connectivity.
Pipeline infrastructure holds the dominant position for corridor-scale supply, while Shipping is climbing the fastest on export hub development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes green hydrogen primarily for steel decarbonization under carbon border pressure, while Japan prioritizes ammonia synthesis for power generation and maritime fuel, and Saudi Arabia targets export-oriented production leveraging solar cost advantages.
Germany
ThyssenKrupp and Salzgitter AG anchor electrolyzer procurement for blast furnace hydrogen injection under the EU Green Deal carbon border adjustment mechanism. The national hydrogen strategy mandates 10 GW domestic electrolyzer capacity by 2030. The Ruhr industrial cluster concentrates stack installation and captive maintenance contracting.
Japan
Nippon Steel and JFE Holdings scale hydrogen direct reduction pilot plants for feedstock substitution in integrated mills. METI coordinates demonstration project subsidies through the Green Innovation Fund. The Chiba-Kashima coastal corridor clusters ammonia synthesis capacity adjacent to LNG import terminals.
United States
Texas and Louisiana port developers structure electrolyzer projects to capture IRA production tax credits while supplying ammonia export markets. FERC interconnection queues delay renewable power delivery to Gulf Coast hydrogen hubs. The Houston Ship Channel anchors power-to-liquid aviation fuel pilot plants serving EU ReFuelEU offtake mandates.
Saudi Arabia
NEOM and Red Sea coastal developers leverage sub-$0.02/kWh photovoltaic generation for export-oriented hydrogen and ammonia production. The national regulator coordinates certification alignment with EU carbon intensity thresholds. Jubail Industrial City hosts electrolyzer manufacturing joint ventures with European stack suppliers.
Netherlands
Port of Rotterdam authorities coordinate hydrogen import terminal buildout for German industrial offtake. The EU F-Gas Regulation dictates equipment leak-rate standards for ammonia synthesis loop integration. The North Sea hydrogen backbone pipeline project links Dutch electrolyzer capacity to Belgian and German demand centers.
Green Hydrogen Market Vendor Landscape
Capability concentration sits with European stack specialists; scale advantage sits with diversified industrial gas incumbents. Siemens Energy and Nel ASA anchor the specialist tier through proprietary membrane and alkaline system architectures. Consolidation pressure is compressing the vendor base around three strategic archetypes: captive renewable developers with integrated electrolyzer manufacturing, industrial gas majors with existing hydrogen logistics networks, and pure-play stack suppliers with aftermarket service lock-in. Competitive moves center on 15-year bundled service contracting and co-location partnerships with offshore wind developers.
Among European specialists, Siemens Energy represents the integrated engineering-to-service archetype, while Nel ASA exemplifies the refurbishment-focused challenger model targeting non-proprietary system aftermarket capture. Air Liquide and Linde occupy positions bridging industrial gas logistics with electrolyzer project development. ITM Power anchors the PEM-specialist tier through UK-based manufacturing scale-up. These four entities illustrate how geographic proximity to North Sea wind corridors and Gulf Coast export infrastructure is reshaping competitive positioning.
| Leading Market Players |
|---|
| Siemens Energy |
| Air Liquide |
| Linde |
| Plug Power |
| Air Products and Chemicals |
| Nel ASA |
| ITM Power |
| ENGIE |
| Cummins |
| Others |
Supply Flow & Price Mechanics
Platinum group metal supply concentration from South African and Russian sources determines both pricing tier spreads and supply chain shape in electrolyzer manufacturing. Input cost volatility from sanctions exposure and mining output disruptions compress margins for proton exchange membrane stack producers while amplifying price premiums for certified low-carbon intensity hydrogen.
Pricing Analysis
Long-term offtake contracts dominate industrial procurement, with ThyssenKrupp and Nippon Steel mandating 15-year bundled service agreements that lock in aftermarket revenue. Price differentiation rests on carbon intensity certification tiers and electrolyzer technology type, with solid oxide systems commanding premiums for high-temperature heat integration. Cost compression in alkaline systems intensifies because Chinese manufacturing scale-up floods utility-scale segments. Ammonia producers exhibit highest price sensitivity due to commodity margin structures, while aviation fuel offtakers under EU ReFuelEU mandates show lowest sensitivity.
Supply Chain Analysis
Export control regimes on electrolyzer stack manufacturing equipment limit technology transfer from Germany and Japan to emerging production hubs. Geographic supply concentration centers on German engineering specialists, Japanese precision component fabricators, and Chinese alkaline system assemblers. Raw material dependencies include iridium catalyst coatings, titanium bipolar plates, and specialized polymer membranes. Single-source vulnerability from South African palladium concentration threatens input security. Distribution runs through captive OEM service networks and third-party maintenance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification schemes and service contracting models creates entry niches for specialists. Divergent carbon intensity thresholds between EU, Japanese, and emerging Middle East frameworks multiply addressable market segments.
For Market Incumbents: Harden aftermarket lock-in by extending bundled service contracts to non-proprietary alkaline installations, displacing third-party refurbishment networks. Accelerate captive manufacturing in Saudi Arabia and UAE to preempt tariff exposure on European-sourced stacks. Secure iridium and palladium offtake agreements with South African mining consortia before resource nationalism tightens export quotas. For New Entrants and Emerging Players: Solid oxide electrolysis pilot installations adjacent to Dutch and German chemical synthesis loops represent the most penetrable entry point for technology differentiation. Third-party stack refurbishment technician training programs in Northern Europe address acute skill shortages while building service revenue foundations. Partner with port authorities in Rotterdam, Singapore, and Los Angeles on hydrogen bunkering infrastructure to capture transport sector demand. For Investors and Strategic Acquirers: The market sits at a manufacturing scale-up phase that favors pure-play stack suppliers with proprietary membrane architectures and established service networks. Five-to-ten year viability hinges on electrolyzer cost curves achieving parity with gray hydrogen in carbon-priced jurisdictions. Watch for FERC interconnection queue resolution in Texas and Louisiana as inflection indicator for IRA credit capture project finance.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Bundling | ThyssenKrupp and Nippon Steel mandates lock in 15-year aftermarket revenue streams. |
| Backward Integration into Catalyst Supply | Iridium and palladium offtake agreements reduce South African supply concentration risk. |
| Co-location with Offshore Wind Assets | North Sea electrolyzer clustering eliminates transmission losses and transport costs. |
| Cross-border Pipeline Certification Alignment | Germany-Netherlands-Belgium standard convergence accelerates hydrogen backbone completion. |
| Solid Oxide Technology Licensing | Dutch and German chemical producers pilot 15-20% efficiency gains from waste heat integration. |
Methodological Framework
Operator-level perspectives from electrolyzer procurement managers at steel and ammonia producers, aftermarket service technicians, and renewable project developers anchored the qualitative base. Primary interviews combined with secondary validation from EU Green Deal implementation reports, METI demonstration project disclosures, FERC interconnection databases, and IEA hydrogen supply chain tracking. Bottom-up electrolyzer installation counts and top-down energy transition investment flows were triangulated for market sizing.
Scenario-bracketing around carbon price trajectories, renewable power cost curves, and electrolyzer manufacturing scale-up rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled include production method, end-use application, and regional regulatory framework. CAGRs were derived from capacity buildout pipelines and offtake contract volumes. Forecast inputs incorporated IRA production tax credit capture rates and EU carbon border adjustment implementation timing.
Stress conditions across palladium supply disruptions, FERC queue resolution delays, and EU-Japan certification divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on electrolyzer cost reduction trajectories and renewable power purchase agreement pricing. Material shifts in EU Green Deal carbon intensity thresholds or METI subsidy program restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Clean Hydrogen Market