
 Aviation Alternative Fuel Market | 2026-2036
Aviation Alternative Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Alternative Fuel Market Analysis
Conventional jet kerosene is hardening as the cost baseline against which sustainable aviation fuel economics must compete. Neste leverages its Rotterdam refinery capacity to anchor European supply security for hydroprocessed renewable jet fuel. Gevo specializes in alcohol-to-jet pathways using isobutanol fermentation, while World Energy sustains North American production scale through its Paramount facility conversion.
Aviation alternative fuel comprises drop-in hydrocarbons certified under ASTM D7566 that substitute for conventional Jet A or Jet A-1 without airframe modification, produced via Fischer-Tropsch synthesis, hydroprocessed esters and fatty acids, or alcohol-to-jet conversion of biomass, waste lipids, or synthetic gas streams. Sustainable aviation fuel leads current production volumes due to established certification pathways and airline offtake commitments, while synthetic fuels represent the emerging margin pool as power-to-liquid technologies mature. Commercial aviation dominates application demand through international carrier decarbonization targets, whereas cargo transport segments differentiate through dedicated freighter operator sustainability pledges.
The US EPA renewable fuel standard and California Low Carbon Fuel Standard shape domestic blending economics, while the EU ReFuelEU Aviation mandate establishes binding sustainable aviation fuel percentages at EU airports. ICAO CORSIA compliance requirements drive demand quantification and certification infrastructure investment across participating states. Stakeholders must monitor feedstock availability constraints and policy durability as production capacity scales toward airline net-zero commitments.
Market Dynamics
The aviation alternative fuel market is being restructured by the collision between ICAO CORSIA compliance deadlines and the physical constraints of HEFA feedstock availability, forcing carriers to secure offtake years ahead of production ramp.
Growth Catalysts
- EU ReFuelEU Aviation mandate:Binding SAF blending percentages at EU airports create guaranteed demand floors that de-risk refinery investment decisions.
- Power-to-liquid maturation:Electrofuel pathways using renewable hydrogen and captured CO2 are attracting capital as Fischer-Tropsch catalyst efficiency improves.
- US DOE loan guarantees:Biorefinery scale-up financing through federal backing accelerates domestic production capacity deployment.
Market Restraints
- Feedstock cost volatility:Waste lipid and biomass oil prices track agricultural commodity swings, compressing HEFA pathway margins unpredictably.
- Refinery concentration:European SAF supply security depends heavily on Rotterdam corridor capacity, creating single-point vulnerability.
- ASTM D7566 certification bottlenecks:Novel alcohol-to-jet pathways face extended approval timelines that delay commercial deployment.
Strategic Opportunities
- California LCFS credit stacking:SAF producers can layer federal and state incentives to improve project returns beyond base economics.
- Cargo operator premium segments:Dedicated freighter fleets at integrators like FedEx and DHL offer concentrated demand for certified sustainable fuel.
- Power-to-liquid geographic arbitrage:Regions with stranded renewable electricity and CO2 point sources can anchor electrofuel production at cost parity.
Industry Challenges
- Biorefinery engineering talent scarcity:Specialized process design expertise for hydroprocessing and gasification units remains concentrated at incumbent oil majors.
- Book-and-claim accounting complexity:Mass-balance certification systems require traceability infrastructure that smaller carriers struggle to implement.
- Airport fuel system integration:Co-mingling SAF with conventional jet kerosene demands hydrant testing and compatibility verification at each hub.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Alternative Fuel Market |
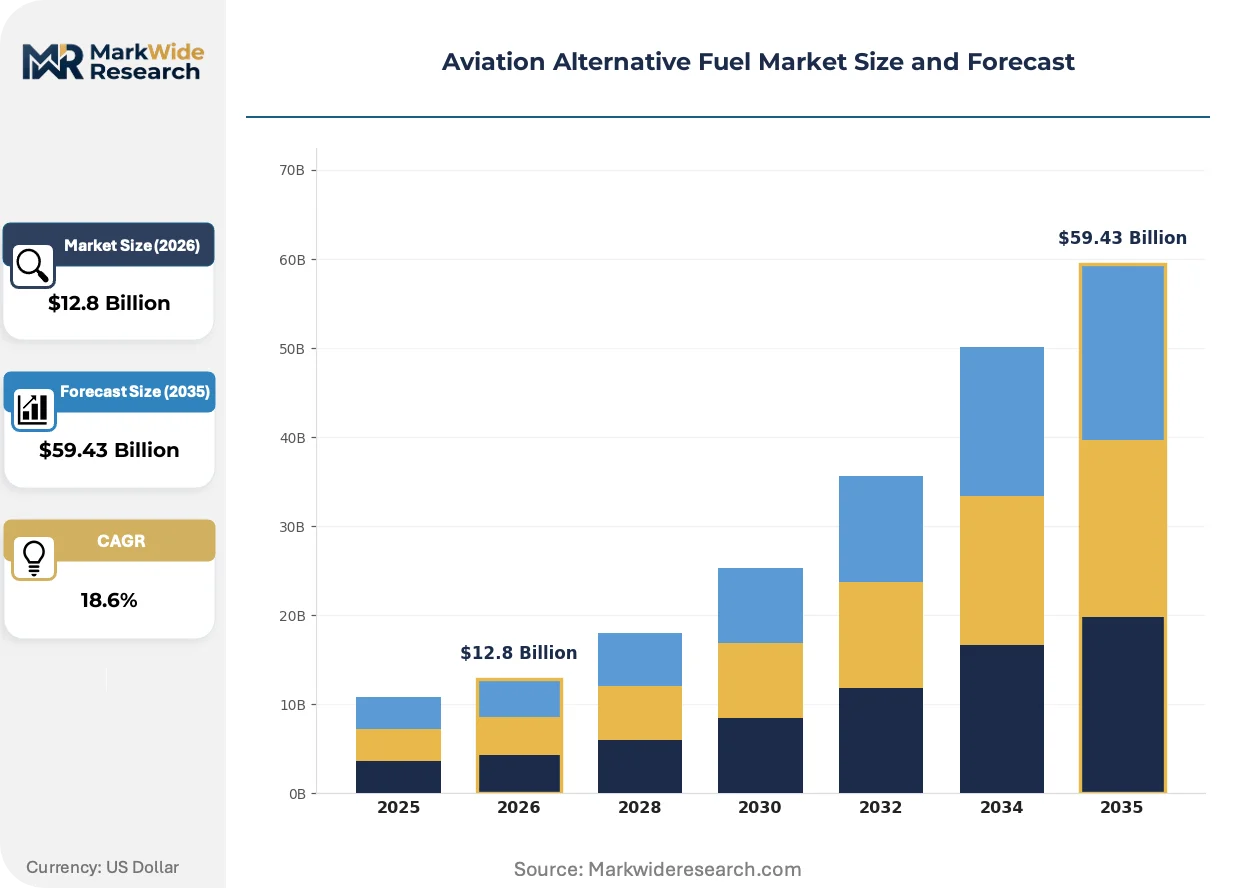
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.43 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Sustainable Aviation Fuel, Biofuels, Synthetic Fuels, Hydrogen Application: Commercial Aviation, Military Aviation, Cargo Transport, General Aviation Distribution Channel: Direct Supply, Retail Outlets, Partnerships, Airport Fueling Services End User: Airlines, Government Bodies, Charter Services, Freight Companies |
| Companies Covered | SkyNRG, Fulcrum Bioenergy, Neste, Aemetis, Velocys, World Energy, Eni, Alder Fuels, Gevo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Alternative Fuel Market Emerging Trajectories
Technology convergence and regulatory precision are compressing the timeline between pilot-scale demonstration and commercial offtake, while procurement models evolve to share risk across the value chain.
Alcohol-to-jet conversion is automating the transition from fermentation-derived isobutanol to synthetic paraffinic kerosene through continuous catalytic upgrading. Regional carriers and corporate aviation fleets are adopting this pathway ahead of major international airlines. The technology is automating quality control steps that previously required batch testing, reducing certification overhead for smaller producers.
The EU F-Gas Regulation and complementary ETS aviation inclusion are tightening emissions accounting requirements for intra-European flights. Industrial consequence includes mandatory SAF percentage ramps at EU airports starting 2025. Short-haul carriers operating high-frequency routes are responding by locking in decade-long supply contracts to hedge price exposure.
Corporate travel procurement departments are embedding carbon intensity clauses into airline contract renewals, forcing network carriers to disclose SAF blend percentages by route. This behavior is displacing traditional price-per-seat-mile negotiations in premium cabin segments. The shift is most visible in transatlantic business travel corridors where Fortune 500 sustainability targets dictate vendor selection.
Aviation Alternative Fuel Market Segmentation
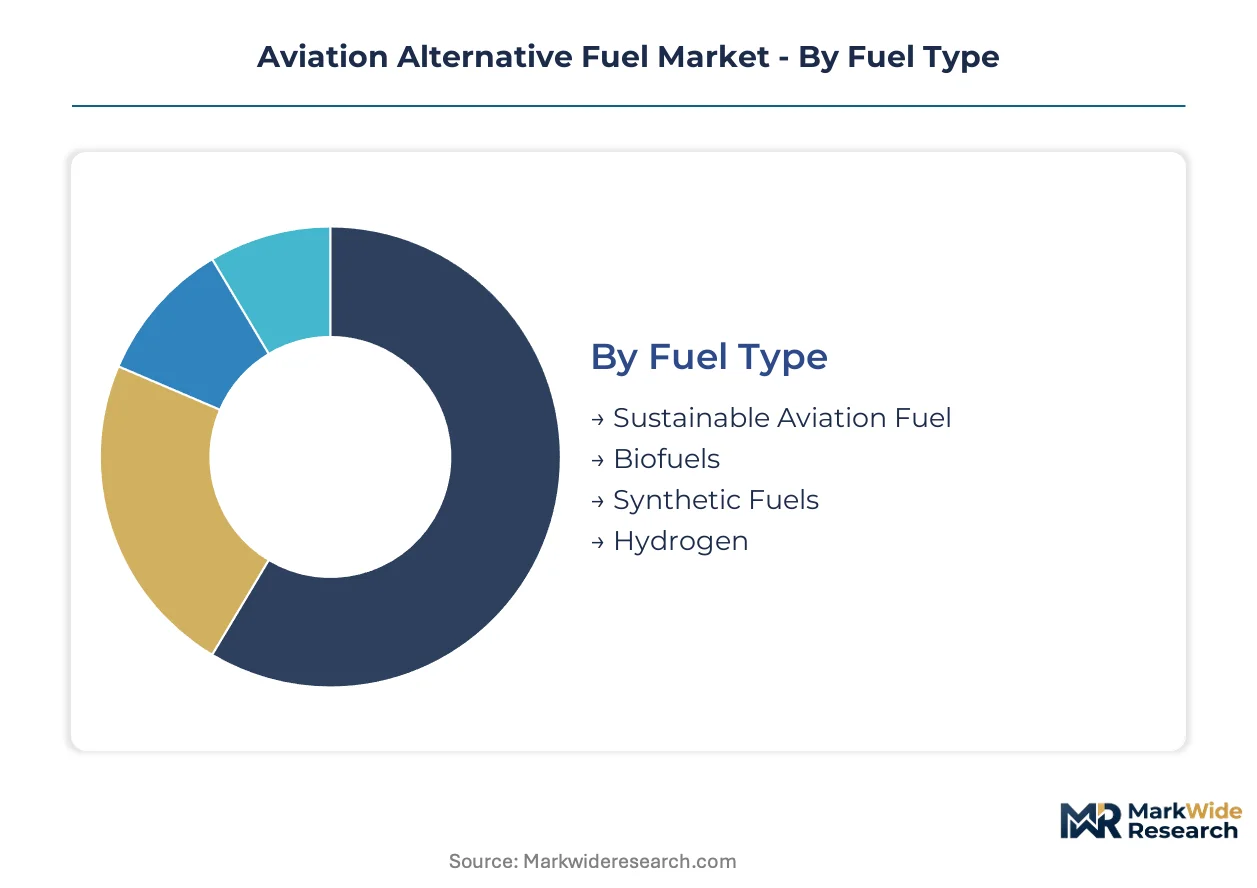
Segmentation in aviation alternative fuels reveals how certification pathways, infrastructure requirements, and procurement authority distribute across fuel chemistries and operational contexts. Understanding these divisions exposes where capital deployment faces friction versus where policy guarantees demand.
Fuel Type:
Integration depth varies sharply: drop-in certified fuels substitute directly into existing aircraft and fuel systems, while hydrogen demands airframe redesign and ground infrastructure overhaul.
- Sustainable Aviation Fuel:Hydroprocessed esters and fatty acids plus alcohol-to-jet pathways produce ASTM D7566-certified synthetic paraffinic kerosene that blends seamlessly with conventional Jet A. Commercial carriers at Amsterdam Schiphol and Los Angeles International now contract for dedicated SAF volumes under EU ReFuelEU and California LCFS frameworks. Certification maturity and airline offtake commitments anchor current production scale.
- Synthetic Fuels:Fischer-Tropsch synthesis and power-to-liquid electrofuels using renewable hydrogen with captured CO2 yield fully synthetic drop-in replacements. Projects in Norway and Chile leverage stranded wind resources and industrial CO2 point sources to target cost parity. Technology maturation and catalyst efficiency gains are compressing demonstration-to-commercial timelines.
- Biofuels:Unprocessed or partially upgraded lipid and cellulosic feedstocks lacking full aviation certification serve research and blending applications.
- Hydrogen:Cryogenic liquid and compressed gaseous forms require turbofan redesign and airport liquefaction infrastructure not yet deployed at scale.
Sustainable aviation fuel leads volumes today; synthetic fuels are gaining share fastest.
Application:
Operational intensity and route predictability determine which segments absorb premium fuel costs first.
- Commercial Aviation:Scheduled passenger carriers with fixed hub operations and corporate travel procurement pressure drive certified SAF demand. Network carriers at Frankfurt and Singapore Changi anchor initial offtake volumes through decade-long supply agreements.
- Cargo Transport:Integrated express operators with concentrated freighter fleets and sustainability pledges from e-commerce shippers create dedicated demand pools. FedEx and DHL commitments at Memphis and Leipzig hubs demonstrate concentrated procurement authority.
- Military Aviation:Defense procurement specifications and energy security mandates in the United States and United Kingdom support alternative fuel testing at scale.
- General Aviation:Corporate and private operators with flexible scheduling and sustainability branding needs adopt alcohol-to-jet pathways ahead of certification standardization.
Commercial aviation commands procurement scale; cargo transport climbs fastest on concentrated fleet conversion.
Distribution Channel:
Physical fuel system integration constraints favor channels with existing hydrant infrastructure and mass-balance certification capability.
- Airport Fueling Services:Into-plane operators with existing Jet A hydrant systems and SAF co-mingling protocols dominate certified fuel delivery. Amsterdam, Los Angeles, and Singapore terminals now offer routine SAF loading through established infrastructure.
- Direct Supply:Long-term offtake contracts between producers and individual carriers bypass intermediaries for price certainty and supply security. Neste's airline partnerships exemplify this channel's growth.
- Partnerships:Joint ventures between oil majors, technology developers, and carriers share construction risk for new biorefinery capacity.
- Retail Outlets:Limited to general aviation fixed-base operators with tankage for small-volume certified fuel sales.
Airport fueling services handle present throughput; direct supply contracts expand most quickly as carriers seek price hedges.
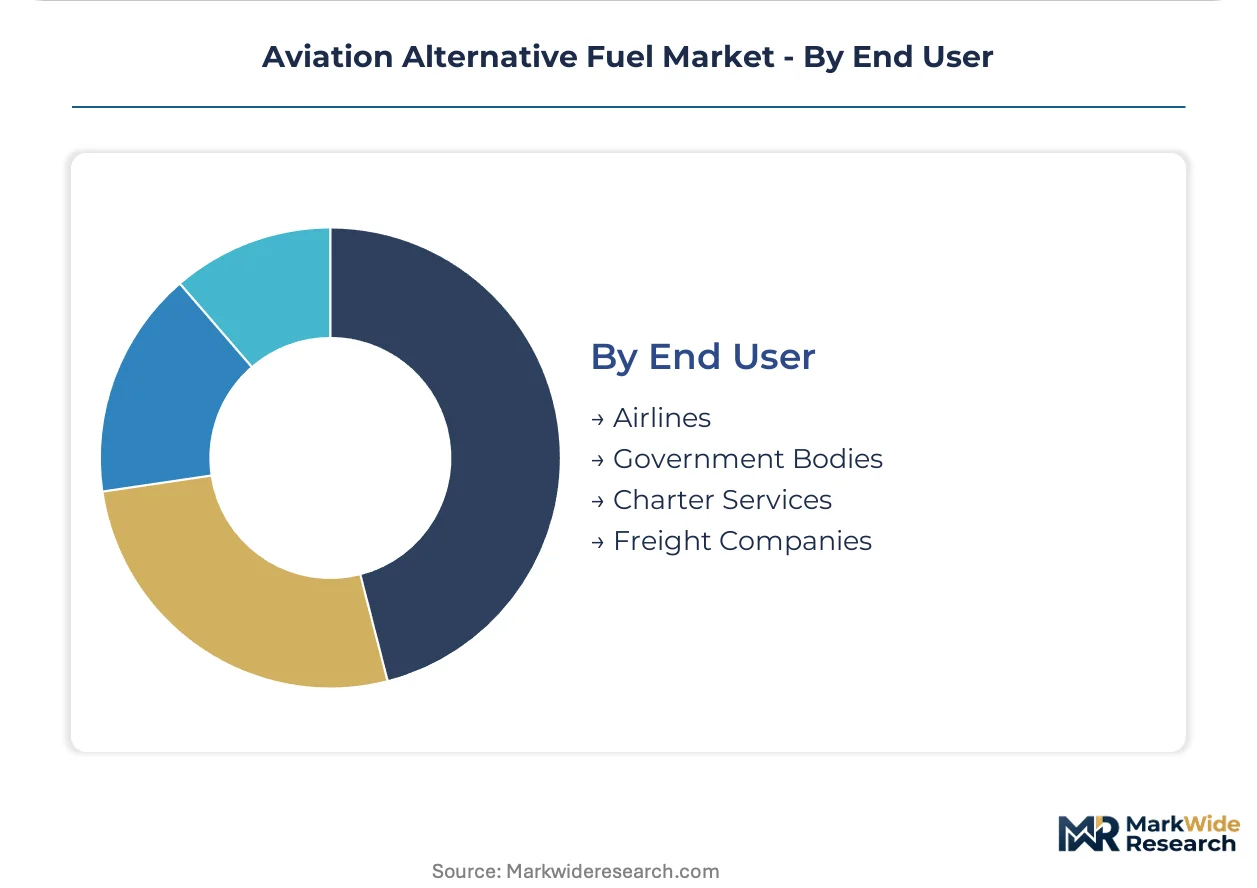
End User:
Procurement authority and sustainability target stringency segment demand across organizational types with diverging risk tolerances.
- Airlines:Network and low-cost carriers with ICAO CORSIA compliance obligations and corporate travel contract requirements drive certified SAF procurement. IAG and Lufthansa Group commitments illustrate airline-led demand formation.
- Freight Companies:Express integrators and dedicated cargo operators with concentrated hub operations and shipper sustainability mandates purchase at volume. Amazon and Shopify shipping commitments cascade through carrier fuel selection.
- Government Bodies:Military and civilian aviation agencies with energy security and emissions reduction mandates support demonstration projects and strategic reserve programs.
- Charter Services:Corporate and VIP operators with flexible scheduling and branding requirements adopt early-phase certified fuels ahead of mainstream airline deployment.
Airlines dominate current procurement; freight companies show the steepest expansion trajectory on e-commerce sustainability pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's biorefinery corridor anchors European supply security for hydroprocessed renewable jet fuel, while California's Low Carbon Fuel Standard and the US Department of Energy loan guarantee program redirect capital toward North American production scale-up.
United States
Federal tax incentives and state-level clean fuel standards drive biorefinery construction across the Gulf Coast and Midwest. The EPA renewable fuel standard and California LCFS create stackable credit mechanisms that improve project economics. World Energy's Paramount facility in California sustains North American production scale through continuous hydroprocessing capacity expansion.
Netherlands
EU ReFuelEU Aviation mandates binding SAF percentages at Amsterdam Schiphol and Rotterdam The Hague Airport from 2025. The Dutch national government aligns with EU F-Gas Regulation and ETS aviation inclusion to tighten emissions accountability. Neste leverages its Rotterdam refinery complex to anchor European supply security for certified sustainable aviation fuel volumes.
Germany
Corporate travel procurement pressure and Lufthansa Group decarbonization targets concentrate demand at Frankfurt and Munich hubs. The EU Green Deal and national climate protection legislation enforce aviation emissions reduction pathways. Industrial clusters in North Rhine-Westphalia and Bavaria host power-to-liquid demonstration projects using renewable hydrogen and captured CO2.
Singapore
Changi Airport's hub status and Singapore Airlines sustainability commitments position the city-state as Asia-Pacific's SAF procurement gateway. The Civil Aviation Authority of Singapore coordinates with ICAO CORSIA compliance frameworks for international carrier accountability. Jurong Island's existing petrochemical infrastructure offers brownfield sites for biorefinery conversion and electrofuel pilot plants.
United Kingdom
Heathrow and Gatwick corporate travel contracts increasingly embed carbon intensity clauses forcing network carrier disclosure. The UK Department for Transport supports alternative aviation fuel testing through the Future Fuels for Flight and Freight Competition program. Industrial clusters in Teesside and Humberside attract power-to-liquid investment leveraging North Sea offshore wind and industrial CO2 point sources.
Aviation Alternative Fuel Market Vendor Landscape
Capacity expansion dominates the current landscape as producers race to secure feedstock contracts ahead of ICAO CORSIA compliance deadlines. The market structure consolidates around integrated oil majors with existing refining infrastructure, pure-play biorefinery developers, and technology licensors specializing in alcohol-to-jet conversion. Strategic archetypes include HEFA pathway incumbents leveraging waste lipid supply chains, Fischer-Tropsch specialists targeting synthetic fuel scale-up, and fermentation-based developers advancing isobutanol-to-kerosene routes. Dominant competitive moves encompass strategic partnerships between feedstock aggregators and refiners, plus vertical integration into captive biorefinery construction.
Within the HEFA pathway tier, Neste and World Energy exemplify production-scale operators with established ASTM D7566 certification and airline offtake relationships. Among technology-forward developers, Gevo occupies a position representing alcohol-to-jet specialization through fermentation-derived isobutanol conversion. These named entities anchor industry-level commentary on how pathway diversification and geographic positioning determine competitive access to policy-supported demand pools.
| Leading Market Players |
|---|
| SkyNRG |
| Fulcrum Bioenergy |
| Neste |
| Aemetis |
| Velocys |
| World Energy |
| Eni |
| Alder Fuels |
| Gevo |
| Others |
Supply Flow & Price Mechanics
Network carrier procurement departments at Lufthansa, IAG, and Singapore Airlines anchor pricing power toward long-term offtake contracts that lock in SAF premiums against conventional Jet A baselines. The concentration of buying authority among decarbonization-committed flag carriers forces producers toward contract-based pricing structures that sacrifice spot-market flexibility for volume security.
Pricing Analysis
Feedstock cost pass-through dominates HEFA pathway economics, with waste lipid and biomass oil price volatility transmitted directly to airline contract renegotiations. Pricing stratifies across certification tiers, with ASTM D7566-certified synthetic paraffinic kerosene commanding premiums over novel alcohol-to-jet pathways still awaiting full approval. Cost compression in the HEFA tier is intensifying because agricultural commodity swings erode refinery margins unpredictably. Cargo operators at FedEx and DHL show least price sensitivity due to concentrated sustainability mandates from e-commerce shippers, while regional carriers remain most exposed to spot-price fluctuations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Los Angeles, and Singapore anchor hub-and-spoke fuel logistics, with into-plane operators managing SAF co-mingling through existing Jet A hydrant infrastructure. Production capacity concentrates in the United States, the Netherlands, and Singapore, drawing from waste lipid aggregators, agricultural biomass processors, and industrial CO2 point sources respectively. Single-source vulnerability at the Rotterdam biorefinery corridor creates supply chain risk if feedstock disruptions or regulatory shifts interrupt European output. Distribution runs through airport fueling services with mass-balance certification capability, though direct supply contracts between producers and carriers are expanding fastest as price hedging instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation alternative fuel operates as a regulatory compounder where EU ReFuelEU Aviation mandates and ICAO CORSIA compliance deadlines mechanically expand addressable demand regardless of crude oil price cycles.
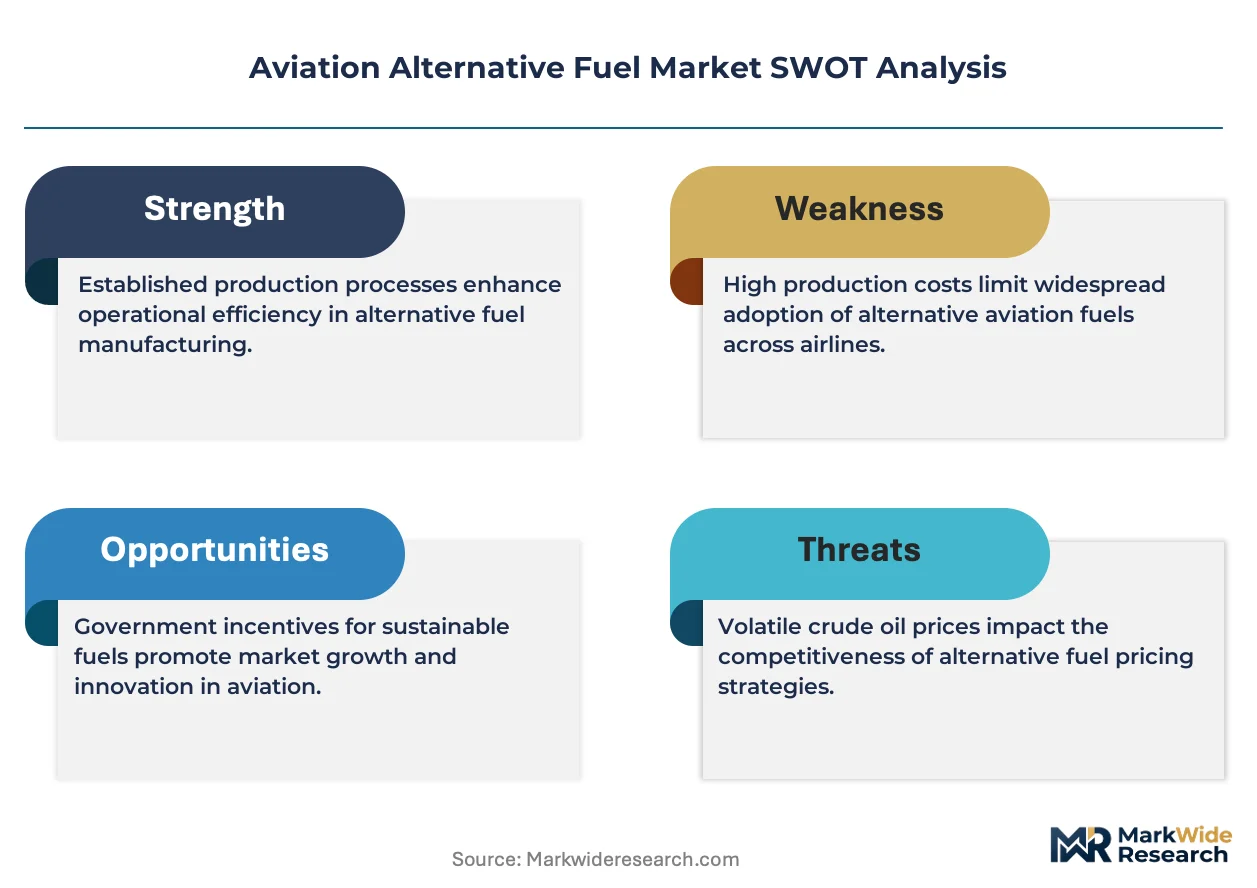
For Market Incumbents: Extend ASTM D7566 certification coverage to emerging alcohol-to-jet pathways before novel producers achieve commercial scale, locking in regulatory preference for established pathways. Neste and World Energy should anchor backward integration into captive waste lipid supply chains in the United States and Southeast Asia, defending margin position against feedstock cost volatility that threatens HEFA economics. Capacity addition in Singapore and California reinforces geographic diversification against European supply concentration risk. For New Entrants and Emerging Players: Power-to-liquid electrofuel technology offers the most penetrable wedge for capital-light entry, targeting regions with stranded renewable electricity and industrial CO2 point sources in Norway, Chile, and the United Kingdom where incumbents lack established infrastructure. Alcohol-to-jet conversion using fermentation-derived isobutanol presents a second white-space target, serving corporate aviation and regional carrier segments ahead of mainstream airline certification. Go-to-market positioning should emphasize ASTM D7566 pre-certification partnerships with smaller producers seeking quality control automation. For Investors and Strategic Acquirers: Integrated oil majors with existing refining infrastructure are the most active acquirers in this space, seeking technology licenses and brownfield biorefinery sites to accelerate SAF capacity deployment. Acquisition targets should display captive feedstock contracts, approved certification pathways, and airline offtake agreements extending across the analysis window. The signal to watch is California LCFS credit price trajectory, which indicates whether state-level incentive stacking can sustain project returns if federal policy support weakens.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Agreement | Airline commitments at Amsterdam Schiphol and Los Angeles International de-risk refinery construction financing. |
| Feedstock Supply Integration | Backward integration into waste lipid aggregation secures margin against agricultural commodity price swings. |
| Certification Pathway Expansion | ASTM D7566 approval for alcohol-to-jet routes opens procurement to corporate aviation and regional fleets. |
| Power-to-Liquid Scale-Up | Electrofuel projects in Norway leverage stranded wind resources to target cost parity with HEFA pathways. |
| Geographic Capacity Diversification | Biorefinery construction in Singapore and California reduces European supply concentration vulnerability. |
Methodological Framework
Direct dialogue with biorefinery project developers, airline sustainability officers, fuel procurement managers at network carriers, and ASTM certification specialists grounded qualitative assessment in operational reality. Secondary validation drew from EPA renewable fuel standard filings, EU ReFuelEU Aviation regulatory texts, ICAO CORSIA implementation documents, and Department of Energy loan guarantee disclosures. Bottom-up capacity installation tracking and top-down policy demand quantification were triangulated against producer revenue disclosures and airline offtake announcements.
Segment-level projections across fuel type, application, distribution channel, and end user were generated through the analysis window using capacity buildout timelines, feedstock availability constraints, and regulatory mandate enforcement schedules. CAGRs were derived from installed production capacity trajectories, airline fleet renewal cycles, and corporate travel procurement pressure indices. Forecast inputs incorporated HEFA pathway yield assumptions, power-to-liquid electrolyzer cost curves, and alcohol-to-jet catalytic efficiency improvements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to feedstock cost volatility, policy durability across electoral cycles, and novel pathway certification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Hydrogen Furnace Market