
 Eosinophilic Granulomatosis with Polyangiitis Treatment Market | 2026-2036
Eosinophilic Granulomatosis with Polyangiitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Eosinophilic Granulomatosis with Polyangiitis Treatment Market Foresight
Subscription-based patient monitoring and digital adherence platforms are shifting how pharmaceutical firms monetize EGPA therapy beyond the drug vial. GlaxoSmithKline leverages its respiratory-immunology overlap to sustain bundled service contracts with academic medical centers. AstraZeneca anchors its position through biologics manufacturing scale, while F. Hoffmann-La Roche differentiates via diagnostic-companion testing integration.
Eosinophilic granulomatosis with polyangiitis is a systemic small-vessel vasculitis characterized by asthma, eosinophilia, and granulomatous inflammation, typically managed with corticosteroid induction followed by steroid-sparing maintenance protocols. Biologics targeting interleukin-5 pathways now command the fastest-expanding share of the product type segment as clinicians seek remission without prolonged high-dose corticosteroid exposure. The intravenous administration route still dominates hospital-based induction therapy, though subcutaneous biologics are gaining ground in maintenance stages where homecare and specialty center channels reduce infusion burden.
FDA orphan drug exclusivity and EMA's rare disease designation framework shape development priorities by extending market protection timelines for novel EGPA therapies. The EU AI Act and MDR compliance requirements are raising the validation threshold for algorithmic diagnostic tools used in eosinophil monitoring and relapse prediction. Stakeholders must track how regulator convergence on real-world evidence standards will reshape post-market commitment requirements and pricing negotiations for biologic maintenance regimens.
Market Dynamics
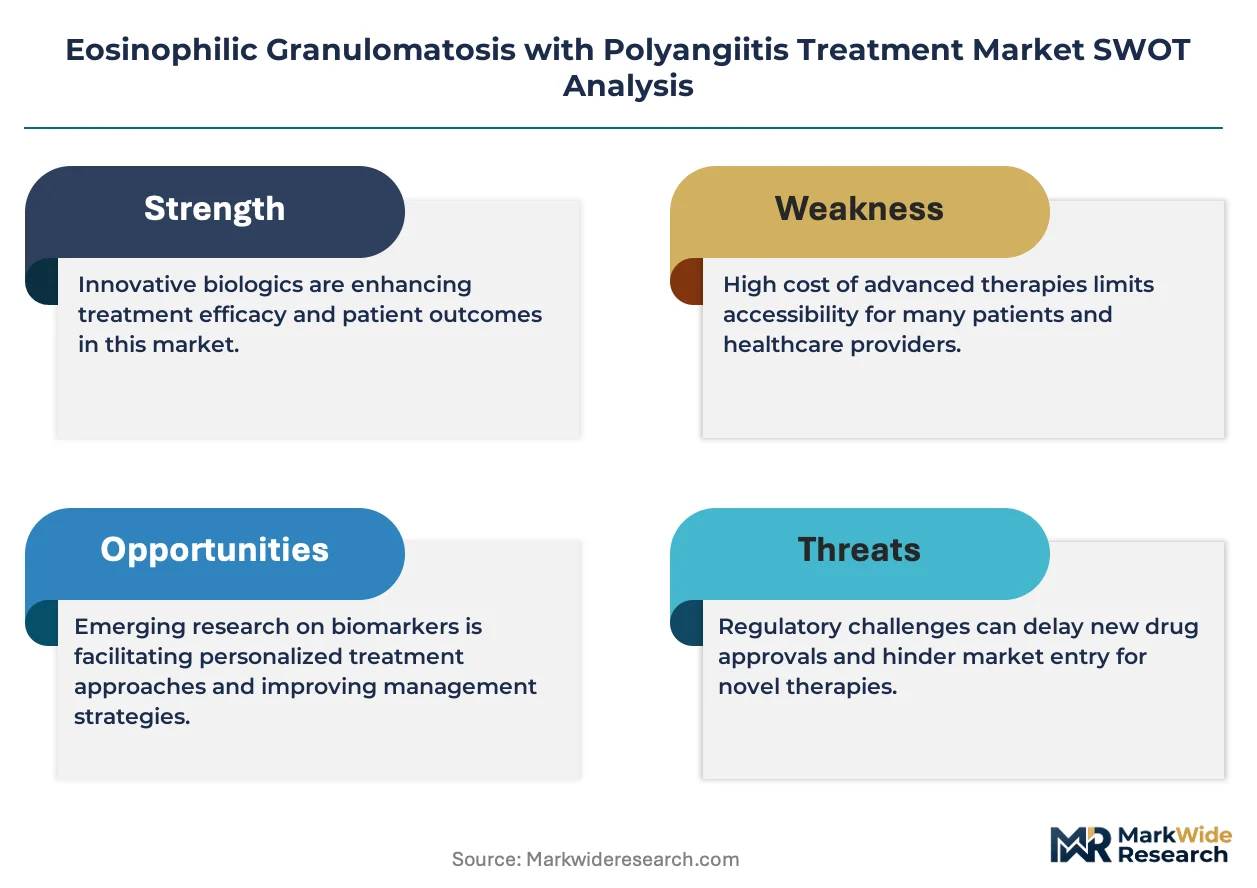
Biologics targeting interleukin-5 pathways are displacing prolonged corticosteroid protocols in EGPA maintenance therapy, reshaping prescribing patterns across hospital-based rheumatology and immunology departments while compressing the addressable market for traditional immunosuppressants.
Growth Catalysts
- FDA orphan drug exclusivity:Extended market protection timelines incentivize novel therapy development for rare autoimmune indications. Pharmaceutical developers prioritize EGPA pipelines due to regulatory de-risking.
- Homecare infusion networks:Subcutaneous biologic administration is expanding patient access beyond academic medical centers. Specialty pharmacy channels reduce treatment burden for maintenance-stage patients.
- Eosinophil monitoring algorithms:Diagnostic-companion testing integration enables precision dosing and relapse prediction. Clinicians adopt biomarker-guided protocols to optimize biologic intervals.
Market Restraints
- Biologics manufacturing concentration:Contract development and manufacturing organizations cluster in Switzerland and Ireland. Supply vulnerability persists for monoclonal antibody production at commercial scale.
- EMA MDR compliance costs:Algorithmic diagnostic tools face elevated validation thresholds for eosinophil quantification devices. Small diagnostic developers exit rather than absorb certification expenses.
- Corticosteroid substitution inertia:Generic prednisone remains the default induction therapy in resource-constrained settings. Payer prior authorization requirements delay biologic access.
Strategic Opportunities
- Japan's rare disease reimbursement:The Ministry of Health, Labour and Welfare maintains premium pricing for designated intractable diseases. EGPA qualifies for expedited coverage under the sakigake framework.
- Digital adherence platforms:Subscription-based patient monitoring creates recurring revenue beyond drug vial sales. Pharmaceutical firms bundle injection training and symptom tracking services.
- Real-world evidence convergence:FDA and EMA alignment on post-market study standards reduces duplicate data collection. Developers leverage single global registries to satisfy multiple regulators.
Industry Challenges
- Specialized immunology nursing shortages:Biologic infusion protocols require trained staff for adverse event management. Academic medical centers compete for limited talent pools.
- Legacy electronic health record integration:Eosinophil trend visualization tools face interoperability barriers with hospital IT systems. Implementation timelines stretch across multiple budget cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eosinophilic Granulomatosis with Polyangiitis Treatment Market |
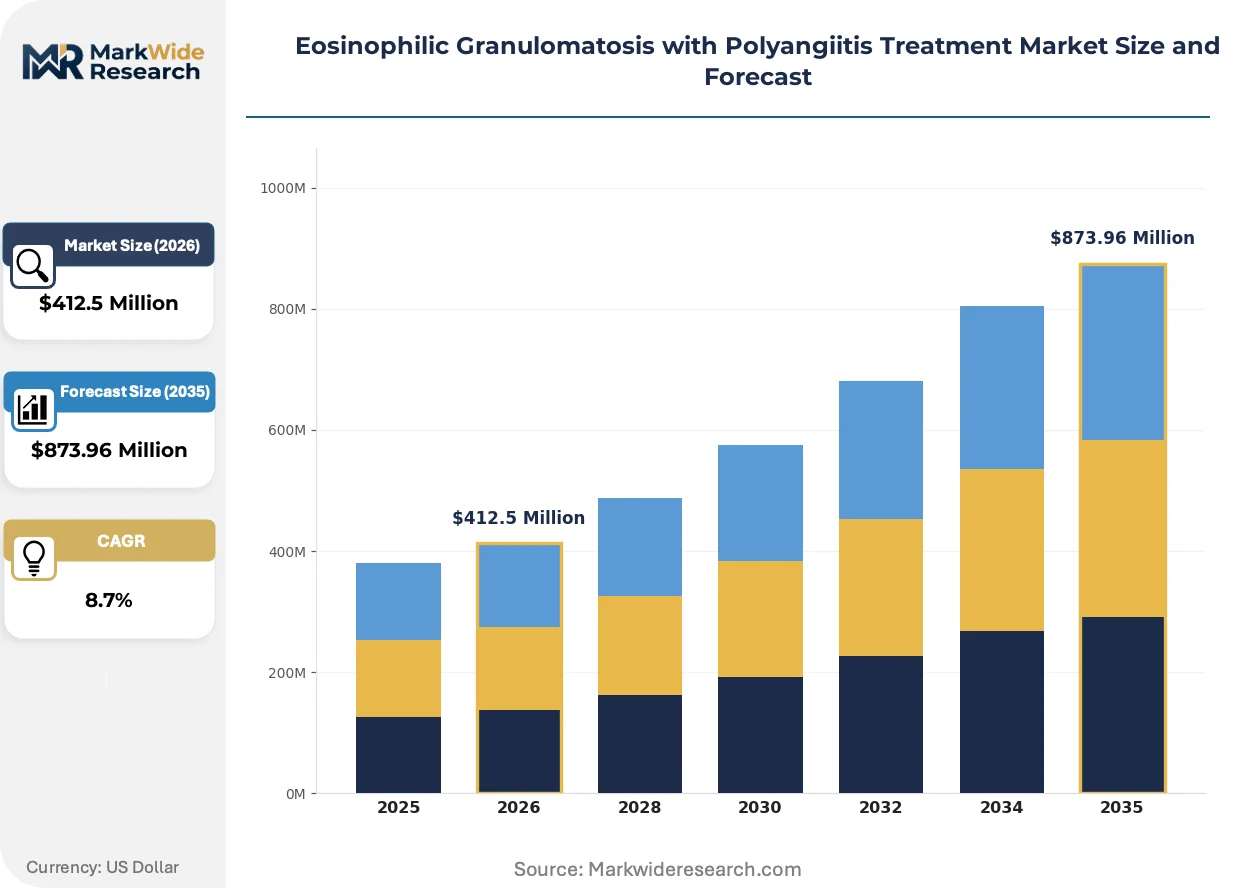
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Plasma Exchange Administration Route: Oral, Intravenous, Subcutaneous, Inhalation End User: Hospitals, Clinics, Homecare, Specialty Centers Treatment Stage: Induction, Maintenance, Relapse, Supportive Care |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, F. Hoffmann-La Roche Ltd, Pfizer Inc., Novartis AG, Sanofi S.A., Bristol Myers Squibb, Teva Pharmaceutical Industries Ltd, NS Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eosinophilic Granulomatosis with Polyangiitis Treatment Market Shifts & Advancements
Next-generation IL-5 and IL-5 receptor antagonists are compressing remission timelines while digital biomarkers enable remote disease activity monitoring outside traditional clinic visits.
Subcutaneous auto-injector formulations for anti-IL-5 biologics are rewriting patient convenience expectations in maintenance therapy. Community rheumatology practices adopt these devices to retain patients who would otherwise transfer to infusion centers. The shift is compressing hospital outpatient revenue while expanding specialty pharmacy dispensing volumes.
EMA's Medical Device Regulation implementation is elevating clinical evidence requirements for algorithmic eosinophil counting systems. Diagnostic manufacturers must generate prospective validation data rather than relying on analytical equivalence studies. Germany's reference laboratory network is consolidating purchasing around MDR-certified platforms, marginalizing uncertified competitors.
Hospital pharmacy committees increasingly require pharmacoeconomic modeling before adding biologics to formularies. Payers in the United States demand outcomes-based contracts with rebate triggers tied to steroid-free remission rates. Academic medical centers in Massachusetts and California pilot these arrangements, establishing templates for national contract expansion.
Eosinophilic Granulomatosis with Polyangiitis Treatment Market Segmentation
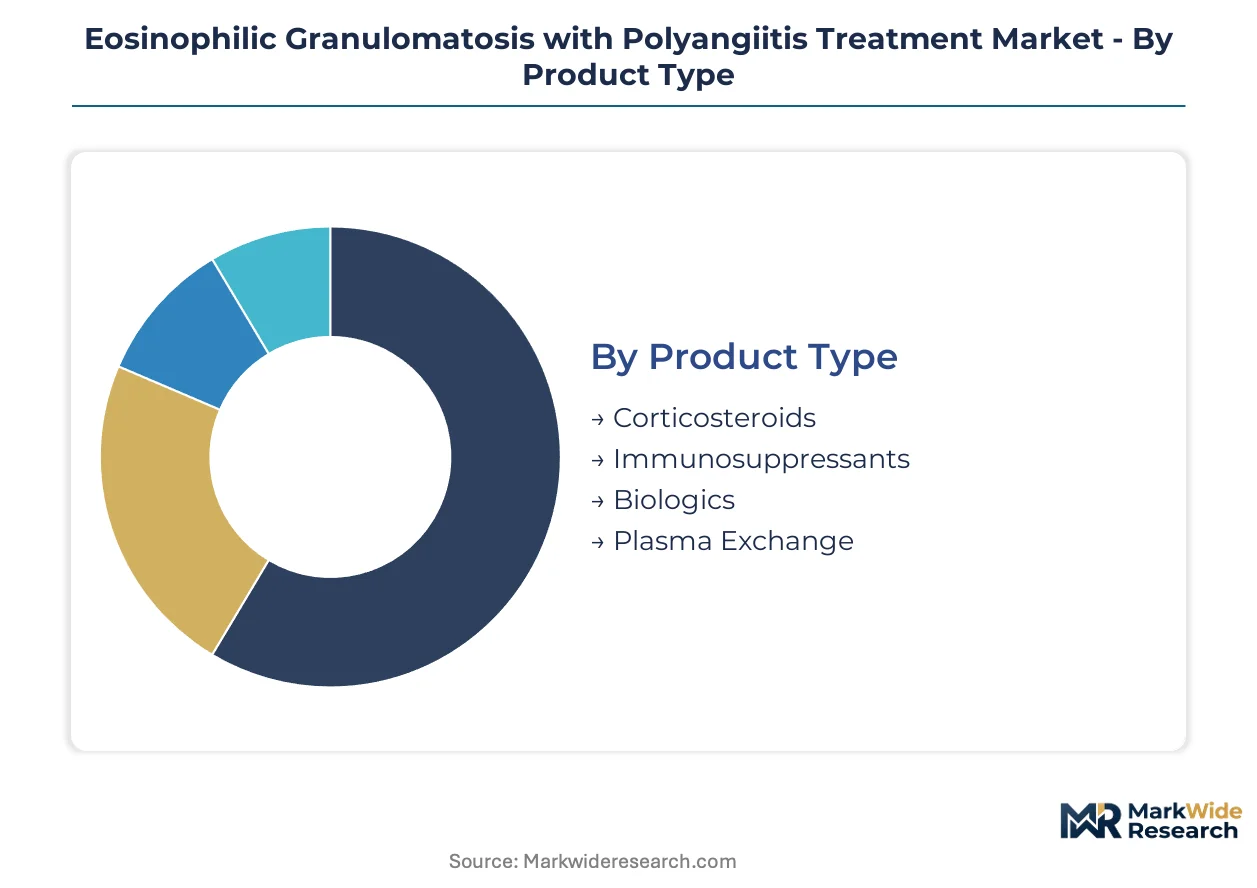
EGPA treatment segmentation reveals how therapeutic modalities, delivery channels, and care settings interact to shape prescribing economics. Each dimension carries distinct reimbursement codes, manufacturing requirements, and patient access constraints that determine commercial viability.
Product Type:
Integration depth varies sharply across this category, with biologics requiring cold-chain infrastructure and companion diagnostics while corticosteroids operate through generic wholesale channels.
- Biologics:Monoclonal antibodies targeting IL-5 pathways require sub-zero storage and trained infusion staff. Demand concentrates in academic medical centers across Germany and Japan where specialist density supports complex protocol management.
- Corticosteroids:Oral prednisone and methylprednisolone remain the induction standard due to immediate availability and minimal infrastructure requirements. Volume placements dominate in resource-constrained settings where payer prior authorization delays biologic access.
- Immunosuppressants:Cyclophosphamide and azathioprine bridge patients toward steroid-sparing maintenance.
- Plasma Exchange:Apheresis protocols address severe organ-threatening manifestations.
Volume placements concentrate in Corticosteroids; the faster expansion belongs to Biologics.
Administration Route:
Cost tiering separates hospital-based infusion services from ambulatory and home delivery models, with reimbursement differentials driving channel migration.
- Intravenous:Hospital outpatient departments administer biologic induction therapy under continuous monitoring. Germany's DRG system bundles these services, concentrating volume in university hospitals.
- Subcutaneous:Auto-injector devices enable maintenance dosing outside infusion centers. Specialty pharmacy networks across the United States capture this volume as patients seek reduced clinic burden.
- Oral:Prednisone tablets dominate induction protocols globally.
- Inhalation:Nebulized corticosteroids address respiratory manifestations.
Intravenous captures current volume leadership; Subcutaneous is climbing the fastest as homecare infrastructure matures.
End User:
Customer type segmentation maps to severity grading, with organ-threatening disease routing to hospitals and stable maintenance shifting toward lower-acuity settings.
- Hospitals:Tertiary centers manage acute vasculitis flares, alveolar hemorrhage, and cardiac involvement. Japan's designated intractable disease hospitals concentrate EGPA referrals under the sakigake framework.
- Specialty Centers:Dedicated vasculitis clinics coordinate multidisciplinary care including rheumatology, pulmonology, and cardiology. Massachusetts and California academic medical centers pilot outcomes-based contracts with payers.
- Clinics:Community rheumatology practices handle stable maintenance patients.
- Homecare:Nursing services support subcutaneous biologic administration.
Hospitals retain the highest case complexity; Specialty Centers are gaining share fastest through bundled payment models.
Treatment Stage:
Maturity gradients separate established induction protocols from evolving maintenance strategies and emerging relapse prevention approaches.
- Induction:High-dose corticosteroid protocols with or without cyclophosphamide achieve rapid disease control. FDA and EMA guidelines standardize these approaches across the United States and European Union.
- Maintenance:Biologic substitution for prolonged steroid exposure now dominates clinical trial design. Payers demand steroid-free remission metrics before approving extended therapy.
- Relapse:Escalation protocols re-induce remission after disease recurrence.
- Supportive Care:Adjunctive therapies address comorbid asthma and sinus disease.
Induction holds current procedural volume; Maintenance shows the steepest expansion trajectory as biologics displace chronic steroid dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing concentrates in Switzerland and Ireland, while patient demand clusters in markets with established rare disease reimbursement pathways. The United States, Germany, and Japan absorb the majority of advanced therapy volumes due to specialist referral density and orphan drug pricing frameworks.
United States
Academic medical centers in Massachusetts and California pilot outcomes-based contracts with commercial payers. FDA orphan drug exclusivity extends market protection timelines for novel EGPA therapies. The Boston-Cambridge corridor anchors biologics clinical trial activity and specialist vasculitis clinic networks.
Germany
University hospitals concentrate EGPA induction therapy under the DRG bundled payment system. EMA orphan designation and MDR compliance requirements shape diagnostic tool validation standards. The reference laboratory network in North Rhine-Westphalia consolidates purchasing around MDR-certified eosinophil monitoring platforms.
Japan
Designated intractable disease hospitals concentrate patient referrals under the sakigake expedited approval framework. The Ministry of Health, Labour and Welfare maintains premium pricing for rare autoimmune conditions. The Kanto region around Tokyo hosts the highest density of specialist immunology departments and biologics infusion capacity.
Switzerland
Contract development and manufacturing organizations cluster around Basel and Zurich for monoclonal antibody production at commercial scale. Swissmedic regulates biologics quality standards for EU and global export markets. The Basel biotech corridor supplies active pharmaceutical ingredients to formulation facilities across Germany and France.
United Kingdom
NHS England's specialized commissioning framework routes EGPA patients to designated vasculitis centers in London and Manchester. The MHRA post-Brexit regulatory pathway maintains alignment with EMA orphan drug standards. The Oxford-Cambridge-London golden triangle anchors academic research into IL-5 pathway therapeutics.
Eosinophilic Granulomatosis with Polyangiitis Treatment Market Competitive Landscape
Capital-heavy biologics manufacturers compete with asset-light specialty pharmaceutical developers for positioning in the EGPA treatment landscape. The market structure consolidates around three large-cap immunology players with respiratory overlap, mid-tier rare disease specialists, and emerging biotech developers pursuing novel cytokine targets. Dominant competitive moves include M&A to acquire IL-5 pathway assets and strategic partnerships to secure manufacturing capacity.
Within the large-cap immunology tier, GlaxoSmithKline plc and AstraZeneca plc occupy positions defined by respiratory-immunology portfolio overlap and biologics manufacturing scale. F. Hoffmann-La Roche Ltd exemplifies the diagnostic-therapeutic integration archetype through companion testing capabilities. These three companies represent distinct strategic positions: bundled service contracts, manufacturing scale advantages, and precision medicine integration respectively.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Novartis AG |
| Sanofi S.A. |
| Bristol Myers Squibb |
| Teva Pharmaceutical Industries Ltd |
| NS Pharma |
| Others |
Supply & Pricing Matrix
Captive biologics manufacturing in Switzerland and Ireland anchors supply positions while enabling premium pricing power for monoclonal antibody producers serving hospital-based rheumatology departments across Germany, Japan, and the United States. This integration pattern insulates incumbents from generic prednisone competition while concentrating margin capture upstream in active pharmaceutical ingredient production.
Pricing Analysis
Pricing pressure intensifies in maintenance-stage biologics as United States payers demand outcomes-based contracts with rebate triggers tied to steroid-free remission metrics. Three-tier pricing structure across originator biologics, biosimilar entrants, and generic corticosteroids reflects FDA orphan exclusivity premiums versus volume-driven prednisone commoditization. Academic medical centers in Massachusetts and California exhibit highest price sensitivity due to bundled payment pilot obligations, while Japan's sakigake-designated hospitals maintain lowest sensitivity under premium rare disease reimbursement.
Supply Chain Analysis
Direct-to-hospital pharmacy channels handle biologic induction therapy distribution, with specialty pharmacy networks capturing subcutaneous maintenance volumes. Manufacturing concentrates in Switzerland, Ireland, and the United States for monoclonal antibody production, drawing from Chinese and Indian sources for chemical synthesis precursors. Single-source vulnerability persists for IL-5 pathway bioreactor capacity, with tariff exposure on cold-chain logistics equipment amplifying supply risk for European and Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR compliance and FDA orphan drug frameworks erect substantial cost-of-entry barriers that protect compliant biologics manufacturers from diagnostic tool competitors unable to absorb certification expenses.
For Market Incumbents: Deepen diagnostic-therapeutic integration through companion eosinophil monitoring algorithms to defend against standalone biologic commoditization. Expand captive manufacturing capacity in Basel and Zurich corridors to offset CDMO concentration risk from Irish single-source dependencies. For New Entrants and Emerging Players: FDA orphan drug exclusivity in the United States opens a window for novel cytokine target developers to secure extended market protection timelines before established IL-5 players consolidate. Target subcutaneous auto-injector formulation gaps in community rheumatology practices, leveraging specialty pharmacy channel partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier rare disease specialists with Phase III-ready pipelines and established EMA rapporteur relationships. Long-term viability hinges on regulatory navigation capabilities rather than manufacturing scale alone. Watch FDA real-world evidence guidance convergence as the inflection signal for post-market commitment burden reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA orphan designation and FDA breakthrough therapy status compress development timelines for novel IL-5 targets. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Swiss CDMO clusters secures supply for United States and Japanese hospital networks. |
| Diagnostic Companion Development | Algorithmic eosinophil monitoring integration enables precision dosing protocols and relapse prediction services. |
| Reimbursement Strategy | Outcomes-based contracting with Massachusetts and California payers establishes templates for national contract expansion. |
| Pipeline Diversification | Next-generation IL-5 receptor antagonists address non-responder populations inadequately served by existing biologics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. FDA orphan drug designations, EMA submission documents, ClinicalTrials.gov entries, and hospital procurement databases supplied quantitative anchors. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation validated segment-level estimates.
Granularity-level framing applied treatment stage, administration route, and regional regulatory cluster as core segmentation dimensions across the projection horizon. CAGRs derived from patient population epidemiology, biologic penetration curves, and corticosteroid substitution elasticity. Forecast inputs incorporated Japan's sakigake approval velocity and United States outcomes-based contract adoption rates.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous auto-injector biologics would alter the outlook if homecare infrastructure deployment lags. Forecasts reflect assumptions on IL-5 pathway dominance, EMA MDR enforcement stringency, and rare disease reimbursement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market