
 APAC Uterine Cancer Therapeutics and Diagnostics Market | 2026-2036
APAC Uterine Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Uterine Cancer Therapeutics and Diagnostics Market Outlook
India's biologics manufacturing corridor is narrowing the supply gap for monoclonal antibodies used in uterine cancer protocols. Merck & Co. leverages its Keytruda franchise to anchor immuno-oncology positioning across APAC oncology centers. Eisai sustains deep relationships with Japanese academic medical centers for Lenvima combination studies. Roche competes through its Ventana companion diagnostic platform, which controls tissue-based PD-L1 testing workflows in Singapore and Australia.
APAC uterine cancer therapeutics and diagnostics encompasses pharmaceutical interventions and clinical assays targeting malignancies of the endometrium and uterine mesenchyme, including carboplatin-paclitaxel regimens, aromatase inhibitors, anti-PD-1 antibodies, and immunohistochemistry-based biomarker panels that guide treatment selection and monitor therapeutic response. The primary purpose is to reduce mortality from endometrial cancer, the most common gynecologic malignancy in the region, through stage-stratified intervention. Immunotherapy now leads growth among product types as pembrolizumab combinations expand into frontline endometrial carcinoma across APAC formularies. Diagnostic laboratories represent the fastest-scaling end user segment as centralized pathology networks in South Korea and Australia adopt digital slide platforms for remote biomarker interpretation. Hormonal therapies retain mature volume in early-stage, estrogen-receptor-positive populations where fertility preservation drives therapeutic selection.
Japan's PMDA, China's NMPA, and Australia's TGA shape market access through divergent evidentiary requirements for companion diagnostic co-approvals, creating complexity for sponsors pursuing regional label harmonization. India's CDSCO PLI scheme for active pharmaceutical ingredients is reshaping local manufacturing economics for generic chemotherapy agents. South Korea's MFDS real-world evidence framework accelerates post-market surveillance for novel targeted therapies. Stakeholders must monitor how China's national reimbursement list updates affect premium therapy access in provincial hospital networks.
Market Dynamics
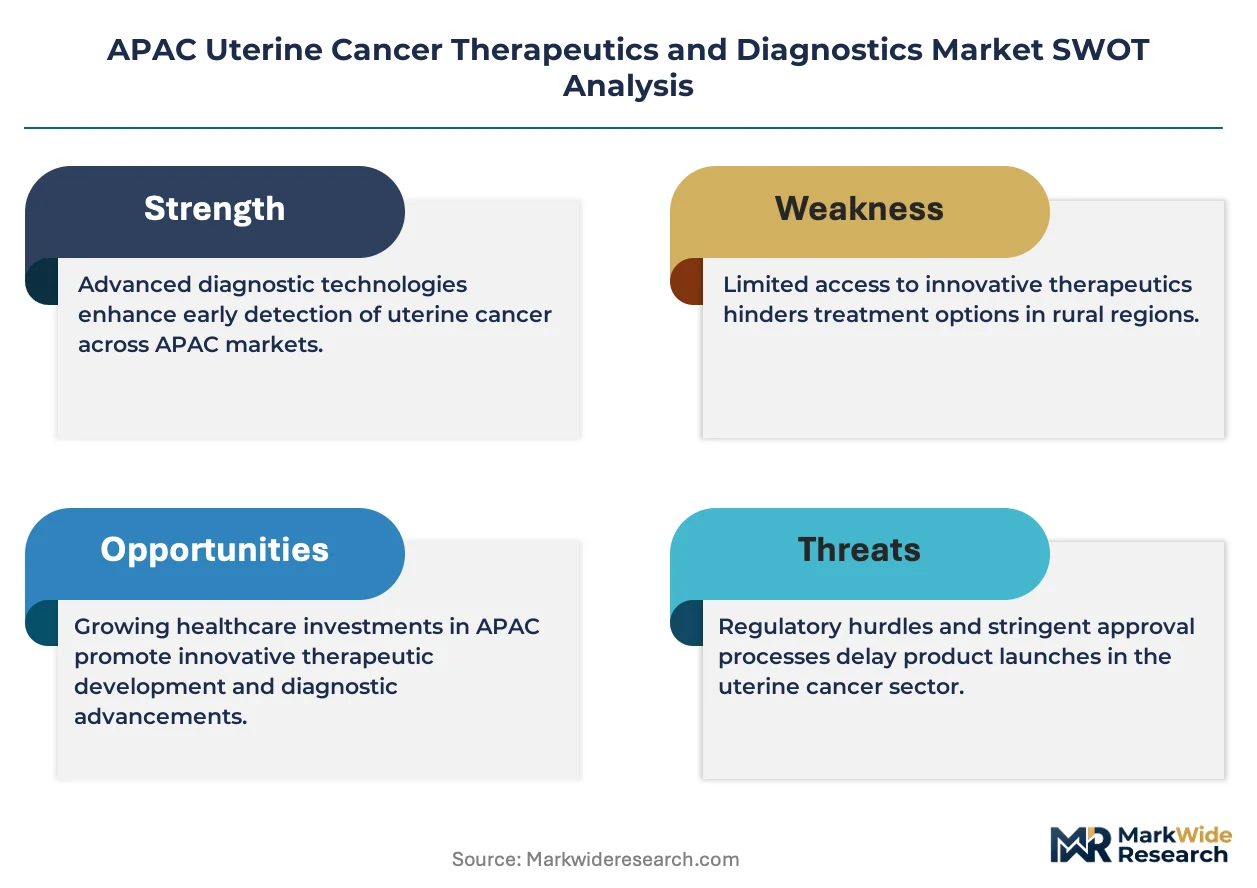
The APAC uterine cancer market pivots on regulatory divergence between Japan's PMDA accelerated approval pathways and China's NMPA real-world evidence requirements, forcing sponsors to maintain parallel development tracks for companion diagnostics and biosimilar hormonal therapies.
Growth Catalysts
- CDSCO PLI Scheme:India's production-linked incentive program for active pharmaceutical ingredients is reshoring generic chemotherapy manufacturing capacity, reducing import dependency for carboplatin and paclitaxel precursors.
- Digital Pathology Networks:Centralized diagnostic laboratories in South Korea and Australia are deploying whole-slide imaging platforms, compressing turnaround times for PD-L1 immunohistochemistry interpretation.
- Frontline Immunotherapy Expansion:Anti-PD-1 antibody combinations are displacing hormonal monotherapy in estrogen-receptor-negative endometrial carcinoma across public hospital formularies in China's tier-1 cities.
Market Restraints
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution for biologic therapies remains concentrated in Japan, Australia, and South Korea, limiting monoclonal antibody access in Southeast Asian secondary cities.
- Companion Diagnostic Co-Approval Friction:PMDA, NMPA, and TGA maintain non-harmonized evidentiary standards for tissue-based biomarker tests, forcing redundant clinical validation studies.
- Reimbursement List Lag:China's National Reimbursement Drug List updates operate on multi-year cycles, delaying patient access to novel targeted therapies approved through conditional pathways.
Strategic Opportunities
- India's Biologics Manufacturing Corridor:Contract development and manufacturing organizations in Hyderabad and Bengaluru are capturing fill-finish capacity for monoclonal antibodies used in uterine cancer protocols.
- Next-Generation Sequencing Integration:Molecular tumor boards in Shanghai and Beijing are adopting comprehensive genomic profiling to guide mismatch repair deficiency testing, creating demand for NGS-based companion diagnostics.
- Telepathology Networks:Rural and tier-3 hospital systems in China and India are connecting to centralized pathology hubs through cloud-based slide sharing, extending biomarker testing reach without capital expenditure.
Industry Challenges
- Bioinformatics Talent Scarcity:Interpretation of complex genomic data from NGS platforms requires specialized computational pathology skills that remain concentrated in Tokyo, Singapore, and Sydney academic medical centers.
- Cross-Border Sample Logistics:Tissue specimen transport for centralized PD-L1 testing encounters customs clearance delays and degradation risks between Southeast Asian collection sites and Australian diagnostic reference laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Uterine Cancer Therapeutics and Diagnostics Market |
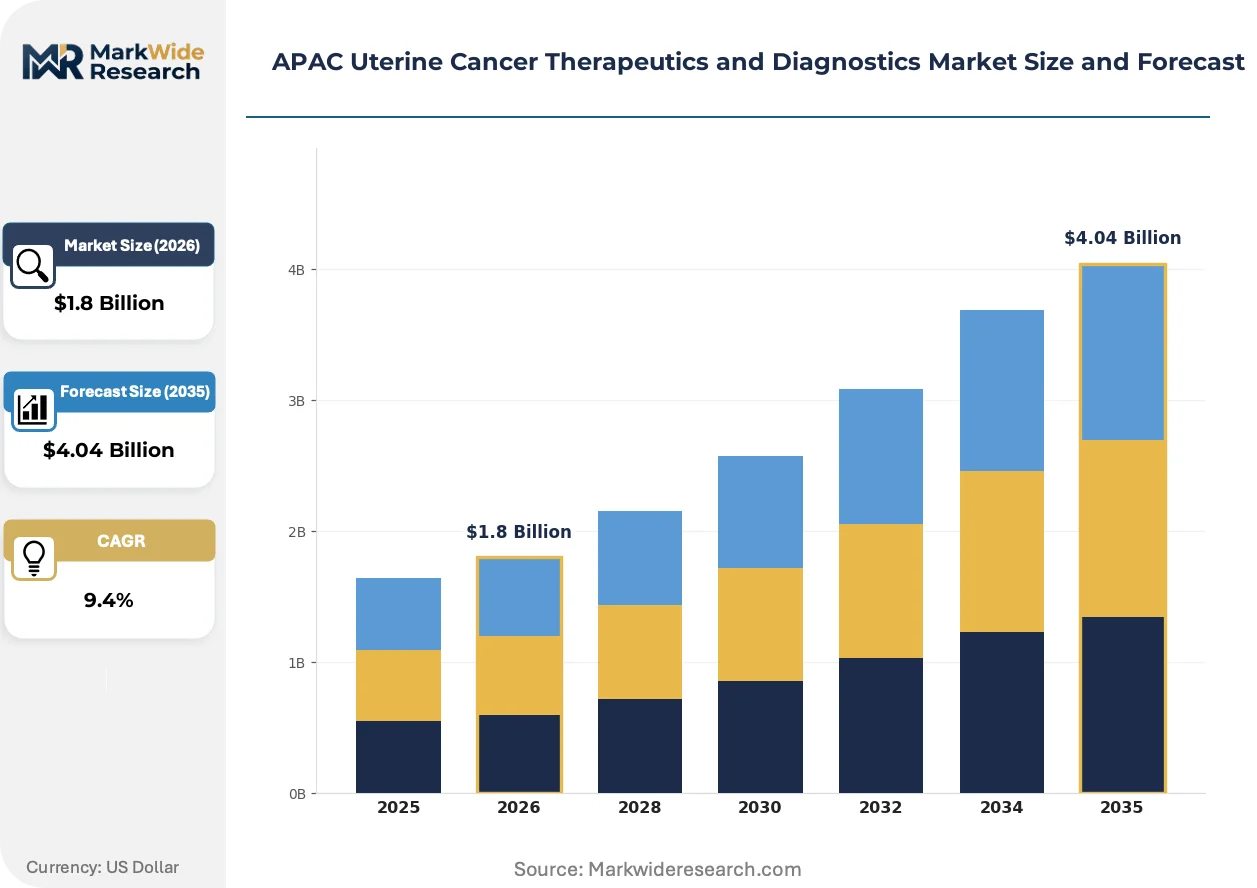
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Hormonal Therapies, Immunotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Indication: Endometrial Cancer, Uterine Sarcoma, Early-stage Cancer, Advanced-stage Cancer |
| Companies Covered | Merck & Co., Inc, Eisai Co. Ltd, F. Hoffmann-La Roche Ltd, Takeda Pharmaceutical Company Limited, Abbott Laboratories, GlaxoSmithKline Plc, Novartis AG, Siemens Healthcare Inc, AstraZeneca PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Uterine Cancer Therapeutics and Diagnostics Market Strategic Shifts
Digital pathology infrastructure is virtualizing tissue-based diagnostic workflows across APAC, compressing the spatial and temporal distance between biopsy acquisition and biomarker-guided treatment selection in distributed hospital networks.
Whole-slide imaging platforms paired with artificial intelligence-assisted scoring algorithms are virtualizing traditional light microscopy workflows for PD-L1 and mismatch repair protein interpretation. Diagnostic laboratories in Melbourne and Seoul are deploying these systems at scale, enabling remote pathologist review across multi-site hospital networks. This virtualization is collapsing the need for on-site specialist pathologists in every treatment center, centralizing interpretive expertise while accelerating turnaround times for endometrial carcinoma molecular subtyping.
PMDA's Sakigake designation system and NMPA's breakthrough therapy pathways are compressing review timelines for novel immuno-oncology combinations, though evidentiary requirements for companion diagnostic co-approval remain jurisdiction-specific. Sponsors pursuing regional label harmonization must navigate divergent tissue collection standards and analytical validation protocols. Japanese academic medical centers are responding by front-loading real-world evidence generation through expanded access programs, while Chinese sites prioritize local clinical trial enrollment to satisfy NMPA domestic data requirements.
Hospital procurement committees in China's provincial networks are consolidating purchasing power through centralized tendering platforms, displacing individual hospital pharmacy autonomy. This concentration is compressing price negotiations for premium hormonal therapies and biosimilar antibodies, with tier-2 and tier-3 facilities delegating formulary decisions to regional health consortiums. The shift is most visible in Jiangsu and Guangdong provinces, where public hospital group purchasing organizations now aggregate demand across 50-plus facilities.
APAC Uterine Cancer Therapeutics and Diagnostics Market Segmentation
Therapeutic modality and care setting stratification reveals divergent investment priorities across APAC oncology networks. Segmentation by molecular mechanism, administration route, and treatment site exposes where capital deployment concentrates versus where infrastructure gaps persist.
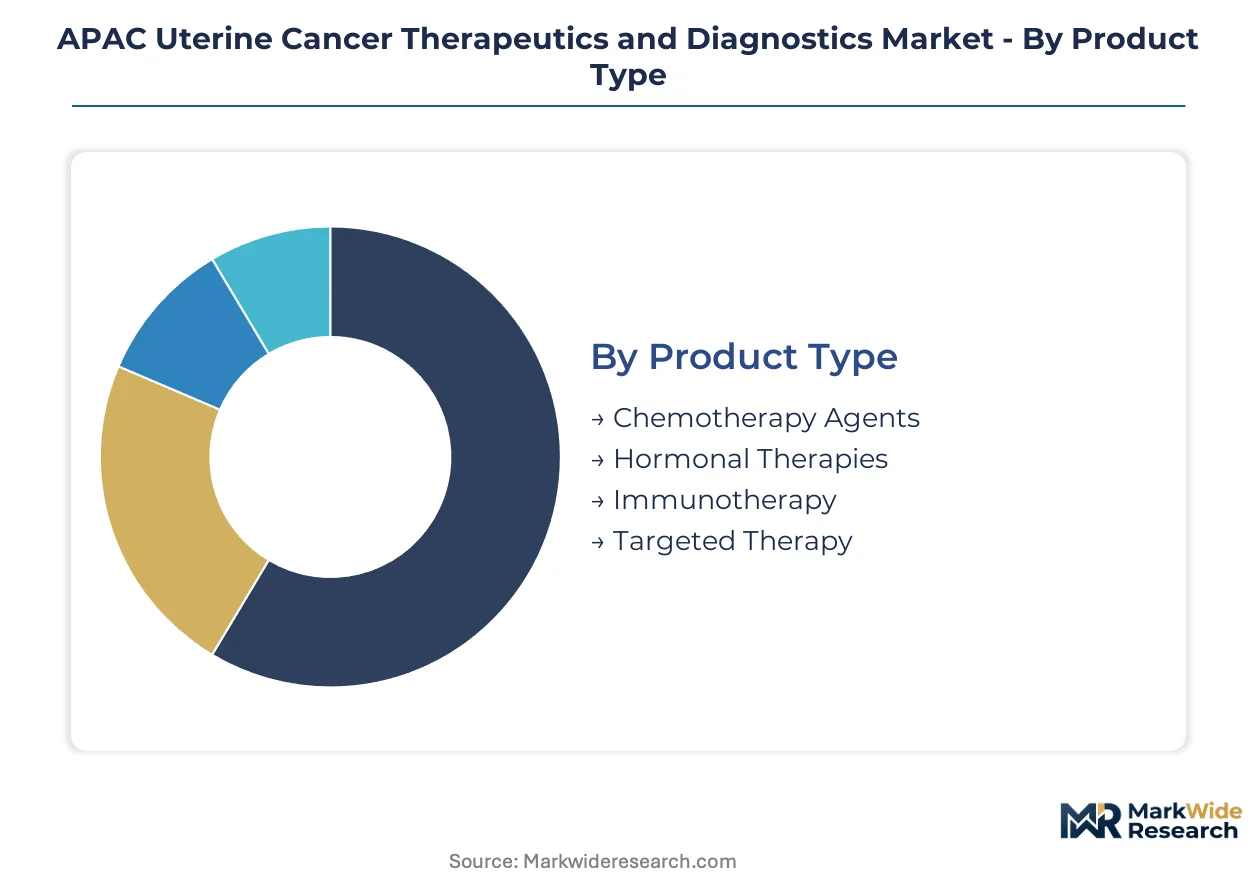
Product Type:
The use-case spectrum spans cytotoxic regimens for first-line intervention through precision immuno-oncology for refractory disease, with each mechanism commanding distinct manufacturing and distribution capabilities.
- Immunotherapy:Anti-PD-1 antibodies and checkpoint inhibitors require cold chain logistics and companion diagnostic pairing. Demand concentrates in Shanghai and Tokyo academic medical centers where molecular tumor boards guide patient selection for pembrolizumab-based protocols.
- Chemotherapy Agents:Carboplatin-paclitaxel combinations remain the backbone of adjuvant and neoadjuvant protocols across India's public hospital networks. Volume concentrates where CDSCO's PLI scheme has reshored generic API manufacturing to reduce import dependency.
- Hormonal Therapies:Aromatase inhibitors and progestins serve estrogen-receptor-positive early-stage populations where fertility preservation drives therapeutic selection in Seoul and Singapore gynecologic oncology units.
- Targeted Therapy:Anti-angiogenics and kinase inhibitors address specific molecular subtypes with concentrated uptake in Australian and Japanese tertiary centers with NGS infrastructure.
Established volume favors Chemotherapy Agents; emerging adoption favors Immunotherapy.
Delivery Mode:
Route selection maps directly to care setting infrastructure and patient throughput requirements across tiered hospital networks.
- Intravenous:Infusion-dependent biologics and cytotoxics dominate hospital-based administration. Demand concentrates in China's tier-1 public hospitals where day oncology units manage high patient volumes.
- Oral:Small-molecule targeted agents and hormonal tablets enable outpatient management. Adoption is climbing fastest in Australian and South Korean networks where pharmacy benefit design supports home-based therapy.
- Subcutaneous:Self-administered monoclonal antibodies reduce infusion chair utilization. Melbourne and Sydney cancer centers are piloting these formulations to decompress day unit capacity.
- Topical:Limited application for localized cervical or vaginal presentations with minimal uterine cancer-specific utilization.
Infusion infrastructure anchors Intravenous dominance; patient convenience and cost containment are accelerating Oral uptake.
End User:
Treatment site stratification reflects diagnostic capability depth and reimbursement pathway complexity across APAC health systems.
- Hospitals:Comprehensive cancer centers with embedded pathology and pharmacy services manage complex multi-modality protocols. Volume concentrates in China's provincial hospital networks and Japan's National Cancer Center-designated facilities.
- Diagnostic Laboratories:Centralized reference labs with NGS and digital pathology platforms are gaining share fastest in South Korea and Australia where regional networks aggregate biomarker testing.
- Clinics:Community oncology practices handle stable hormonal maintenance therapy with limited uptake for acute intervention.
- Home Care:Oral therapy administration and supportive care with nascent penetration limited by cold chain requirements for biologics.
Integrated care favors Hospitals; test centralization and remote interpretation favor Diagnostic Laboratories.
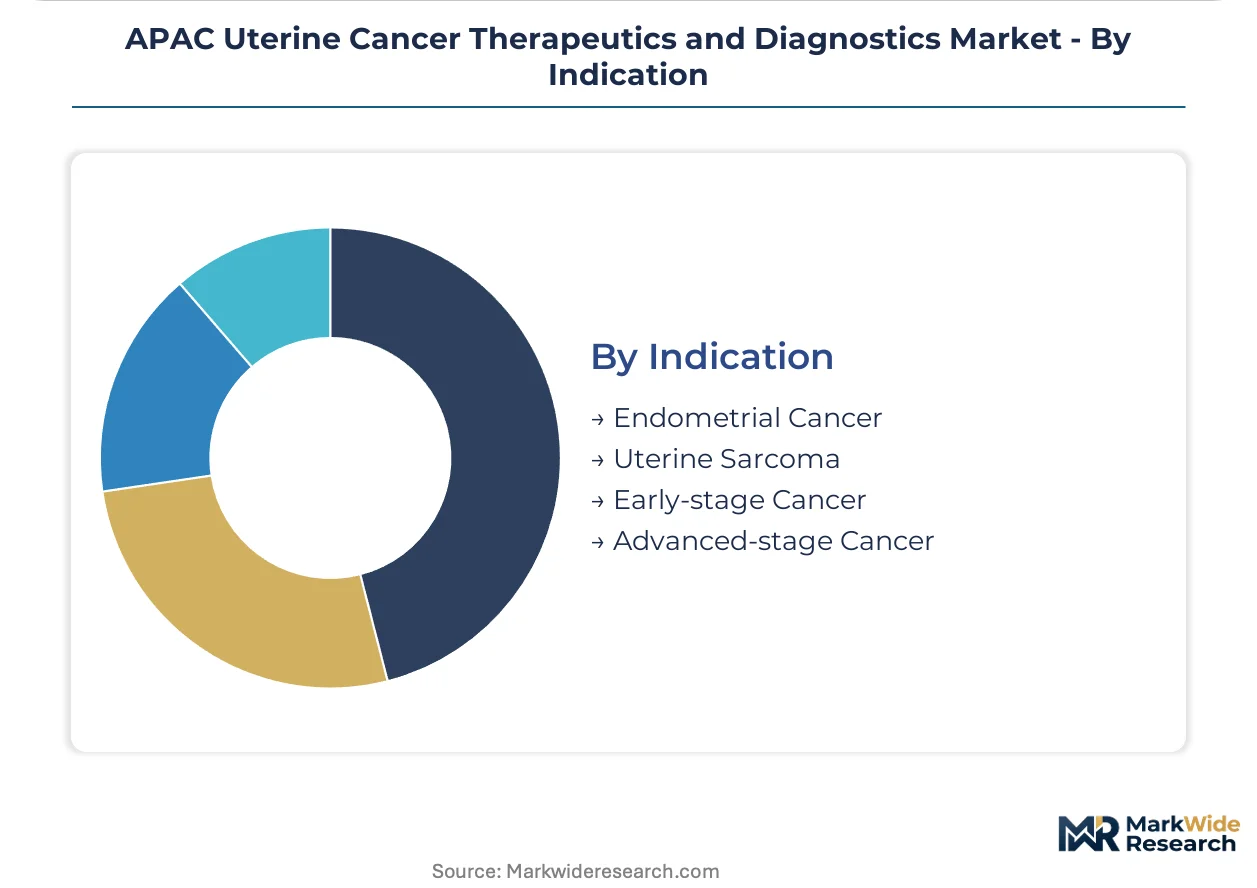
Indication:
Disease stage and histology segmentation determines therapeutic intensity and molecular profiling depth.
- Endometrial Cancer:The dominant histology with molecular subtyping (POLE-mutated, MSI-high, copy-number low, copy-number high) now standard in Beijing and Tokyo academic centers. Demand for mismatch repair testing is climbing fastest.
- Advanced-stage Cancer:Recurrent and metastatic disease drives immunotherapy and combination protocol adoption with concentrated treatment in tertiary referral networks.
- Early-stage Cancer:Surgical adjuvant therapy with hormonal or cytotoxic regimens dominates India's public hospital oncology departments.
- Uterine Sarcoma:Rare mesenchymal histologies requiring specialized sarcoma unit expertise with limited dedicated protocol availability outside Tokyo and Sydney.
Volume concentration sits with Endometrial Cancer; therapeutic innovation and trial enrollment concentrate in Advanced-stage Cancer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's real-world evidence framework and reimbursement list mechanics anchor China's central position in APAC uterine cancer market expansion. Hospital procurement centralization and molecular diagnostic infrastructure investments across tier-1 cities concentrate demand generation and price negotiation leverage.
China
Public hospital networks in Shanghai and Beijing integrate next-generation sequencing into standard endometrial cancer workups, driving companion diagnostic demand. NMPA's conditional approval pathways accelerate pembrolizumab-based protocol access, though National Reimbursement Drug List update cycles delay provincial network penetration. Jiangsu and Guangdong provinces deploy centralized tendering platforms aggregating demand across 50-plus facilities.
Japan
Academic medical centers in Tokyo and Osaka sustain deep relationships for Lenvima combination studies, anchoring immuno-oncology clinical development. PMDA's Sakigake designation compresses review timelines for novel combinations, though tissue-based biomarker co-approval standards diverge from regional neighbors. National Cancer Center-designated facilities concentrate specialized sarcoma unit expertise for rare mesenchymal histologies.
India
CDSCO's production-linked incentive scheme for active pharmaceutical ingredients reshores generic carboplatin and paclitaxel manufacturing to Hyderabad and Bengaluru corridors. Public hospital oncology departments manage high volumes of adjuvant chemotherapy with limited molecular diagnostic infrastructure. Contract development organizations capture fill-finish capacity for monoclonal antibodies used in tertiary referral protocols.
Australia
Melbourne and Sydney cancer centers pilot subcutaneous monoclonal antibody formulations to decompress day unit capacity, shifting administration site economics. TGA's evidentiary requirements for companion diagnostic co-approval create friction with PMDA and NMPA standards, forcing redundant validation studies. Digital pathology platforms enable remote biomarker interpretation across regional hospital networks.
South Korea
MFDS real-world evidence frameworks accelerate post-market surveillance for targeted therapies while Seoul-based molecular tumor boards drive mismatch repair deficiency testing adoption. Centralized reference laboratories deploy whole-slide imaging platforms, compressing PD-L1 immunohistochemistry turnaround times. Gynecologic oncology units in the capital region prioritize fertility-preserving hormonal protocols for early-stage estrogen-receptor-positive populations.
APAC Uterine Cancer Therapeutics and Diagnostics Market Competitive Environment
Multinational pharmaceutical conglomerates and specialized oncology biotechs split the market between broad immuno-oncology platforms and focused gynecologic malignancy portfolios. Consolidation concentrates around checkpoint inhibitor franchises and companion diagnostic control points, with tiered competition separating premium biologic manufacturers from generic chemotherapy suppliers. Three archetypes dominate: integrated immuno-oncology developers with diagnostic partnerships, biosimilar hormonal therapy specialists leveraging manufacturing scale, and centralized pathology platform operators. Competitive moves center on regulatory co-approval bundling and regional hospital procurement consortium penetration.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Eisai Co., Ltd. occupy positions anchored by pembrolizumab-lenvatinib combination development across APAC academic centers. F. Hoffmann-La Roche Ltd exemplifies the diagnostic-platform archetype through tissue-based PD-L1 testing workflow control. These three entities represent distinct strategic vectors: Merck & Co., Inc. with checkpoint inhibitor market development, Eisai Co., Ltd. with kinase inhibitor combination science, and F. Hoffmann-La Roche Ltd with companion diagnostic infrastructure capture.
| Leading Market Players |
|---|
| Merck & Co., Inc |
| Eisai Co. Ltd |
| F. Hoffmann-La Roche Ltd |
| Takeda Pharmaceutical Company Limited |
| Abbott Laboratories |
| GlaxoSmithKline Plc |
| Novartis AG |
| Siemens Healthcare Inc |
| AstraZeneca PLC |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Singapore cold chain corridors carry temperature-sensitive biologics at premium freight rates, concentrating supply power among carriers with validated pharma logistics capabilities while forcing price stratification between Japan-Australia networks and Southeast Asian secondary markets where infrastructure gaps persist.
Pricing Analysis
Price spreads between Tokyo academic medical centers and India's public hospital networks exceed threefold for pembrolizumab-based protocols, with Japan's PMDA Sakigake premium tier, China's NMPA conditional approval mid-tier, and India's CDSCO generic substitution economy tier forming the dominant structure. Price differentiation rests on regulatory pathway speed and companion diagnostic bundling. Cost compression in China's provincial tendering platforms is intensifying as Jiangsu and Guangdong health consortiums aggregate demand across 50-plus facilities. India's public hospital procurement committees demonstrate highest price sensitivity; Japanese National Cancer Center-designated facilities show lowest sensitivity due to fixed reimbursement schedules.
Supply Chain Analysis
Export controls on next-generation sequencing instruments and synthetic biology reagents limit flows from US and EU origins into Chinese diagnostic laboratories, forcing APAC manufacturers to reroute through Singapore and South Korea transshipment hubs. Active pharmaceutical ingredient production concentrates in India's Hyderabad-Bengaluru corridor, China's Zhejiang chemical parks, and South Korea's Songdo biocluster. Biologic fill-finish capacity draws from mammalian cell culture media, single-use bioreactor systems, and aseptic vialing lines. Single-source vulnerability sits with Singapore-based cold chain consolidators. Distribution runs through hospital group purchasing organizations in China, specialty pharmacy networks in Australia, and direct-to-tertiary-center logistics in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic testing services and molecular tumor board consulting are expanding faster than hardware sales, converting one-time instrument placements into recurring revenue streams across APAC oncology networks.
For Market Incumbents: Pre-empt biosimilar hormonal therapy erosion by locking exclusive fill-finish capacity in India's CDSCO PLI corridor and securing PMDA-NMPA simultaneous companion diagnostic co-approval pathways. Anchor defensive positioning through backward integration into PD-L1 antibody production rather than reliance on contract manufacturing organizations. For New Entrants and Emerging Players: Establish a beachhead in China's tier-2 and tier-3 telepathology networks where cloud-based slide sharing extends biomarker testing reach without capital expenditure competition from centralized laboratories. Target India's CDSCO PLI scheme beneficiaries for contract development partnerships as the most penetrable manufacturing entry point. For Investors and Strategic Acquirers: Digital pathology platform operators with FDA-cleared AI scoring algorithms and established hospital network contracts represent the priority acquisition archetype. Long-term viability hinges on converting instrument placements into per-test revenue models across the next decade. Watch for NMPA real-world evidence framework expansions as the inflection signal for premium therapy access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Approval Pathway | PMDA-NMPA simultaneous submissions reduce redundant clinical validation costs for tissue-based biomarker tests. |
| Cold Chain Infrastructure Partnership | Singapore-based logistics consolidation addresses temperature-controlled distribution gaps in Southeast Asian secondary cities. |
| Digital Pathology Platform Integration | Whole-slide imaging deployment in Seoul and Melbourne enables remote PD-L1 interpretation across regional hospital networks. |
| Biologics Manufacturing Scale-Up | Hyderabad and Bengaluru fill-finish expansion captures monoclonal antibody capacity for uterine cancer protocols. |
| Real-World Evidence Generation Program | Japanese academic medical center expanded access programs front-load post-market surveillance for novel immuno-oncology combinations. |
Study Parameters
Cross-validation between primary interviews with oncology drug development executives, regulatory affairs leads at multinational pharmas, hospital formulary directors in Shanghai and Tokyo, and payer access specialists anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov protocol databases, and APAC national reimbursement list publications. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation reconcile volume estimates across the analysis window.
Calibration against historical NMPA approval timelines, PMDA Sakigake designations, and CDSCO PLI scheme disbursement patterns informs the analytical framework. Segmentation dimensions span therapeutic modality, administration route, molecular biomarker status, treatment line setting, and regional regulatory cluster. CAGRs derive from slope-intercept fitting to approved therapy volumes and diagnostic test reimbursement trajectories. Forecast inputs incorporate cold chain infrastructure investment pipelines and centralized pathology network deployment schedules.
Stress conditions across NMPA National Reimbursement Drug List update delays, PMDA companion diagnostic evidentiary requirement shifts, and CDSCO PLI scheme extension decisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway convergence and hospital procurement centralization velocity. Material shifts in China's provincial tendering platform governance or Japan's tissue-based biomarker co-approval standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Global Restless Legs Syndrome Market