
 United States Sports Medicine Market | 2026-2036
United States Sports Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports Medicine Market Intelligence
The Hospital Outpatient Prospective Payment System final rule is rebalancing reimbursement toward ambulatory surgical centers performing arthroscopic procedures. Stryker leverages its integrated operating room platforms to sustain service contracts across major health systems. Arthrex, Inc. anchors the Southwest and Southeast through specialized distributor networks focused on surgeon training. Smith & Nephew plc differentiates via its cartilage repair portfolio and sports trauma hardware lines.
United States sports medicine encompasses orthopedic devices, rehabilitation systems, and performance monitoring technologies designed to prevent, diagnose, and treat musculoskeletal injuries sustained during athletic activity. Surgical devices incorporate bioresorbable anchors and knotless suture constructs for tendon and ligament reattachment. Orthopedic braces command established volume pools while wearable technology represents the fastest-expanding segment as continuous kinematic monitoring gains clinical validation. Rehabilitation applications draw sustained investment from professional franchise medical staffs and university athletic departments.
FDA 510(k) clearance requirements and CMS national coverage determinations shape product commercialization timelines and reimbursement eligibility for novel implantable devices. State-level athletic training licensure boards in Texas, California, and New York govern scope-of-practice rules that determine equipment utilization settings. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classifications for biomechanical analytics platforms.
Market Dynamics
FDA 510(k) clearance streamlining for wearable monitoring devices is compressing commercialization timelines and enabling orthopedic manufacturers to bundle continuous kinematic data with surgical hardware contracts.
Growth Catalysts
- Preventive Care Equipment Procurement:Professional sports teams and collegiate athletic programs are expanding capital budgets for injury prevention systems. Texas, California, and Florida training facility density drives concentrated equipment orders.
- CMS Reimbursement Rebalancing:The Hospital Outpatient Prospective Payment System final rule redirects arthroscopic procedure payments toward ambulatory surgical centers. This expands addressable sites for minimally invasive sports medicine devices.
- Bioresorbable Implant Innovation:Knotless suture constructs and bioabsorbable anchors for tendon reattachment are replacing permanent metal hardware in younger athlete populations. Surgeon training programs accelerate adoption curves.
Market Restraints
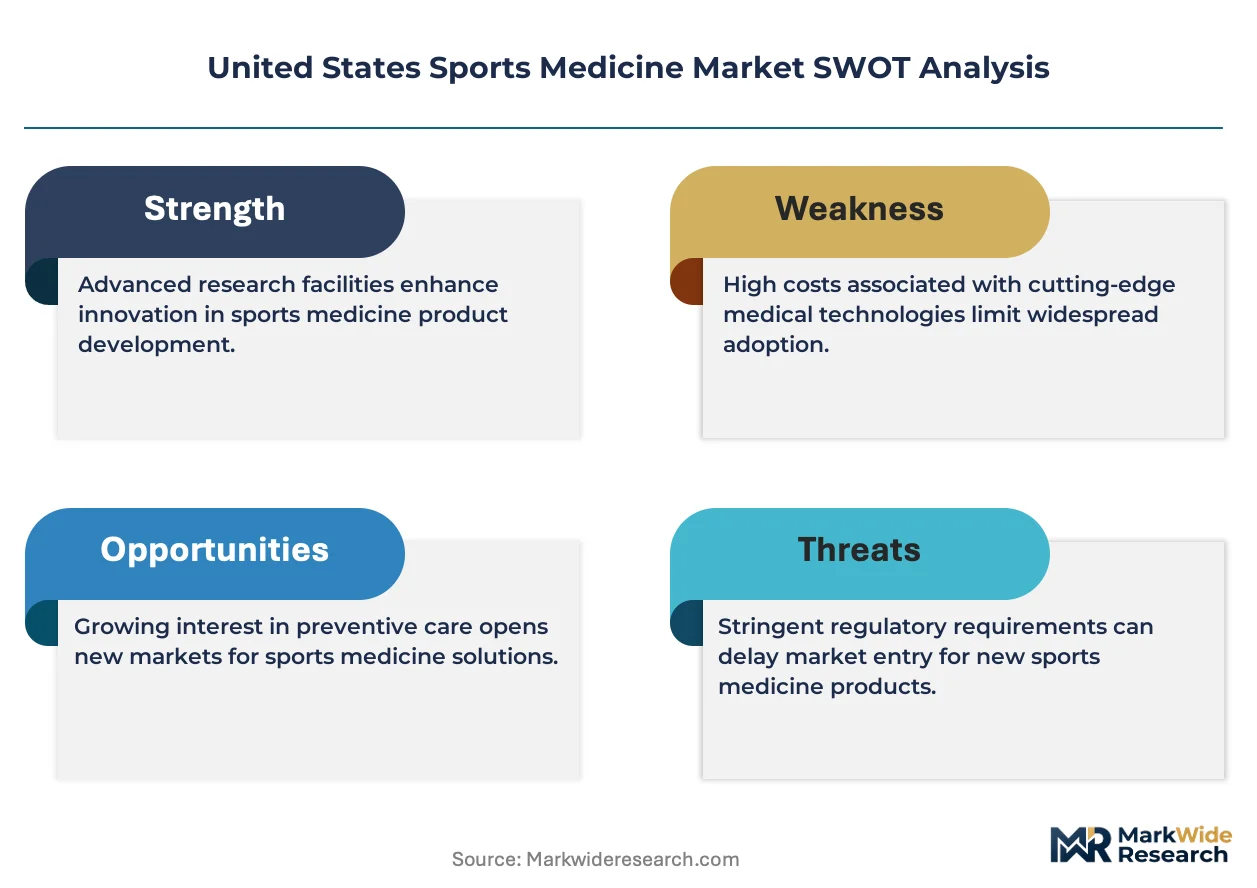
- Software-as-Medical-Device Classification Uncertainty:Evolving FDA guidance on biomechanical analytics platforms creates regulatory friction for AI-enabled motion analysis tools. Developers face unpredictable validation requirements.
- Input Cost Volatility in Advanced Polymers:Bioresorbable polymer feedstock prices fluctuate with specialty chemical supply chains. Device margins compress when medical-grade PLA and PGA resin contracts reset.
- Substitution by Conservative Management:Platelet-rich plasma injections and physical therapy protocols delay or prevent surgical intervention in partial ligament tears. Reimbursement parity with biologics threatens hardware volumes.
Strategic Opportunities
- Underpenetrated Collegiate Athletic Departments:Division II and III universities lack full-time sports medicine infrastructure. Equipment-as-a-service models reduce capital barriers for mid-tier athletic programs.
- Convergence of Wearables and Surgical Planning:Preoperative kinematic data from continuous monitoring is integrating with patient-specific implant design. This creates bundled value propositions for health system contracts.
- State Athletic Training Licensure Expansion:Scope-of-practice rule liberalization in Texas, California, and New York permits athletic trainers to operate advanced diagnostic equipment. This expands the qualified user base for portable imaging and monitoring systems.
Industry Challenges
- Surgeon Training Pipeline Constraints:Fellowship programs in sports medicine produce limited arthroscopy specialists relative to procedure demand. Hospital systems compete for scarce talent through equipment exclusivity deals.
- Integration Complexity with Legacy EMR Systems:Biomechanical data platforms require custom API development to feed kinematic metrics into existing electronic health records. Health system IT backlogs delay deployment.
- Reimbursement Evidence Generation Burden:Novel implantable devices require extensive clinical data for CMS national coverage determinations. Startups lack capital to fund multi-site trials comparable to incumbent portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports Medicine Market |
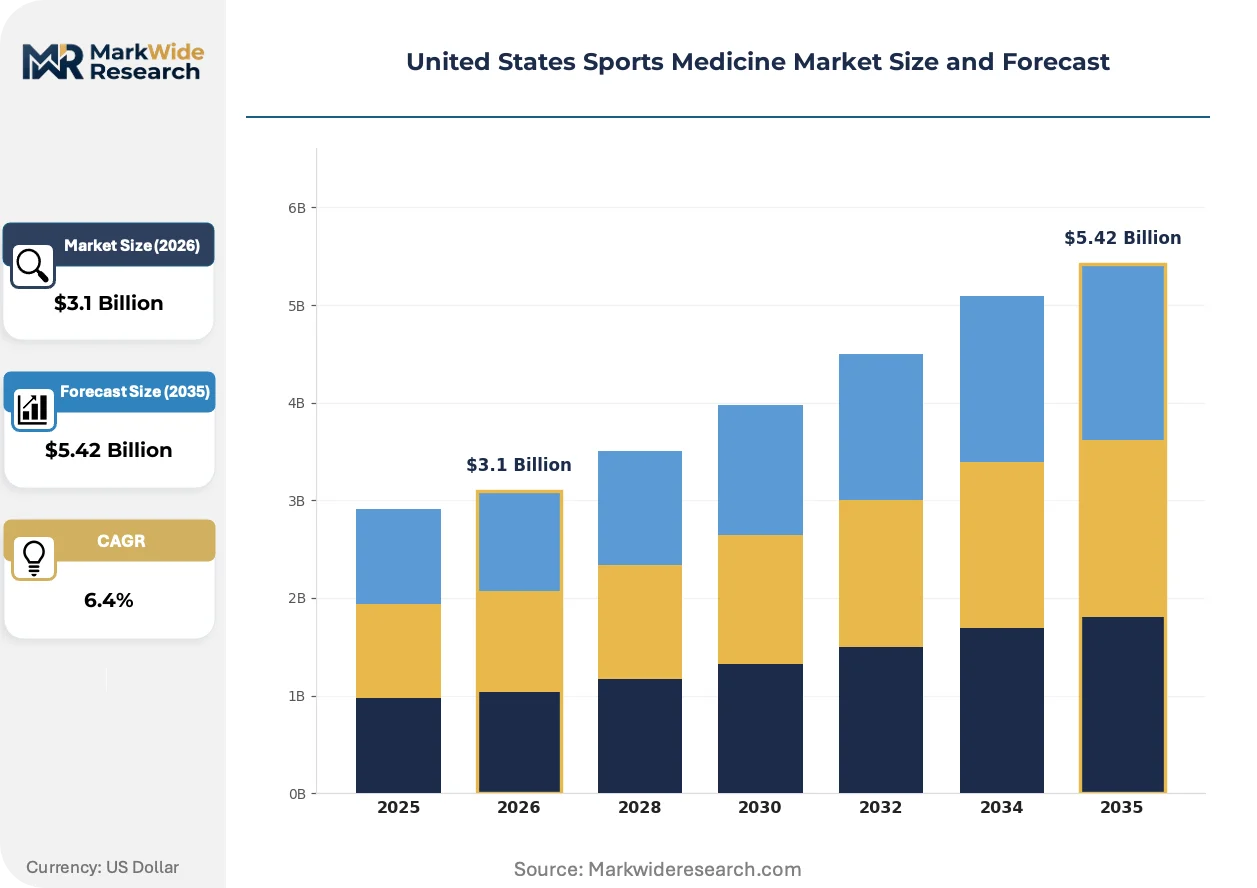
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Braces, Physiotherapy Equipment, Surgical Devices, Others End User: Athletes, Coaches, Fitness Enthusiasts, Recreational Sports Participants Application: Injury Prevention, Rehabilitation, Performance Enhancement, Nutrition Technology: Biomechanics, Wearable Technology, Telehealth, Research Tools |
| Companies Covered | Arthrex, Inc., Smith & Nephew plc, Stryker, Zimmer Biomet Holdings, Inc., CONMED Corporation, DePuy Synthes, Johnson & Johnson Services, Inc., Enovis Corp, Orthofix Medical Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports Medicine Market Strategic Shifts & Innovations
Wearable technology is displacing episodic clinical assessment with continuous kinematic monitoring, while regulatory frameworks and procurement models co-evolve to capture real-time biomechanical data within standard care pathways.
Smart textile sensors and inertial measurement units are integrating into compression garments and joint sleeves for real-time motion capture. NCAA Division I athletic departments and NBA franchise medical staffs deploy these systems for load management and fatigue prediction. The technology is integrating training decisions with objective tissue stress metrics, reducing reliance on subjective athlete reporting.
FDA guidance on software-as-a-medical-device classifications is stabilizing pathways for biomechanical analytics platforms. Developers now structure 510(k) submissions around predetermined change control plans for algorithm updates. Arthroscopic device manufacturers respond by acquiring motion analysis capabilities to bundle diagnostic and therapeutic offerings.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Health systems now separately contract maintenance, software updates, and clinical training for orthopedic devices. This pattern concentrates in California and Texas health networks with dedicated sports medicine service lines, where procurement teams negotiate componentized vendor agreements.
United States Sports Medicine Market Segmentation
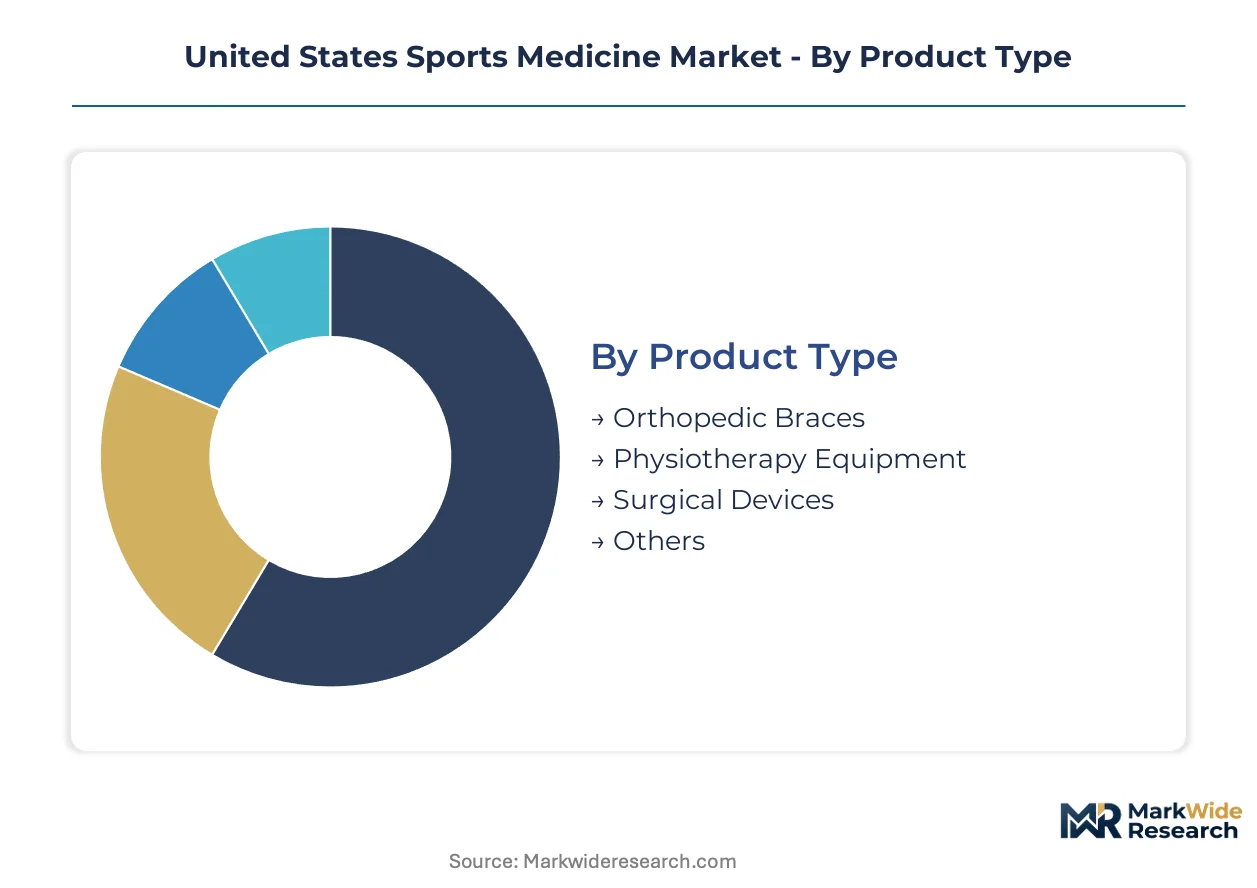
Sports medicine procurement patterns diverge sharply between institutional buyers with capital budgets and individual consumers paying out-of-pocket. Device specifications, reimbursement pathways, and end-user training requirements create distinct commercial segments with separate pricing architectures and distribution channels.
Product Type:
Material composition and regulatory classification determine reimbursement eligibility and sales cycle length across hardware categories.
- Surgical Devices:Bioresorbable anchors and knotless suture constructs dominate tendon reattachment procedures. Demand concentrates in ambulatory surgical centers across Texas and Florida where CMS reimbursement rebalancing has expanded site eligibility for arthroscopic hardware.
- Orthopedic Braces:Rigid and soft-shell designs for joint stabilization command established volume pools through durable medical equipment suppliers. California health systems negotiate bundled contracts for post-operative bracing alongside surgical devices.
- Physiotherapy Equipment:Continuous passive motion machines and electrical stimulation devices support rehabilitation protocols in collegiate athletic departments.
- Others:Compression garments and cryotherapy systems serve training room applications without implantable device regulatory burden.
Mature deployment sits with orthopedic braces through established DME channels. Newer deployment is concentrated in surgical devices as bioresorbable materials displace permanent metal hardware in younger athlete populations.
End User:
Procurement authority and budget scale separate institutional buyers from individual consumers in equipment distribution.
- Athletes:Professional franchise medical staffs and NCAA Division I programs deploy continuous kinematic monitoring for load management. Texas and California training facilities represent the densest concentration of capital equipment orders for preventive care systems.
- Coaches:Staff at Division II and III universities lack full-time sports medicine infrastructure, creating demand for equipment-as-a-service models with reduced upfront capital requirements.
- Fitness Enthusiasts:Direct-to-consumer wearable sales bypass clinical reimbursement pathways entirely.
- Recreational Sports Participants:Retail channel purchases of braces and compression sleeves depend on out-of-pocket spending without insurance coverage.
Institutional procurement dominates revenue concentration among athletes and coaches. Individual consumer segments are expanding most quickly through direct-to-consumer wearable channels.
Application:
Clinical evidence requirements and reimbursement codes shape investment priority across use cases.
- Rehabilitation:Post-surgical protocols and injury recovery programs draw sustained investment from professional franchise medical staffs. CMS national coverage determinations for continuous passive motion therapy anchor reimbursement stability.
- Injury Prevention:Pre-season screening and load management systems gain validation through NCAA athletic department deployments. FDA 510(k) clearance streamlining for wearable monitoring devices compresses commercialization timelines for biomechanical analytics platforms.
- Performance Enhancement:Training optimization tools face limited insurance reimbursement, constraining market to institutional and consumer-paid segments.
- Nutrition:Supplementation and metabolic monitoring sit outside device regulatory pathways, with distinct competitive dynamics from hardware segments.
Established reimbursement infrastructure supports rehabilitation applications. Injury prevention is gaining share fastest as continuous monitoring technology achieves clinical validation and procurement integration.
Technology:
Regulatory classification uncertainty creates friction between validated hardware and evolving software platforms.
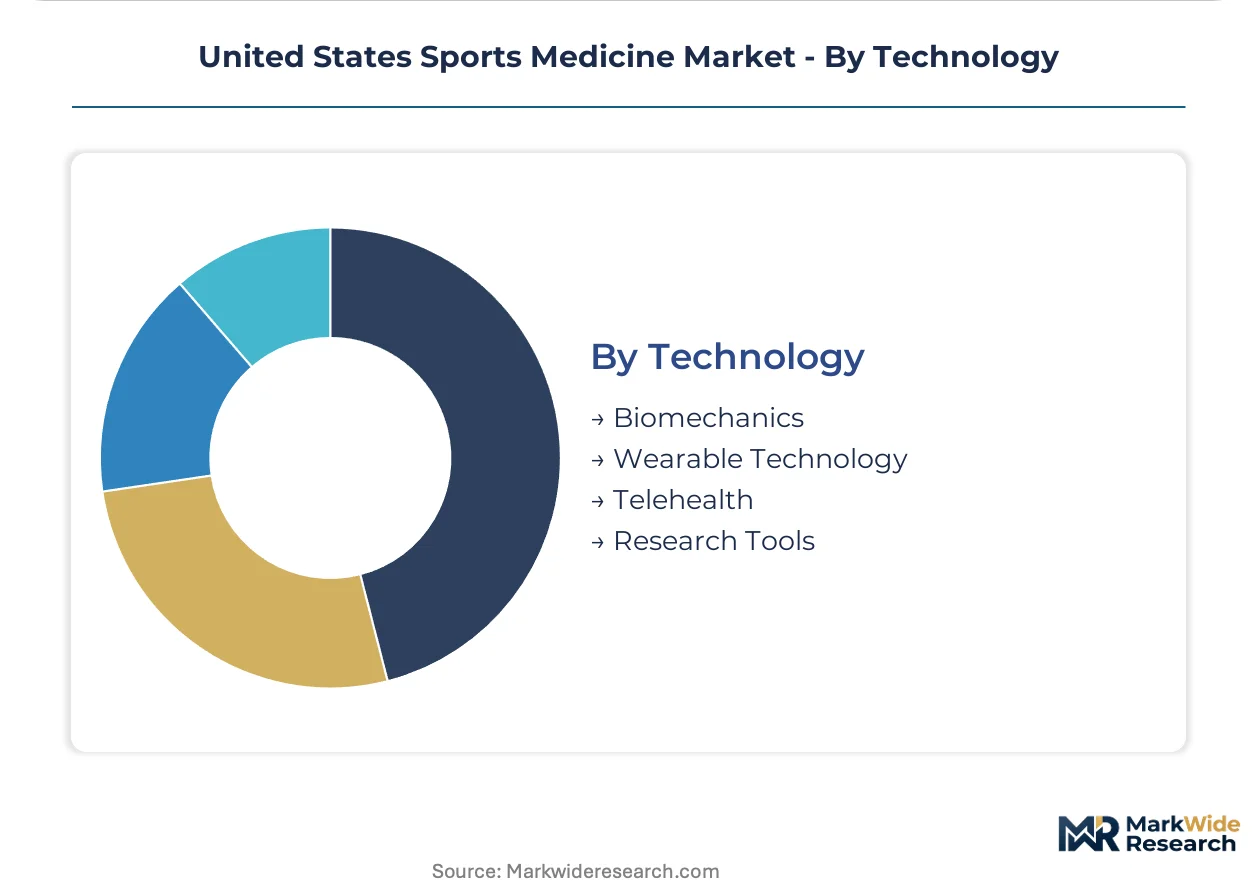
- Wearable Technology:Smart textile sensors and inertial measurement units integrated into compression garments enable real-time motion capture. NBA franchise medical staffs and NCAA Division I programs deploy these systems for fatigue prediction and tissue stress quantification.
- Biomechanics:Motion capture laboratories and gait analysis systems serve pre-operative planning and post-operative assessment in major health system sports medicine centers.
- Telehealth:Remote rehabilitation monitoring expanded adoption during care delivery disruptions, though reimbursement permanence remains under CMS review.
- Research Tools:Investigational devices and protocol-specific equipment serve academic medical centers with limited commercial scale.
Hardware-centric biomechanics platforms represent mature deployment in academic medical centers. Wearable technology is climbing the fastest as FDA software-as-medical-device guidance stabilizes and health systems integrate continuous kinematic data into care pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Triangle cities anchor United States sports medicine equipment procurement, with Dallas-Fort Worth, Houston, and Austin training facilities generating concentrated orders for preventive care systems and arthroscopic devices.
California
NCAA Division I athletic departments across Los Angeles, the Bay Area, and San Diego deploy continuous kinematic monitoring for load management. FDA 510(k) clearance streamlining accelerates wearable device commercialization from Silicon Valley developers. Stanford and UCLA medical centers integrate biomechanical data into orthopedic surgery planning.
Texas
Professional franchise medical staffs in Houston and Dallas-Fort Worth expand capital budgets for injury prevention equipment. State athletic training licensure boards govern scope-of-practice rules permitting advanced diagnostic equipment operation. Austin and San Antonio ambulatory surgical centers absorb CMS reimbursement rebalancing for arthroscopic procedures.
Florida
Spring training facilities and collegiate athletic programs in Tampa Bay, Orlando, and Miami drive orthopedic brace and rehabilitation equipment orders. CMS national coverage determinations for continuous passive motion therapy stabilize reimbursement for post-surgical protocols. Jacksonville health systems negotiate bundled contracts for surgical devices and post-operative bracing.
New York Metro
Academic medical centers in Manhattan and Long Island serve as validation sites for bioresorbable implant innovation. State-level athletic training licensure expansion permits qualified trainers to operate portable imaging systems. Greater Boston corridor specialists compete for arthroscopy fellowship talent through equipment exclusivity arrangements.
Southeast
Atlanta and Charlotte health networks build dedicated sports medicine service lines with componentized vendor agreements. Conservative management protocols including platelet-rich plasma injections delay surgical intervention in partial ligament tears. Nashville and Raleigh-Durham rehabilitation centers draw investment from professional franchise medical staffs.
United States Sports Medicine Market Key Industry Players
The competitive structure tilts toward diversified orthopedic conglomerates with integrated operating room platforms. Market concentration remains moderate, with three to five major players commanding significant health system contract volume alongside specialized regional distributors. Strategic archetypes include full-service orthopedic conglomerates, specialized arthroscopy device manufacturers, and rehabilitation-focused equipment suppliers. Dominant competitive moves encompass M&A activity targeting motion analysis capabilities and service contract unbundling to capture maintenance and training revenue separately.
Among diversified orthopedic conglomerates, Stryker, Smith & Nephew plc, and Arthrex, Inc. exemplify contrasting market positions. Stryker represents the integrated platform archetype with sustained service contracts across major health systems. Smith & Nephew plc occupies a position emphasizing cartilage repair portfolios and sports trauma hardware differentiation. Arthrex, Inc. anchors the specialized distributor network model, with regional coverage concentrated in the Southwest and Southeast through surgeon training-focused arrangements.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Smith & Nephew plc |
| Stryker |
| Zimmer Biomet Holdings, Inc. |
| CONMED Corporation |
| DePuy Synthes |
| Johnson & Johnson Services, Inc. |
| Enovis Corp |
| Orthofix Medical Inc. |
| Others |
Cost & Logistics Intelligence
Medical-grade PLA and PGA resin contracts reset quarterly, feeding through bioresorbable anchor manufacturers in Texas and California to tiered hospital procurement brackets downstream. Specialty polymer price volatility compresses margins at the mid-tier while premium integrated platforms maintain pricing power through service bundling.
Pricing Analysis
Outcome-based contracts anchored to arthroscopic procedure throughput dominate health system negotiations. Three-tier pricing structure across premium integrated platforms, standard surgical hardware, and economy DME braces reflects FDA clearance tier and surgeon training depth. Cost compression in the mid-tier intensifies as bioresorbable polymer feedstock contracts reprice. Division II and III athletic departments exhibit highest price sensitivity; major health systems with dedicated sports medicine service lines demonstrate lowest sensitivity due to bundled value capture.
Supply Chain Analysis
Bioresorbable polymer feedstock rests on German and Japanese specialty chemical producers with limited qualified medical-grade suppliers. Surgical device manufacturers draw from Taiwan for precision-machined instrumentation and domestic US sources for sterile packaging. Single-source vulnerability concentrates in medical-grade PGA resin where FDA master file documentation creates switching barriers. Distribution runs through specialized orthopedic distributors in the Southwest and Southeast, with direct-to-hospital contracts expanding in California and Texas health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance requirements function as a cost-of-compliance moat, filtering out undercapitalized entrants while rewarding established players with predicate device portfolios. CMS national coverage determination processes create additional barrier-to-entry protection for implantable device categories.
For Market Incumbents: Extend service contract unbundling to capture maintenance and clinical training revenue separately from hardware sales. Deepen backward integration into bioresorbable polymer compounding to insulate margins from feedstock volatility. Consolidate distributor relationships in the Southeast where Arthrex's surgeon-training network faces fragmentation pressure from health system procurement centralization. For New Entrants and Emerging Players: The premium-to-economy price gap in wearable monitoring devices creates entry space for software-native developers with predetermined change control plans for algorithm updates. Target Division II and III collegiate athletic departments with equipment-as-a-service models that eliminate upfront capital barriers. Pursue FDA 510(k) clearance for biomechanical analytics platforms before incumbent orthopedic manufacturers complete motion analysis acquisitions. For Investors and Strategic Acquirers: FDA guidance finalization on software-as-medical-device classifications is the leading indicator that valuation multiples for AI-enabled motion analysis tools will compress toward hardware comparables. Long-term viability favors platforms with integrated kinematic data streams feeding surgical planning workflows. Acquisition target archetype: mid-cap wearable developers with health system pilot contracts and established 510(k) predicates. Watch CMS reimbursement permanence for remote rehabilitation monitoring as the signal for telehealth platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate device portfolios compress clearance timelines for bioresorbable anchors in Texas ASCs. |
| Hospital System Partnership Expansion | Exclusive service contracts with California health networks lock out competing orthopedic platforms. |
| Software Companion Development | Biomechanical analytics integration with Stryker's operating room systems creates bundled value propositions. |
| Reimbursement Strategy Investment | CMS national coverage determination data packages anchor payment stability for novel implant categories. |
| CE Marking Pathway Parallel Track | European regulatory validation supports multinational health system procurement standardization. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, and biomedical engineers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement system records. Bottom-up demand modeling across ambulatory surgical centers and collegiate athletic departments triangulates with top-down orthopedic device market sizing.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions span product type, end user procurement authority, application reimbursement code, and technology regulatory classification. CAGRs derive from procedure volume trajectories, implant penetration curves, and wearable device adoption slopes. Forecast inputs incorporate athletic training licensure expansion timelines and FDA software-as-medical-device guidance evolution.
Underlying measurement precision varies by segment; surgical device revenue pools carry tighter precision than emerging wearable technology estimates. Forecasts reflect documented assumptions regarding CMS reimbursement stability and bioresorbable material adoption curves. Regulatory guidance delays, polymer supply disruptions, and conservative management substitution by platelet-rich plasma protocols warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Skin Cancer Therapeutics Market