
 Medical Specialty Bags Market | 2026-2036
Medical Specialty Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Specialty Bags Market Intelligence
The Medical Specialty Bags Market is consolidating around a widening gap between premium silicone-based systems and commodity PVC products. Baxter International Inc. leverages its integrated plasma fractionation network to anchor hospital-grade blood bag supply chains. Coloplast A/S differentiates through hydrocolloid-adhesive ostomy platforms that command specialized clinician loyalty. Medline Industries LP competes on distribution density, sustaining same-day replenishment contracts across North American acute care networks.
Medical specialty bags are sterile, single-use flexible containers engineered from polyvinyl chloride, polyethylene, polyurethane, or silicone resins, manufactured via extrusion blow-molding or radio-frequency welding to precise burst-strength and biocompatibility specifications; they function to contain, collect, or deliver fluids, biological specimens, or pharmaceutical agents in controlled clinical environments. IV bags lead volume within product type segmentation, though polyurethane and silicone material grades capture disproportionate margin pools due to extended dwell-time indications and reduced phthalate leaching risk. Home care end users represent the fastest-expanding demand channel, as ambulatory infusion and enteral feeding protocols shift post-acute monitoring outside hospital walls.
The FDA enforces biocompatibility and extractables testing under ISO 10993 for all blood-contacting bag surfaces, while the EU MDR mandates clinical evidence renewal for legacy Class IIa fluid management devices, tightening market access for non-compliant suppliers. Japan's PMDA imposes supplementary stability protocols on imported polyethylene IV containers, extending registration timelines for foreign manufacturers. Stakeholders must monitor evolving material substitution mandates and channel reimbursement parity between institutional and home-based administration settings.
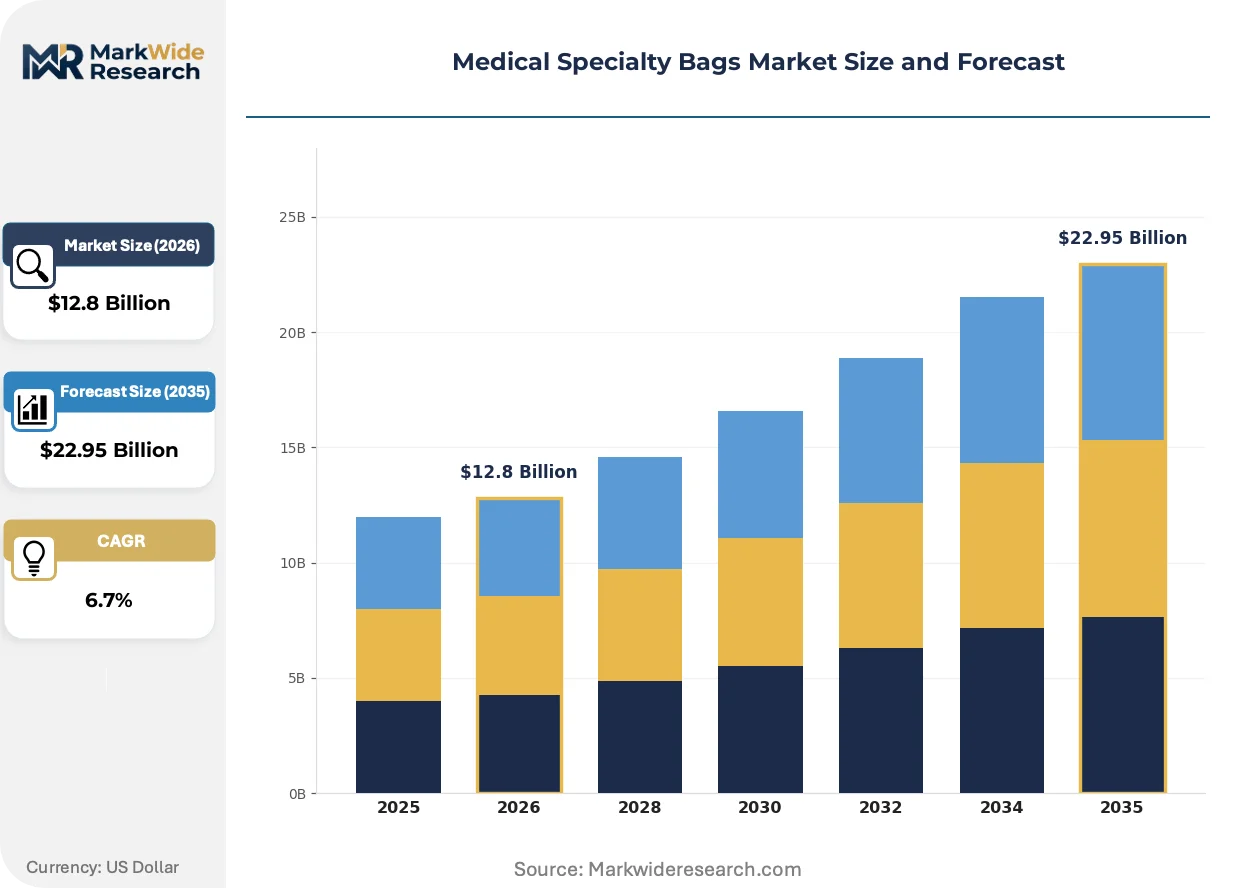
Market Dynamics
Material substitution mandates are compressing PVC's dominance as silicone and polyurethane formulations capture extended-dwell applications, while home care channel expansion reconfigures distribution economics away from hospital-centric replenishment models.
Growth Catalysts
- EU MDR clinical evidence requirements:Legacy Class IIa fluid management devices face renewal deadlines, accelerating compliance-driven replacement cycles among European hospital systems.
- Home care infusion protocols:Post-acute monitoring outside institutional walls is expanding portable drainage and enteral feeding system deployments.
- Japan's PMDA stability protocols:Extended registration timelines for imported polyethylene IV containers are prompting domestic manufacturing partnerships.
Market Restraints
- Specialized resin supply concentration:Medical-grade silicone precursor production clusters in Northeast Asian chemical corridors, exposing buyers to geographic disruption risk.
- ISO 10993 testing cost escalation:Extractables and biocompatibility validation for blood-contacting surfaces extends product development timelines by 12-18 months.
- Alternative container formats:Rigid bottle systems and closed-transfer devices are displacing flexible bags in select oncology compounding applications.
Strategic Opportunities
- German outpatient reimbursement parity:Home-based parenteral nutrition administration now carries equivalent coding to institutional infusion, unlocking ambulatory demand.
- RF welding automation convergence:Radio-frequency sealing technology is integrating with inline vision inspection to reduce particulate contamination in high-volume lines.
- United States chronic wound drainage:Negative pressure wound therapy expansion into long-term care facilities creates underpenetrated channel potential.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with medical-grade extrusion expertise command premium compensation, constraining R&D scaling.
- Legacy ERP integration friction:Track-and-trace serialization requirements are forcing replacement of obsolete manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Specialty Bags Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Bags, Blood Bags, Urine Bags, Surgical Bags Material: Polyvinyl Chloride, Polyethylene, Polyurethane, Silicone End User: Hospitals, Clinics, Home Care, Laboratories Application: Fluid Therapy, Waste Management, Drug Delivery, Emergency Care |
| Companies Covered | Terumo Corporation, Coloplast A/S, Baxter International Inc., Hollister Incorporated, ConvaTec Group PLC, B. Braun Melsungen AG, ICU Medical Inc., Medline Industries LP, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Specialty Bags Market Strategic Shifts & Innovations
Active material science advancement is collapsing the performance gap between established PVC formulations and next-generation alternatives, while regulatory pressure on phthalate leaching accelerates validation timelines for novel elastomer platforms.
Multi-layer coextrusion barrier technology is converging with ethylene vinyl alcohol interlayers to extend drug stability in parenteral containers beyond 24-month shelf life targets. Specialty pharmaceutical manufacturers are adopting these platforms for biologic formulations requiring oxygen and moisture protection. The convergence is compressing commodity PVC's addressable market in high-value infusion applications.
FDA's updated biocompatibility guidance for PVC alternatives is mandating expanded cytotoxicity and sensitization testing for all new bag submissions. Device manufacturers are restructuring quality assurance departments to accommodate parallel ISO 10993 and USP Class VI validation tracks. Blood bag producers face the steepest compliance burden given direct erythrocyte contact requirements.
Consolidated purchasing by United States hospital networks is displacing fragmented distributor relationships with direct manufacturer contracts tied to utilization guarantees. Integrated delivery networks in Texas and Florida are negotiating multi-year enteral feeding supply agreements with penalty clauses for stockout events. This concentration is visible most acutely in regions where health system mergers have reduced independent acute care facilities below 15% of bed capacity.
Medical Specialty Bags Market Segmentation
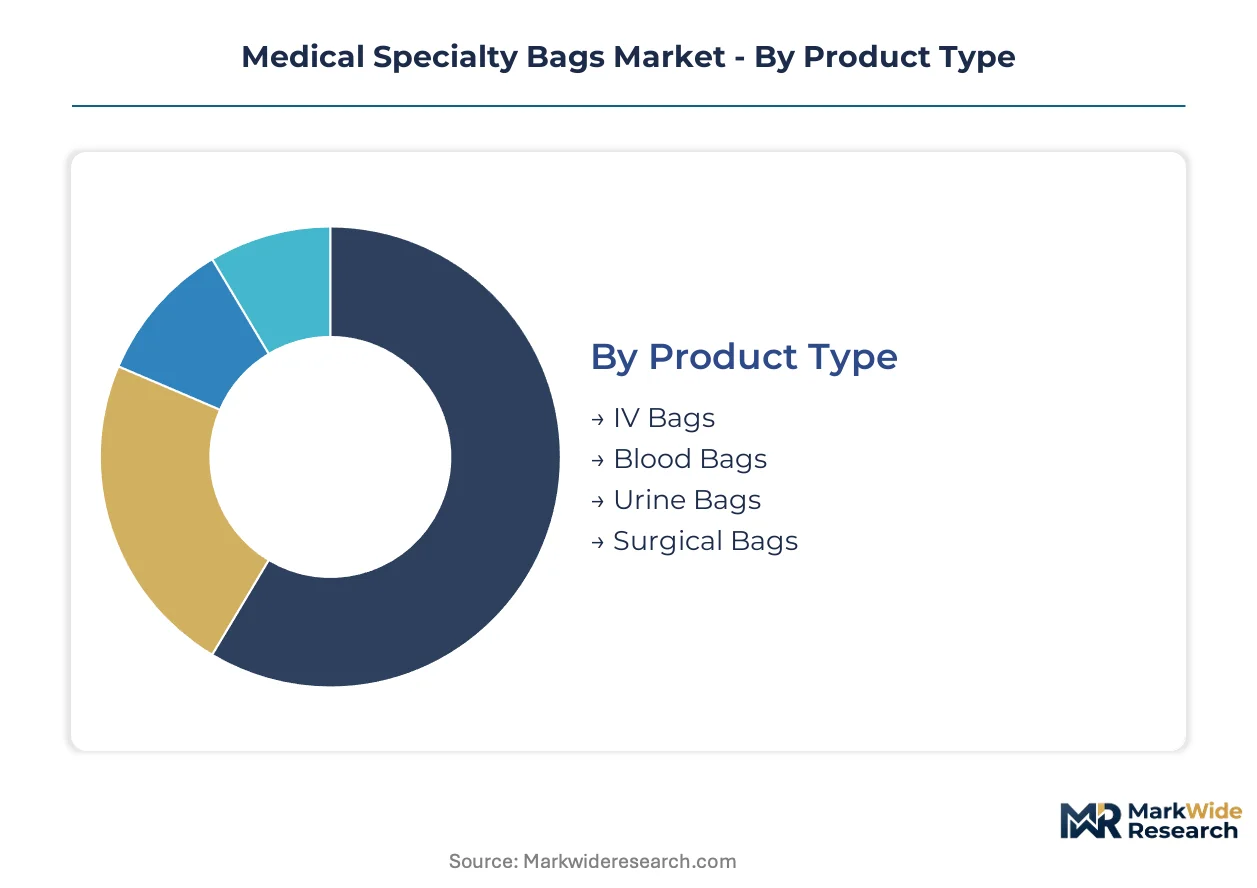
Medical specialty bags fragment across four critical dimensions that determine pricing power, regulatory burden, and channel access. Material chemistry and end-use setting together dictate margin structure, while product format and application define volume concentration.
Product Type:
Supply concentration in resin-grade extrusion capacity favors high-volume formats with standardized burst-strength specifications.
- IV Bags:Multi-chamber parenteral nutrition containers and large-volume crystalloid reservoirs dominate hospital procurement. United States acute care networks are consolidating annual contracts around utilization guarantees for these high-throughput formats.
- Blood Bags:Triple-bag systems with integral satellite pouches require ISO 10993-4 hemocompatibility validation and direct erythrocyte contact testing. Japanese domestic manufacturers leverage PMDA stability protocol familiarity to defend share against imports.
- Urine Bags:Drainage systems with anti-reflux valves serve post-operative and long-term care populations.
- Surgical Bags:Specimen collection and irrigation reservoirs support operating room fluid management.
Today's leader: IV Bags. Tomorrow's challenger: Blood Bags.
Material:
Cost tiers separate legacy commodity formulations from premium elastomer platforms commanding extended-dwell indications.
- Polyvinyl Chloride:Plasticized PVC retains volume leadership in standard infusion and drainage applications despite phthalate leaching scrutiny. German hospital systems are accelerating replacement timelines ahead of REACH substance restriction deadlines.
- Silicone:Platinum-cured elastomer formulations enable 30-day indwelling catheter compatibility and reduced protein adhesion. Home care parenteral nutrition patients in the United States drive disproportionate demand for these high-durability platforms.
- Polyethylene:Linear low-density grades serve irrigation and waste containment with lower extractables profiles.
- Polyurethane:Thermoplastic aromatic and aliphatic grades balance chemical resistance with kink resistance for ambulatory infusion.
Silicone and polyurethane together are climbing the fastest as substitution mandates compress PVC's addressable market.
End User:
Customer type determines distribution economics, with channel migration toward non-institutional settings reconfiguring replenishment models.
- Home Care:Portable enteral feeding and drainage systems require compact, tamper-evident packaging with patient-directed labeling. German outpatient reimbursement parity now codes home-based parenteral nutrition equivalently to institutional infusion, accelerating ambulatory deployment.
- Hospitals:Integrated delivery networks in Texas and Florida negotiate multi-year supply agreements with stockout penalty clauses, concentrating purchasing power among fewer decision-makers.
- Clinics:Outpatient surgical centers demand single-procedure kits with pre-connected components.
- Laboratories:Biorepository and specimen transport bags require temperature stability validation.
Home Care is gaining share fastest as post-acute monitoring protocols shift outside institutional walls.
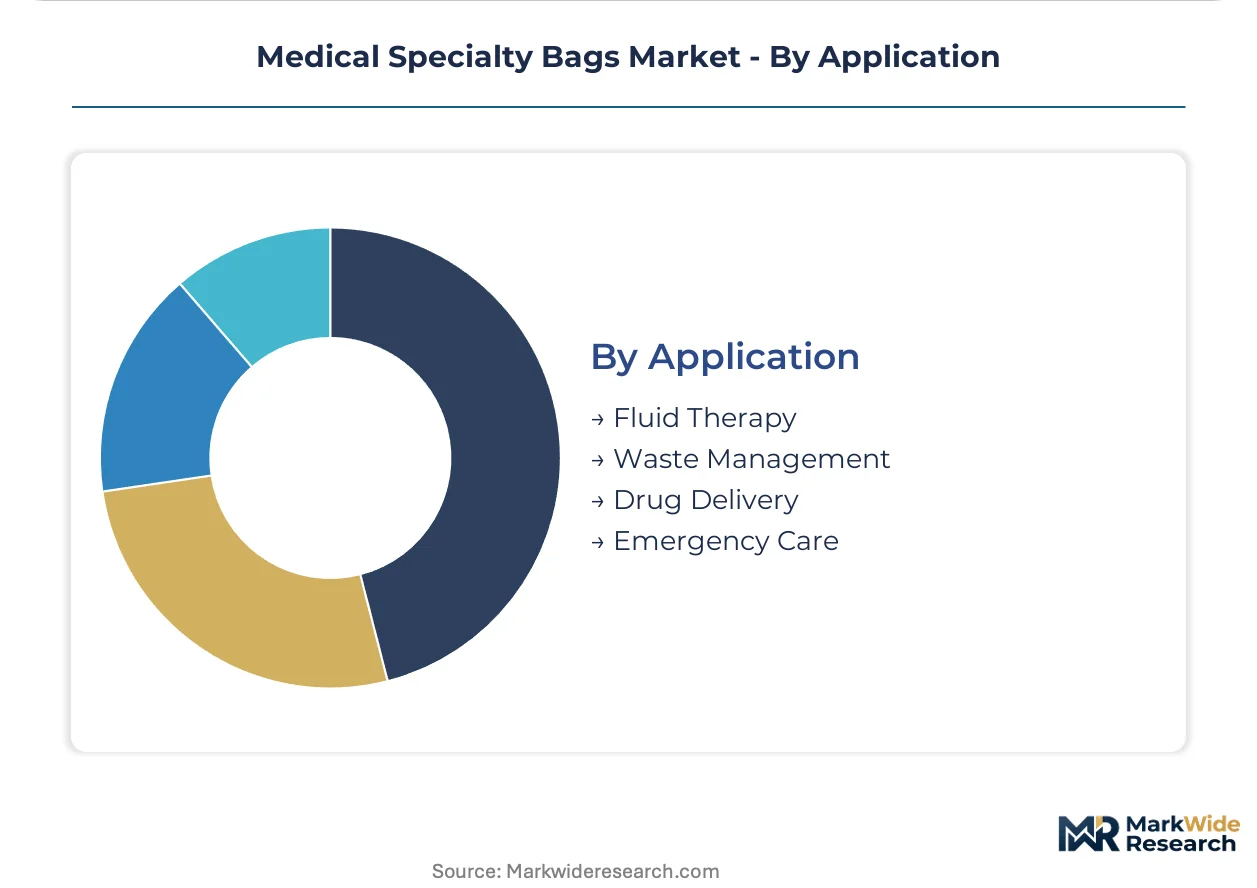
Application:
Application segmentation maps directly to clinical workflow integration and reimbursement coding specificity.
- Fluid Therapy:Volume resuscitation and maintenance electrolyte administration represent the highest-throughput use case. United States emergency departments drive seasonal demand spikes for large-volume crystalloid containers.
- Drug Delivery:Oncology compounding and biologic infusion require oxygen-barrier multi-layer coextrusion with ethylene vinyl alcohol interlayers. Specialty pharmaceutical manufacturers are adopting these platforms for 24-month shelf life targets.
- Waste Management:Suction canisters and infectious material containment support infection control protocols.
- Emergency Care:Pre-hospital trauma and disaster response kits demand ruggedized, temperature-stable construction.
Drug Delivery carries the steepest margin expansion trajectory as biologic formulation complexity escalates barrier requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer formulation chemists and medical-grade extrusion specialists cluster in Germany's Rhine-Ruhr corridor, Japan's Kansai industrial belt, and the United States' upper Midwest manufacturing corridor. These talent concentrations anchor regional production capabilities and shape material innovation pipelines.
United States
Integrated delivery networks in Texas and Florida negotiate multi-year enteral feeding supply agreements with stockout penalty clauses, concentrating purchasing power among fewer hospital system decision-makers. FDA biocompatibility guidance for PVC alternatives mandates expanded cytotoxicity testing for all new bag submissions. The upper Midwest corridor hosts blow-molding and RF welding operations serving domestic acute care networks.
Germany
Hospital systems accelerate replacement timelines for plasticized PVC ahead of ECHA REACH substance restriction deadlines, driving silicone and polyurethane transitions. EU MDR clinical evidence renewal requirements for legacy Class IIa fluid management devices compress compliance timelines. The Rhine-Ruhr corridor anchors medical-grade silicone precursor formulation and extrusion capacity.
Japan
Domestic manufacturers leverage PMDA stability protocol familiarity to defend blood bag market share against imported polyethylene IV containers. METI industrial policy supports local production of platinum-cured elastomer platforms for extended-dwell applications. The Kansai belt concentrates RF welding automation and vision inspection system integration.
China
Northeast Asian chemical corridors host medical-grade silicone precursor production, exposing global buyers to geographic concentration risk. NMPA registration pathways for imported blood-contacting devices extend validation timelines. The Yangtze River Delta clusters multi-layer coextrusion barrier technology development for oxygen-sensitive biologic formulations.
India
CDSCO regulatory harmonization with ISO 10993 standards accelerates domestic validation capabilities for extractables and leachables testing. Hospital procurement centralization in Maharashtra and Karnataka drives volume consolidation toward standardized IV bag specifications. The Mumbai-Pune corridor attracts contract manufacturing for European and North American device firms seeking cost-advantaged production.
Medical Specialty Bags Market Key Industry Players
Top-tier vendors anchor hospital-grade supply chains with integrated plasma fractionation networks, while mid-tier specialists compete on material science differentiation and regional distribution density. The market structures around three archetypes: integrated multinational device conglomerates with captive resin supply, regional fabricators with specialized clinician relationships, and private-label distributors leveraging same-day replenishment contracts. M&A activity targets silicone formulation capabilities, while capacity expansion concentrates on RF welding automation with inline vision inspection.
Among integrated multinational conglomerates, Baxter International Inc., Coloplast A/S, and B. Braun Melsungen AG exemplify divergent strategic positions. Baxter represents the plasma supply chain-anchored archetype with fractionation-integrated blood bag operations. Coloplast occupies a position within specialized clinician loyalty models through hydrocolloid-adhesive platforms. B. Braun sits within the European hospital-system contracting archetype with broad infusion therapy portfolios.
| Leading Market Players |
|---|
| Terumo Corporation |
| Coloplast A/S |
| Baxter International Inc. |
| Hollister Incorporated |
| ConvaTec Group PLC |
| B. Braun Melsungen AG |
| ICU Medical Inc. |
| Medline Industries LP |
| Fresenius Kabi AG |
| Others |
Cost & Logistics Intelligence
Polymer formulation chemists with medical-grade extrusion expertise cluster in Germany's Rhine-Ruhr corridor and Japan's Kansai belt, creating labor-cost differentials that widen pricing-tier spreads between premium silicone platforms and commodity PVC alternatives. These talent concentrations anchor three-tier pricing structure across premium, standard, and economy levels, with platinum-cured elastomer commands reflecting scarcity premiums against plasticized resin grades.
Pricing Analysis
Bundled service contracts with stockout penalty clauses dominate hospital procurement, while unbundled per-unit transactions persist in home care channels. Price differentiation separates ISO 10993-4 validated blood bags from standard drainage formats, with FDA biocompatibility tier certification commanding 15-40% premiums. Pricing pressure stems from REACH substance restriction deadlines accelerating PVC replacement timelines. Integrated delivery networks exhibit lowest price sensitivity; independent long-term care facilities face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade silicone precursor production clustering in Northeast Asian chemical corridors, exposing buyers to geographic disruption risk. Raw material dependencies center on platinum-cured elastomer formulations, ethylene vinyl oxygen-barrier interlayers, and pharmaceutical-grade polyethylene resins. Tariff exposure on imported IV containers extends registration timelines under Japan's PMDA stability protocols. Distribution runs through integrated delivery network direct contracts, displacing fragmented distributor relationships in United States acute care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical specialty bags rests on material substitution economics, as silicone and polyurethane platforms capture extended-dwell indications while PVC replacement cycles compress development cost bases.
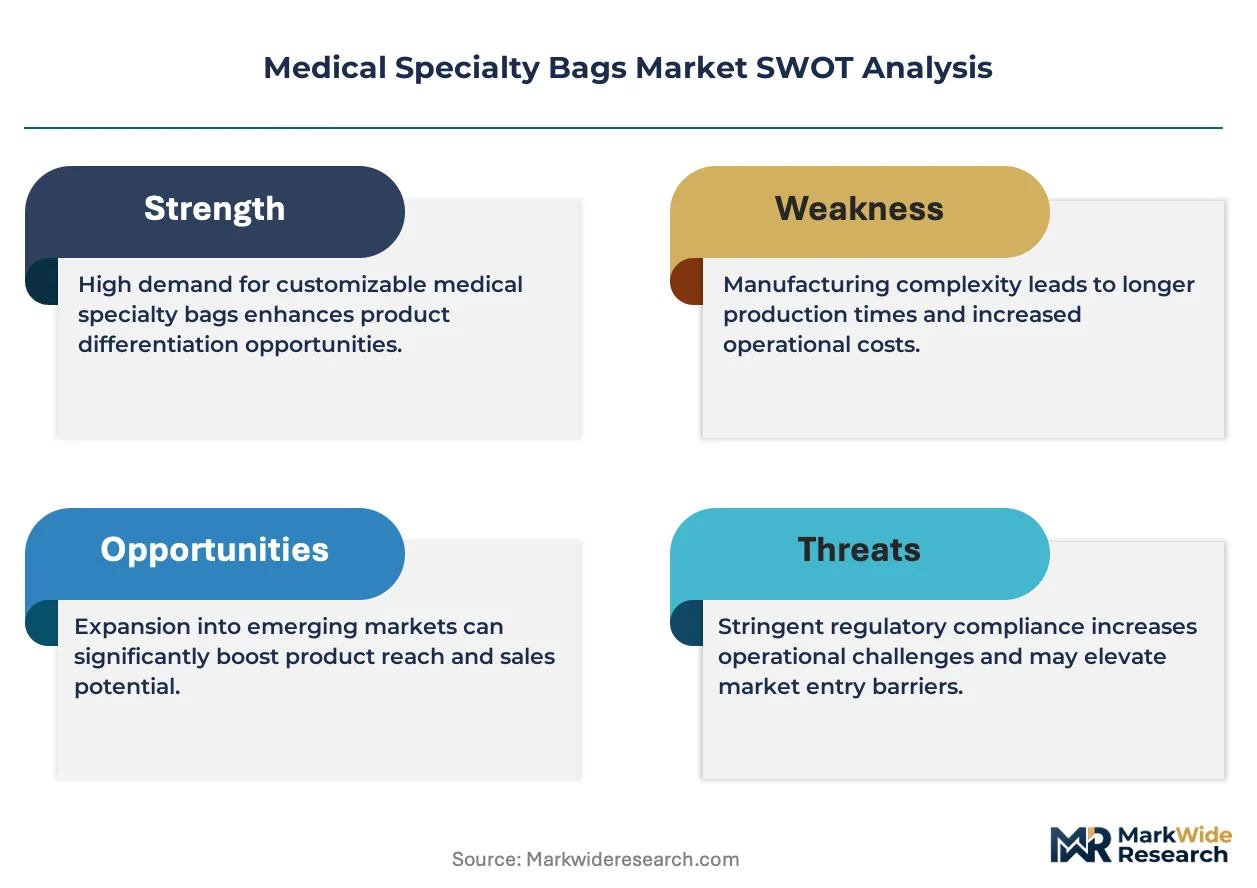
For Market Incumbents: Deploy RF welding automation with inline vision inspection to reduce particulate contamination and defend hospital-grade supply positions. Secure backward integration into medical-grade silicone precursor formulation to offset Northeast Asian supply concentration. Accelerate ISO 10993-4 hemocompatibility validation pipelines ahead of EU MDR renewal deadlines for legacy Class IIa devices. For New Entrants and Emerging Players: Home care distributors represent the most penetrable channel partner type for ambulatory enteral feeding and portable drainage systems. Target German outpatient reimbursement parity codes for home-based parenteral nutrition administration, now equivalent to institutional infusion. Pursue private-label contracts with same-day replenishment service levels to bypass consolidated hospital purchasing committees. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with specialized clinician relationships in ostomy and wound drainage segments. Five-to-ten year viability favors silicone formulation capabilities with platinum-curing expertise and PMDA registration familiarity. Monitor RF welding automation convergence rates as inflection indicator for manufacturing scale efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| RF Welding Automation Deployment | Inline vision inspection integration reduces particulate contamination in high-volume medical bag lines. |
| Silicone Formulation Backward Integration | Captive precursor supply mitigates geographic concentration risk in Northeast Asian chemical corridors. |
| EU MDR Clinical Evidence Renewal | Accelerated compliance timelines for legacy Class IIa fluid management devices compress replacement cycles. |
| Home Care Channel Partnership | German outpatient reimbursement parity unlocks ambulatory parenteral nutrition demand outside institutional walls. |
| PMDA Stability Protocol Registration | Domestic Japanese manufacturing partnerships defend blood bag share against extended import validation timelines. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market cluster combining interviews with polymer formulation chemists, hospital GPO contracts managers, biomedical engineers, and home care equipment distributors. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, PMDA submission databases, and hospital procurement contract registries. Bottom-up volume modeling triangulates against top-down expenditure estimates across material chemistry and end-use setting dimensions.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon, with segmentation modeling spanning product format, material grade, end-user channel, and application indication. CAGRs derive from fitted trend analysis incorporating regulatory compliance timelines, reimbursement code parity events, and channel migration patterns. Industry-specific inputs include ISO 10993 testing duration assumptions and RF welding automation adoption curves.
Revisions become necessary when REACH substance restriction deadlines accelerate, PMDA stability protocols extend, or home care reimbursement parity codes expand beyond German precedent. Forecasts reflect documented assumptions on material substitution elasticities and hospital purchasing consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Global Medical Mask Market