
 Bipolar Disorder (BPD) Market | 2026-2036
Bipolar Disorder (BPD) Market Size, Share, and Industry Trends Forecast 2026-2036
Bipolar Disorder (BPD) Market Outlook
North American pharmaceutical manufacturing capacity for psychiatric APIs is consolidating around specialized fermentation and synthesis hubs. Johnson & Johnson leverages its Janssen division's long-standing presence in atypical antipsychotics to sustain formulation leadership. Eli Lilly and Company anchors its position through R&D intensity in mood disorder pipelines. AstraZeneca competes by extending its Seroquel franchise into depot formulations across European and Asian markets.
Bipolar disorder comprises recurrent episodes of mania, hypomania, and depression requiring pharmacologic stabilization of neurotransmitter systems, primarily through modulation of dopamine, serotonin, and glutamate pathways. Atypical antipsychotics and lithium salts constitute the backbone of acute and maintenance protocols, with oral tablets dominating initial therapy and long-acting injectables gaining traction in non-adherent populations. Among delivery modes, injectable formulations represent the fastest-growing segment as healthcare systems prioritize medication adherence in severe cases. Hospitals retain the largest patient volume for acute mania admissions, though outpatient clinics capture expanding margin pools through maintenance therapy management.
FDA's Risk Evaluation and Mitigation Strategies and EMA's pharmacovigilance obligations shape clinical trial design and post-market surveillance requirements for all new BPD entrants. The EU's Medical Device Regulation and impending AI Act will govern digital therapeutics and algorithm-based diagnostic aids entering bipolar treatment workflows. Stakeholders must monitor how FDA's emerging guidance on digital biomarkers and real-world evidence intersects with payer demands for outcomes-based contracts in maintenance therapy.
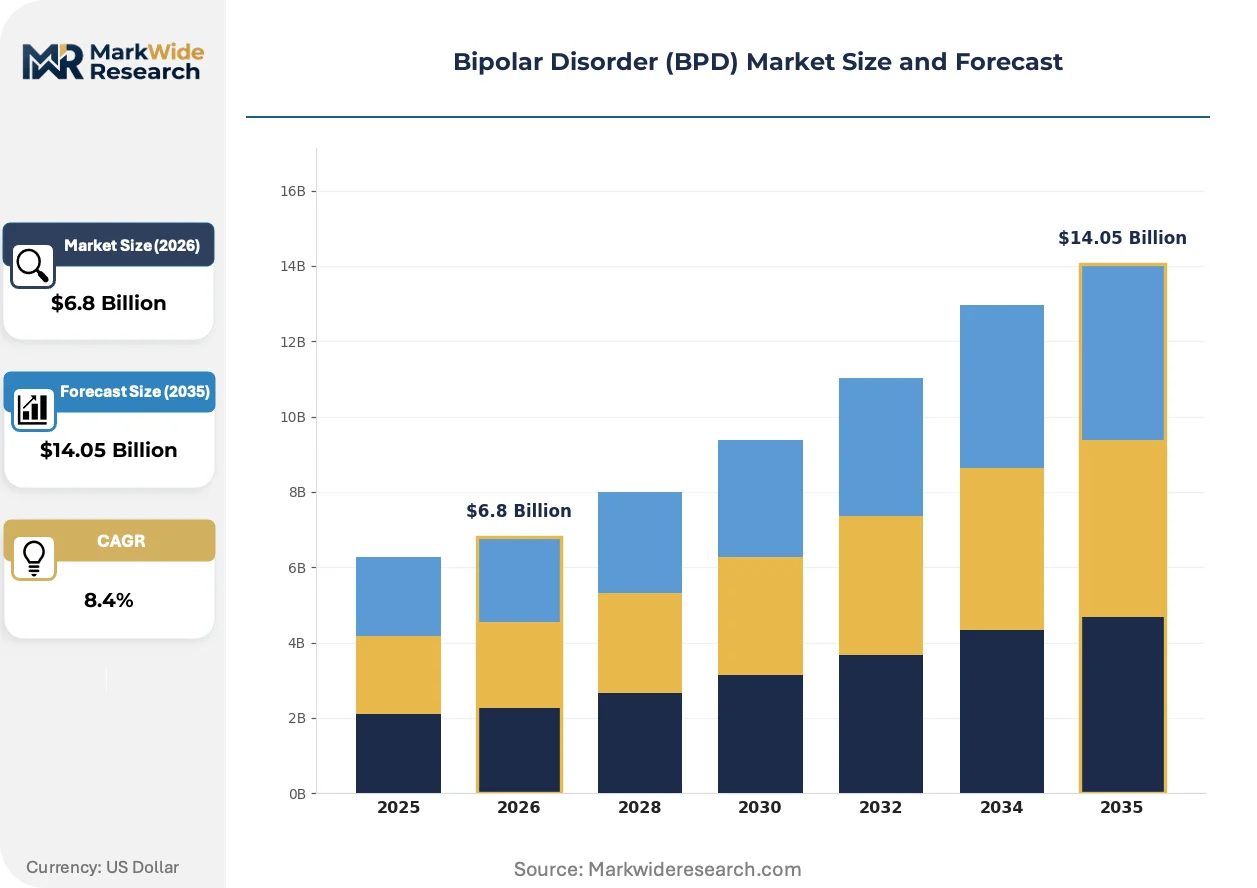
Market Dynamics
Maintenance therapy protocols are shifting from hospital-centric acute care toward outpatient long-term management, restructuring reimbursement flows and formulation priorities across psychiatric pharmaceutical supply chains.
Growth Catalysts
- FDA Risk Evaluation and Mitigation Strategies:These frameworks mandate rigorous post-market surveillance for mood stabilizers, elevating data quality standards that accelerate payer confidence in novel formulations.
- Long-acting injectables:These delivery systems address adherence failures in severe bipolar cases, with healthcare systems in Germany and Japan prioritizing depot antipsychotic coverage in maintenance protocols.
- Digital biomarker integration:Smartphone-based mood monitoring and sleep-wake cycle tracking are converging with pharmacologic protocols to enable preemptive intervention before manic or depressive episode onset.
Market Restraints
- Lithium carbonate supply concentration:Chilean and Australian brine extraction operations dominate active pharmaceutical ingredient sourcing, exposing formulation networks to geopolitical and climate-related disruption.
- EMA pharmacovigilance documentation burdens:Post-authorization safety study requirements for atypical antipsychotics extend time-to-market for depot formulations by 18-24 months relative to oral equivalents.
- Generic erosion of Seroquel IR:Immediate-release quetiapine faces commoditization across European markets, compressing margin pools available for innovative formulation R&D.
Strategic Opportunities
- Underpenetrated Japanese maintenance therapy:Cultural stigma surrounding chronic psychiatric medication creates latent demand for discreet depot formulations administered at extended intervals.
- Real-world evidence contracting:Outcome-based reimbursement agreements with US commercial payers reward demonstrated reductions in hospitalization frequency through adherence-optimized delivery systems.
- Digital therapeutics convergence:FDA's emerging guidance on prescription digital therapeutics creates regulatory pathway for algorithm-based cognitive behavioral adjuncts to pharmacologic stabilization.
Industry Challenges
- Specialized psychopharmacology talent scarcity:Clinical trial design for bipolar indications requires expertise in mood disorder phenotyping that outstrips current training pipeline output in the United States and Germany.
- Depot formulation manufacturing complexity:Microsphere encapsulation and crystalline suspension technologies demand capital-intensive sterile manufacturing infrastructure with limited contract manufacturing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bipolar Disorder (BPD) Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atypical Antipsychotics, Lithium, Mood Stabilizers, Antidepressants End User: Hospitals, Outpatient Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Oral, Injectable, Transdermal, Intravenous Therapy Area: Acute Mania, Hypomania, Depressive Episodes, Maintenance Treatment |
| Companies Covered | Johnson & Johnson, Eli Lilly and Company, AstraZeneca, GSK plc, Otsuka Holdings Co., Ltd., Pfizer Inc., AbbVie Inc., Bristol-Myers Squibb Company, H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bipolar Disorder (BPD) Market Strategic Shifts
Neuroscience-informed drug delivery and regulatory frameworks for digital interventions are restructuring how maintenance therapy is prescribed, monitored, and reimbursed across outpatient psychiatric care.
Pharmacogenomic testing for cytochrome P450 enzyme variants is converging with atypical antipsychotic prescribing to reduce adverse metabolic responses and treatment-resistant trajectories. US academic medical centers and specialized mood disorder clinics in Germany are integrating preemptive genotyping into intake protocols. This convergence is compressing trial-and-error medication selection cycles that previously extended 8-12 weeks.
EMA's Medical Device Regulation and impending EU AI Act are imposing conformity assessment requirements on algorithm-based diagnostic aids for bipolar spectrum identification. Device-software combination products must demonstrate clinical validity against DSM-5 criteria through prospective studies. European psychiatric service providers are responding by consolidating vendor relationships with firms possessing notified body certification experience.
Payers in the United States are unbundling medication adherence monitoring from traditional pharmacy benefit management, creating standalone reimbursement codes for remote therapeutic monitoring. This behavioral shift disrupts legacy fee-for-service psychiatry models and rewards integrated care platforms combining pharmacologic and digital interventions. The transformation is most visible in Medicare Advantage plans targeting severe mental illness populations with high historical hospitalization rates.
Bipolar Disorder (BPD) Market Segmentation
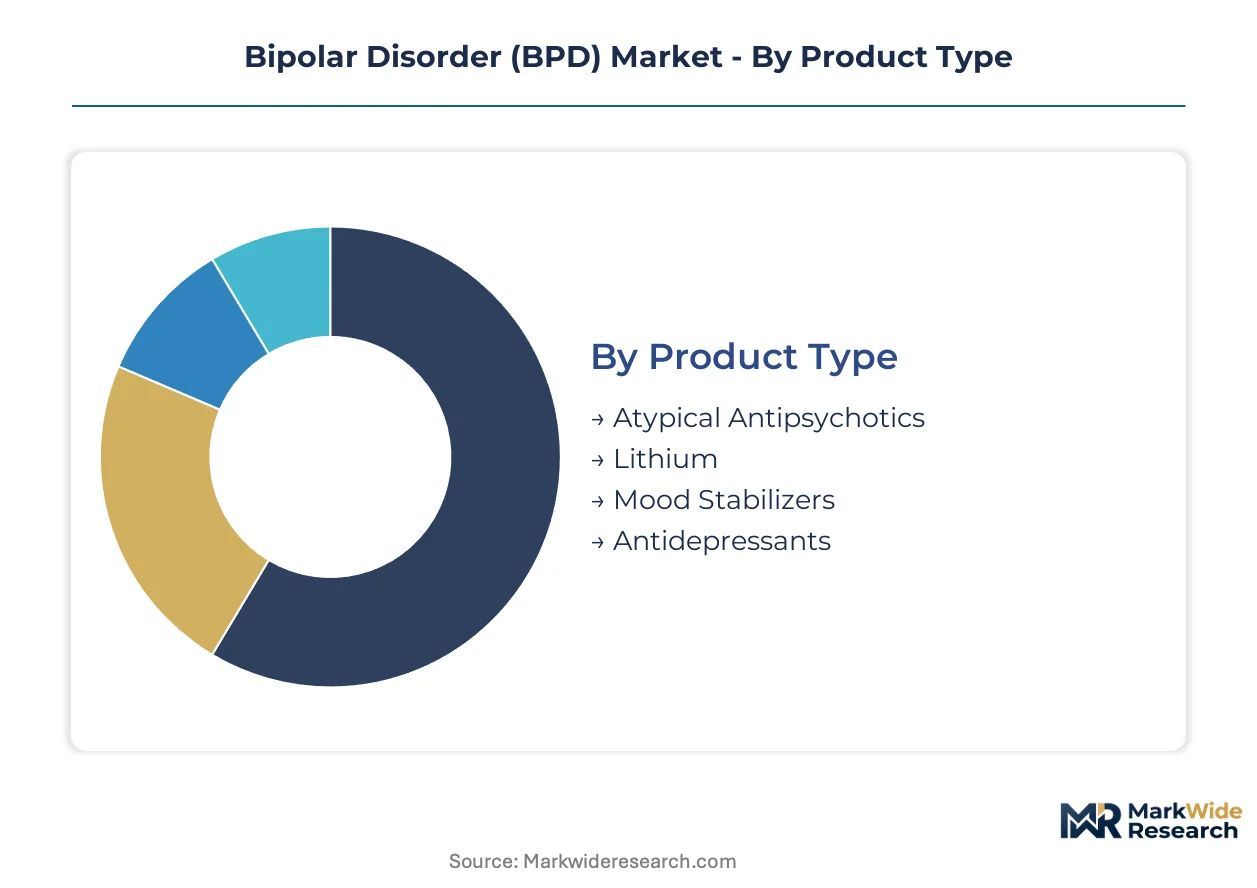
Bipolar disorder treatment markets fragment across pharmacologic classes, care settings, and delivery technologies. Each segmentation axis carries distinct capital requirements, reimbursement profiles, and adherence implications that shape competitive positioning.
Product Type:
Capital intensity varies sharply across pharmacologic categories, with fermentation-based APIs and complex synthesis pathways demanding the heaviest upfront manufacturing investment.
- Atypical Antipsychotics:Second-generation dopamine-serotonin modulators including quetiapine, olanzapine, and aripiprazole dominate acute mania protocols. US and German formulators prioritize depot extensions of established oral franchises to capture maintenance therapy adherence premiums.
- Lithium:Lithium carbonate and citrate salts remain the gold-standard mood stabilizer despite narrow therapeutic windows. Chilean and Australian brine extraction operations concentrate API sourcing, exposing formulation networks to geopolitical supply risk.
- Mood Stabilizers:Valproate and lamotrigine formulations address mixed episodes and rapid-cycling phenotypes without antipsychotic metabolic burden.
- Antidepressants:Selective serotonin reuptake inhibitors and dual-action agents carry mania induction risk, limiting their standalone use to depressive phase management with mood stabilizer co-prescription.
Most installed capacity flows through atypical antipsychotics. Expansion is steepest in lithium carbonate formulation as generic erosion compresses antipsychotic margins.
End User:
Care setting determines reimbursement velocity and formulation preference, with institutional purchasers prioritizing acute intervention and ambulatory sites capturing longitudinal margin pools.
- Hospitals:Inpatient psychiatric units manage acute mania admissions requiring rapid-acting intramuscular antipsychotics and environmental stabilization. US academic medical centers and German university hospitals anchor volume for severe episode intervention.
- Outpatient Clinics:Specialized mood disorder clinics in the United States and Japan coordinate maintenance therapy through extended-interval depot administration and pharmacogenomic-guided prescribing.
- Homecare Settings:Visiting nurse services administer long-acting injectables to mobility-limited patients, particularly in Medicare Advantage populations with severe mental illness carve-outs.
- Rehabilitation Centers:Residential and day-treatment programs bridge acute discharge to community reintegration, emphasizing adherence monitoring and psychosocial intervention.
Hospital volume still exceeds ambulatory sites in absolute patients. Outpatient clinics are climbing the fastest as maintenance therapy protocols shift beyond institutional settings.
Delivery Mode:
Route of administration directly shapes manufacturing complexity, with parenteral formulations requiring sterile infrastructure that oral tablet production avoids.
- Oral:Immediate-release and extended-release tablets dominate initial therapy initiation. German and Japanese formulators emphasize taste-masked and orally disintegrating variants for pediatric and geriatric adherence.
- Injectable:Long-acting intramuscular and subcutaneous depot formulations address non-adherence in severe recurrent cases. Microsphere encapsulation and crystalline suspension technologies demand capital-intensive sterile manufacturing with limited contract manufacturing availability.
- Transdermal:Patch-based delivery remains experimental for bipolar indications, with selegiline and rotigotine platforms adapted from Parkinson's disease applications.
- Intravenous:Rapid-onset IV formulations serve emergency department mania management where oral intake is precluded.
Oral formulations retain the deepest installed base. Injectable delivery is gaining share fastest as healthcare systems prioritize adherence in high-utilization patient cohorts.
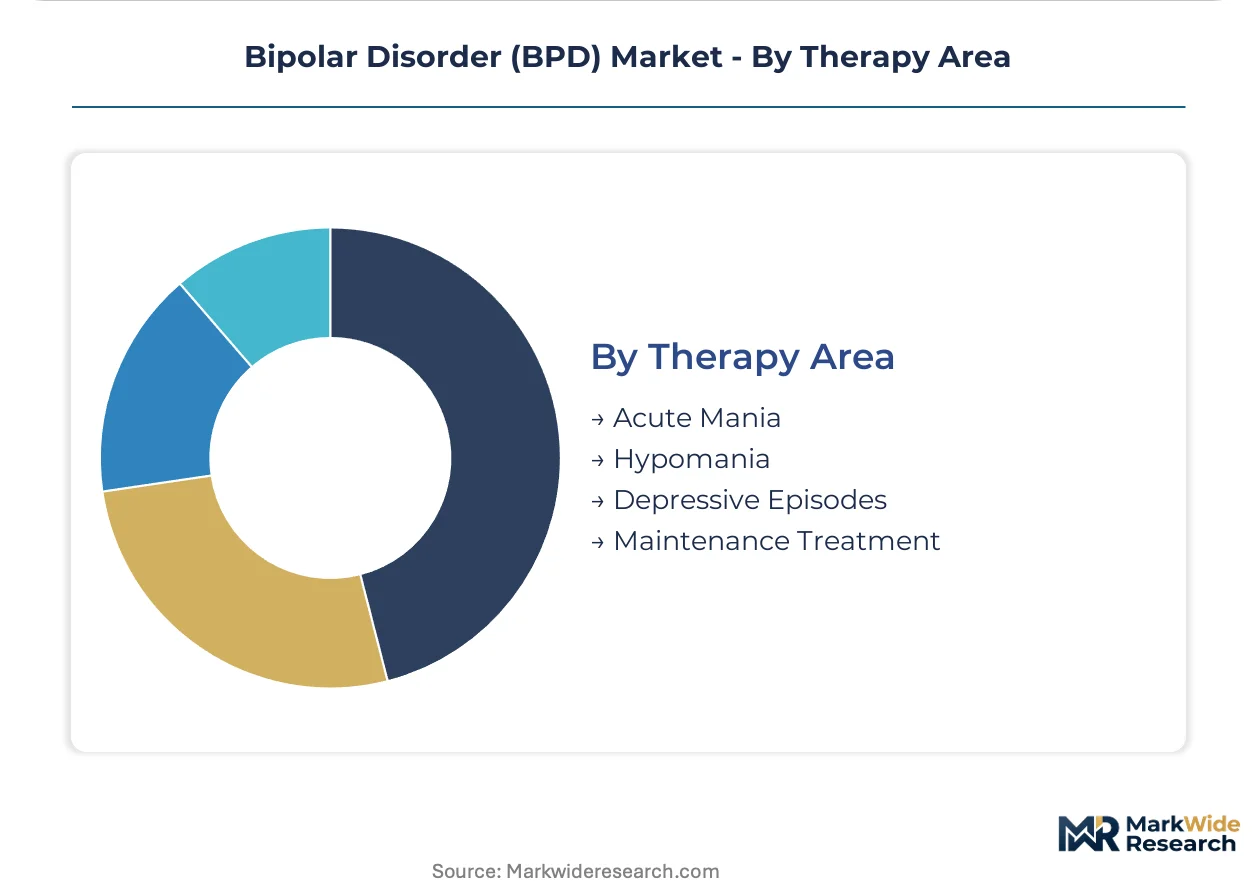
Therapy Area:
Clinical indication segments align with episode polarity and treatment phase, each carrying distinct regulatory evidence requirements and prescriber specialization needs.
- Acute Mania:Severe agitation and psychomotor acceleration require rapid neuroleptic stabilization. US emergency departments and German psychiatric emergency services anchor demand for fast-acting intramuscular formulations.
- Hypomania:Subsyndromal elevation presents diagnostic complexity, with US specialized mood disorder clinics and Japanese outpatient services driving pharmacologic intervention before progression.
- Depressive Episodes:Bipolar depression carries higher suicide risk than mania, with quetiapine and lurasidone formulations capturing prescriber preference over antidepressant monotherapy.
- Maintenance Treatment:Long-term relapse prevention emphasizes mood stabilizer continuity and antipsychotic depot adherence. US Medicare Advantage and German statutory health insurance reimbursement pathways have matured for extended-interval administration.
Maintenance treatment commands the largest addressable patient-years. Acute mania intervention is expanding most quickly as emergency psychiatric service capacity builds in the United States and Germany.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance system reimburses depot antipsychotics at higher rates than oral equivalents, while Japan's cultural stigma toward psychiatric medication creates contrasting demand patterns for discreet delivery formats.
United States
Medicare Advantage plans targeting severe mental illness populations drive demand for adherence-optimized delivery systems. FDA's Risk Evaluation and Mitigation Strategies mandate rigorous post-market surveillance for mood stabilizers. The Boston-Cambridge corridor anchors specialized psychopharmacology research clusters advancing pharmacogenomic-guided prescribing protocols.
Germany
Statutory health insurance reimbursement pathways for maintenance therapy have matured around extended-interval depot administration. EMA pharmacovigilance obligations extend time-to-market for novel formulations through post-authorization safety study requirements. The Rhine-Ruhr metropolitan region concentrates psychiatric service providers consolidating vendor relationships for algorithm-based diagnostic aids.
Japan
Cultural stigma surrounding chronic psychiatric medication creates latent demand for discreet depot formulations administered at extended intervals. PMDA frameworks govern approval pathways for digital therapeutics converging with pharmacologic protocols. Tokyo's specialized mood disorder clinics coordinate maintenance therapy through visiting nurse services for mobility-limited patients.
United Kingdom
NHS England's Long Term Plan prioritizes community-based mental health services over institutional admissions. MHRA pharmacovigilance requirements align with EMA documentation standards for atypical antipsychotic safety profiles. The Maudsley Biomedical Research Centre in London anchors academic-industry partnerships exploring smartphone-based mood monitoring integration.
India
CDSCO regulatory pathways for psychiatric APIs are streamlining as domestic formulation capabilities expand. Government-funded district mental health programs extend reach beyond metropolitan hospital networks. Hyderabad's active pharmaceutical ingredient manufacturing clusters are diversifying into complex synthesis pathways for mood stabilizer production.
Bipolar Disorder (BPD) Market Competitive Environment
United States-based pharmaceutical conglomerates anchor one tier through diversified psychiatric portfolios; European specialists hold formulation leadership in depot extensions and synthesis technologies. The vendor base clusters around three strategic archetypes: integrated healthcare conglomerates with Janssen-style psychiatric divisions, mid-cap mood disorder specialists, and API-to-formulation integrated operators. Dominant competitive moves include M&A targeting pharmacogenomic testing capabilities and sterile manufacturing capacity expansion for microsphere encapsulation.
Within the integrated healthcare conglomerate tier, Johnson & Johnson and Eli Lilly and Company exemplify divergent strategic positioning—Johnson & Johnson leverages long-standing atypical antipsychotic presence through its Janssen division, while Eli Lilly anchors R&D intensity in mood disorder pipelines. AstraZeneca occupies a position extending established oral franchises into depot formulations across European and Asian markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Eli Lilly and Company |
| AstraZeneca |
| GSK plc |
| Otsuka Holdings Co., Ltd. |
| Pfizer Inc. |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| H. Lundbeck A/S |
| Others |
Value Chain & Pricing Dynamics
Depot formulation premiums versus oral generic commoditization create a bifurcated margin architecture that reshapes both procurement strategies and manufacturing investment patterns across bipolar disorder treatment networks. This divergence concentrates pricing power with sterile injectable specialists while compressing returns for immediate-release tablet manufacturers dependent on lithium carbonate API spot markets.
Pricing Analysis
Distributor margins on long-acting injectables run 35-45 points above oral equivalents, reflecting cold-chain handling and specialty pharmacy administration requirements. Three-tier pricing structure across premium depot, standard extended-release, and economy immediate-release oral segments stratifies by formulation complexity and adherence monitoring bundling. Cost compression in immediate-release quetiapine is intensifying because Indian and Chinese API entrants have eroded incumbent margin buffers. Hospital procurement committees exhibit highest price sensitivity for acute mania intramuscular formulations, while Medicare Advantage payers accept premium depot pricing when bundled with remote therapeutic monitoring outcomes guarantees.
Supply Chain Analysis
FDA's Risk Evaluation and Mitigation Strategies and EMA's post-authorization safety study requirements gate sterile manufacturing qualification, limiting contract manufacturing organization availability for microsphere encapsulation. API sourcing draws from Chilean and Australian brine operations for lithium carbonate, German and Swiss fermentation hubs for atypical antipsychotic precursors, and Indian synthesis clusters for lamotrigine intermediates. Single-source vulnerability concentrates in Chilean lithium extraction exposed to water rights disputes and climate-related brine evaporation disruption. Distribution runs through specialty pharmacy networks for depot formulations and traditional wholesale for oral maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bipolar disorder treatment rests on adherence-optimized delivery formats capturing premium reimbursement, while generic erosion in oral antipsychotics forces incumbents to absorb API cost volatility through formulation innovation.
For Market Incumbents: Anchor formulation leadership through captive sterile manufacturing capacity in Germany and the United States, insulating against contract manufacturing organization scarcity for microsphere depot production. Defend against digital therapeutic entrants by integrating smartphone-based mood monitoring into maintenance therapy protocols ahead of FDA prescription digital therapeutic guidance finalization. Prioritize pharmacogenomic testing partnerships to compress trial-and-error prescribing cycles that currently drive patient switching. For New Entrants and Emerging Players: Begin with underpenetrated Japanese maintenance therapy segments where cultural stigma toward daily oral medication creates latent demand for discreet quarterly depot administration. Target visiting nurse service partnerships in Medicare Advantage severe mental illness carve-outs as the most penetrable channel for adherence-optimized delivery introduction. Pursue real-world evidence contracting with US commercial payers as the primary go-to-market mechanism, demonstrating hospitalization reduction through extended-interval formulation adherence. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing qualification scarcity meets rising depot formulation demand across maintenance therapy protocols. Long-term viability favors operators with backward integration into lithium carbonate sourcing or proprietary microsphere encapsulation intellectual property. Monitor FDA digital biomarker guidance issuance as the inflection signal for algorithm-based diagnostic aid convergence with pharmacologic treatment workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Manufacturing Scale-Up | Captures Medicare Advantage premium reimbursement for adherence-optimized maintenance therapy delivery. |
| Pharmacogenomic Testing Partnership | Reduces 8-12 week medication selection cycles at US academic medical centers and German mood disorder clinics. |
| Digital Therapeutic Regulatory Pathway | Positions for FDA prescription digital therapeutic approval in algorithm-based cognitive behavioral adjuncts. |
| Lithium API Supply Security | Mitigates Chilean and Australian brine concentration risk through offtake agreements or captive extraction investment. |
| Real-World Evidence Infrastructure | Enables outcomes-based contracting with commercial payers rewarding demonstrated hospitalization frequency reduction. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at US commercial payers, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov protocols, and CMS Medicare claims data. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing across pharmacologic classes and delivery modes.
Segment-weighting approaches distributed value and volume across atypical antipsychotic, lithium, and mood stabilizer categories, further disaggregated by oral versus injectable administration routes and acute versus maintenance therapy indications. CAGRs were derived from epidemiological prevalence projections, treatment rate assumptions, and pricing trajectory analysis across the projection horizon. Forecast inputs incorporated FDA Risk Evaluation and Mitigation Strategies implementation timelines and EMA pharmacovigilance documentation burden effects on formulation launch sequencing.
Caveats apply where FDA digital biomarker guidance finalization or EMA Medical Device Regulation conformity assessment delays could materially shift the outlook for digital therapeutic convergence. Forecasts reflect assumptions regarding maintenance therapy protocol shifts and depot formulation reimbursement pathway maturation. A model refresh is warranted upon material change in lithium carbonate supply concentration or Medicare Advantage severe mental illness carve-out expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market