
 US Hospital Gowns Market | 2026-2036
US Hospital Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
US Hospital Gowns Market Intelligence
EPA textile waste guidelines and state-level single-use plastic scrutiny is rebalancing procurement priorities across acute care networks. Medline Industries leverages vertical manufacturing scale to control domestic gown production from raw polymer to finished sterile product. Cardinal Health sustains broad distributor relationships that anchor its presence in group purchasing organization contracts. Standard Textile Co. specializes in reusable surgical gown programs that compete on total cost-of-ownership metrics against disposable alternatives.
US hospital gowns are personal protective garments engineered to AAMI PB70 liquid barrier standards, constructed from spunbond-meltblown-spunbond laminates, woven cotton, or polypropylene nonwovens, designed to isolate patients and healthcare workers from infectious agents and bodily fluid transmission. Disposable gowns dominate volume due to infection control protocols, while reusable cotton and polyester blends retain margin concentration in academic medical centers with on-site laundering infrastructure. SMS fabric represents the fastest-growing material substrate as manufacturers optimize breathability against fluid penetration performance.
FDA enforces AAMI PB70 classification for surgical gowns, while OSHA bloodborne pathogen standards mandate employer-provided protective apparel, and state health departments impose additional laundering and disposal regulations that shape local vendor qualification. CMS reimbursement policies indirectly influence gown selection through bundled payment incentives that reward reduced surgical site infection rates. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions on textile treatments and prepare supply chains for potential shifts in barrier chemistry requirements.
Market Dynamics
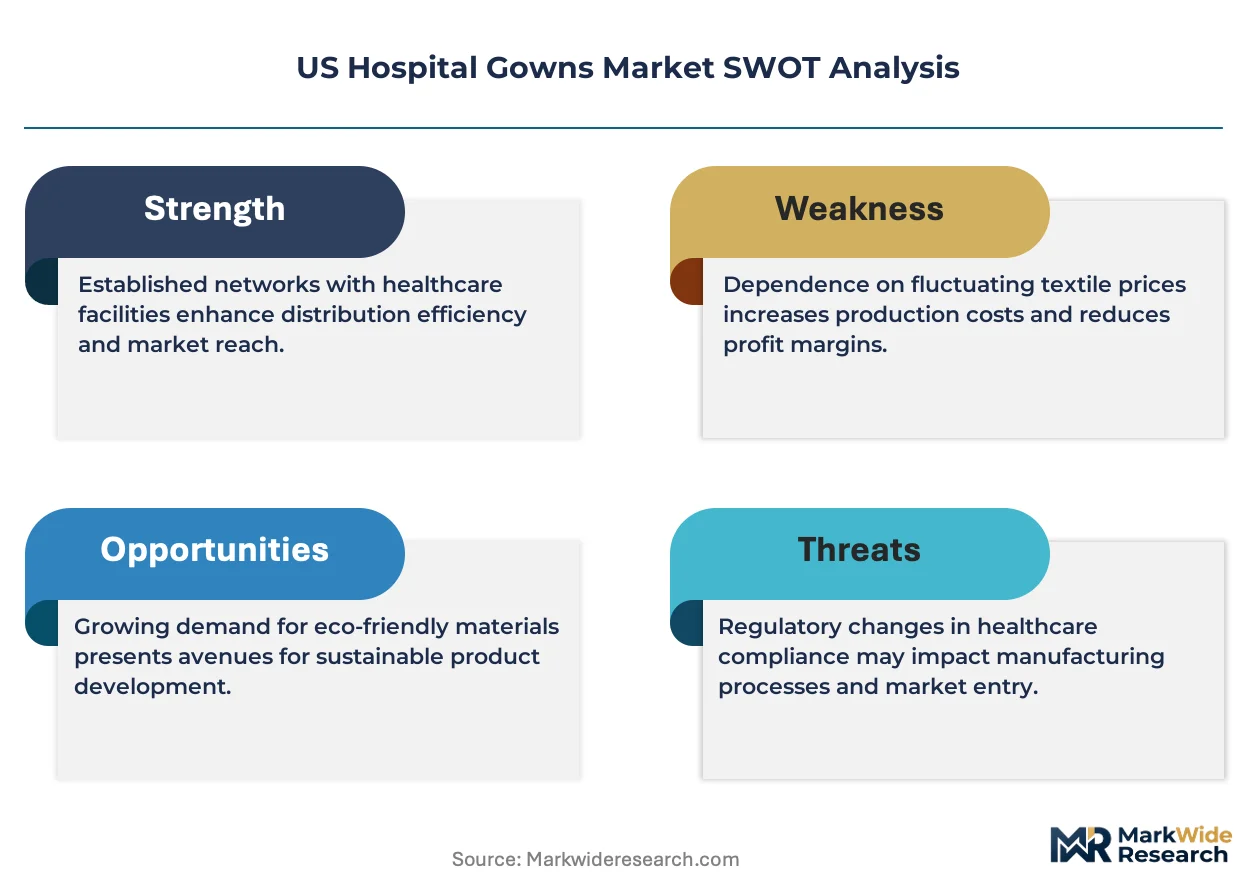
CMS bundled payment incentives reward surgical site infection reduction, pressuring acute care networks toward higher AAMI-rated gowns while EPA per- and polyfluoroalkyl substance restrictions threaten established barrier chemistry supply chains.
Growth Catalysts
- ASC Expansion:Ambulatory surgical centers in the southeastern United States are accelerating single-use protective apparel procurement as outpatient procedure volumes climb.
- FDA Barrier Elevation:Updated liquid barrier performance guidance is mandating minimum AAMI PB70 Level 3 ratings for surgical gowns across hospital networks.
- SMS Fabric Optimization:Spunbond-meltblown-spunbond laminates are capturing share from woven alternatives as manufacturers balance breathability against fluid penetration thresholds.
Market Restraints
- Petrochemical Input Volatility:Polypropylene resin prices fluctuate with crude oil markets, compressing margins for nonwoven gown manufacturers without captive polymer supply.
- Domestic Production Concentration:Vertical manufacturing scale concentrates in Midwest industrial corridors, creating geographic supply vulnerability during regional logistics disruptions.
- Reusable Program Competition:Academic medical centers with on-site laundering infrastructure deploy total cost-of-ownership metrics that undercut disposable gown value propositions.
Strategic Opportunities
- State-Level Sustainability Mandates:California and New York textile waste guidelines create procurement preference windows for biodegradable barrier materials ahead of federal EPA action.
- On-Site Sterilization Integration:GPO contracts increasingly bundle sterile processing services with gown supply, rewarding vendors with integrated logistics capabilities.
- Southeastern Construction Pipeline:Hospital and ASC development in Florida, Georgia, and Texas outpaces national averages, concentrating near-term demand expansion.
Industry Challenges
- AAMI Certification Timelines:FDA 510(k) clearance for novel barrier chemistries extends 18-24 months, delaying product launches against evolving EPA substance restrictions.
- Laundry Infrastructure Retrofit Costs:Health systems evaluating reusable gown programs face capital-intensive washer-extractor and tunnel washer installations with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hospital Gowns Market |
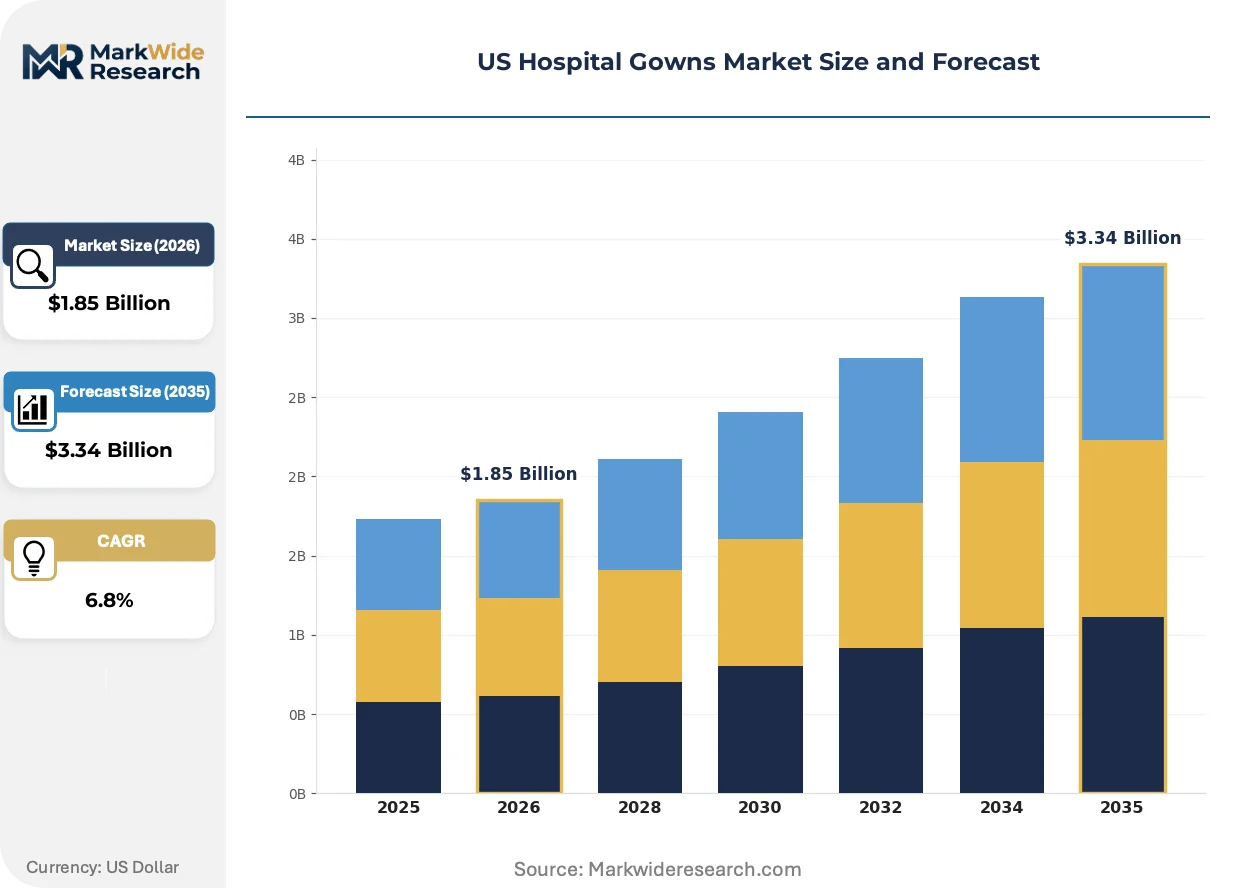
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Gowns, Disposable Gowns, Surgical Gowns, Protective Gowns Material: Cotton, Polypropylene, Polyester, SMS Fabric End User: Hospitals, Clinics, Nursing Homes, Research Facilities Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Distributors |
| Companies Covered | Medline Industries, Cardinal Health, 3M, Standard Textile Co., AmeriPride Services Inc., Angelica Corporation, Owens & Minor, Encompass Group, Vestis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hospital Gowns Market Strategic Shifts & Innovations
Barrier material science and procurement contracting models are converging to reshape competitive positioning, with sustainability compliance emerging as a parallel design constraint alongside infection control performance.
SMS laminate technology is consolidating surgical gown material selection as manufacturers optimize meltblown layer density for AAMI Level 3-4 penetration resistance. Academic medical centers and ASC networks are standardizing on SMS platforms to simplify inventory management. This consolidation is compressing woven cotton and polypropylene alternatives into niche applications where laundering infrastructure or extreme cost sensitivity dominates.
EPA per- and polyfluoroalkyl substance restrictions are forcing reformulation of durable water-repellent textile treatments across domestic gown production. The industrial consequence is accelerated R&D spending on silicone-based and hydrocarbon barrier alternatives. Surgical gown vendors with captive polymer research facilities are responding fastest, while smaller converters face raw material qualification delays.
Group purchasing organization contracting is compressing vendor rosters as health systems consolidate supplier relationships to secure volume pricing and standardize barrier performance tiers. Regional GPOs in the Midwest and Southeast are displacing direct hospital procurement for gowns under $50,000 annual spend thresholds. Texas and Florida health networks exhibit the most aggressive GPO consolidation, with three distributors capturing majority share in metropolitan markets.
US Hospital Gowns Market Segmentation
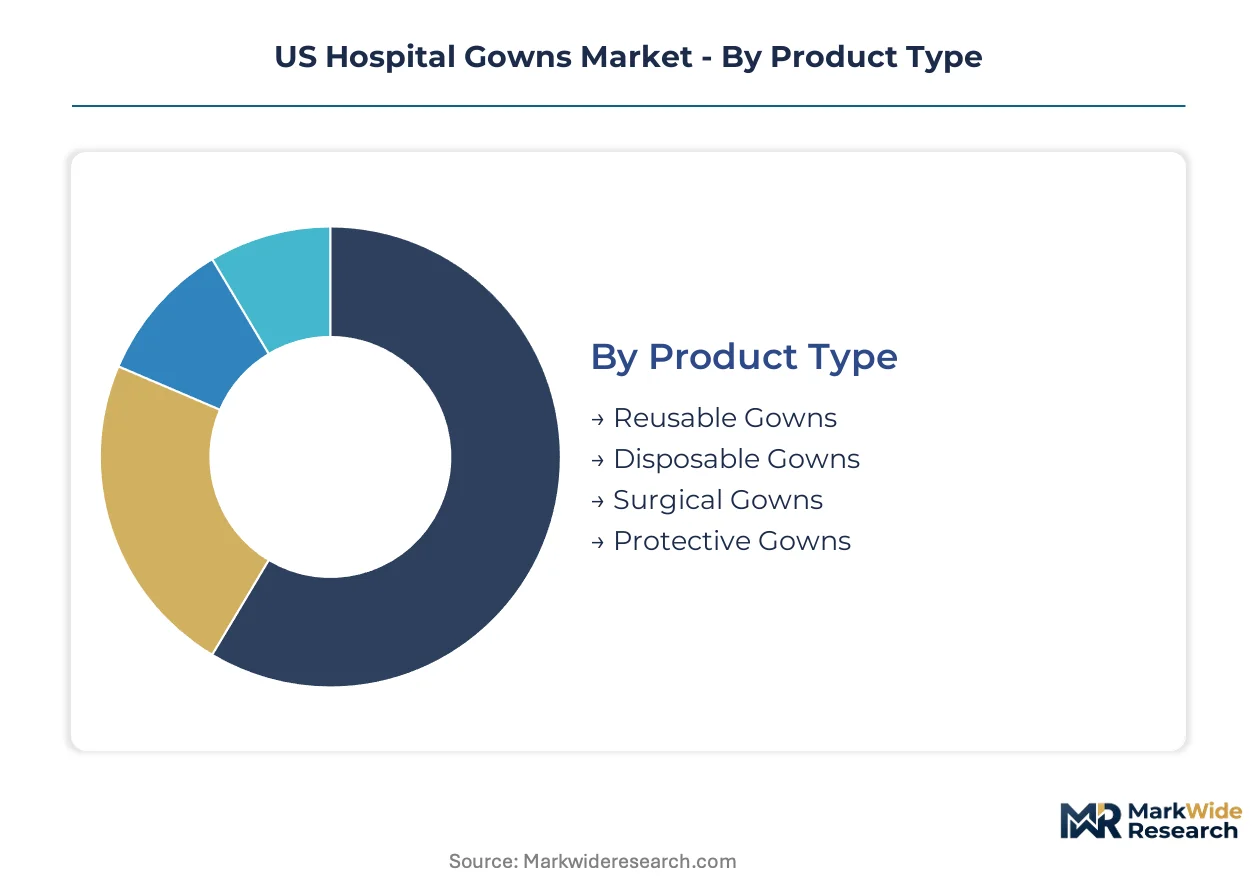
US hospital gown procurement splits across multiple decision axes that reshape vendor access and margin capture. Material science advances and infection control protocols are fragmenting what once operated as a commoditized supply category into distinct performance tiers with diverging pricing power.
Product Type:
Supply concentration clusters around disposable platforms as manufacturers exploit polymer supply chain control to lock in recurring volume.
- Reusable Gowns:Woven cotton and polyester blends engineered for 75-100 industrial wash cycles. Academic medical centers in the Midwest and Northeast with captive laundering infrastructure anchor demand, though capital retrofit requirements stall expansion into smaller systems.
- Disposable Gowns:Spunbond-meltblown-spunbond laminates and polypropylene nonwovens designed for single-use isolation. Southeastern ASC networks and Florida hospital construction pipelines are accelerating procurement as outpatient procedure volumes climb.
- Surgical Gowns:AAMI PB70-rated sterile barriers with reinforced critical zones. FDA elevation of minimum liquid barrier ratings is compressing Level 1-2 inventory into non-surgical applications.
- Protective Gowns:Isolation apparel for contact and droplet precautions in general patient care. Nursing homes and long-term acute care facilities prioritize cost minimization over barrier performance in this segment.
Today's leader: Disposable Gowns. Tomorrow's challenger: Reusable Gowns.
Material:
Cost tier stratification separates premium barrier performance from economy-grade alternatives.
- SMS Fabric:Spunbond-meltblown-spunbond laminates optimizing meltblown layer density for AAMI Level 3-4 penetration resistance. Texas and Florida health networks are standardizing procurement on SMS platforms to consolidate inventory SKUs.
- Polypropylene:Spunbond nonwovens offering economy-tier pricing for isolation and visitor gown applications. Petrochemical input volatility compresses margins for converters without captive polymer supply.
- Polyester:Woven and knit constructions for reusable surgical programs. On-site laundering infrastructure requirements limit addressable market to health systems with capital deployment capacity.
- Cotton:Traditional woven natural fiber retained in niche academic medical center contracts. EPA textile waste scrutiny and laundering energy costs are accelerating displacement by synthetic alternatives.
Volume concentrates in SMS Fabric. Margin protection depends on Polyester.
End User:
Application intensity varies sharply across care settings, with surgical volume driving premium gown consumption.
- Hospitals:Integrated delivery networks with bundled payment exposure to surgical site infection penalties. CMS reimbursement incentives are pressuring procurement toward higher AAMI-rated gowns across operating room and interventional suites.
- Clinics:Outpatient and ambulatory settings with lower barrier performance requirements. Group purchasing organization consolidation is displacing direct procurement for annual gown spend under threshold limits.
- Nursing Homes:Long-term care facilities prioritizing economy-grade isolation apparel. Staff turnover and Medicaid reimbursement constraints suppress willingness to pay for premium barrier materials.
- Research Facilities:Academic and pharmaceutical laboratories with specialized biocontainment requirements. Small order quantities and specification variability limit vendor interest relative to acute care volume.
Revenue pools deepest in Hospitals. Growth velocity peaks in Clinics.
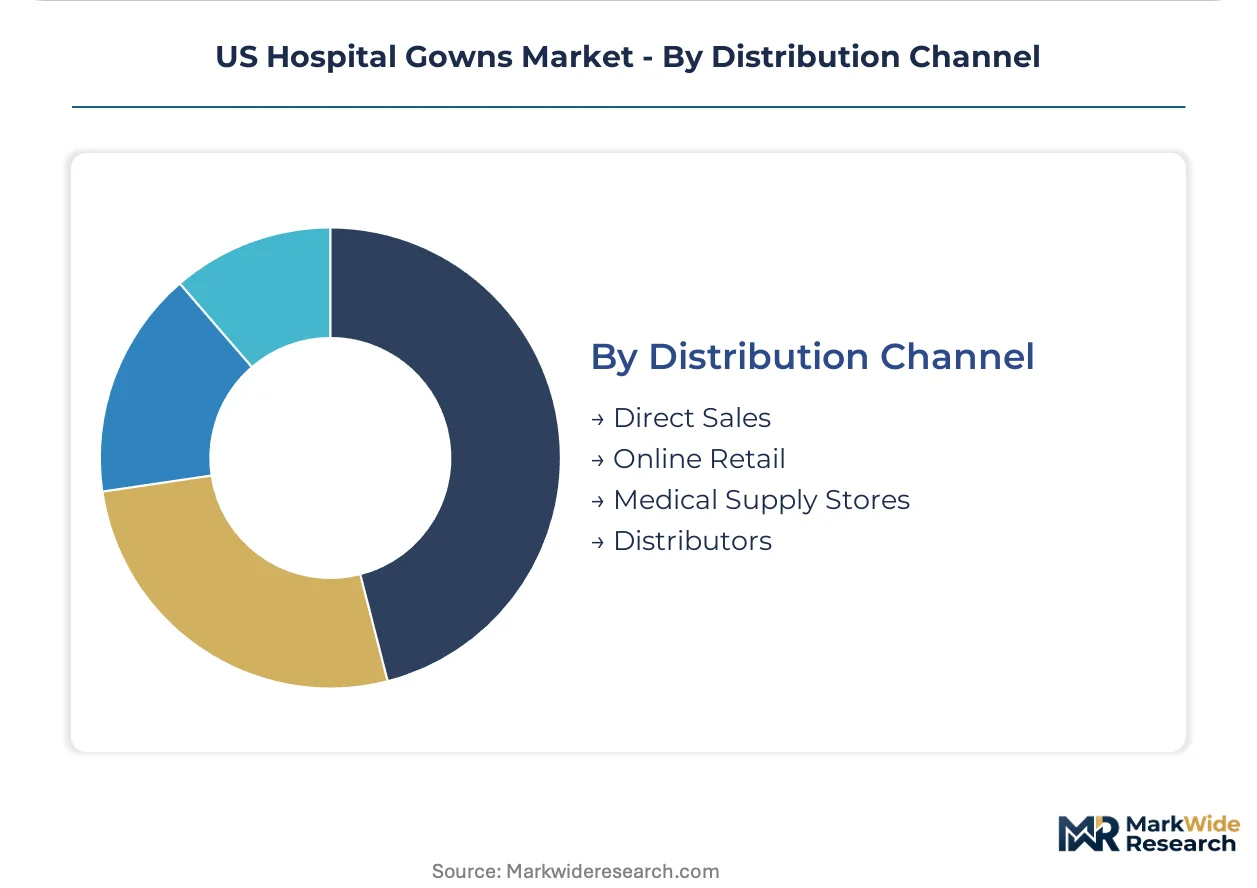
Distribution Channel:
Customer type and procurement scale determine channel selection, with large systems consolidating through integrated distributors.
- Distributors:Cardinal Health and McKesson anchor group purchasing organization contracts with bundled logistics and sterile processing services. Metropolitan markets in Texas and Florida exhibit the most aggressive consolidation into three-distributor oligopoly structures.
- Direct Sales:Medline Industries and vertical manufacturers bypass intermediaries for health systems with sufficient volume to justify dedicated account management. Midwest industrial corridor proximity supports this model.
- Medical Supply Stores:Regional and local dealers serving independent practices and rural facilities below GPO threshold scale. Inventory breadth constraints limit gown selection to commodity SKUs.
- Online Retail:Amazon Business and specialized medical marketplaces capturing small-facility and emergency replenishment demand. Price transparency compresses margins but expands geographic reach.
Share accumulates fastest in Distributors. Direct Sales defends margin most effectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare workforce concentration in the southeastern United States anchors regional demand expansion, with nursing and surgical staff density driving procurement volumes in high-growth hospital construction corridors.
Southeast (Florida, Georgia, Texas)
Ambulatory surgical center construction in Florida and Texas accelerates single-use protective apparel procurement as outpatient procedure volumes climb. OSHA bloodborne pathogen standards mandate employer-provided protective apparel across Georgia ASC networks. Houston and Dallas medical districts concentrate distributor warehousing capacity to serve expanding suburban hospital systems.
Midwest (Illinois, Ohio, Michigan)
Academic medical centers in Chicago and Cleveland retain on-site laundering infrastructure supporting reusable surgical gown programs. EPA textile waste guidelines pressure Illinois health systems toward biodegradable barrier materials. Midwest industrial corridors host vertical polymer-to-gown manufacturing facilities with captive resin supply.
Northeast (New York, Massachusetts, Pennsylvania)
Medicaid reimbursement constraints in New York long-term care facilities suppress premium gown willingness-to-pay. State health departments impose additional laundering regulations shaping local vendor qualification in Massachusetts. Philadelphia and Pittsburgh health networks consolidate group purchasing organization contracts to secure volume pricing.
West (California, Washington, Arizona)
California textile waste guidelines create procurement preference windows for biodegradable barrier materials ahead of federal EPA action. Arizona retirement community expansion drives isolation gown demand in skilled nursing settings. Los Angeles and Seattle health systems pilot silicone-based barrier alternatives responding to per- and polyfluoroalkyl substance restrictions.
Southwest (Texas, Arizona, New Mexico)
Border region hospital construction concentrates demand for Level 3-4 AAMI-rated surgical gowns in El Paso and Tucson markets. CMS bundled payment incentives pressure Texas health networks toward infection-reducing protective apparel. Phoenix medical corridor development outpaces national averages for ASC facility openings.
US Hospital Gowns Market Key Industry Players
Capital-heavy producers compete with asset-light converters across the US hospital gown supply base, with vertical polymer-to-gown manufacturers facing distributed converters sourcing commoditized nonwovens. Market structure tilts toward consolidation as group purchasing organization contracts compress vendor rosters below threshold spend limits. Three strategic archetypes dominate: integrated manufacturers with captive resin supply, broad-line distributors anchoring GPO relationships, and specialized reusable program operators. Competitive moves concentrate on sterile processing service bundling and sustainability-compliant barrier material qualification.
Among integrated manufacturers, Medline Industries exemplifies backward integration into raw polymer production, while Cardinal Health occupies a position as a broad-line distributor with GPO contract anchoring. Standard Textile Co. represents the reusable program specialist archetype competing on total cost-of-ownership metrics.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| 3M |
| Standard Textile Co. |
| AmeriPride Services Inc. |
| Angelica Corporation |
| Owens & Minor |
| Encompass Group |
| Vestis |
| Others |
Cost & Logistics Intelligence
Group purchasing organization consolidation in Texas and Florida health networks anchors contract-based procurement with volume-tiered discounts, compressing spot-market pricing power for smaller converters while rewarding integrated manufacturers with captive polymer supply.
Pricing Analysis
Three-tier pricing structure across premium AAMI Level 4 surgical gowns, standard Level 3 isolation apparel, and economy-grade polypropylene visitor gowns dominates procurement contracts. Price differentiation hinges on FDA barrier certification tier and vertical manufacturing scale, with petrochemical input volatility intensifying cost compression in the economy segment. Academic medical centers with reusable programs exhibit lowest price sensitivity, while nursing homes under Medicaid constraints drive hardest bargain.
Supply Chain Analysis
Domestic-content preferences in federal and state procurement guidelines are reshaping sourcing toward Midwest polymer-to-gown manufacturing corridors. Raw material supply draws from Texas and Louisiana petrochemical feedstocks, South Carolina spunbond nonwoven capacity, and domestic meltblown filtration media production. Single-source vulnerability concentrates in polypropylene resin supply during regional logistics disruptions. Distribution runs through Cardinal Health and McKesson GPO contracts anchoring metropolitan hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US hospital gowns rests on SMS fabric optimization reducing raw material intensity per AAMI-rated unit while FDA barrier elevation shifts volume toward premium-tier certified products.
For Market Incumbents: Cement GPO contract anchoring through sterile processing service bundling, defending against distributor disintermediation by Medline's direct sales model. Expand captive meltblown capacity in Midwest industrial corridors to offset petrochemical price volatility. Prioritize EPA-compliant silicone-based barrier R&D ahead of per- and polyfluoroalkyl substance restrictions. For New Entrants and Emerging Players: The price-point gap between premium AAMI Level 4 surgical gowns and economy polypropylene isolation apparel offers entry at mid-tier Level 3 SMS platforms. Target southeastern ASC networks in Florida and Texas bypassing entrenched three-distributor oligopolies. Lead with sustainability-certified biodegradable barrier materials qualifying for California and New York procurement preferences. For Investors and Strategic Acquirers: Broad-line healthcare distributors are the most active acquirer in this space, seeking vertical gown manufacturing capabilities to secure GPO contract margins. Five-to-ten-year viability favors converters with EPA-compliant barrier chemistry pipelines over commodity polypropylene assemblers. Monitor FDA 510(k) clearance timelines for novel barrier materials as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SMS Fabric Capacity Expansion | Captures AAMI Level 3-4 standardization demand from Texas and Florida health networks. |
| Silicone-Based Barrier R&D Investment | Positions ahead of EPA per- and polyfluoroalkyl substance restrictions on textile treatments. |
| GPO Contract Consolidation | Locks in volume pricing with southeastern ASC construction pipelines outpacing national averages. |
| On-Site Sterilization Integration | Bundles sterile processing services with gown supply, rewarding vendors with logistics capabilities. |
| Reusable Program Infrastructure Partnership | Supplies washer-extractor and tunnel washer systems to academic medical centers evaluating total cost-of-ownership models. |
Research Approach
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterile processing directors combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EPA textile waste guideline documents. Bottom-up demand modeling from ASC construction pipelines and surgical procedure volume trajectories triangulated against top-down market sizing from polymer consumption data and distributor revenue disclosures.
Segmentation outputs across product type, material substrate, end-user setting, and distribution channel dimensions generated volume and value projections across the analysis window. CAGRs derived from weighted average of historical surgical procedure growth, ASC facility opening rates, and AAMI barrier rating upgrade cycles. Forecast inputs incorporated polypropylene resin price elasticity, FDA clearance timeline distributions, and state-level sustainability mandate adoption curves.
Caveats apply where EPA per- and polyfluoroalkyl substance enforcement timelines, CMS bundled payment recalibration, or Midwest logistics disruptions could materially shift the outlook. Forecasts reflect documented assumptions on ASC construction completion rates and barrier chemistry qualification success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plastic Syringes Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Breast Shells Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
India Disposable Latex Gloves Market