
 Benign and Malignant Soft Tissue Tumors Treatment Market | 2026-2036
Benign and Malignant Soft Tissue Tumors Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Benign and Malignant Soft Tissue Tumors Treatment Market Outlook
The FDA's Breakthrough Therapy designation is consolidating the cost-of-entry calculus for developers of novel soft tissue sarcoma agents. Pfizer leverages its established oncology infrastructure to sustain commercial reach across major treatment centers. Bristol Myers Squibb anchors its position through deep immuno-oncology expertise in solid tumor indications. Novartis AG competes via targeted therapy platforms that address specific sarcoma molecular subtypes.
Benign and malignant soft tissue tumors treatment encompasses surgical resection, radiation protocols, systemic chemotherapy, and molecularly targeted agents administered through intravenous, oral, or localized delivery routes, with treatment selection governed by histologic grade, tumor size, anatomic location, and metastatic status. Surgery and radiation therapy occupy the mature core of the intervention landscape, while targeted therapy represents the fastest-expanding segment driven by biomarker-defined patient stratification. Oncology clinics and hospitals capture the dominant share of procedure volume, though outpatient centers are extending their role in post-surgical monitoring and adjuvant therapy administration.
The FDA, EMA, and WHO collectively shape product standards through oncology-specific efficacy endpoints, Good Manufacturing Practice requirements for biologics, and international consensus guidelines for sarcoma classification. These frameworks force developers to generate robust biomarker data prior to regulatory submission, elevating R&D investment thresholds. Stakeholders must monitor evolving payer evidence requirements for combination regimens and decide whether to build in-house biomarker diagnostic capabilities or pursue companion diagnostic partnerships.
Market Dynamics
FDA's Breakthrough Therapy designation is compressing clinical development timelines for sarcoma agents while simultaneously elevating biomarker data requirements, forcing developers to front-load diagnostic infrastructure investments before first-in-human trials.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's oncology-specific efficacy endpoints enable faster market entry for targeted agents addressing unmet needs in rare sarcoma subtypes.
- Biomarker-Defined Stratification:Next-generation sequencing adoption in academic medical centers is expanding addressable patient populations for molecularly targeted therapies.
- Multidisciplinary Program Expansion:United States hospital networks are anchoring dedicated sarcoma units that integrate surgical, radiation, and systemic therapy capabilities under single institutional frameworks.
Market Restraints
- Companion Diagnostic Dependency:EMA's stringent co-development requirements for targeted agents create dual-validation bottlenecks that extend regulatory timelines.
- Biologics Manufacturing Concentration:Contract manufacturing for monoclonal antibodies concentrates among a limited supplier base in North America and Western Europe.
- Radiation Therapy Capacity Limits:Linear accelerator installation requires substantial capital outlays and specialized shielding infrastructure that constrains geographic access.
Strategic Opportunities
- Outpatient Administration Migration:Community oncology centers are capturing post-surgical monitoring and oral adjuvant therapy volume from inpatient settings.
- Artificial Intelligence Integration:Machine learning platforms for radiologic staging and treatment response assessment are converging with electronic health record systems.
- Inflation Reduction Act Provisions:Medicare price negotiation mechanisms for selected oncology drugs are reshaping commercial strategy calculations for pipeline assets.
Industry Challenges
- Sarcoma Pathology Specialization:Accurate histologic classification requires fellowship-trained pathologists, creating diagnostic bottlenecks at non-academic centers.
- Clinical Trial Enrollment Friction:Patient dispersion across low-incidence subtypes complicates recruitment for biomarker-selected cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benign and Malignant Soft Tissue Tumors Treatment Market |
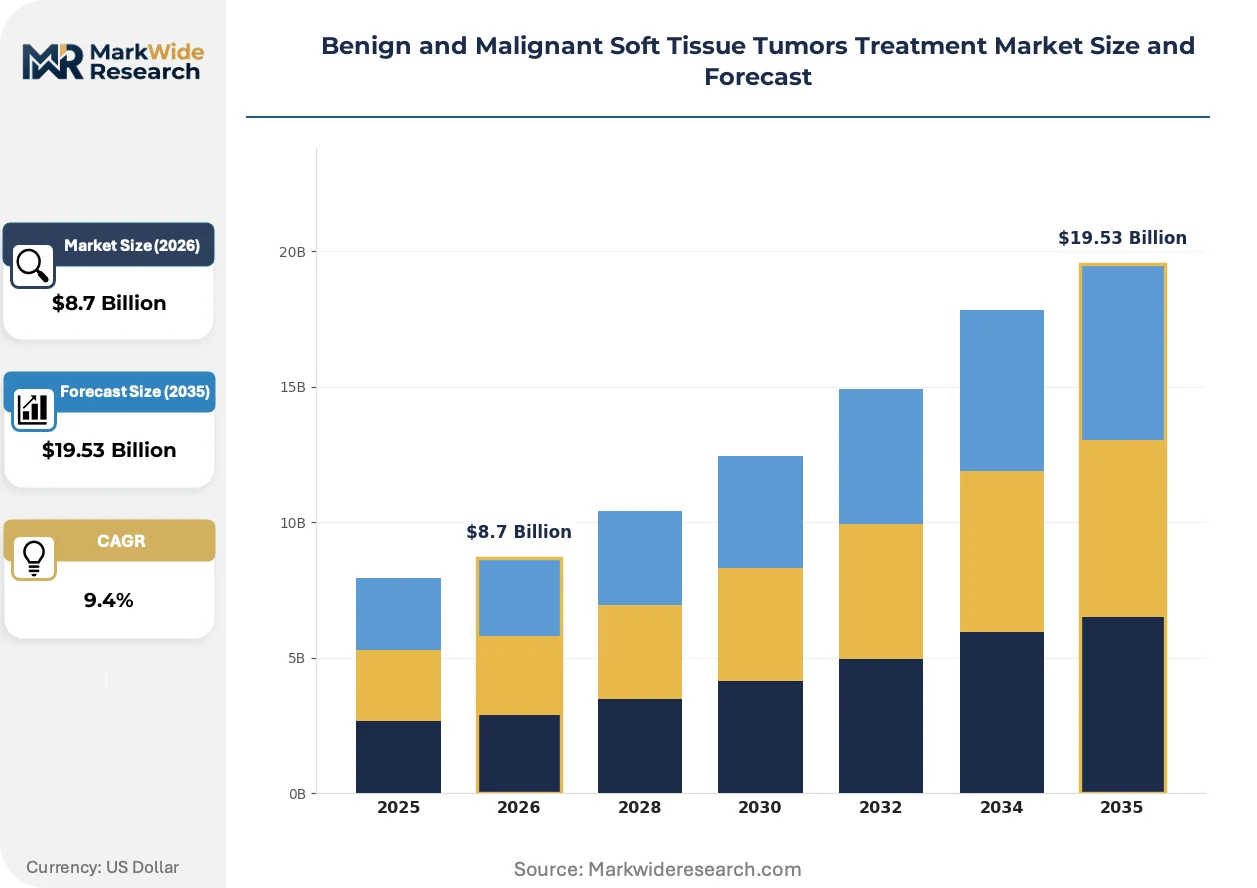
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy Application: Oncology Clinics, Hospitals, Outpatient Centers, Home Care Delivery Mode: Intravenous, Oral, Injectable, Local Delivery End User: Healthcare Providers, Patients, Caregivers, Research Institutions |
| Companies Covered | Pfizer, Eli Lilly and Company, Bristol Myers Squibb, Novartis AG, Roche Holding AG, Bayer AG, Philogen, Intensity Therapeutics, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benign and Malignant Soft Tissue Tumors Treatment Market Strategic Shifts
Artificial intelligence applications are penetrating diagnostic and treatment planning workflows, while regulatory frameworks evolve to accommodate real-world evidence generation for rare oncology indications.
Digital pathology platforms are automating histologic review processes that previously required manual examination by specialized pathologists. Academic medical centers in the United States are deploying these systems for remote consultation and second-opinion workflows. This capability is automating case triage and reducing diagnostic turnaround times for complex sarcoma specimens.
The European Medicines Agency's expanded use of real-world data in regulatory submissions is altering evidence-generation strategies for post-market commitments. Developers must now architect prospective observational studies during pivotal trial design. This shift most affects sponsors of targeted therapies seeking conditional marketing authorization in the European Union.
Consolidated purchasing by integrated delivery networks is compressing vendor access for novel agents. Hospital systems are centralizing formulary decisions and demanding outcome guarantees for high-cost oncology therapies. This concentration is most pronounced in United States metropolitan markets where academic medical centers anchor regional referral patterns.
Benign and Malignant Soft Tissue Tumors Treatment Market Segmentation
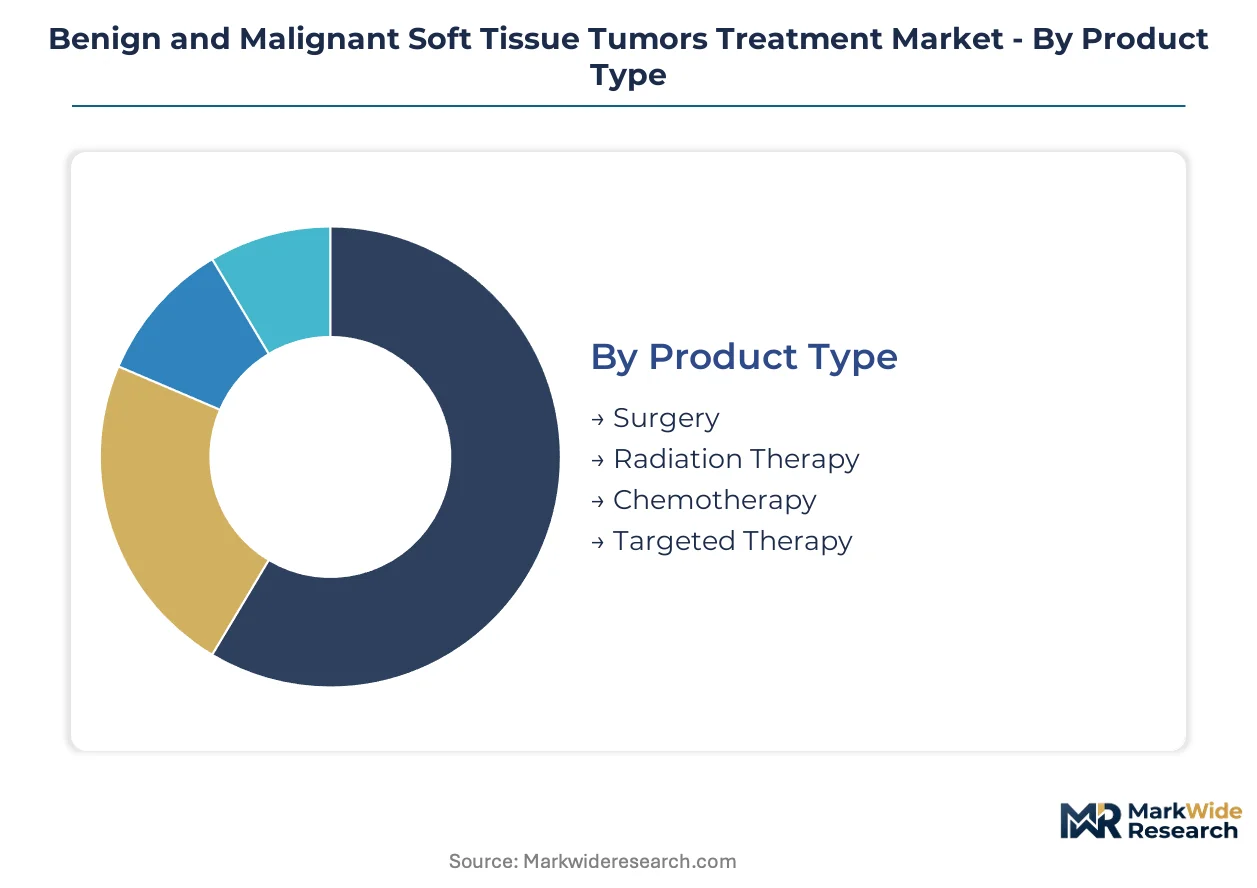
Soft tissue sarcoma treatment modalities fragment across intervention types, care settings, and administration pathways. Each segmentation dimension carries distinct supply chain configurations, reimbursement mechanics, and capacity constraints that shape competitive positioning.
Product Type:
Supply concentration varies sharply across intervention categories, with capital-intensive modalities requiring specialized infrastructure and personnel.
- Surgery:Open and minimally invasive resection techniques demand fellowship-trained surgical oncologists and dedicated sarcoma operating suites. Academic medical centers in the United States concentrate complex limb-sparing procedures, while community hospitals handle localized excisions with lower recurrence risk profiles.
- Radiation Therapy:External beam and brachytherapy protocols rely on linear accelerator installations requiring substantial shielding infrastructure and physics support. Installation concentrates in metropolitan United States markets where patient volume justifies capital deployment, leaving rural access gaps.
- Chemotherapy:Cytotoxic agents administered through established oncology infusion networks with generic availability compressing margin structures.
- Targeted Therapy:Molecularly directed agents with companion diagnostic requirements creating prescriber education and testing access dependencies.
Surgery absorbs the bulk of installed capacity; targeted therapy is expanding most quickly.
Application:
Care setting fragmentation reflects acuity gradients and reimbursement differentials across the treatment continuum.
- Hospitals:Inpatient facilities anchor multidisciplinary sarcoma programs integrating surgical, radiation, and systemic therapy capabilities under single institutional frameworks. United States academic medical centers capture complex cases requiring neoadjuvant protocols and reconstructive surgery.
- Oncology Clinics:Dedicated cancer centers specialize in protocol-driven chemotherapy administration and clinical trial enrollment with concentrated pharmaceutical access.
- Outpatient Centers:Ambulatory settings capture post-surgical monitoring and oral adjuvant therapy volume migrating from inpatient settings.
- Home Care:Oral targeted agents and supportive care medications administered outside institutional settings with pharmacy benefit management dependencies.
Hospitals retain the highest procedure complexity; outpatient centers are gaining share fastest.
Delivery Mode:
Administration pathway selection governs site-of-care economics and patient compliance profiles.
- Intravenous:Infusion-dependent agents requiring healthcare facility presence with nursing supervision and adverse event monitoring capabilities.
- Oral:Self-administered targeted therapies with pharmacy distribution and adherence program requirements.
- Injectable:Subcutaneous and intramuscular formulations with administration flexibility across settings.
- Local Delivery:Isolated limb perfusion and intratumoral injection techniques restricted to specialized sarcoma centers with technical expertise concentration.
Intravenous delivery dominates current volume; oral administration shows the steepest expansion trajectory.
End User:
Stakeholder complexity multiplies across the care continuum with divergent information and economic priorities.
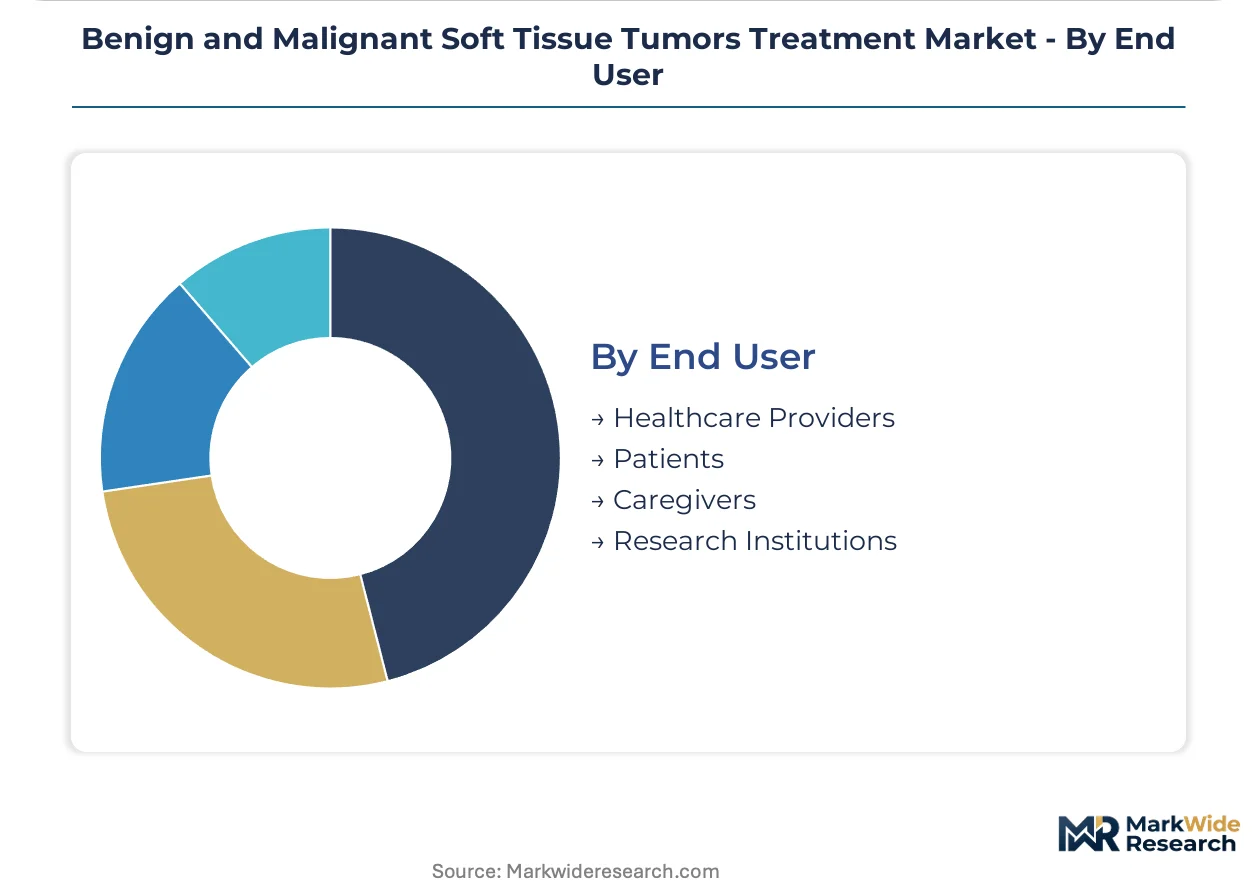
- Healthcare Providers:Multidisciplinary teams including surgical oncologists, medical oncologists, radiation oncologists, and specialized pathologists requiring coordinated decision frameworks.
- Patients:Individuals navigating treatment selection with rare disease information asymmetries and clinical trial access considerations.
- Caregivers:Family members managing transportation, appointment coordination, and post-treatment monitoring responsibilities.
- Research Institutions:Academic centers and contract research organizations driving biomarker discovery and protocol development for rare sarcoma subtypes.
Healthcare providers anchor purchasing decisions; research institutions are expanding influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones surrounding major academic medical clusters concentrate sarcoma treatment infrastructure. Tax-advantaged development districts in the United States, Germany, and Japan anchor specialized surgical and radiation therapy capacity. These zones attract capital deployment for linear accelerator installations and multidisciplinary program expansion.
United States
FDA Breakthrough Therapy designations accelerate sarcoma agent development timelines. The Inflation Reduction Act's Medicare price negotiation provisions reshape commercial strategy for oncology pipeline assets. Memorial Sloan Kettering Cancer Center in New York anchors one of the nation's highest-volume sarcoma programs, integrating surgical oncology with translational research capabilities.
Germany
EMA centralized marketing authorization procedures enable cross-border patient access to novel targeted therapies. The country's statutory health insurance system mandates coverage for orphan oncology indications with demonstrated clinical benefit. Heidelberg University Hospital's sarcoma unit coordinates the German Interdisciplinary Sarcoma Working Group, standardizing histopathologic classification protocols across federal states.
Japan
PMDA's Sakigake designation system compresses review timelines for innovative oncology therapies addressing unmet medical needs. The national health insurance price listing system provides predictable reimbursement for approved sarcoma treatments. National Cancer Center Hospital in Tokyo operates the country's largest dedicated soft tissue sarcoma service, managing complex limb-sparing procedures.
Switzerland
Swissmedic's proximity to EMA procedures enables synchronized regulatory submissions for European market access. Cantonal hospital networks concentrate specialized sarcoma care in university-affiliated centers. University Hospital Basel anchors northwestern Switzerland's multidisciplinary sarcoma program, integrating the Tumor Center Basel with molecular pathology diagnostics.
United Kingdom
NICE technology appraisals establish cost-effectiveness thresholds for NHS commissioning of novel oncology agents. The Cancer Drugs Fund provides interim access to promising therapies pending full NICE evaluation. The Royal Marsden NHS Foundation Trust in London operates Europe's largest dedicated sarcoma unit, coordinating national referral patterns for complex cases.
Benign and Malignant Soft Tissue Tumors Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the soft tissue sarcoma treatment landscape. Large pharmaceutical groups leverage established oncology infrastructure and companion diagnostic partnerships to sustain commercial reach. Mid-sized biotechnology firms concentrate on biomarker-defined patient subpopulations with unmet therapeutic needs. Strategic moves center on targeted therapy platform acquisitions and radiopharmaceutical development partnerships.
Within the diversified pharmaceutical tier, Pfizer and Bristol Myers Squibb exemplify archetypes of scale-driven oncology commercialization. Novartis AG occupies a position representing targeted therapy specialization with molecular platform investments. These entities anchor competitive positioning through distinct capability configurations rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Pfizer |
| Eli Lilly and Company |
| Bristol Myers Squibb |
| Novartis AG |
| Roche Holding AG |
| Bayer AG |
| Philogen |
| Intensity Therapeutics |
| GSK plc |
| Others |
Value Chain & Pricing Dynamics
Companion diagnostic reagent costs cascade through three pricing tiers as they move from contract manufacturers in Germany and the United States through hospital procurement networks to end-user laboratories. Academic medical centers absorb premium pricing for validated assay kits with FDA breakthrough-device status, while community oncology centers face compressed margins on commoditized immunohistochemistry panels.
Pricing Analysis
Short lead-time premiums for CAR-T cell processing materials command 15-40% markups over standard inventory cycles in the United States hospital procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade biologics from research-use-only reagents and bulk API sourcing. Pricing pressure stems from the Inflation Reduction Act's Medicare negotiation mechanisms, which force manufacturers to absorb margin compression on selected oncology agents. Community oncology clinics exhibit the highest price sensitivity due to pharmacy benefit management clawback structures, while academic medical centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive biologics concentrate manufacturing investment in the United States, Germany, and Switzerland, where specialized courier networks maintain chain-of-custody integrity. Monoclonal antibody production draws from Chinese hamster ovary cell lines, single-use bioreactor systems, and affinity chromatography resins as critical upstream inputs. Single-source vulnerability pervades the contract manufacturing organization tier, where three facilities handle the majority of North American fill-finish capacity for parenteral oncology agents. Distribution runs through specialty pharmacy networks with hub-and-spoke configurations that centralize inventory risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over companion diagnostic development represents the decisive downstream lever separating sustainable margins from commodity exposure.
For Market Incumbents: Extend biomarker platform ownership through in-house diagnostic development or exclusive partnership lockups with sequencing vendors. Consolidate radiation therapy capacity in metropolitan United States clusters where linear accelerator utilization rates justify capital deployment. Pfizer's established oncology infrastructure demonstrates how companion diagnostic integration insulates pricing power from generic chemotherapy erosion. For New Entrants and Emerging Players: Begin with oral targeted therapy formulations that bypass infusion center infrastructure requirements and capture outpatient migration volume. Community oncology centers in secondary United States metropolitan markets present the most penetrable access point, with formulary committees receptive to outcome-based contracting for rare sarcoma subtypes. Direct-to-patient adherence programs with telemedicine integration offer a differentiated go-to-market angle against incumbent hospital-centric models. For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation density is the leading indicator that a therapeutic modality is approaching consolidation inflection. The five-to-ten-year viability window favors platforms with validated companion diagnostic pathways and existing Medicare coverage determinations. Acquisition targets should display radiopharmaceutical development capabilities or AI-enabled pathology platforms with regulatory clearance momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | EMA's stringent co-validation requirements force synchronized FDA-EMA submission architectures for targeted agents. |
| Radiopharmaceutical Manufacturing Scale-Up | Isotope supply agreements with Oak Ridge National Laboratory anchor production security for alpha-emitter therapies. |
| AI Pathology Platform Integration | Digital slide scanning at Memorial Sloan Kettering demonstrates automated sarcoma classification reducing diagnostic turnaround. |
| Outpatient Administration Network Expansion | Community oncology center partnerships capture oral adjuvant therapy volume migrating from inpatient settings. |
| Real-World Evidence Generation Infrastructure | Prospective observational study architectures satisfy EMA conditional marketing authorization post-market commitments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving sarcoma program directors at academic medical centers, formulary directors at integrated delivery networks, regulatory affairs leads at biotechnology firms, and procurement managers at hospital systems. FDA 510(k) submissions, EMA marketing authorization applications, ClinicalTrials.gov protocol registrations, and CMS Medicare coverage determinations supplied quantitative anchors. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical revenue disclosures.
Data-stream reconciliation across patient registry flows, pharmaceutical shipment records, and hospital discharge databases established the analytical framework for projections across the analysis window. Segmentation modeling incorporated treatment modality, care setting, administration route, and molecular subtype stratification. CAGRs derived from logistic diffusion curves fitted to biomarker adoption patterns and regulatory approval velocity. Forecast inputs included FDA breakthrough therapy designation trajectories and EMA centralized procedure timelines.
Underlying measurement precision varies by segment; surgery and radiation therapy volumes carry tighter precision than emerging targeted therapy adoption curves due to claims data latency. Forecasts reflect modeling assumptions about biomarker test penetration and payer coverage expansion that could revise materially if Medicare national coverage determinations delay. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Dravet Syndrome Treatment Market