
 UK Ambulatory Services Market | 2026-2036
UK Ambulatory Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK Ambulatory Services Market Intelligence
NHS England's elective recovery framework is expanding the cost-of-entry calculus for independent sector providers. Spire Healthcare leverages its national network of surgical hospitals to capture redirected NHS waiting list volumes. HCA Healthcare U.K. anchors its position through deep specialization in complex same-day procedures. Circle Health Group competes by integrating digital triage with physical clinic access across its regional footprint.
Ambulatory services encompass outpatient medical care delivered without overnight hospital admission, typically involving procedures completed within four hours using local anesthesia, conscious sedation, or minimal invasive techniques designed for same-day discharge. The primary commercial purpose centers on reducing per-episode treatment costs while maintaining clinical outcomes equivalent to inpatient alternatives. Surgical clinics dominate margin pools through higher-revenue specialty procedures in orthopedics and gastroenterology, while telehealth delivery mode sustains the fastest structural expansion as NHS Integrated Care Boards embed remote consultation into standard care pathways. Primary care maintains the largest patient volume base but faces reimbursement compression under national contract frameworks.
The Care Quality Commission enforces registration standards that determine market access for all independent ambulatory providers, while NHS England's procurement rules shape contract eligibility and pricing parameters through the Standard Contract for NHS services. The General Medical Council and Nursing and Midwifery Council set practitioner qualification requirements that constrain workforce supply and directly affect service expansion capacity. Stakeholders must monitor how NHS Integrated Care Board commissioning shifts between direct provision and independent sector capacity will reshape competitive positioning without assuming automatic volume migration.
Market Dynamics
NHS England's elective recovery framework is redirecting surgical volumes toward independent sector capacity, fundamentally altering how ambulatory providers compete for NHS contracts and patient flows.
Growth Catalysts
- Telehealth platform integration:NHS Integrated Care Boards mandate remote consultation pathways, expanding reimbursable digital touchpoints for ambulatory networks serving rural patient populations.
- Ageing demographic concentration:England's over-65 population growth concentrates demand in same-day orthopedic and ophthalmology procedures suited to ambulatory settings.
- Waiting list reduction targets:NHS England's operational planning guidance creates contractual incentives for independent providers to absorb redirected elective surgery volumes.
Market Restraints
- Workforce supply constraints:General Medical Council registration requirements limit anesthetist and surgical specialist availability, capping clinic expansion capacity regardless of capital investment.
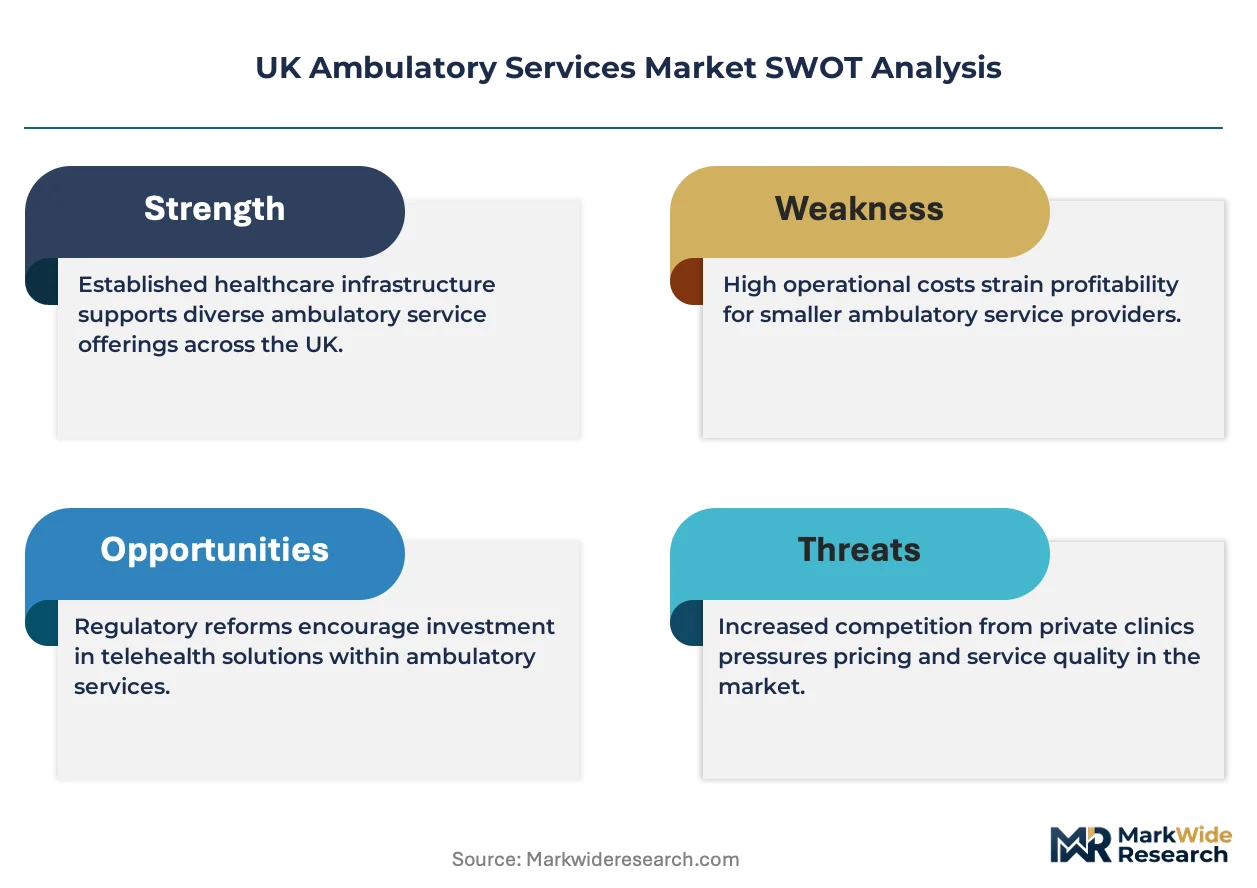
- Property cost inflation:Clinical space rents in London and Greater Manchester corridors squeeze fixed-cost structures for independent clinic operators.
- Reimbursement compression:National tariff pricing under NHS Standard Contracts constrains margin expansion even as procedure volumes rise.
Strategic Opportunities
- Integrated diagnostic-treatment pathways:Same-site imaging and minor surgery capabilities reduce patient journey friction and capture higher-value episode payments.
- Workforce model innovation:Physician associate and advanced nurse practitioner scope expansion under Nursing and Midwifery Council frameworks enables skill-mix optimization.
- Rural network penetration:CQC-registered mobile surgical units and hub-and-spoke models address access gaps across Northern England and Welsh border regions.
Industry Challenges
- Digital infrastructure interoperability:Integration with NHS electronic health record systems requires capital-intensive IT adaptation for independent providers.
- Quality assurance standardization:Care Quality Commission inspection variability across regions creates operational uncertainty for multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Ambulatory Services Market |
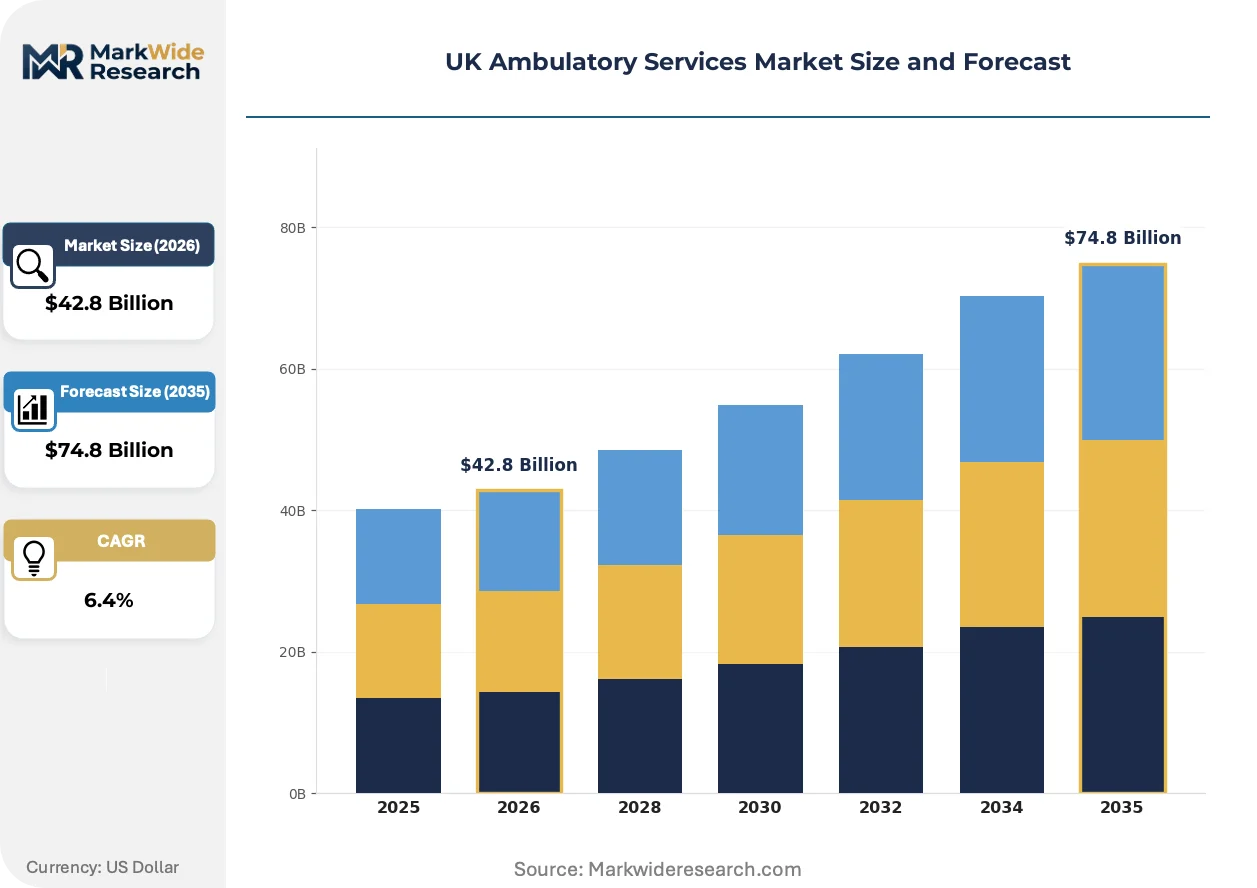
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Care, Surgical Clinics, Urgent Care, Rehabilitation Services Delivery Mode: Telehealth, In-Person Visits, Mobile Clinics, Community Centers Patient Type: Adults, Pediatrics, Geriatrics, Special Needs Patients Treatment Area: Cardiology, Orthopedics, Gastroenterology, Neurology |
| Companies Covered | Spire Healthcare, HCA Healthcare U.K., Circle Health Group, Guy's and St Thomas' NHS Foundation Trust, Aspen Healthcare, Practice Plus Group, OneWelbeck, Chelsea and Westminster Hospital NHS Foundation Trust, Brighton and Sussex University Hospitals NHS Foundation Trust, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Ambulatory Services Market Strategic Shifts & Innovations
Digital health infrastructure and care model redesign are compressing traditional boundaries between hospital, clinic, and home-based service delivery across NHS commissioning areas.
Remote patient monitoring platforms combining wearable biosensors with cloud-based analytics are consolidating post-operative surveillance into continuous home-based pathways. NHS trusts in Birmingham and Leeds are piloting these systems for orthopedic day-case patients, reducing unplanned return visits while shifting liability frameworks toward technology vendors.
NHS England's 2023/24 priorities and operational planning guidance embeds same-day emergency care standards that mandate ambulatory alternatives to acute admission. Independent sector providers must reconfigure staffing and physical capacity to meet these protocols, with London Integrated Care Systems leading compliance timelines.
Patient-initiated follow-up pathways are replacing scheduled outpatient reviews across gastroenterology and urology services. NHS trusts in Manchester and Bristol report 30-40% reduction in routine clinic appointments, forcing ambulatory providers to develop digital engagement capabilities or lose recurring revenue streams.
UK Ambulatory Services Market Segmentation
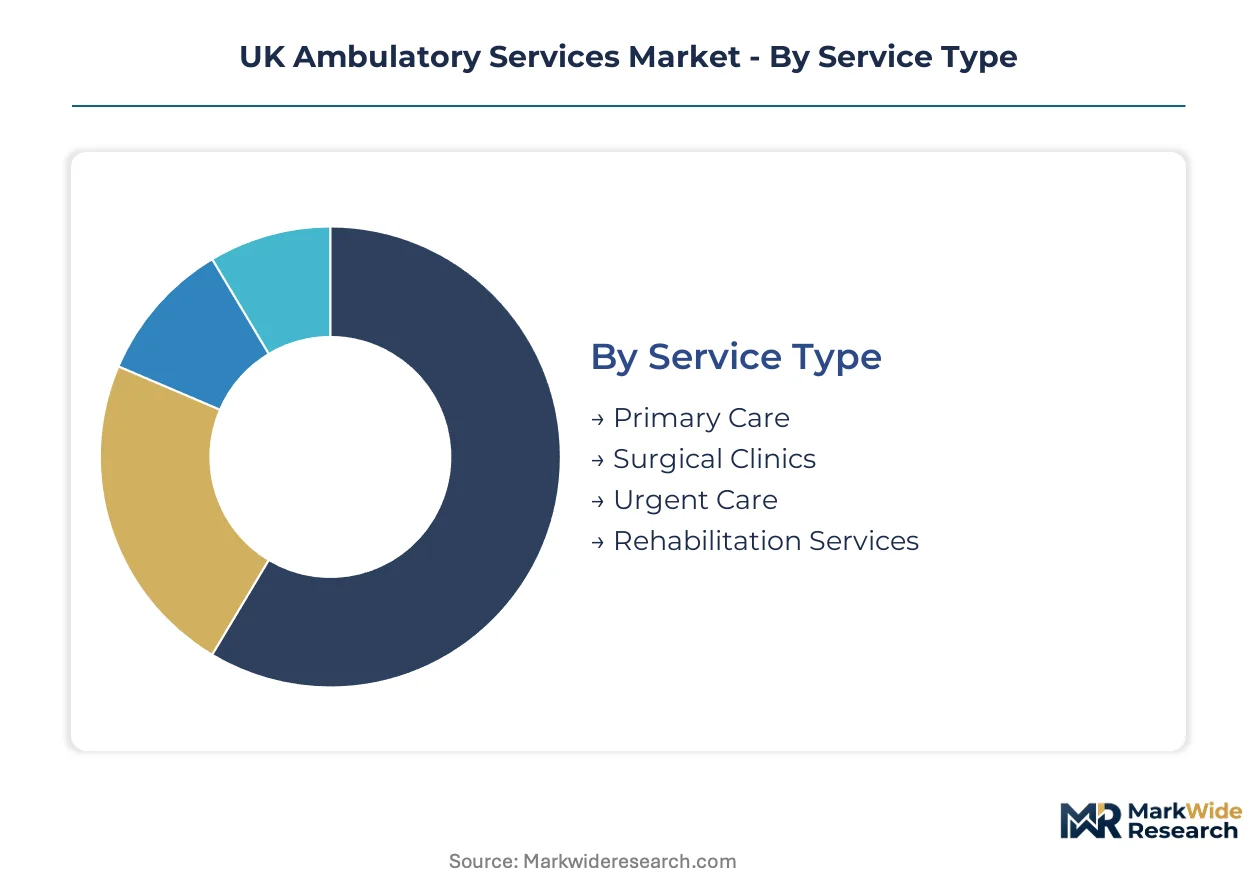
Service configuration determines contract eligibility under NHS Integrated Care Board frameworks. Procurement patterns favor providers with flexible delivery models spanning physical and digital touchpoints. Margin structures vary sharply across patient acuity levels and procedure complexity tiers.
Service Type:
Supply concentration clusters around surgical capacity in England's metropolitan corridor from London to Manchester.
- Surgical Clinics:Facilities equipped for same-day procedures using local anesthesia or conscious sedation. Demand concentrates in orthopedic and gastroenterology day-cases across NHS England's elective recovery program, driven by tariff incentives for reduced length-of-stay.
- Primary Care:General practitioner consultations and chronic disease management delivered through national contract frameworks. Volume concentrates in England's urban Integrated Care Systems where list sizes exceed 10,000 patients per practice, constrained by reimbursement compression under the NHS Standard Contract.
- Urgent Care:Same-day treatment for non-life-threatening conditions outside emergency departments. Walk-in centers across Greater London absorb diverted A&E attendances under NHS operational planning guidance.
- Rehabilitation Services:Post-acute therapy and functional restoration programs. Community-based provision in Northern England addresses stroke and orthopedic recovery pathways.
Surgical clinics absorb the bulk of installed capacity; urgent care is expanding most quickly.
Delivery Mode:
Cost tier differentiation separates capital-intensive fixed sites from variable-cost mobile deployments.
- Telehealth:Remote consultation and digital triage platforms integrated with NHS electronic health record systems. NHS Integrated Care Boards in Birmingham and Leeds mandate these pathways for routine follow-up, reducing physical clinic overhead while requiring interoperability investment.
- In-Person Visits:Traditional clinic-based consultations and procedures. London and Greater Manchester corridors concentrate premium surgical capacity where property costs squeeze independent operator margins.
- Mobile Clinics:CQC-registered surgical units and diagnostic vehicles serving dispersed populations. Rural penetration across Northern England and Welsh border regions addresses access gaps without permanent facility investment.
- Community Centers:Localized health hubs co-locating multiple services. Manchester and Bristol pilots consolidate primary care, diagnostics, and minor surgery under single-site NHS contracts.
In-person visits retain the dominant cost base; telehealth is gaining share fastest.
Patient Type:
Volume distribution tracks England's demographic concentration and morbidity burden.
- Geriatrics:Patients aged 65+ requiring age-adjusted anesthesia protocols and fall-risk assessment. England's over-65 population growth concentrates demand in same-day orthopedic and ophthalmology procedures across Integrated Care Systems.
- Adults:Working-age patients aged 18-64 presenting elective and urgent care needs. Metropolitan corridor clinics capture employer-sponsored and NHS-referred volumes for musculoskeletal and gastrointestinal services.
- Pediatrics:Child and adolescent patients requiring specialist nursing ratios and family accommodation. Dedicated day-case units in London and Birmingham maintain pediatric anesthetist accreditation under General Medical Council frameworks.
- Special Needs Patients:Individuals with learning disabilities, autism, or complex behavioral requirements. Adapted environments in Manchester and Leeds reduce sedation needs through sensory-friendly design.
Geriatrics absorbs the bulk of procedure volume; special needs provision is climbing the fastest.
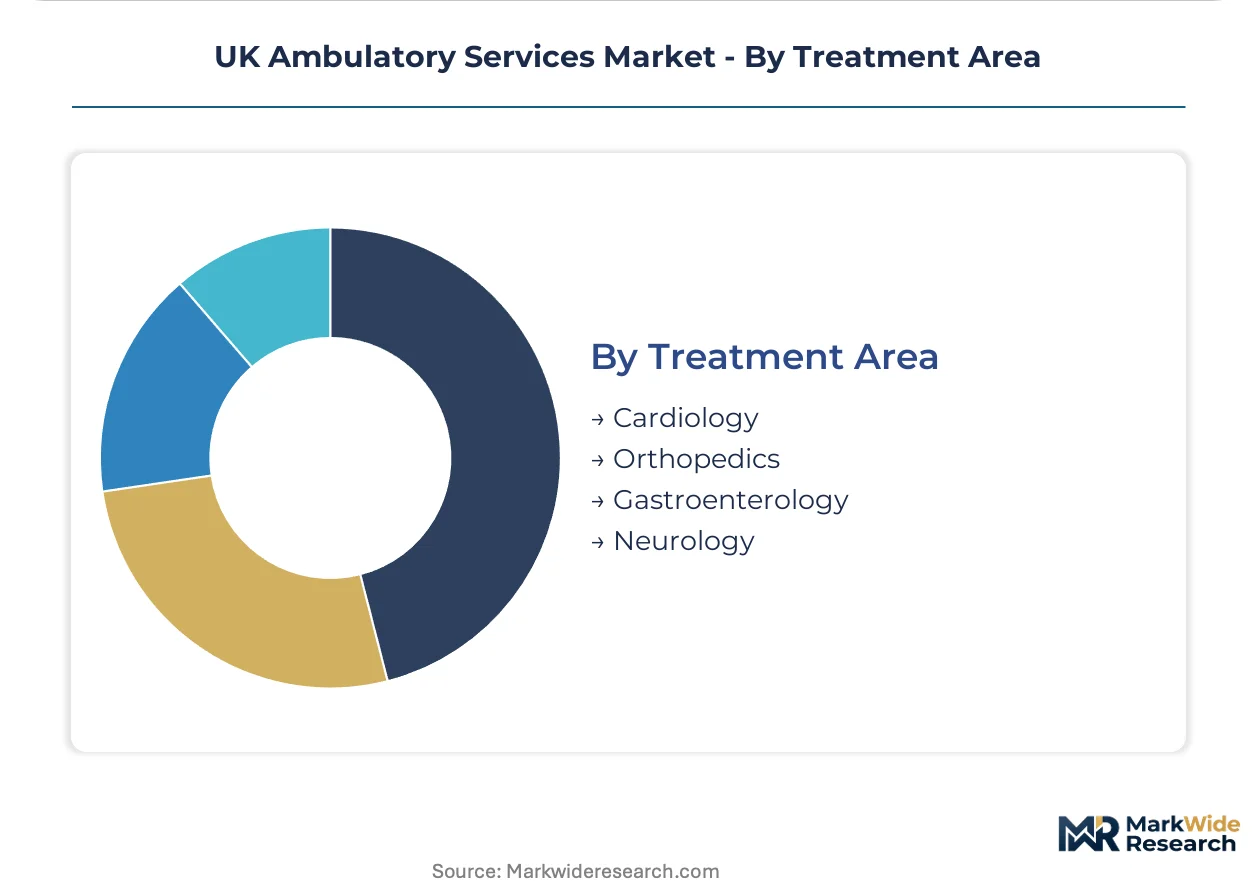
Treatment Area:
Margin concentration aligns with procedure reimbursement tiers and workforce specialization.
- Orthopedics:Arthroscopy, joint injection, and soft-tissue repair performed under regional or local anesthesia. Day-case hip and knee procedures expand across independent sector capacity under NHS England's waiting list reduction targets.
- Gastroenterology:Endoscopy and colonoscopy services with same-day sedation recovery. Screening program volumes concentrate in London and South East England where JAG accreditation determines NHS contract eligibility.
- Cardiology:Diagnostic electrophysiology and minor interventional procedures. Ambulatory arrhythmia monitoring shifts toward remote telemetry platforms integrated with NHS trusts.
- Neurology:Outpatient consultation and botulinum toxin injection for movement disorders. Deep specialization in London anchors complex case referral patterns.
Orthopedics carries the steepest expansion trajectory; cardiology is shifting fastest toward remote delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's Integrated Care Systems create distinct procurement zones that concentrate ambulatory investment around metropolitan hospital clusters. NHS England's elective recovery framework allocates capital differentially across these zones, shaping where independent providers establish surgical capacity.
London and Southeast England
Private surgical hospitals cluster along the M25 corridor to capture NHS waiting list referrals and self-pay orthopedics. The Care Quality Commission's London inspection team maintains stricter accreditation timelines for independent day-case units. HCA Healthcare U.K. and OneWelbeck anchor premium positioning in Harley Street and Westminster respectively.
Midlands
Birmingham and Leicester Integrated Care Systems pilot remote patient monitoring for orthopedic day-cases under NHS England's 2023/24 operational guidance. The Nursing and Midwifery Council's expanded scope protocols for physician associates enable staffing model flexibility in Coventry and Wolverhampton community surgical hubs.
North England
Manchester and Leeds concentrate independent sector capacity absorption under NHS elective recovery targets. Circle Health Group leverages its Yorkshire footprint to integrate digital triage with physical clinic access across the Pennine corridor. Property cost advantages versus London support margin retention for multi-site operators.
Scotland
NHS Scotland's separate contracting framework limits English independent provider penetration, though Glasgow and Edinburgh maintain private surgical capacity for insured and self-pay segments. The Scottish Government's National Elective Coordination Unit centralizes waiting list management, creating distinct referral dynamics from England's Integrated Care Board model.
Wales
Cardiff and Newport corridor clinics address cross-border patient flows from English border counties where NHS England commissioning creates access gaps. Welsh Government health policy emphasizes community-based care, though workforce supply constraints under General Medical Council registration rules cap expansion velocity.
UK Ambulatory Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across NHS and private pay segments. Market structure tilts toward consolidation as independent hospital groups absorb redirected elective volumes under NHS England's operational planning guidance. Three archetypes dominate: national surgical networks with CQC-registered multi-site capacity, NHS foundation trusts expanding day-case units, and integrated digital-physical platforms. Competitive moves center on workforce model innovation and same-site diagnostic-treatment pathway configuration.
Within the national surgical network tier, Spire Healthcare and HCA Healthcare U.K. exemplify scale-driven positioning across England's metropolitan corridor. Circle Health Group occupies a hybrid archetype combining regional physical presence with digital triage integration. Among NHS foundation trusts, Guy's and St Thomas' and Chelsea and Westminster anchor academic medical center positioning in London's premium segment.
| Leading Market Players |
|---|
| Spire Healthcare |
| HCA Healthcare U.K. |
| Circle Health Group |
| Guy's and St Thomas' NHS Foundation Trust |
| Aspen Healthcare |
| Practice Plus Group |
| OneWelbeck |
| Chelsea and Westminster Hospital NHS Foundation Trust |
| Brighton and Sussex University Hospitals NHS Foundation Trust |
| Others |
Cost & Logistics Intelligence
NHS England's elective recovery framework is redirecting surgical volumes toward independent sector capacity, forcing ambulatory providers to absorb redirected volumes under tariff constraints that compress margins regardless of procedure complexity. This procurement pressure concentrates pricing power among CQC-registered multi-site operators with existing NHS contracts, while squeezing independent clinic margins through national tariff ceilings.
Pricing Analysis
Short lead-time premiums for urgent NHS waiting list slots command tariff uplifts against standard elective scheduling, while spot capacity releases during winter pressure periods trade at discounted rates. Three-tier pricing structure across premium self-pay, standard insured, and economy NHS tariff levels segments patient access by payment source. Price differentiation hinges on JAG accreditation status for endoscopy services and Care Quality Commission inspection ratings for surgical units. Cost compression in standard NHS tiers is intensifying because Integrated Care Boards are consolidating contracts toward fewer, larger providers. Employer-sponsored musculoskeletal services show least price sensitivity; routine primary care consultations face greatest reimbursement pressure.
Supply Chain Analysis
Anesthetist supply rests on General Medical Council registration pathways that constrain workforce expansion regardless of capital investment in clinic infrastructure. Clinical consumables draw from domestic distributors and German, Dutch, and Irish medical device manufacturers serving NHS procurement frameworks. Single-source vulnerability concentrates in specialized orthopedic implants and endoscopy equipment where replacement timelines extend clinical downtime. Distribution runs through NHS Supply Chain central procurement for contracted providers, with independent operators sourcing through regional medical distributors serving London and Manchester metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as NHS England's contract consolidation favors scaled operators with CQC-registered multi-site networks, forcing sub-scale independents toward acquisition or exit.
For Market Incumbents: Deepen vertical integration into diagnostic imaging to capture same-site episode payments and reduce patient journey friction across orthopedic and gastroenterology pathways. Acquire CQC-registered surgical capacity in Northern England where property cost advantages support margin retention against London-based competitors. Workforce supply constraints under General Medical Council registration rules threaten expansion velocity; prioritize physician associate scope expansion under Nursing and Midwifery Council frameworks to optimize skill-mix ratios. For New Entrants and Emerging Players: Digital triage platforms offer the lowest capital route to NHS contract eligibility, enabling remote consultation capabilities that satisfy Integrated Care Board mandates before physical site investment. Target rural network penetration across Welsh border regions and Northern England where mobile surgical units address access gaps without permanent facility commitment. Pursue hub-and-spoke configurations that anchor community diagnostic hubs to existing NHS trust infrastructure. For Investors and Strategic Acquirers: The window for entry favors regional surgical networks with CQC accreditation and existing NHS contract relationships over greenfield development. Long-term viability centers on operators with demonstrated capacity to absorb redirected elective volumes under tariff constraints while maintaining quality metrics. Watch NHS Integrated Care Board commissioning shifts between direct provision and independent sector capacity as the inflection indicator for volume migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Workforce Model Innovation | Physician associate scope expansion under NMC frameworks enables skill-mix optimization against GMC-constrained specialist supply. |
| Integrated Diagnostic-Treatment Pathways | Same-site imaging and minor surgery capabilities reduce patient journey friction and capture higher-value episode payments. |
| Digital Infrastructure Interoperability | NHS electronic health record integration requires capital-intensive IT adaptation that determines contract eligibility. |
| Rural Network Penetration | CQC-registered mobile surgical units address access gaps across Northern England without permanent facility investment. |
| Quality Assurance Standardization | Care Quality Commission inspection variability across regions creates operational uncertainty requiring multi-site compliance investment. |
Research Approach
Multi-period observation of NHS waiting list volumes, tariff reimbursement rates, and CQC registration patterns anchored the trend analysis, supplemented by interviews with Integrated Care Board commissioning directors, independent sector operations executives, hospital procurement managers, and biomedical engineering leads. Secondary validation drew from NHS England operational planning guidance, Care Quality Commission inspection reports, General Medical Council workforce statistics, and Nursing and Midwifery Council scope-of-practice documentation. Bottom-up modeling of clinic capacity and patient throughput triangulated against top-down expenditure analysis across Integrated Care Systems.
Segment-weighting across service type, delivery mode, patient demographics, and treatment area dimensions shaped volume and value outputs across the projection horizon. CAGRs were derived from procedure volume trajectories, tariff inflation assumptions, and demographic demand modeling. NHS elective recovery targets, telehealth pathway mandates, and workforce supply constraints served as primary forecast inputs.
The model holds under stable NHS commissioning frameworks and continued tariff-indexed reimbursement; deviation in Integrated Care Board procurement centralization or workforce registration policy shifts would revise capacity expansion assumptions. A small set of triggers—NHS contract consolidation velocity, CQC inspection regime changes, and digital health interoperability mandates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Vaccine Logistics Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Patient Transportation Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
US Registered Nurses Market