
 Tonsil Cancer Market | 2026-2036
Tonsil Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Tonsil Cancer Market Analytics
Adjuvant therapy revenue is fragmenting across branded biologics and biosimilar entrants. AstraZeneca leverages its checkpoint inhibitor portfolio to sustain premium positioning in recurrent settings. Merck & Co. anchors its presence through broad PD-1 label expansion, while Bristol-Myers Squibb competes via combination regimens in locally advanced disease.
Tonsil cancer comprises malignant neoplasms arising from the palatine or lingual tonsillar tissue, predominantly squamous cell carcinoma with HPV-positive or HPV-negative molecular subtypes, staged by TNM criteria and treated through multimodal protocols combining systemic agents with precision radiotherapy. Immunotherapy now leads growth among product types as PD-1/PD-L1 inhibitors displace conventional chemotherapy in first-line recurrent and metastatic indications. Hospitals capture the dominant share of end users due to integrated surgical, medical, and radiation oncology infrastructure, though ambulatory surgical centers are expanding their role in early-stage resection and same-day systemic administration.
FDA oncology center guidance governs accelerated approval pathways and confirmatory trial requirements for novel tonsil cancer therapeutics, while EMA's Committee for Medicinal Products for Human Use shapes conditional marketing authorization standards across European markets. The National Comprehensive Cancer Network guidelines function as de facto reimbursement gatekeepers in the United States, directly influencing payer coverage decisions and prescriber behavior. Stakeholders must monitor biomarker-driven trial designs and real-world evidence generation requirements as regulators tighten evidentiary standards for accelerated pathways.
Market Dynamics
PD-1/PD-L1 checkpoint inhibitors are compressing treatment timelines and redistributing revenue from chemotherapy infusion centers toward outpatient immunotherapy administration, fundamentally restructuring how oncology networks configure their service lines and capital deployment.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA Oncology Center's streamlined review mechanisms for breakthrough therapies compress development-to-commercialization cycles for novel tonsil cancer biologics.
- HPV-Positive Subtype Prevalence:Shifting etiology patterns toward HPV-driven disease create larger addressable populations with favorable immunotherapy response profiles in tertiary hospital networks.
- Precision Radiotherapy Integration:Image-guided adaptive radiation systems enable dose escalation to tonsillar beds while sparing adjacent critical structures, expanding curative-intent treatment candidacy.
Market Restraints
- Biologic Manufacturing Concentration:Monoclonal antibody production for checkpoint inhibitors concentrates among a limited number of contract manufacturing organizations, creating supply vulnerability.
- Reimbursement Compression:CMS National Coverage Determination processes impose documentation burdens that delay novel therapy access in community oncology practices.
- Specialized Workforce Scarcity:Head and neck surgical oncologists and radiation oncologists with oropharyngeal expertise remain concentrated in academic medical centers, limiting geographic reach.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:Same-day tonsillectomy and early-stage resection protocols enable procedure migration from inpatient settings, capturing margin from facility fee differentials.
- Biomarker-Driven Trial Design:PD-L1 expression and tumor mutational burden stratification create registrational pathways for combination regimens in molecularly selected populations.
- Real-World Evidence Generation:Flatiron Health and similar oncology data platforms enable post-marketing efficacy documentation that satisfies FDA confirmatory trial requirements for accelerated approvals.
Industry Challenges
- Multidisciplinary Care Coordination:Integrated medical, surgical, and radiation oncology workflows require information system interoperability that remains fragmented across hospital networks.
- Immunotherapy Resistance Mechanisms:Primary and acquired resistance to PD-1 blockade in HPV-negative subtypes necessitate combination strategy development with unproven toxicology profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tonsil Cancer Market |
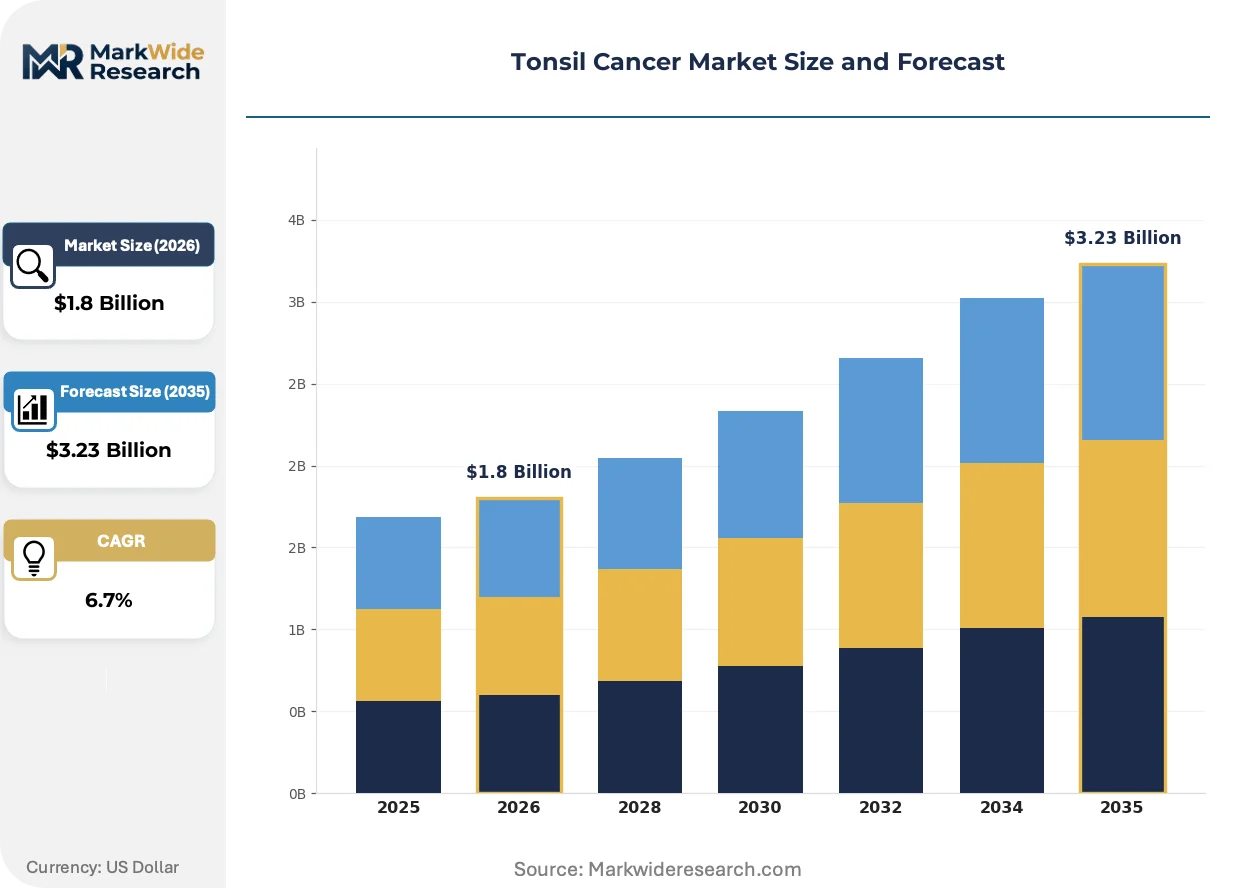
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Research Institutions Treatment Stage: Early Stage, Locally Advanced, Recurrent, Metastatic Delivery Mode: Oral, Intravenous, Topical, Subcutaneous |
| Companies Covered | AstraZeneca plc, Amgen Inc., F. Hoffmann-La Roche Ltd, Johnson & Johnson (Janssen Pharmaceuticals), Pfizer Inc., Merck & Co., Inc., Novartis AG, AbbVie Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tonsil Cancer Market Evolving Landscape
Digital pathology and artificial intelligence are compressing diagnostic timelines while liquid biopsy platforms enable real-time treatment monitoring, collectively shifting clinical decision-making from empirical protocols toward dynamically adaptive precision approaches.
Artificial intelligence-powered histopathology analysis is virtualizing traditional diagnostic workflows by automating HPV status prediction from hematoxylin and eosin slides. Academic pathology departments at tertiary centers are deploying these algorithms to reduce turnaround times for molecular stratification. The technology is virtualizing the need for separate p16 immunohistochemistry testing in a substantial fraction of cases, compressing diagnostic costs and accelerating treatment initiation.
The FDA's Project Optimus initiative is reshaping dose-selection methodologies for oncology therapeutics by mandating randomized dose-comparison studies rather than relying solely on maximum-tolerated dose paradigms. This regulatory evolution forces developers to invest in expanded early-phase cohorts before advancing to registrational trials. Biopharma sponsors with tonsil cancer programs are responding by embedding pharmacokinetic-pharmacodynamic modeling into Phase I designs to justify selected doses to review divisions.
Consolidated purchasing by integrated delivery networks is concentrating formulary control among fewer decision-makers, displacing traditional prescriber-level autonomy in product selection. National cancer center networks are negotiating system-wide contracts for checkpoint inhibitors that override individual physician preferences. This concentration is most visible in the United States, where NCCN guideline adherence functions as a de facto procurement standard across member institutions.
Tonsil Cancer Market Segmentation
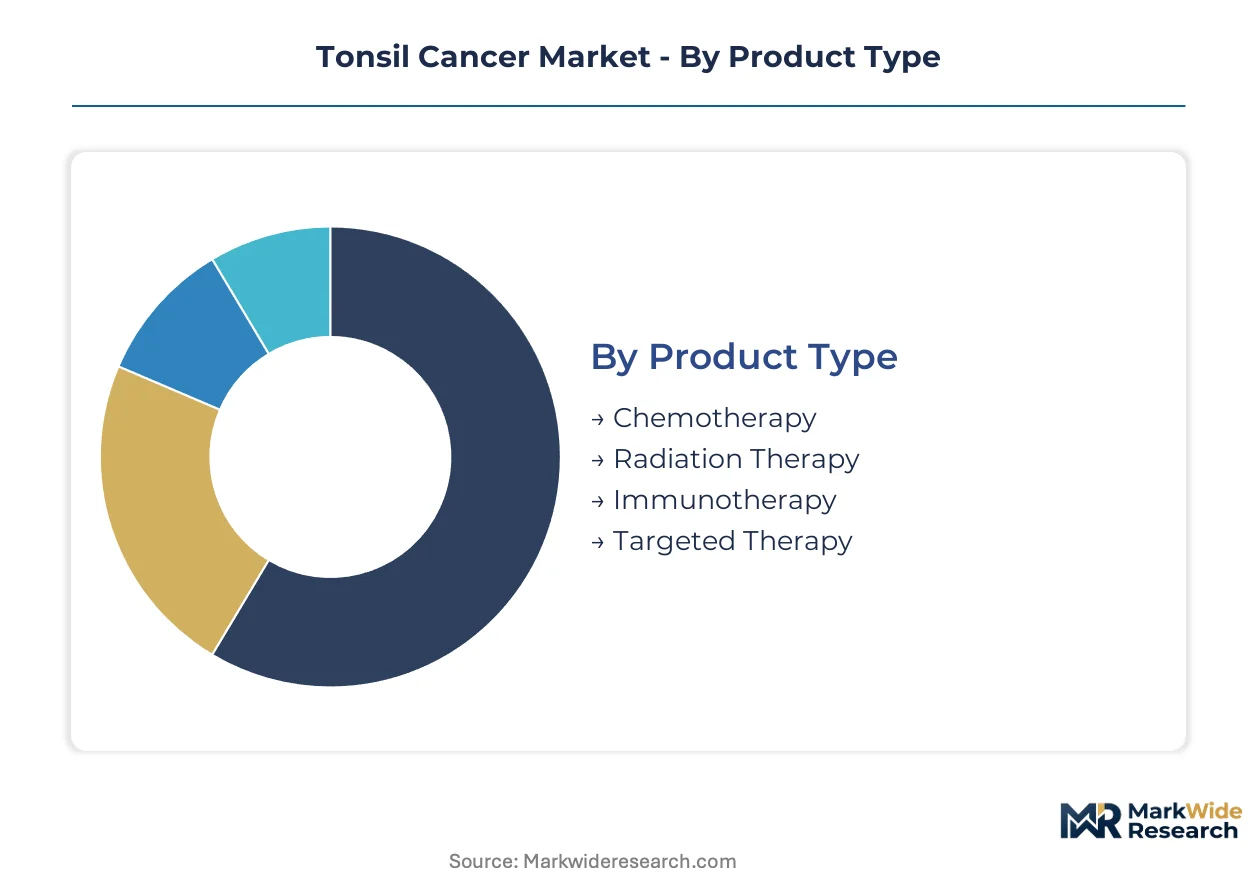
Tonsil cancer treatment protocols demand precise alignment between disease stage, molecular profile, and care setting. Segmentation reveals how revenue concentrates across modality combinations and how service line configurations reshape competitive positioning in oncology networks.
Product Type:
Use cases span curative-intent multimodal regimens through palliative systemic control, with each modality occupying distinct positions in treatment sequencing algorithms.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors deliver durable responses in HPV-positive recurrent disease through immune microenvironment modulation. Demand concentrates in tertiary hospital networks across the United States and Germany as NCCN and EMA guidance reshape first-line standards. The modality is displacing chemotherapy in metastatic indications where biomarker selection identifies responsive populations.
- Radiation Therapy:Image-guided adaptive systems enable dose escalation to tonsillar beds while sparing adjacent critical structures through fractionation optimization. Demand clusters in academic medical centers with integrated proton and photon capabilities, driven by precision radiotherapy integration mandates in Japan and specialized workforce concentration constraints.
- Chemotherapy:Platinum-taxane combinations retain adjuvant positioning in HPV-negative locally advanced protocols despite immunotherapy encroachment.
- Targeted Therapy:EGFR inhibitors and angiogenesis modulators serve niche roles in combination regimens for immunotherapy-refractory cases.
Established volume favors radiation therapy; emerging adoption favors immunotherapy.
End User:
Service delivery infrastructure determines patient flow and reimbursement capture across the care continuum.
- Hospitals:Integrated surgical, medical, and radiation oncology infrastructure enables complex multimodal coordination for locally advanced cases. Demand concentrates in NCCN-designated cancer centers across the United States and university hospitals in Germany, driven by specialized workforce scarcity and CMS facility fee structures.
- Oncology Clinics:Community-based infusion centers deliver systemic therapy with lower overhead, capturing stable disease monitoring and maintenance regimens.
- Ambulatory Surgical Centers:Same-day tonsillectomy and early-stage resection protocols enable procedure migration from inpatient settings. Adoption accelerates in United States markets where facility fee differentials reward outpatient migration and where integrated delivery network purchasing concentrates formulary control.
- Research Institutions:Academic medical centers host biomarker-driven trials and real-world evidence generation platforms that satisfy FDA confirmatory requirements.
Procedure volume concentrates in hospitals; margin expansion favors ambulatory surgical centers.
Treatment Stage:
Disease extent dictates curative versus palliative intent and determines modality intensity.
- Locally Advanced:Stage III-IVA disease requires concurrent chemoradiation or surgery followed by adjuvant therapy, representing the highest per-patient revenue intensity. Demand clusters where multidisciplinary tumor boards coordinate trimodal protocols, constrained by information system interoperability gaps.
- Early Stage:T1-T2 N0-N1 disease permits single-modality surgery or radiation with favorable functional outcomes.
- Recurrent:Salvage surgery, re-irradiation, or systemic therapy in previously treated fields demands specialized expertise concentrated in referral centers.
- Metastatic:Palliative systemic therapy prioritizes quality of life and symptom control through outpatient administration.
Revenue intensity peaks in locally advanced; clinical unmet need concentrates in recurrent.
Delivery Mode:
Administration route shapes care setting requirements and patient compliance profiles.
- Intravenous:Checkpoint inhibitors and cytotoxic agents require infusion center infrastructure with nursing supervision for hypersensitivity monitoring. Volume concentrates in hospital-based infusion suites and oncology clinics with pharmacy compounding capabilities.
- Oral:Tyrosine kinase inhibitors and chemotherapy prodrugs enable home administration with periodic monitoring.
- Subcutaneous:Emerging formulations of monoclonal antibodies reduce infusion duration and enable ambulatory administration.
- Topical:Limited application in tonsil cancer due to anatomic accessibility constraints.
Infusion dependence favors intravenous; convenience and cost pressures favor subcutaneous migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across national reimbursement frameworks. Germany and Japan absorb premium immunotherapy pricing through centralized health technology assessments, while United States community oncology practices face prior authorization friction that compresses access timelines.
United States
NCCN-designated cancer centers concentrate immunotherapy demand through integrated multidisciplinary protocols. FDA Oncology Center breakthrough therapy designations compress commercialization cycles for novel checkpoint inhibitors. Academic medical clusters in Boston, Houston, and New York anchor biomarker-driven trial enrollment that satisfies confirmatory requirements.
Germany
University hospital networks dominate complex oropharyngeal surgical oncology through concentrated head and neck specialist workforce. EMA conditional marketing authorization pathways enable early patient access pending Phase III completion. The Heidelberg-Mannheim corridor hosts real-world evidence platforms that document post-marketing efficacy for IQWiG reimbursement dossiers.
Japan
PMDA sakigake designation accelerates regulatory review for combination regimens in HPV-positive populations. Precision radiotherapy adoption concentrates in Tokyo and Osaka metropolitan tertiary centers with proton beam capabilities. METI industrial policy supports domestic manufacturing of monoclonal antibodies to reduce import dependence.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that delay novel therapy access outside Cancer Drugs Fund coverage. NHS England specialized commissioning concentrates tonsil cancer surgery in designated head and neck centers across London, Manchester, and Birmingham. The UK Biobank and Genomics England infrastructure enables population-scale biomarker discovery for trial stratification.
India
CDSCO accelerated approval pathways for biosimilar checkpoint inhibitors expand addressable patient volumes through price-competitive positioning. Tata Memorial Centre in Mumbai and All India Institute of Medical Sciences in Delhi anchor surgical oncology training and clinical trial networks. State government health insurance schemes in Maharashtra and Tamil Nadu are expanding coverage for targeted therapies in public hospital systems.
Tonsil Cancer Market Competitive Landscape
Capability concentration sits with large-cap biopharmaceuticals commanding integrated oncology portfolios; scale advantage sits with mid-tier specialists leveraging regional regulatory expertise. The competitive structure tiered across three archetypes: checkpoint inhibitor portfolio holders, precision radiotherapy system manufacturers, and biosimilar developers exploiting patent cliffs. Dominant competitive moves include M&A for pipeline augmentation and strategic partnerships for real-world evidence generation platforms.
Within the checkpoint inhibitor tier, AstraZeneca plc and Merck & Co., Inc. occupy positions defined by PD-1/PD-L1 label breadth, while Bristol-Myers Squibb Company exemplifies combination regimen development in locally advanced indications. F. Hoffmann-La Roche Ltd anchors diagnostic-therapeutic integration through companion testing infrastructure. These entities represent the consolidation logic driving oncology portfolio assembly.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson (Janssen Pharmaceuticals) |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Cambridge, Massachusetts anchors monoclonal antibody manufacturing capacity for checkpoint inhibitors, with facility utilization rates directly shaping downstream pricing power for oncology networks negotiating system-wide contracts.
Pricing Analysis
Extended service contracts for biomarker testing and patient monitoring drive lifetime value capture beyond drug acquisition costs. Three-tier pricing structure across premium, standard, and economy levels separates branded checkpoint inhibitors from biosimilar entrants and regional generics. Price differentiation hinges on NCCN guideline adherence tier and companion diagnostic bundling. Pricing pressure stems from CMS National Coverage Determination documentation burdens that delay novel therapy access. Community oncology practices exhibit highest price sensitivity; academic medical centers with research funding demonstrate lowest.
Supply Chain Analysis
Lonza, Samsung Biologics, and Boehringer Ingelheim hold contract manufacturing capacity for monoclonal antibody production. Supply concentrates in Switzerland, South Korea, and Germany with secondary capabilities in the United States and Ireland. Raw material dependencies include Chinese-sourced recombinant proteins, German-engineered bioreactor systems, and Singapore-based filtration media. Single-source vulnerability for cell line development creates supply chain risk. Distribution runs through specialty pharmacy networks with cold-chain logistics mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated head and neck surgical expertise remains concentrated in fewer than 200 academic medical centers globally, creating structural bottlenecks that constrain market expansion regardless of therapeutic innovation.
For Market Incumbents: Entrench position through captive bioreactor capacity additions in Singapore and Switzerland, insulating against contract manufacturing concentration risk. Secure exclusive real-world evidence generation partnerships with Flatiron Health and similar oncology data platforms to satisfy FDA confirmatory trial requirements. Deepen relationships with NCCN guideline committee members to influence reimbursement gatekeeping standards before biosimilar entrants achieve formulary parity. For New Entrants and Emerging Players: Pursue ambulatory surgical center partnerships in United States markets where facility fee differentials reward outpatient migration and integrated delivery network purchasing concentrates decision-making. Target early-stage tonsil cancer resection protocols as the most penetrable segment, leveraging same-day discharge protocols and lower capital requirements. Deploy subcutaneous formulation development as a differentiated go-to-market angle against intravenous-dependent incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic-therapeutic integrators with companion testing infrastructure and biomarker-driven trial capabilities. Long-term viability over a multi-year horizon rests on regulatory navigation expertise across FDA, EMA, and PMDA accelerated approval pathways. Acquisition target archetype: mid-tier biopharma with Phase II checkpoint inhibitor assets in HPV-positive indications. Watch FDA Project Optimus dose-optimization mandates as an inflection signal for expanded early-phase investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Driven Trial Design | PD-L1 stratification enables registrational pathways in molecularly selected populations per FDA guidance. |
| Real-World Evidence Generation | Flatiron Health partnerships document post-marketing efficacy for accelerated approval confirmatory requirements. |
| Ambulatory Surgical Center Expansion | Same-day resection protocols capture margin from facility fee differentials in United States markets. |
| Subcutaneous Formulation Development | Reduced infusion duration enables ambulatory administration against intravenous-dependent competitors. |
| Companion Diagnostic Integration | p16 immunohistochemistry automation compresses diagnostic timelines and accelerates treatment initiation. |
Research Methodology
Initial hypotheses were tested against primary input from head and neck surgical oncologists, radiation oncology department chairs, formulary directors at integrated delivery networks, and payer access specialists, then refined through secondary validation against FDA oncology center guidance documents, EMA Committee for Medicinal Products for Human Use opinions, ClinicalTrials.gov registry entries, and NCCN guideline version histories. Bottom-up patient flow modeling and top-down revenue triangulation converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning treatment stage, molecular subtype, delivery mode, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline incidence and prevalence estimates. Forecast inputs incorporated HPV-positive subtype prevalence shifts, precision radiotherapy adoption curves, and immunotherapy displacement rates in metastatic indications.
Sensitivities concentrate around FDA confirmatory trial requirement tightening, biosimilar checkpoint inhibitor launch timing, and specialized workforce expansion rates. Forecasts reflect documented assumptions about regulatory pathway durations and reimbursement policy stability. Quarterly review of NCCN guideline update cadence, FDA breakthrough therapy designation grants, and CMS National Coverage Determination timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Synovial Sarcoma Market