
 Global Cancer Registry Software Market | 2026-2036
Global Cancer Registry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Registry Software Market Foresight
ISO 27001 certification is bifurcating the vendor landscape into enterprise-ready suppliers and regional challengers. Elekta leverages its installed base in radiation oncology to extend registry software into integrated care pathways. IBM anchors its position through Watson Health analytics layered on legacy hospital data architectures. McKesson Corporation dominates North American distribution channels with deep EHR connectivity.
Cancer registry software comprises specialized data collection, curation, and reporting platforms engineered to capture standardized tumor pathology, staging, treatment, and outcome variables per protocols such as NAACCR standards. These systems enable longitudinal patient tracking, population-level epidemiology, and regulatory reporting for national cancer control programs. Cloud-based deployment is capturing the fastest expansion as health systems abandon capital-intensive on-premise infrastructure for subscription models with automatic standard updates. Reporting and analytics solutions concentrate margin pools where AI-augmented surveillance dashboards command premium pricing from government agencies and research institutes. Patient tracking applications remain mature with slower replacement cycles in established markets.
FDA 21 CFR Part 11, HIPAA, and EU GDPR collectively shape product development roadmaps by mandating audit trails, consent management, and cross-border data transfer protocols. EMA's expanded pharmacovigilance requirements and WHO's Global Initiative for Cancer Registry Development are accelerating demand for interoperable, multi-jurisdiction platforms. Stakeholders must evaluate whether their data architectures can absorb impending ICH E2B R3 compliance obligations without fragmenting patient records across incompatible national systems.
Market Dynamics
Cloud-native deployment is compressing replacement cycles for cancer registry platforms as hospital networks abandon perpetual licenses for subscription models with embedded compliance updates. This shift concentrates purchasing authority within health system IT governance committees rather than departmental oncology leads.
Growth Catalysts
- Interoperability Mandates:HIPAA and 21 CFR Part 11 in the United States require audit-ready data trails that cloud registry platforms automate. Hospital procurement committees prioritize vendors with pre-certified compliance architectures.
- Pharmacovigilance Expansion:EMA's tightened adverse-event reporting obligations for oncology therapeutics create demand for longitudinal patient tracking. Registry software captures treatment-outcome pairs that sponsors must submit.
- Population Health Analytics:National cancer control programs in Germany and Japan mandate standardized incidence reporting. Government agencies fund infrastructure upgrades to meet WHO Global Initiative targets.
Market Restraints
- Data Sovereignty Friction:EU GDPR restricts cross-border patient record transfers. Multi-national hospital networks face architectural fragmentation when linking registries across member states.
- Specialized Talent Scarcity:Clinical informaticists with dual oncology and health IT expertise command premium compensation. Vendor implementation timelines stretch when qualified staff are unavailable.
- Legacy System Entrenchment:Decades of on-premise registry data in proprietary formats create migration costs. Health systems defer cloud transitions when decommissioning budgets compete with clinical priorities.
Strategic Opportunities
- AI-Augmented Surveillance:Machine learning models trained on registry data identify recurrence patterns earlier than rule-based alerts. Research institutes pay premium subscriptions for predictive dashboards.
- Low-Code Configuration:Modular platforms allow cancer centers to adapt workflows without vendor dependency. This reduces implementation costs for mid-tier community hospitals.
- Real-World Evidence Integration:Linking registry records with claims and pharmacy data creates comprehensive patient journeys. Pharmaceutical manufacturers seek these datasets for label expansion submissions.
Industry Challenges
- Multi-Jurisdiction Compliance:Vendors must maintain parallel certification tracks for FDA, EMA, and PMDA requirements. Feature roadmaps fragment when national regulators impose conflicting data standards.
- Interoperability Testing Burden:Each health system's EHR configuration demands custom interface validation. Implementation teams spend disproportionate effort on HL7 FHIR mapping rather than core registry functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Registry Software Market |
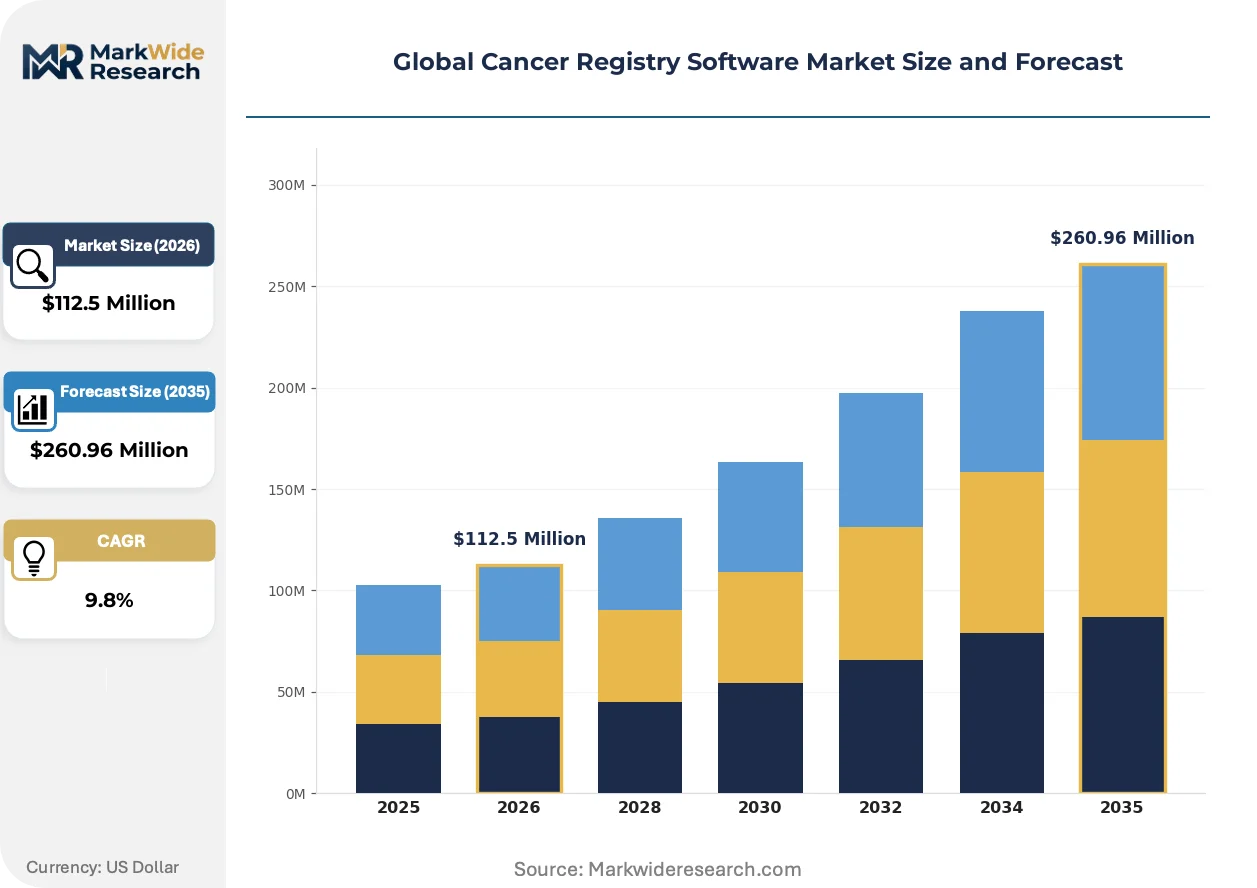
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $260.96 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premise, Hybrid, Virtual Private Server Solution Type: Data Management, Reporting & Analytics, Patient Tracking, Compliance Monitoring, Integration Application: Epidemiology Research, Clinical Trials Management, Public Health Surveillance, Healthcare Planning End User: Cancer Centers, Research Institutes, Government Agencies, Health Insurance Providers, NGOs |
| Companies Covered | Elekta, McKesson Corporation, IBM, Oracle, Conduent, Inc., C/NET Solutions, ONCO, Inc., Rocky Mountain Cancer Data Systems, Health Catalyst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Registry Software Market Shifts & Advancements
Federated data architectures are displacing centralized repository models as privacy-preserving analytics gain traction among multi-site research networks. This shift redefines competitive advantage around governance tooling rather than storage scale.
Natural language processing is fragmenting pathology report curation by extracting structured staging data from unstructured clinical notes. Academic medical centers deploy these tools to reduce manual abstraction backlogs. The technology compresses registry update latency from months to days, enabling near-real-time surveillance.
EU MDR and GDPR convergence is forcing vendors to embed privacy-by-design into core platform architecture. Products must demonstrate data minimization and purpose limitation at the code level. European hospital procurement now requires third-party certification of these controls before contract execution.
Subscription pricing is displacing perpetual licensing across North American and European health systems. Finance departments prefer operational expenditure classification for software assets. Oncology departments lose capital budget autonomy as IT governance centralizes vendor selection.
Global Cancer Registry Software Market Segmentation
Cancer registry software segmentation reveals how procurement authority and margin capture shift across deployment models, solution architectures, and institutional buyer types. Understanding these fault lines exposes where vendors concentrate R&D investment versus where price competition erodes returns.
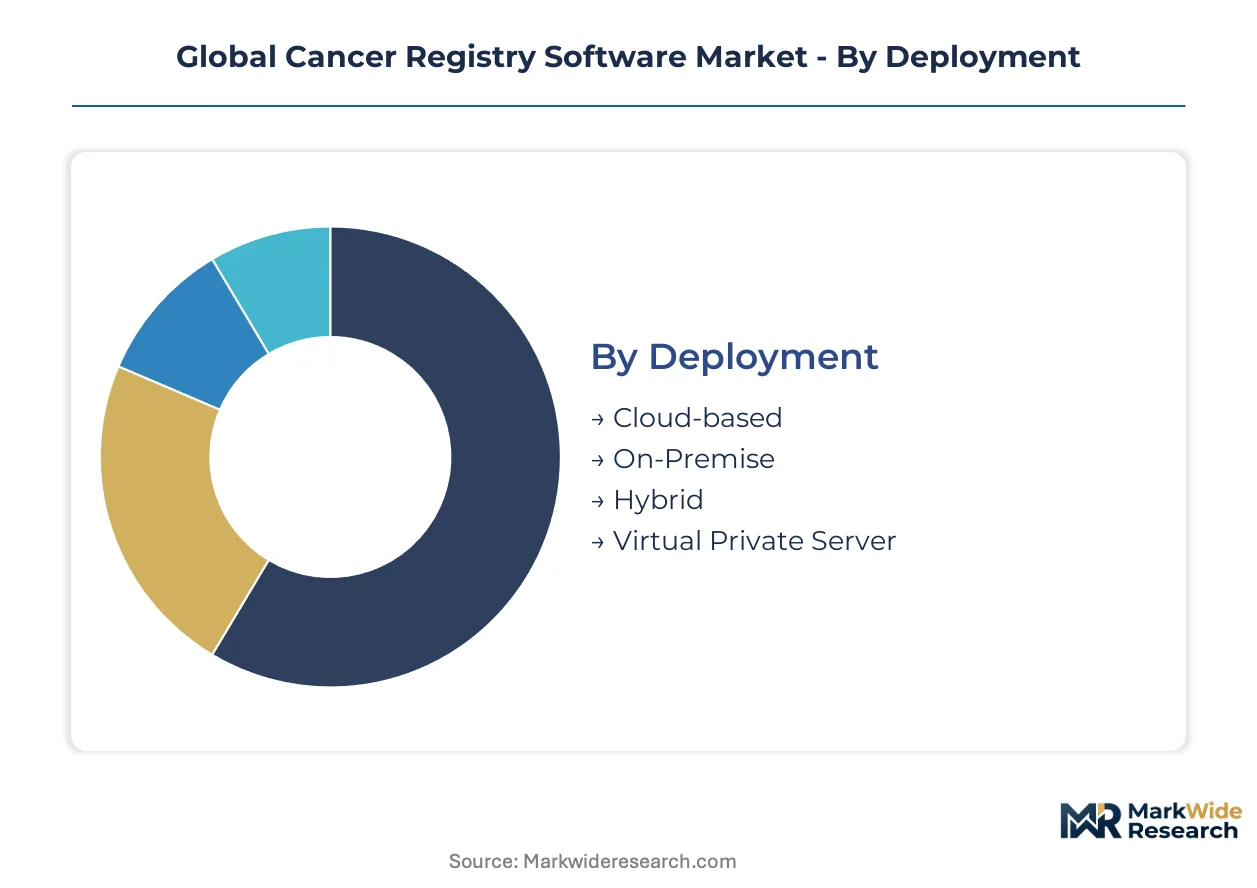
Deployment:
Margin pools concentrate in recurring revenue streams where automatic compliance updates lock health systems into long-term subscription relationships.
- Cloud-based:Multi-tenant SaaS architectures with embedded HIPAA and GDPR compliance automation command premium pricing from hospital networks. Procurement committees in the United States and Germany prioritize these platforms to eliminate capital expenditure cycles and ensure continuous NAACCR standard updates without manual patching.
- On-Premise:Perpetual license models with localized data sovereignty appeal to national cancer institutes in Japan and France where patient record export restrictions are stringent. These deployments carry higher upfront implementation costs but satisfy institutional requirements for physical data control.
- Hybrid:Split architectures keep sensitive pathology data on-site while pushing analytics workloads to cloud infrastructure.
- Virtual Private Server:Single-tenant cloud instances balance isolation requirements with operational expenditure classification.
On-premise systems hold installed capacity. Cloud-based deployment is rotating up the share rankings.
Solution Type:
Application sophistication determines pricing tiers, with AI-augmented modules separating premium vendors from commodity data repositories.
- Reporting & Analytics:Dashboard platforms with machine learning-powered recurrence detection and population surveillance visualizations attract research institute budgets. Government agencies in Germany fund these capabilities to meet WHO Global Initiative reporting targets.
- Data Management:Core registry infrastructure for standardized tumor pathology capture and longitudinal patient record curation forms the foundation layer.
- Patient Tracking:Mature follow-up workflow tools with automated survival status updates see slower replacement demand in established markets.
- Compliance Monitoring:Audit trail engines with 21 CFR Part 11 electronic signature support address FDA-regulated clinical trial use cases.
- Integration:HL7 FHIR middleware and EHR connectivity layers absorb disproportionate implementation effort.
Data management holds installed capacity. Reporting and analytics is rotating up the share rankings.
Application:
Budget authority varies sharply by use case, with pharmaceutical-funded clinical trials commanding higher per-seat pricing than public health surveillance.
- Clinical Trials Management:Registry platforms capturing treatment-outcome pairs for EMA pharmacovigilance submissions integrate with sponsor data management systems. Academic medical centers in Switzerland and the United Kingdom deploy these for oncology therapeutic development partnerships.
- Epidemiology Research:Population-level incidence analysis tools with standardized NAACCR output formats serve national cancer control program mandates.
- Public Health Surveillance:Real-time outbreak detection and cluster identification modules receive government agency procurement.
- Healthcare Planning:Resource allocation forecasting based on registry-derived incidence projections supports hospital network expansion decisions.
Epidemiology research holds installed capacity. Clinical trials management is rotating up the share rankings.
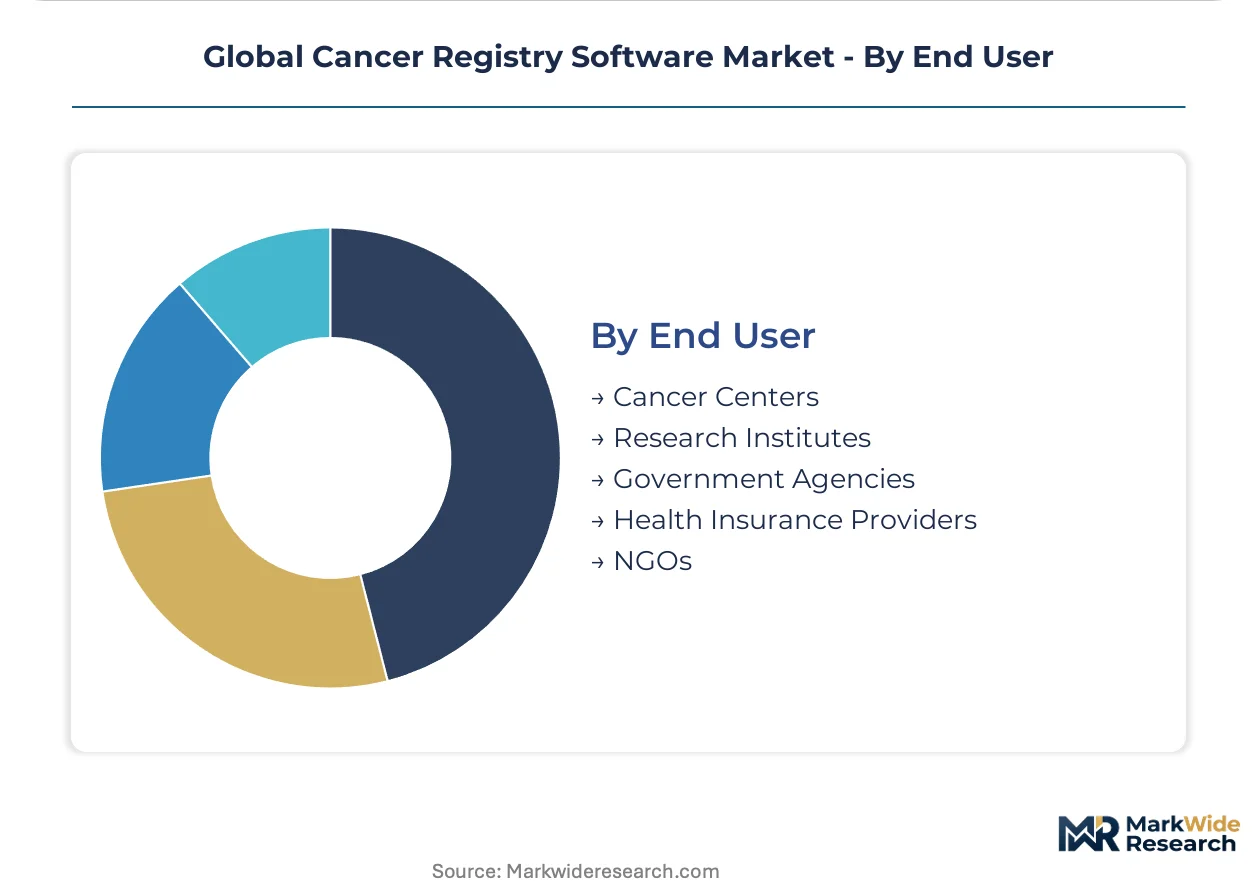
End User:
Customer concentration and procurement sophistication create divergent sales cycle dynamics across institutional categories.
- Cancer Centers:Comprehensive oncology departments with integrated radiation and medical oncology units demand end-to-end registry-to-treatment workflow integration. Elekta's installed base in radiation therapy equipment creates cross-sell opportunities for registry platforms in these settings.
- Government Agencies:National cancer institutes and health ministries fund infrastructure standardization to meet international reporting obligations.
- Research Institutes:Academic medical centers with NIH or European Research Council grants prioritize federated data architectures for multi-site studies.
- Health Insurance Providers:Payers analyzing registry-linked claims data for outcome-based contracting represent emerging demand.
- NGOs:Cancer advocacy organizations with patient navigation programs require lightweight, low-cost tracking tools.
Cancer centers hold installed capacity. Research institutes is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for cancer registry platforms, driven by national cancer control program mandates and evolving interoperability requirements.
United States
FDA 21 CFR Part 11 and HIPAA compliance requirements drive cloud-native procurement among hospital networks seeking audit-ready data trails. The National Cancer Institute funds infrastructure standardization through SEER program expansions. Academic medical centers in Boston and Houston deploy federated data architectures for multi-site oncology research.
Germany
Population health analytics investments from the Robert Koch Institute accelerate standardized incidence reporting infrastructure. EU MDR and GDPR convergence forces privacy-by-design certification into procurement specifications. Cancer registries in Bavaria and North Rhine-Westphalia lead cloud migration among German hospital networks.
Japan
PMDA pharmacovigilance requirements for oncology therapeutics create demand for longitudinal patient tracking platforms. METI industrial policy supports health IT modernization in university hospitals. The Kanto region around Tokyo concentrates registry software deployment for national cancer control program compliance.
United Kingdom
NHS Digital interoperability mandates push cancer centers toward HL7 FHIR-connected registry platforms. The National Disease Registration Service consolidates reporting infrastructure across England. Research institutes in London and Manchester prioritize AI-augmented surveillance dashboards for population-level epidemiology.
Switzerland
Swissmedic expanded pharmacovigilance obligations drive clinical trials management procurement among academic medical centers. Federal data protection law restricts cross-border patient record transfers to EU-compatible platforms. Basel and Zurich hospital networks anchor registry software demand for pharmaceutical partnership programs.
Global Cancer Registry Software Market Competitive Landscape
Player mix skews toward diversified health IT conglomerates with established EHR connectivity, though specialized oncology workflow vendors retain defensible positions in radiation therapy-integrated settings. Market structure concentrates margin capture among three archetypes: cloud-native SaaS platforms with embedded compliance automation, legacy enterprise systems with deep hospital data architecture penetration, and radiation oncology equipment vendors extending into care pathway software. Dominant competitive moves include strategic partnerships with national cancer institutes for registry infrastructure tenders and portfolio diversification into AI-augmented analytics modules.
Within the diversified health IT tier, McKesson Corporation and Oracle occupy positions anchored by North American distribution channel control and enterprise database architecture penetration respectively. Elekta exemplifies the radiation oncology equipment-to-software extension archetype, leveraging installed base relationships in integrated cancer centers. IBM represents the legacy analytics layering approach, positioning Watson Health capabilities atop existing hospital data infrastructure. These three anchors demonstrate how vendor origin—health IT conglomerate, medical equipment manufacturer, and technology platform company—shapes competitive trajectory in registry software procurement cycles.
| Leading Market Players |
|---|
| Elekta |
| McKesson Corporation |
| IBM |
| Oracle |
| Conduent, Inc. |
| C/NET Solutions |
| ONCO, Inc. |
| Rocky Mountain Cancer Data Systems |
| Health Catalyst |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservations with automatic compliance indexation lock hospital networks into predictable operational expenditure cycles while securing vendor revenue visibility across multi-year contracts. This structure concentrates pricing power among cloud-native platform providers who embed HIPAA and GDPR certification costs into recurring fees.
Pricing Analysis
Cost-plus contracts with NAACCR standard update indexation dominate enterprise procurement in the United States and Germany. Three-tier pricing structure across premium AI-augmented analytics, standard compliance automation, and economy data management tiers separates research institutes from community hospitals. Pricing pressure stems from mid-tier buyers consolidating vendor relationships to reduce interface integration costs. Government agencies exhibit lowest price sensitivity due to grant-funded infrastructure mandates, while independent oncology practices face acute budget constraints.
Supply Chain Analysis
HL7 FHIR interoperability certification bottlenecks in North American health IT channels constrain vendor onboarding velocity. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning anchored in AWS and Azure data regions. The supply chain draws from specialized clinical informaticist labor pools, open-source healthcare interoperability frameworks, and third-party audit certification services. Single-source vulnerability exists in EHR connectivity middleware where Epic and Cerner control dominant interface protocols. Distribution runs through health system IT governance committees rather than departmental procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as federated data architectures displace centralized repositories, with interoperability ecosystems becoming the primary value capture mechanism.
For Market Incumbents: Consolidate cloud-native compliance automation capabilities to defend against specialized AI entrants. Deepen EHR connectivity layers through direct HL7 FHIR engineering investment rather than third-party middleware dependency. Lock in long-term subscription renewals by embedding automatic NAACCR standard updates that raise switching costs for hospital networks.
For New Entrants and Emerging Players: Anchor in federated analytics governance tooling where privacy-preserving multi-site research networks face vendor scarcity. Target mid-tier European cancer centers in France and Italy where GDPR complexity deters North American incumbents. Deploy low-code configuration platforms to reduce implementation timeline disadvantages against established players.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native SaaS platforms with embedded multi-jurisdiction certification tracks and recurring revenue concentration above seventy percent. Long-term viability hinges on interoperability moats rather than storage scale. Monitor EMA pharmacovigilance expansion announcements as inflection indicators for clinical trials management module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR connectivity with Epic and Cerner EHR systems locks in hospital network procurement committees. |
| Acquisition of Specialist Firm | NLP pathology abstraction tools compress registry update latency from months to days for academic centers. |
| Strategic Partnership | National cancer institute tenders in Germany and Japan provide multi-year revenue visibility with government backing. |
| Product Launch | AI-augmented recurrence detection dashboards command premium pricing from NIH-funded research institutes. |
| Geographic Expansion | Swiss and UK hospital networks seek GDPR-certified alternatives to US-dominated vendor landscapes. |
Research Methodology
Operator-level perspectives from cancer registry software product managers, hospital IT governance committee chairs, clinical informaticists, and national cancer institute program directors anchored the qualitative base. Primary intelligence combined with secondary validation from FDA 510(k) filings, EMA qualification opinions, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up deployment model sizing and top-down national cancer control program budget analysis provided cross-verification.
Sensitivity analysis across cloud adoption velocity, EHR interoperability penetration, and AI module attach rates shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, solution sophistication tier, application use case, and end-user institutional category. CAGRs derived from logistic diffusion curves fitted to historical health IT transition patterns, with inputs from pharmacovigilance regulatory expansion timelines and WHO Global Initiative funding commitments.
Underlying assumptions cover sustained HIPAA and GDPR enforcement intensity, with deviation risk concentrated in data sovereignty fragmentation and clinical informaticist labor supply constraints. Practitioners should keep alternative scenarios live as EMA pharmacovigilance requirements and federated data architecture adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Femtech Market
Healthcare IT
Healthcare IT Provider Market