
 Polychondritis Disease Treatment Market | 2026-2036
Polychondritis Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Polychondritis Disease Treatment Market Analysis
ISO 13485 certification for medical device-drug combination products is collapsing the supplier base for advanced delivery systems in this space. AbbVie leverages its immunology manufacturing infrastructure to sustain biologics output at scale. Bristol Myers Squibb anchors its position through deep expertise in T-cell modulation platforms. Roche Holding AG dominates the diagnostic-therapeutic continuum with companion testing protocols that guide treatment selection.
Polychondritis disease treatment encompasses pharmacological interventions targeting autoimmune-mediated cartilage inflammation, principally involving immunosuppressive and anti-inflammatory agents formulated for systemic distribution and sustained receptor engagement. These therapies function to arrest disease progression, preserve structural integrity of auricular, nasal, and tracheobronchial cartilage, and prevent life-threatening airway compromise. Corticosteroids retain the largest installed base among therapy types due to immediate efficacy in acute flares, though biologics capture expanding share as steroid-sparing maintenance options with superior long-term safety profiles. The intravenous route of administration maintains primacy in hospital-based induction protocols, while subcutaneous formulations gain traction in outpatient settings seeking reduced infusion burden.
FDA orphan drug incentives and EMA's priority medicines scheme jointly shape clinical trial investment and accelerated assessment pathways for novel polychondritis therapies. The EPA and OSHA impose manufacturing standards on active pharmaceutical ingredient facilities that filter which contract manufacturers qualify for biologics production. Stakeholders must monitor evolving biosimilar entry timelines and reimbursement parity decisions that will reshape competitive economics across corticosteroid, immunosuppressant, and biologic categories.
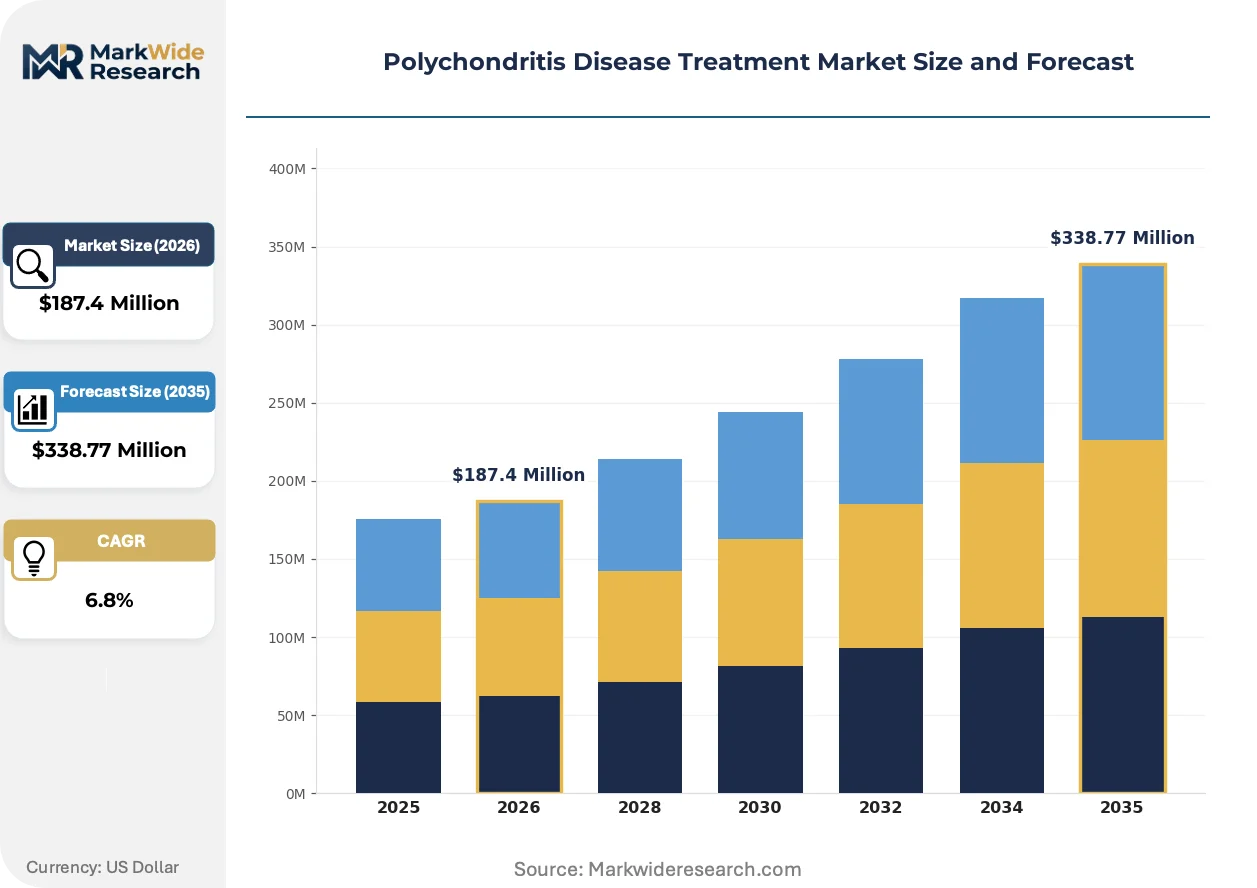
Market Dynamics
FDA orphan drug incentives and EMA priority medicines schemes are compressing development timelines for biologics targeting relapsing polychondritis, while ISO 13485 certification requirements for combination delivery systems are collapsing the qualified supplier base.
Growth Catalysts
- EMA Priority Medicines (PRIME) Scheme:Accelerated assessment pathways reduce time-to-market for novel immunomodulators, incentivizing biotech investment in rare autoimmune indications.
- Subcutaneous formulation advances:Self-administration technologies enable outpatient maintenance therapy, reducing infusion center burden and expanding treatable patient populations.
- Germany:Dense clustering of specialized immunology centers in Munich, Berlin, and Hamburg drives early adoption of corticosteroid-sparing protocols.
Market Restraints
- Biologics manufacturing concentration:Single-source dependency on mammalian cell culture facilities in Switzerland and Ireland creates supply vulnerability for monoclonal antibody production.
- Tracheal stent material costs:Silicone and nitinol price volatility compresses margins for airway stabilization devices used in severe laryngotracheal involvement.
- Diagnostic delay:Average seven-year time to diagnosis limits addressable patient pools and delays therapy initiation.
Strategic Opportunities
- Companion diagnostic integration:Roche's IL-6 receptor expression testing protocols enable precision patient selection for tocilizumab therapy.
- Japan:PMDA's Sakigake designation offers priority review for innovative regenerative medicines targeting cartilage preservation.
- Home infusion services:Specialty pharmacy networks are capturing maintenance therapy volumes previously managed in hospital outpatient departments.
Industry Challenges
- ISO 13485 audit backlogs:Medical device-drug combination product certification timelines extend 14-18 months, delaying commercialization.
- Rheumatology-otolaryngology coordination:Cross-specialty care pathway standardization remains incomplete, fragmenting treatment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polychondritis Disease Treatment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Corticosteroids, Non-Steroidal Anti-Inflammatory Drugs, Immunosuppressants, Biologics Route of Administration: Oral, Intravenous, Subcutaneous, Inhalation Indication: Respiratory Issues, Auricular Cartilage Damage, Nodules, Systemic Involvement Patient Demographics: Adults, Elderly, Pediatrics, Male |
| Companies Covered | Pfizer, Johnson & Johnson, Novartis AG, AbbVie, Bristol Myers Squibb, AstraZeneca, Sanofi, Roche Holding AG, GSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polychondritis Disease Treatment Market Emerging Trajectories
Biologics development is converging with precision diagnostics to reshape treatment selection, while manufacturing standards and delivery technologies undergo parallel transformation.
Subcutaneous auto-injector platforms for IL-6 pathway inhibitors are miniaturizing infusion infrastructure requirements. Rheumatology practices in the United States are adopting these devices for maintenance dosing, compressing hospital dependency for stable patients.
EMA's MDR transition deadlines are forcing device-drug combination manufacturers to consolidate notified body relationships. Class III implantable airway stents now require enhanced clinical evidence packages, extending regulatory timelines for European market entry.
Patient advocacy networks are compressing diagnostic delay through symptom recognition campaigns. Relapsing Polychondritis Foundation outreach in the United States and EURORDIS initiatives in Europe are accelerating physician education, shifting demand toward specialized referral centers.
Polychondritis Disease Treatment Market Segmentation
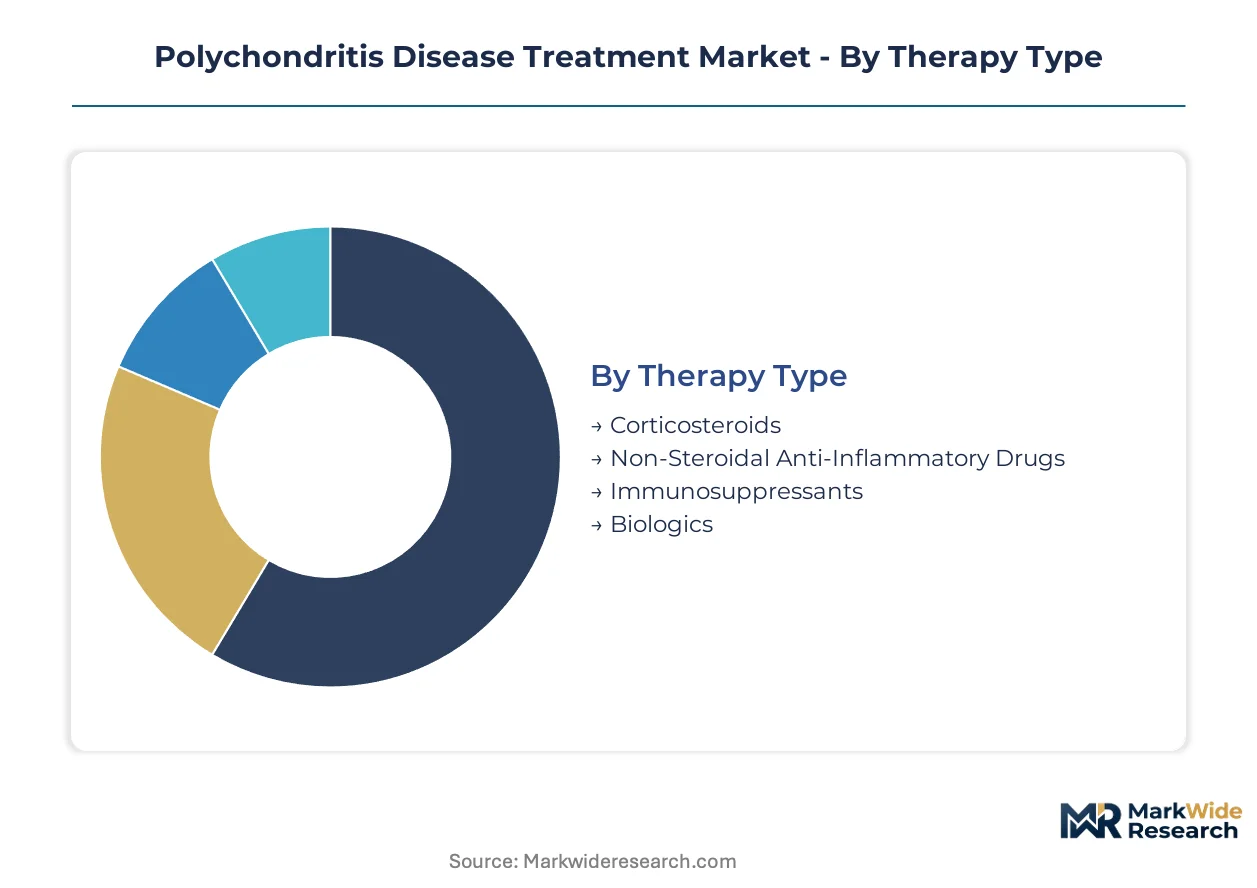
Segmentation in polychondritis disease treatment reveals distinct channel economics and clinical decision pathways. Therapy type determines reimbursement tier and site-of-care requirements, while route of administration shapes patient compliance and long-term adherence profiles.
Therapy Type:
Channel economics diverge sharply across therapy classes, with hospital outpatient departments capturing biologic induction volumes while retail pharmacies dominate corticosteroid maintenance prescriptions.
- Corticosteroids:Prednisone and methylprednisolone formulations retain the largest prescription volume due to immediate flare suppression and universal formulary inclusion. Demand concentrates in community rheumatology practices across the United States, where physicians prioritize rapid symptom control despite metabolic side-effect burdens.
- Biologics:IL-6 pathway inhibitors and TNF antagonists deliver steroid-sparing maintenance with superior cartilage preservation outcomes. Germany's specialized immunology centers in Munich and Berlin drive early adoption, supported by statutory health insurance coverage for off-label autoimmune indications.
- Immunosuppressants:Methotrexate and azathioprine serve as bridging therapy between acute corticosteroid induction and biologic maintenance.
- Non-Steroidal Anti-Inflammatory Drugs:Celecoxib and naproxen address mild auricular and nasal cartilage inflammation in early-stage patients.
By volume, Corticosteroids leads. By growth pace, Biologics is climbing the fastest.
Route of Administration:
Cost tier stratification separates hospital-based infusion services from self-administered outpatient options, with subcutaneous formulations commanding premium pricing for convenience value.
- Intravenous:Hospital-based tocilizumab and rituximab infusions require certified infusion center infrastructure and specialized nursing oversight. Demand clusters in tertiary academic medical centers in the United States, where complex airway involvement necessitates immediate emergency response capability.
- Subcutaneous:Auto-injector platforms for IL-6 inhibitors enable home administration with reduced healthcare utilization. Specialty pharmacy networks in Germany and Switzerland capture these maintenance volumes through direct-to-patient distribution models.
- Oral:Corticosteroid and immunosuppressant tablets dominate prescription volume through retail pharmacy channels.
- Inhalation:Budesonide nebulization addresses laryngotracheal inflammation in patients with subglottic stenosis.
By patient convenience, Subcutaneous achieves highest satisfaction scores. By clinical necessity for severe cases, Intravenous maintains irreplaceable positioning.
Indication:
Application severity determines therapy intensity, with respiratory involvement triggering immediate biologic escalation while isolated auricular damage permits conservative immunosuppression.
- Respiratory Issues:Tracheobronchial collapse and subglottic stenosis represent life-threatening complications requiring urgent intervention. Tocilizumab demonstrates particular efficacy in preserving airway patency, with demand concentrated at otolaryngology-rheumatology collaborative centers.
- Systemic Involvement:Multi-organ autoimmune activation involving cardiac valves and large vessels drives combination biologic protocols. Japanese academic hospitals report expanding use of IL-6 inhibitors for cardiovascular complication prevention.
- Auricular Cartilage Damage:Saddle nose deformity and cauliflower ear drive cosmetic and functional reconstruction referrals.
- Nodules:Cutaneous and ocular inflammatory masses respond variably to corticosteroid-sparing regimens.
By mortality risk, Respiratory Issues commands priority resource allocation. By treatment innovation velocity, Systemic Involvement attracts the most clinical trial investment.
Patient Demographics:
Maturity and comorbidity profiles shape therapeutic risk tolerance, with elderly patients facing stricter cardiovascular monitoring and pediatric cases requiring growth-sparing protocol adaptations.
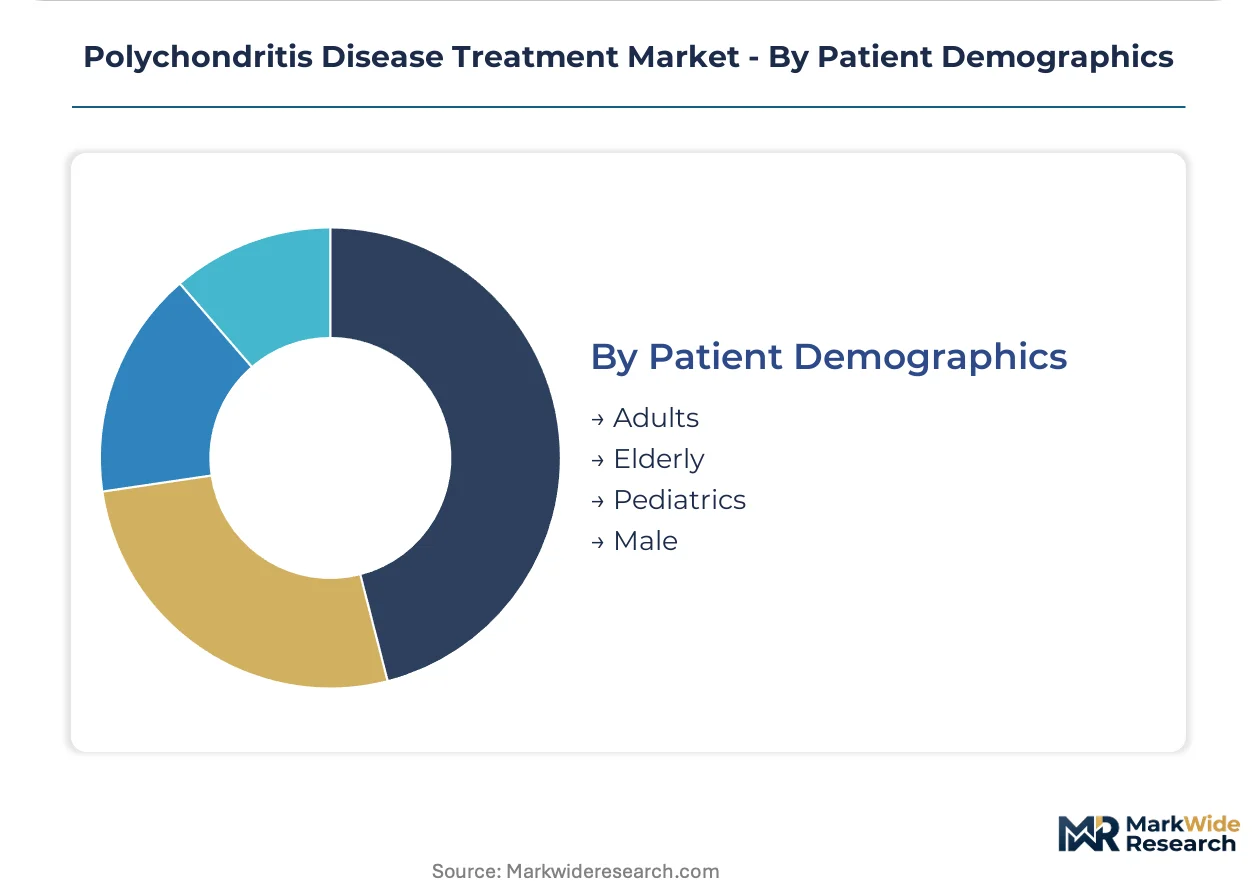
- Adults:Patients aged 18-64 constitute the core addressable population with full biologic eligibility and employment-driven preference for outpatient administration. United States commercial insurance plans increasingly require step therapy through corticosteroids before biologic authorization.
- Elderly:Patients over 65 face amplified infection risk from immunosuppression and require enhanced pneumococcal and shingles prophylaxis. German statutory health funds mandate additional cardiovascular monitoring for this cohort.
- Pediatrics:Juvenile-onset cases require modified dosing protocols and growth plate monitoring.
- Male:Gender-specific prevalence patterns and cardiovascular risk profiles influence therapy selection.
By absolute patient volume, Adults dominates the addressable pool. By unmet need intensity, Pediatrics represents the most underserved segment with few approved pediatric indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and EMA priority medicines schemes are compressing development timelines across major pharmaceutical markets, while specialized immunology centers concentrate demand in urban clusters with established referral networks.
United States
Rheumatology clinics in Boston, New York, and Chicago report expanding patient volumes for advanced autoimmune therapies. FDA's orphan drug designation pathway accelerates biologics development for rare indications. The Mayo Clinic and Cleveland Clinic anchor multi-specialty care coordination for complex airway involvement cases.
Germany
Statutory health insurance coverage for off-label biologic use in autoimmune disease drives early adoption of corticosteroid-sparing regimens. EMA's centralized marketing authorization enables streamlined EU-wide distribution from German distribution hubs. Munich, Berlin, and Hamburg host dense clusters of specialized immunology centers pioneering maintenance therapy protocols.
Japan
PMDA's Sakigake designation attracts regenerative medicine investment targeting cartilage preservation. Academic hospitals in Tokyo and Osaka report expanding IL-6 inhibitor use for cardiovascular complication prevention. The Kanto region concentrates biologics manufacturing infrastructure serving domestic and Asia-Pacific markets.
Switzerland
Single-source mammalian cell culture facilities in Basel and Zurich create supply vulnerability for monoclonal antibody production. Swissmedic maintains stringent GMP standards that filter contract manufacturer qualifications. The country's precision manufacturing base supports advanced delivery system component sourcing.
United Kingdom
NHS England's specialized commissioning framework concentrates biologic prescribing authority in designated tertiary centers. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for novel immunomodulators. London's academic medical centers coordinate otolaryngology-rheumatology referral pathways for airway stabilization.
Polychondritis Disease Treatment Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established immunology franchises. Market structure concentrates around entities possessing integrated biologics manufacturing infrastructure and rare disease regulatory expertise. Three archetypes dominate: large-cap diversified pharmaceuticals with immunology scale, mid-cap autoimmune specialists with T-cell platform depth, and diagnostic-therapeutic integrators with companion testing capabilities. Competitive moves center on portfolio expansion through biologics pipeline advancement and strategic positioning for biosimilar entry timelines.
Among the large-cap diversified tier, Pfizer and Johnson & Johnson occupy positions defined by manufacturing scale and distribution reach across multiple therapy modalities. Novartis AG exemplifies the autoimmune specialist archetype through its immunology platform investments. AbbVie and Bristol Myers Squibb represent entities with deep T-cell modulation expertise, while Roche Holding AG anchors the diagnostic-therapeutic integration vector. These five names illustrate the competitive concentration around entities capable of spanning corticosteroid, immunosuppressant, and biologic categories with regulatory sophistication for rare disease indications.
| Leading Market Players |
|---|
| Pfizer |
| Johnson & Johnson |
| Novartis AG |
| AbbVie |
| Bristol Myers Squibb |
| AstraZeneca |
| Sanofi |
| Roche Holding AG |
| GSK |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with mammalian cell culture facilities in Switzerland and Ireland lock in biologics supply access while anchoring price visibility for IL-6 pathway inhibitors. These contracts insulate specialty pharmaceutical manufacturers from spot-market volatility in monoclonal antibody production, though ISO 13485 certification requirements for combination delivery systems compress the qualified supplier base and transfer cost upward.
Pricing Analysis
Certification level (FDA-grade versus CE-marked) creates the primary spread between premium biologic formulations and standard corticosteroid generics. Three-tier pricing structure across premium, standard, and economy levels reflects GMP compliance tier, batch consistency guarantees, and cold-chain reliability. Cost compression in the corticosteroid tier is intensifying because of biosimilar entry timelines and reimbursement parity pressures. Retail pharmacy channels exhibit highest price sensitivity, while hospital outpatient departments prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Inventory lead times for nitinol and silicone airway stents extend 14-18 months due to ISO 13485 audit backlogs at notified bodies. Active pharmaceutical ingredient production concentrates in Switzerland, Ireland, and the United States, with mammalian cell culture capacity serving as the binding constraint for biologics output. Supply chain risk centers on single-source dependency for specialized immunosuppressant precursors. Distribution runs through specialty pharmacy networks for subcutaneous maintenance formulations and hospital-based infusion centers for acute induction protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home infusion services and patient support programs represent a service-attach opportunity expanding faster than pharmaceutical hardware, with specialty pharmacy networks capturing recurring revenue from maintenance therapy adherence monitoring and injection training.
For Market Incumbents: Compound manufacturing scale advantages by securing dual-source API agreements for immunosuppressant precursors and accelerating subcutaneous auto-injector platform development. Biosimilar entry timelines threaten corticosteroid margin profiles, making backward integration into GMP-certified fill-finish capacity the priority defensive lever. For New Entrants and Emerging Players: Lead with companion diagnostic integration targeting IL-6 receptor expression testing protocols, where Roche's established infrastructure leaves white space for specialized assay developers. Germany's dense clustering of immunology centers offers the most penetrable geography for corticosteroid-sparing regimen adoption. A go-to-market angle anchored in rheumatology-otolaryngology care pathway coordination addresses fragmentation in airway stabilization decisions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty pharmacy networks with direct-to-patient distribution capabilities and adherence monitoring services. Long-term viability across the projection horizon favors entities with integrated diagnostic-therapeutic positioning and rare disease regulatory expertise. The signal to watch as inflection indicator is PMDA Sakigake designation awards for regenerative medicine candidates targeting cartilage preservation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Development | Roche's IL-6 receptor testing protocols enable precision patient selection for tocilizumab therapy. |
| Subcutaneous Formulation Advancement | AbbVie's immunology manufacturing infrastructure supports auto-injector miniaturization for outpatient maintenance dosing. |
| ISO 13485 Certification Investment | EMA's MDR transition deadlines collapse the qualified supplier base for device-drug combination products. |
| Specialty Pharmacy Network Expansion | German statutory health insurance coverage drives direct-to-patient distribution model adoption. |
| Regulatory Orphan Drug Pathway Navigation | FDA's accelerated assessment incentives compress development timelines for biologics targeting relapsing polychondritis. |
Methodological Framework
The analysis maps biologics, corticosteroids, immunosuppressants, and combination delivery systems, each validated through rheumatology clinic directors, specialty pharmacy procurement managers, and regulatory affairs leads at biologics manufacturers. Primary interviews with formulary directors and hospital purchasing committees combined with secondary validation against FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov protocols, and German statutory health insurance reimbursement databases. Bottom-up prescription volume modeling and top-down therapy-class revenue triangulation anchored segmentation outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled therapy type, route of administration, indication severity, and patient demographic segments. CAGRs derived from patient volume trajectories at specialized immunology centers, biologics adoption curves in Germany, and corticosteroid-sparing protocol penetration rates. Forecast inputs incorporated ISO 13485 certification timelines and PMDA Sakigake designation awards.
Forecasts assume regulatory continuity in FDA orphan drug incentives and EMA priority medicines schemes; material policy shifts would require re-modeling. Diagnostic delay compression through patient advocacy outreach and cross-specialty care pathway standardization represent specific risk factors that could revise addressable patient pool estimates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market