
 Asia-Pacific Sports Medicine Market | 2026-2036
Asia-Pacific Sports Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sports Medicine Market Outlook
Asset-light leasing models for arthroscopic equipment is tilting competitive dynamics toward mid-sized distributors with lower capital requirements. Stryker Corporation leverages its end-to-end arthroscopy portfolio to anchor premium service contracts across Japanese hospital networks. Medtronic PLC sustains R&D intensity in minimally invasive soft-tissue repair systems. Arthrex Inc. specializes in suture anchor innovation for rotator cuff procedures, occupying a defensible niche in Australian orthopedic centers.
Asia-Pacific sports medicine encompasses diagnostic, surgical, and rehabilitative interventions for musculoskeletal injuries sustained during athletic activity, including arthroscopic procedures performed through portals under 5mm diameter and biologics formulations with platelet concentrations exceeding baseline levels fivefold. The discipline serves to restore function, accelerate return-to-play timelines, and prevent recurrent trauma in physically active populations. Braces, splints, compression wear, and tapes represent mature revenue pools with stable replacement cycles, while wearable devices and biomechanics analysis command expanding budgets from professional sports teams seeking predictive injury analytics. Clinics and sports teams constitute the fastest-growing end-user channels as franchise medicine models proliferate across Southeast Asian metropolitan areas.
Japan's PMDA enforces stringent biocompatibility standards for implantable sports medicine devices, while Australia's TGA mandates post-market surveillance for high-risk arthroscopic instruments, collectively elevating quality barriers for new entrants. China's NMPA accelerates review timelines for domestically manufactured orthopedic implants under innovation-track pathways, redirecting procurement toward local suppliers. Stakeholders must monitor regulatory divergence between harmonized ASEAN medical device directives and country-specific clinical data requirements as compliance complexity escalates.
Market Dynamics
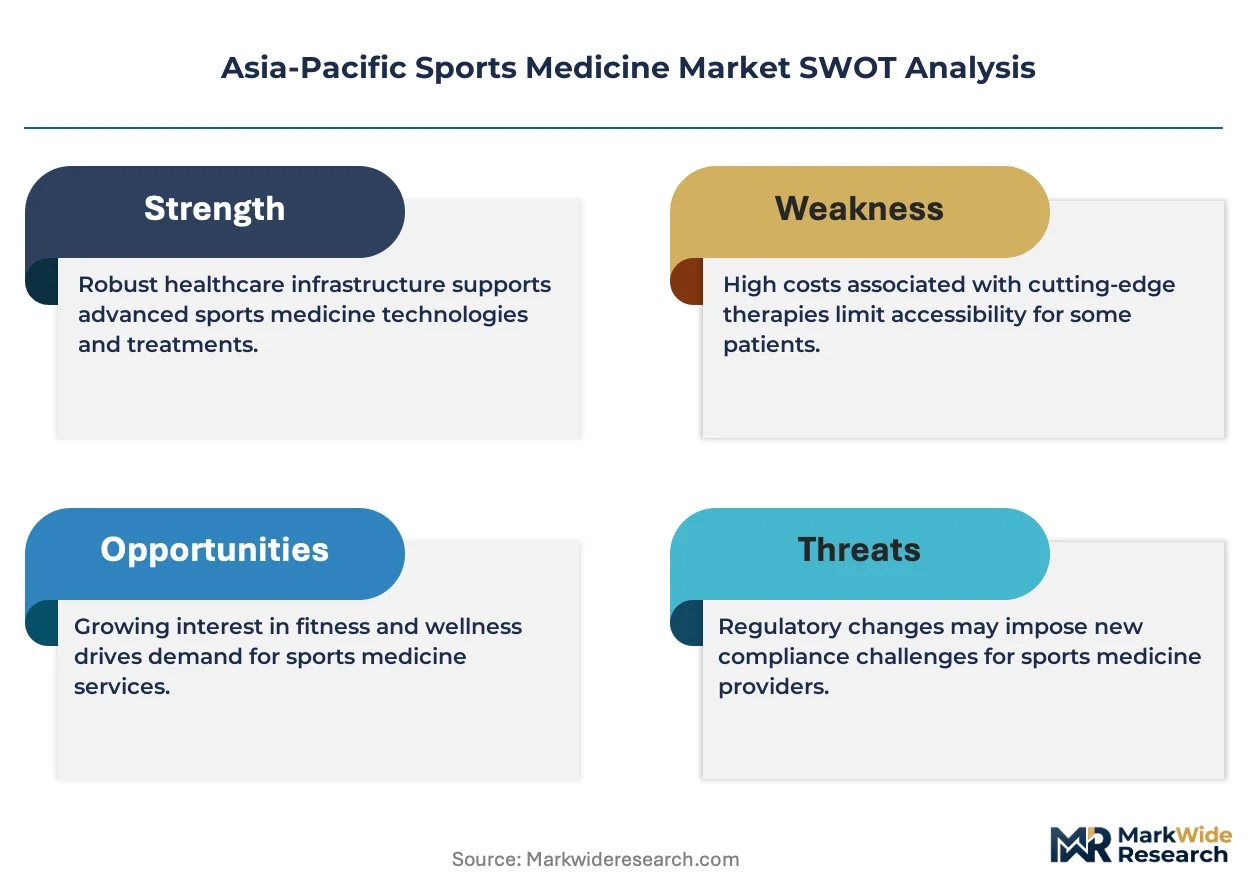
Japan's PMDA fast-track pathways for regenerative orthopedic products compress commercialization timelines, while China's NMPA innovation-track approvals redirect procurement toward domestic manufacturers, collectively reshaping competitive positioning across arthroscopy and biologics segments.
Growth Catalysts
- Wearable biomechanical monitoring:Professional sports franchises in Australia deploy real-time motion sensors for predictive injury analytics, expanding equipment budgets beyond traditional braces and tapes.
- PMDA accelerated review frameworks:Japan's regenerative medicine fast-track pathways compress approval timelines for stem-cell-based cartilage repair products, stimulating R&D investment from domestic orthopedic manufacturers.
- Franchise medicine proliferation:Private sports clinics concentrate in China's tier-one cities, creating demand for arthroscopic systems and rehabilitation equipment through standardized care protocols.
Market Restraints
- Biocompatibility compliance costs:Japan's PMDA enforces stringent implantable device standards, elevating preclinical testing expenditures for foreign entrants seeking market access.
- Post-market surveillance obligations:Australia's TGA mandates ongoing safety monitoring for high-risk arthroscopic instruments, creating recurring compliance burdens for distributors with limited regulatory affairs capacity.
- Domestic procurement preferences:China's NMPA innovation-track pathways favor locally manufactured orthopedic implants, constraining import penetration in the region's largest volume market.
Strategic Opportunities
- ASEAN regulatory harmonization gaps:Divergence between ASEAN medical device directives and country-specific clinical data requirements creates advisory service opportunities for compliance specialists navigating Southeast Asian markets.
- Asset-light equipment leasing:Mid-sized distributors leverage lower capital requirements to capture arthroscopy system placements, displacing traditional capital-intensive sales models in Australian hospital networks.
- Biomechanics analysis convergence:Integration of wearable sensors with cloud-based analytics platforms enables subscription revenue models from professional sports teams seeking injury prevention protocols.
Industry Challenges
- Specialized surgical training scarcity:Arthroscopic procedures demand fellowship-trained orthopedic surgeons, creating bottlenecks for clinic expansion in emerging Southeast Asian metropolitan areas.
- Legacy system integration friction:Sports medicine software platforms face interoperability barriers with hospital electronic health record systems, complicating deployment timelines in Japanese integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sports Medicine Market |
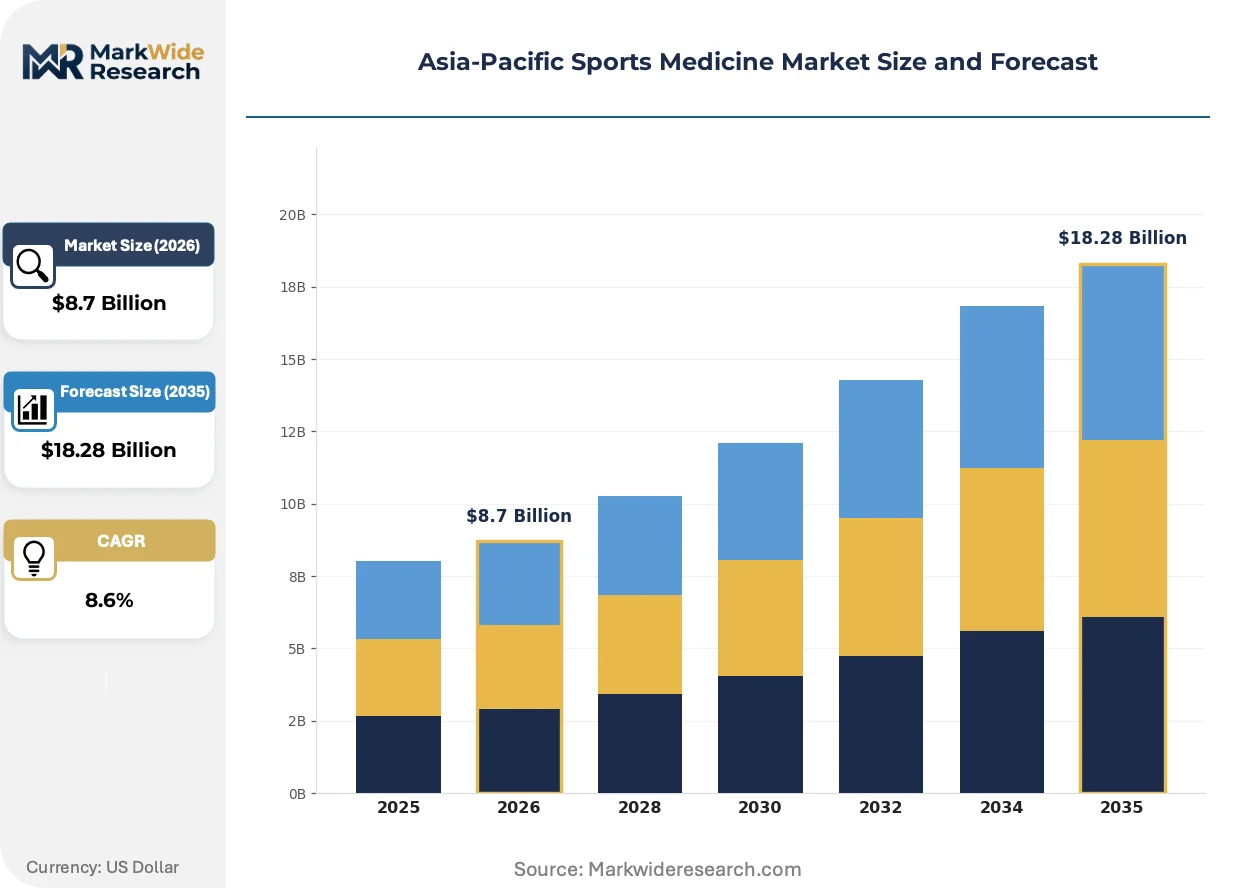
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $18.28 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Splints, Compression Wear, Tapes End User: Professional Athletes, Recreational Users, Clinics, Sports Teams Application: Injury Prevention, Rehabilitation, Pain Management, Performance Enhancement Technology: Wearable Devices, Biomechanics Analysis, Telemedicine, eHealth Solutions |
| Companies Covered | Arthrex Inc., Medtronic PLC, Stryker Corporation, DJO Global Inc., Johnson & Johnson, Zimmer Biomet Holdings Inc., CONMED Corporation, Karl Storz, Smith & Nephew PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sports Medicine Market Strategic Shifts
Wearable technology and regenerative biologics are compressing traditional rehabilitation timelines, while regulatory pathway differentiation across Japan, China, and Australia is fragmentating go-to-market strategies for orthopedic device manufacturers.
Platelet-rich plasma formulations are migrating from experimental adjunct therapy to standard-of-care protocols for tendon and ligament injuries. Australian private sports clinics now specify fivefold platelet concentration thresholds in procurement tenders. This shift is migrating from premium urban centers to regional franchise locations, compressing margins for conventional corticosteroid injection suppliers.
Japan's PMDA regenerative medicine framework accelerates conditional approvals for cell-based cartilage repair products. Manufacturers gain market access with smaller pivotal trial cohorts, contingent on post-market efficacy commitments. Orthopedic biologics specialists in Osaka and Tokyo medical centers are expanding indication claims through registry-based evidence generation.
Professional sports franchises now unbundle injury prevention analytics from equipment supply contracts. Australian rugby and cricket organizations procure wearable biomechanical monitoring as standalone service agreements, displacing bundled vendor relationships. This pattern concentrates in Melbourne and Sydney performance institutes before diffusing to Southeast Asian professional leagues.
Asia-Pacific Sports Medicine Market Segmentation
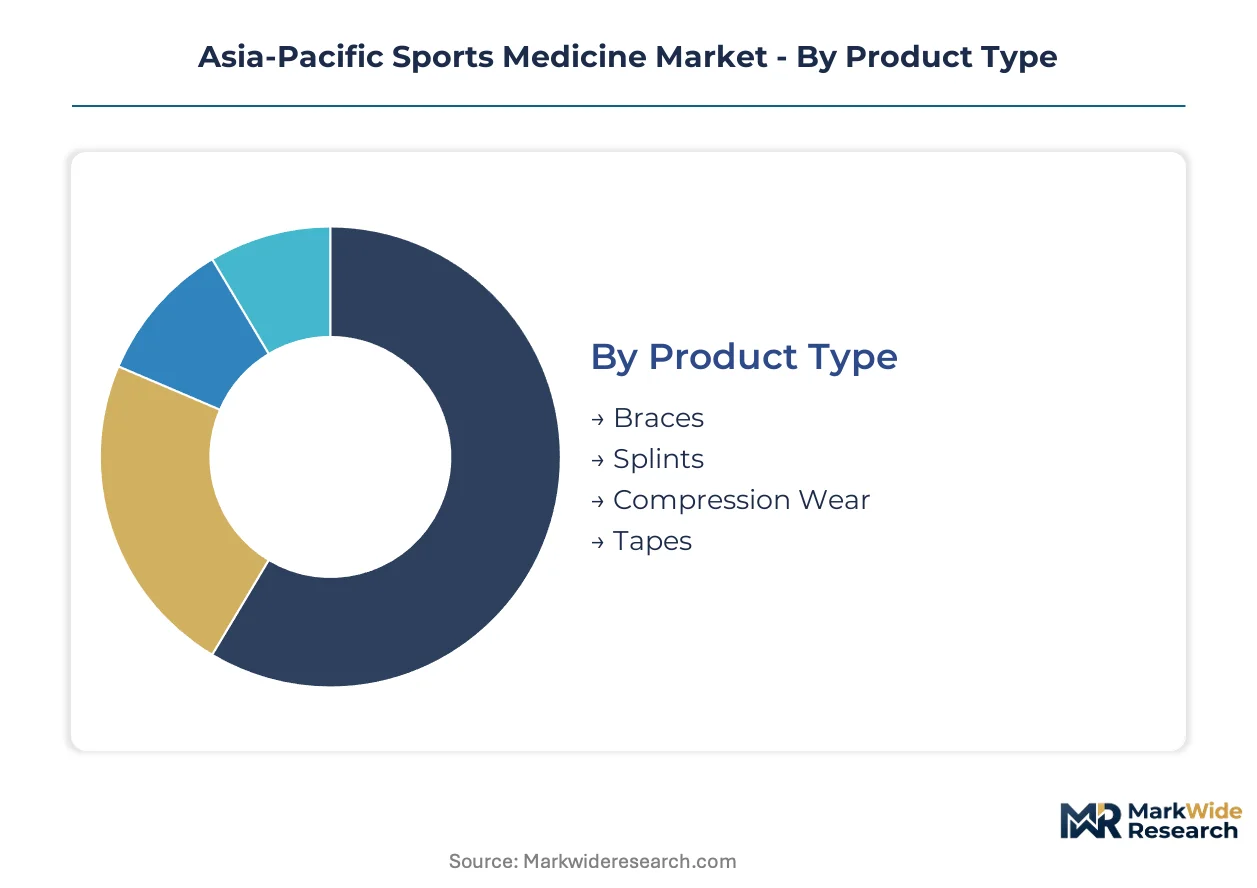
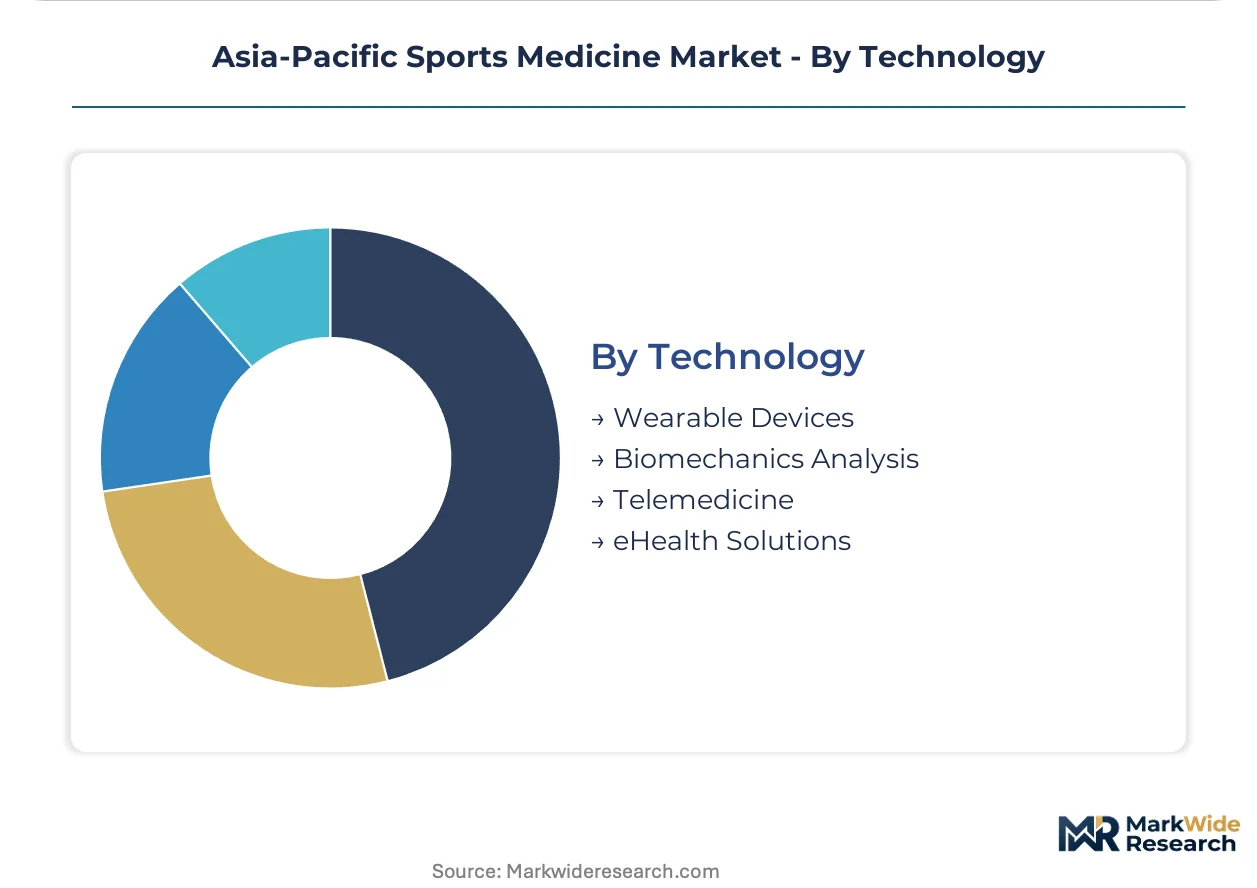
Segmentation in Asia-Pacific sports medicine reveals divergent procurement patterns across mature consumables and emerging digital platforms. Product categories range from commodity braces to AI-driven biomechanical systems, each commanding distinct margin profiles and regulatory pathways.
Product Type:
The use-case spectrum spans acute injury immobilization through chronic condition management, with material specifications and replacement cycles varying dramatically across categories.
- Braces:Rigid and semi-rigid orthotic devices constructed from aluminum, carbon fiber, or molded plastics stabilize joints post-injury or during high-risk activity. Australian rugby franchises specify custom-molded knee braces with bilateral hinge mechanisms, while China's private clinics favor off-the-shelf neoprene sleeves for cost-sensitive patient populations.
- Splints:Immobilization devices fabricated from fiberglass, thermoplastic, or aluminum alloys maintain anatomical alignment during fracture healing or post-surgical recovery. Japan's orthopedic centers prioritize lightweight carbon-composite splints for wrist and ankle applications, driven by PMDA biocompatibility certifications that elevate quality thresholds.
- Compression Wear:Graduated-pressure garments manufactured from elastomeric blends enhance venous return and proprioceptive feedback during athletic activity.
- Tapes:Adhesive strapping materials including zinc oxide, synthetic elastic, and kinesiology variants provide joint support and muscle facilitation.
Established volume favors braces; emerging adoption favors compression wear with integrated sensor compatibility.
End User:
Customer archetypes diverge sharply on procurement authority, budget scale, and technology sophistication requirements.
- Professional Athletes:Elite competitors with franchise-funded medical programs demand premium customized equipment and real-time biometric monitoring. Australian cricket and rugby organizations deploy wearable systems for predictive injury analytics, with procurement decisions centralized through performance institutes in Melbourne and Sydney.
- Clinics:Private sports medicine facilities in China's tier-one cities standardize arthroscopic equipment and rehabilitation protocols through franchise medicine models. These entities represent the steepest expansion trajectory as metropolitan demand concentrates in Beijing, Shanghai, and Shenzhen.
- Recreational Users:Amateur athletes and fitness enthusiasts purchase over-the-counter braces, tapes, and compression garments through retail channels.
- Sports Teams:Amateur and semi-professional organizations procure team-scale equipment packages with limited customization.
Revenue concentration sits with professional athletes; volume expansion is climbing the fastest among clinic networks.
Application:
Clinical objectives range from prophylactic intervention through functional restoration, with reimbursement patterns and outcome metrics shaping segment economics.
- Injury Prevention:Proactive biomechanical screening and protective equipment deployment reduces incident rates in high-risk athletic populations. Australian professional leagues now mandate pre-season movement assessments using three-dimensional motion capture systems.
- Rehabilitation:Post-injury therapeutic protocols restore range of motion, strength, and neuromuscular control through progressive loading and modality-based interventions. Japan's PMDA fast-track pathways for regenerative products accelerate cartilage repair commercialization, redirecting rehabilitation economics toward biologics.
- Pain Management:Pharmacological and interventional approaches address acute and chronic musculoskeletal discomfort.
- Performance Enhancement:Biomechanical optimization and physiological monitoring improve athletic output beyond baseline capacity.
Reimbursement stability favors rehabilitation; discretionary spending growth favors performance enhancement.
Technology:
Digital and connected platforms are gaining share fastest against traditional diagnostic and delivery modalities, with cloud infrastructure and regulatory clearance timelines determining competitive pacing.
- Wearable Devices:Sensor-embedded garments and external monitors capture kinematic, kinetic, and physiological data during training and competition. Australian franchises deploy IMU-based systems for real-time workload management, with data feeds integrated into coaching decision support.
- Biomechanics Analysis:Motion capture, force plate, and pressure mapping systems quantify movement patterns for injury risk stratification. Japanese orthopedic centers in Osaka and Tokyo medical clusters utilize markerless video analysis for ACL return-to-sport protocols.
- Telemedicine:Remote consultation platforms connect athletes with specialists across geographic distances.
- eHealth Solutions:Digital therapeutics and patient engagement platforms support adherence to rehabilitation protocols.
Capital intensity favors biomechanics analysis; subscription scalability favors wearable devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA fast-track pathways for regenerative orthopedic products compress commercialization timelines across Japan, while China's NMPA innovation-track approvals redirect procurement toward domestic manufacturers, collectively reshaping competitive positioning across the region's arthroscopy and biologics segments.
Japan
Osaka and Tokyo medical centers drive demand for stem-cell-based cartilage repair products. PMDA conditional approval frameworks enable market access with smaller pivotal trial cohorts contingent on post-market efficacy commitments. Orthopedic biologics specialists in these clusters expand indication claims through registry-based evidence generation.
China
Private sports clinics proliferate rapidly in Beijing, Shanghai, and Shenzhen, creating concentrated demand for arthroscopic systems and rehabilitation equipment. NMPA innovation-track pathways accelerate review timelines for domestically manufactured orthopedic implants. Franchise medicine models standardize care protocols across tier-one metropolitan networks.
Australia
Professional sports franchises in Melbourne and Sydney deploy wearable biomechanical monitoring for predictive injury analytics. TGA mandates post-market surveillance for high-risk arthroscopic instruments, elevating compliance burdens for distributors. Performance institutes centralize procurement decisions for cricket and rugby organizations.
South Korea
Seoul Capital Area anchors demand for minimally invasive soft-tissue repair systems. MFDS enforces stringent biocompatibility standards for implantable devices, elevating preclinical testing expenditures. Daegu-Gyeongbuk medical clusters specialize in suture anchor innovation for rotator cuff procedures.
Singapore
Regional hub status attracts orthopedic device manufacturers seeking ASEAN market access. HSA regulatory frameworks bridge harmonized ASEAN medical device directives with country-specific clinical data requirements. Biomedical manufacturing parks concentrate precision instrumentation production for Southeast Asian distribution.
Asia-Pacific Sports Medicine Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent go-to-market models. The vendor base separates into three tiers: multinational conglomerates with end-to-end arthroscopy portfolios, mid-sized distributors leveraging asset-light leasing models, and niche innovators in suture anchor and biologics formulations. Dominant competitive moves include strategic partnerships with Japanese hospital networks and technology licensing agreements for wearable biomechanical systems.
Within the multinational conglomerate tier, Stryker Corporation, Medtronic PLC, and Arthrex Inc. occupy positions reflecting distinct strategic archetypes. Stryker anchors premium service contracts across Japanese integrated delivery networks through comprehensive arthroscopy portfolio coverage. Medtronic exemplifies sustained R&D intensity in minimally invasive soft-tissue repair systems, representing the technology-driven archetype. Arthrex sits within the specialized innovation segment, occupying a defensible niche in Australian orthopedic centers through focused suture anchor development. These three entities collectively illustrate the competitive spectrum from broad channel control to targeted product excellence.
| Leading Market Players |
|---|
| Arthrex Inc. |
| Medtronic PLC |
| Stryker Corporation |
| DJO Global Inc. |
| Johnson & Johnson |
| Zimmer Biomet Holdings Inc. |
| CONMED Corporation |
| Karl Storz |
| Smith & Nephew PLC |
| Others |
Value Chain & Pricing Dynamics
Osaka's precision manufacturing clusters anchor biologics formulation capacity, with PMDA-certified production lines commanding premium pricing power over ASEAN-sourced alternatives in Australian hospital procurement. This geographic concentration of regulatory-grade manufacturing creates asymmetric leverage for Japanese suppliers negotiating service contracts across Asia-Pacific orthopedic networks.
Pricing Analysis
Certification level (PMDA/FDA-grade versus non-harmonized) creates the primary spread across implantable sports medicine devices, with three-tier pricing structure across premium, standard, and economy levels. Australian private clinics exhibit highest price sensitivity for consumable braces and tapes, while Japanese integrated delivery networks absorb premium positioning for regenerative biologics. Cost compression in mid-tier arthroscopic instruments is intensifying because China's NMPA innovation-track approvals redirect volume toward domestically manufactured alternatives.
Supply Chain Analysis
Medical-grade polymer feedstocks and precision-machined titanium alloys flow from Japan, Germany, and the United States into Asia-Pacific orthopedic device manufacturing. Raw material dependencies center on biocompatible elastomers for wearable sensors, carbon fiber composites for rigid braces, and recombinant growth factors for platelet-rich plasma formulations. Single-source vulnerability concentrates in PMDA-certified sterilization services located in the Osaka-Tokyo corridor. Distribution runs through hospital procurement committees in Japan, franchise clinic networks in China, and performance institute central buying in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained arthroscopic surgeons represent the critical bottleneck constraining clinic expansion across Southeast Asian metropolitan areas, with capability scarcity in specialized surgical training programs limiting franchise medicine proliferation outside tier-one Chinese cities.
For Market Incumbents: Harden service contract stickiness in Japanese hospital networks by embedding biomedical engineers within integrated delivery systems, insulating against mid-sized distributors capturing placements through asset-light leasing models. Deepen backward integration into PMDA-certified biologics manufacturing to defend margin position against domestic Chinese suppliers benefiting from NMPA innovation-track procurement preferences. For New Entrants and Emerging Players: Second-tier Chinese cities with nascent private sports clinic penetration represent the most penetrable entry point for arthroscopy equipment leasing models, given lower incumbent saturation and standardized franchise protocols. Australian regional performance institutes outside Melbourne and Sydney offer white-space for wearable biomechanical monitoring subscriptions, with direct-to-clinic sales bypassing centralized procurement committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized biologics formulators with PMDA conditional approval experience and registry-based evidence generation capabilities. Long-term viability rests on navigating regulatory divergence between harmonized ASEAN directives and country-specific clinical data requirements. The inflection signal to monitor is MFDS alignment with PMDA fast-track frameworks, which would consolidate Northeast Asian regulatory complexity and advantage pre-positioned players.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Fast-Track Alignment | Conditional approval frameworks compress commercialization timelines for stem-cell-based cartilage repair products in Osaka medical clusters. |
| Asset-Light Leasing Expansion | Mid-sized distributors displace capital-intensive sales models across Australian hospital networks with lower equipment placement barriers. |
| Wearable Analytics Integration | IMU-based biomechanical monitoring unbundles from equipment supply contracts in Sydney and Melbourne performance institutes. |
| Domestic Manufacturing Localization | NMPA innovation-track approvals redirect procurement toward Chinese orthopedic implant suppliers in Beijing and Shanghai clinic networks. |
| Registry-Based Evidence Generation | Post-market efficacy commitments enable indication expansion for biologics specialists in Tokyo orthopedic centers. |
Study Parameters
Cross-validation between hospital procurement database analysis and clinician interview transcripts anchors the qualitative findings across the Asia-Pacific sports medicine landscape. Primary fieldwork encompassed orthopedic surgeons, biomedical engineers, GPO contracts managers, and franchise clinic operators. Secondary validation drew from PMDA approval databases, NMPA innovation-track filings, TGA post-market surveillance registers, and hospital equipment tender records. Bottom-up procedure volume estimates and top-down manufacturer shipment data were reconciled through iterative calibration.
Calibration against historical regulatory approval timelines and equipment replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, end-user archetype, application objective, and technology platform, with additional stratification by national regulatory cluster. CAGRs were derived from procedure volume growth trajectories, pricing trend analysis, and technology substitution patterns. Forecast inputs incorporated PMDA fast-track utilization rates and NMPA domestic procurement preference intensification.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy and medical device tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and surgeon training pipeline expansion. Material shifts in ASEAN medical device directive harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Transient Ischemic Attack Market