
 Glove Box Market | 2026-2036
Glove Box Market Size, Share, and Industry Trends Forecast 2026-2036
Glove Box Market Intelligence
German precision engineering clusters is realigning global supply chains for high-integrity containment systems. MBRAUN GmbH leverages its vertically integrated manufacturing base in Bavaria to dominate European inert atmosphere equipment. Labconco Corporation sustains North American market presence through specialized biohazard containment lines for pharmaceutical cleanrooms. Jacomex differentiates its portfolio with advanced filtration integration for nuclear and radiopharmaceutical applications.
A glove box is a sealed enclosure with integrated gauntlet ports that enables operators to manipulate materials inside a controlled atmosphere of inert gas, vacuum, or filtered air, typically maintaining oxygen levels below 1 ppm in premium configurations. The device serves critical functions in protecting sensitive materials from atmospheric contamination and shielding personnel from hazardous substances during precision operations. Inert glove boxes command the largest share of product type demand due to their indispensability in lithium battery research and OLED development. Stainless steel constructions anchor the material segment because of their durability in corrosive chemical environments and ease of decontamination protocols. Vacuum glove boxes represent the fastest-expanding product category, driven by aerospace material testing and advanced ceramics processing requirements.
FDA cGMP guidelines and OSHA containment standards dictate equipment specifications for pharmaceutical manufacturing environments in the United States, mandating validated isolation systems for potent compound handling. REACH compliance in Europe restricts certain seal and gasket chemistries, pushing manufacturers toward fluoropolymer alternatives that extend product lifecycles. ISO 14644 cleanroom classifications further shape procurement criteria for research laboratory installations across multiple jurisdictions. Stakeholders must weigh total cost of ownership against evolving regulatory stringency when specifying containment infrastructure for multi-year research programs.
Market Dynamics
Semiconductor fabrication facilities in Taiwan and South Korea are accelerating procurement cycles for inert atmosphere enclosures as advanced node production demands sub-ppm oxygen control, compressing equipment qualification timelines from 18 months to under 12 months for qualified suppliers.
Growth Catalysts
- OSHA containment standards:Pharmaceutical manufacturers in the United States must upgrade legacy isolation equipment for potent compound handling, mandating validated systems that meet current OSHA exposure limits.
- Lithium battery research:Specialty polymer and battery material R&D labs in Germany's chemical corridor require hermetically sealed manipulation environments for next-generation solid-state electrolyte development.
- OLED development:Display manufacturers in South Korea are expanding cleanroom footprints for organic light-emitting diode production, where moisture and oxygen sensitivity necessitates premium glove box configurations.
Market Restraints
- Fluoropolymer seal costs:REACH compliance in Europe restricts traditional gasket chemistries, forcing adoption of perfluoroelastomer alternatives that increase maintenance expenditure by 40-60% over standard nitrile compounds.
- Stainless steel supply concentration:High-grade 316L stainless steel for corrosive chemical applications concentrates among a limited supplier base in Germany and Japan, creating input vulnerability for enclosure fabricators.
- Vacuum system technical limitations:Current rotary vane pump configurations struggle to maintain below 10⁻³ mbar consistently in large-volume aerospace material testing chambers, constraining application scope.
Strategic Opportunities
- India battery manufacturing:PLI scheme incentives for advanced chemistry cell production are attracting gigafactory investments in Gujarat and Tamil Nadu, creating demand for localized glove box supply chains.
- Radiopharmaceutical isolation:Nuclear medicine expansion in France and Belgium requires specialized containment with integrated filtration for isotope manipulation, a premium segment with limited incumbent competition.
- Digital twin integration:Remote monitoring platforms are converging with glove box control systems, enabling predictive maintenance contracts that extend customer lifetime value beyond equipment sale.
Industry Challenges
- Cleanroom technician certification:ISO 14644 compliance requires specialized training for personnel operating containment systems, and qualified technicians remain scarce in emerging battery research clusters.
- Legacy equipment integration:Pharmaceutical facilities running 1990s-era isolators face complex retrofit requirements to meet current FDA cGMP guidelines for data integrity and environmental monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glove Box Market |
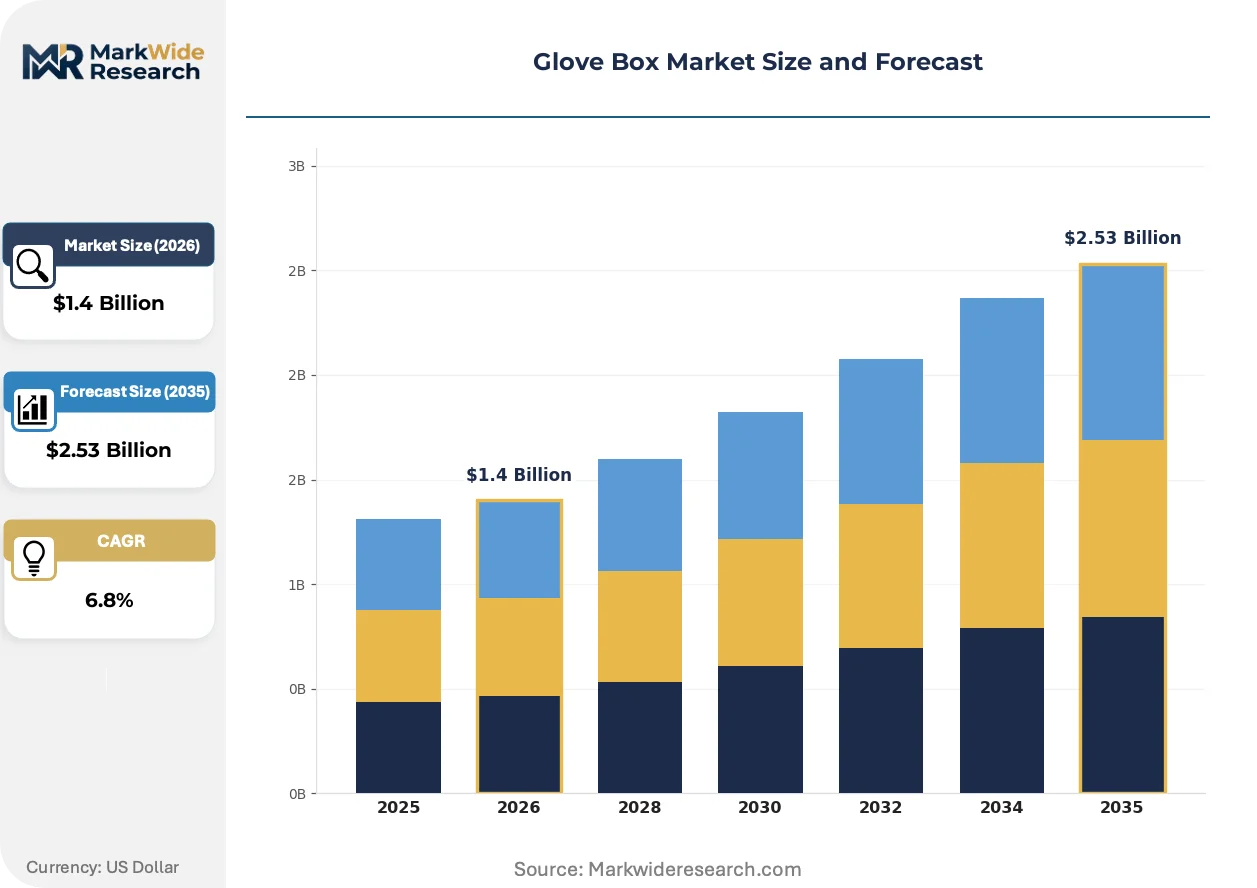
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Glove Boxes, Biohazard Glove Boxes, Vacuum Glove Boxes, Inert Glove Boxes Material: Polycarbonate, Stainless Steel, Acrylic, Polypropylene End User: Pharmaceuticals, Research Laboratories, Chemical Industry, Academia Application: Material Handling, Isolation, Glove Box Inerting, Containment |
| Companies Covered | Labconco Corporation, MBRAUN GmbH, Jacomex, Cleatech LLC, Terra Universal Inc., Vacuum Atmospheres Company, GS GLOVEBOX Systemtechnik GmbH, Coy Laboratory Products Inc., Plas-Labs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glove Box Market Strategic Shifts & Innovations
Active atmosphere control systems are displacing passive purge methods across high-value research applications, while modular enclosure architectures enable rapid reconfiguration between inert, vacuum, and filtered air modes without full decommissioning.
Machine vision systems for glove box operation are converging with haptic feedback interfaces, allowing semiconductor wafer handling without direct manual manipulation. Taiwan-based foundries are piloting these configurations for 3nm node development. The technology is converging with existing cleanroom infrastructure to compress contamination risk windows during critical process steps.
REACH restrictions on perfluorinated substances are compelling seal and gasket manufacturers toward hydrogenated nitrile and thermoplastic elastomer alternatives that maintain chemical resistance profiles. European chemical laboratories face equipment replacement timelines accelerated by regulatory sunset clauses. Specialty polymer suppliers in Germany are responding with accelerated qualification programs for compliant material formulations.
Research consortia in battery materials are consolidating procurement through shared-user facility models rather than individual laboratory installations. National laboratory networks in the United States and Germany are displacing traditional single-investigator equipment purchases with centralized access programs. South Korean government-funded institutes have pioneered this approach most extensively, reducing per-researcher capital burden while maximizing equipment utilization rates.
Glove Box Market Segmentation
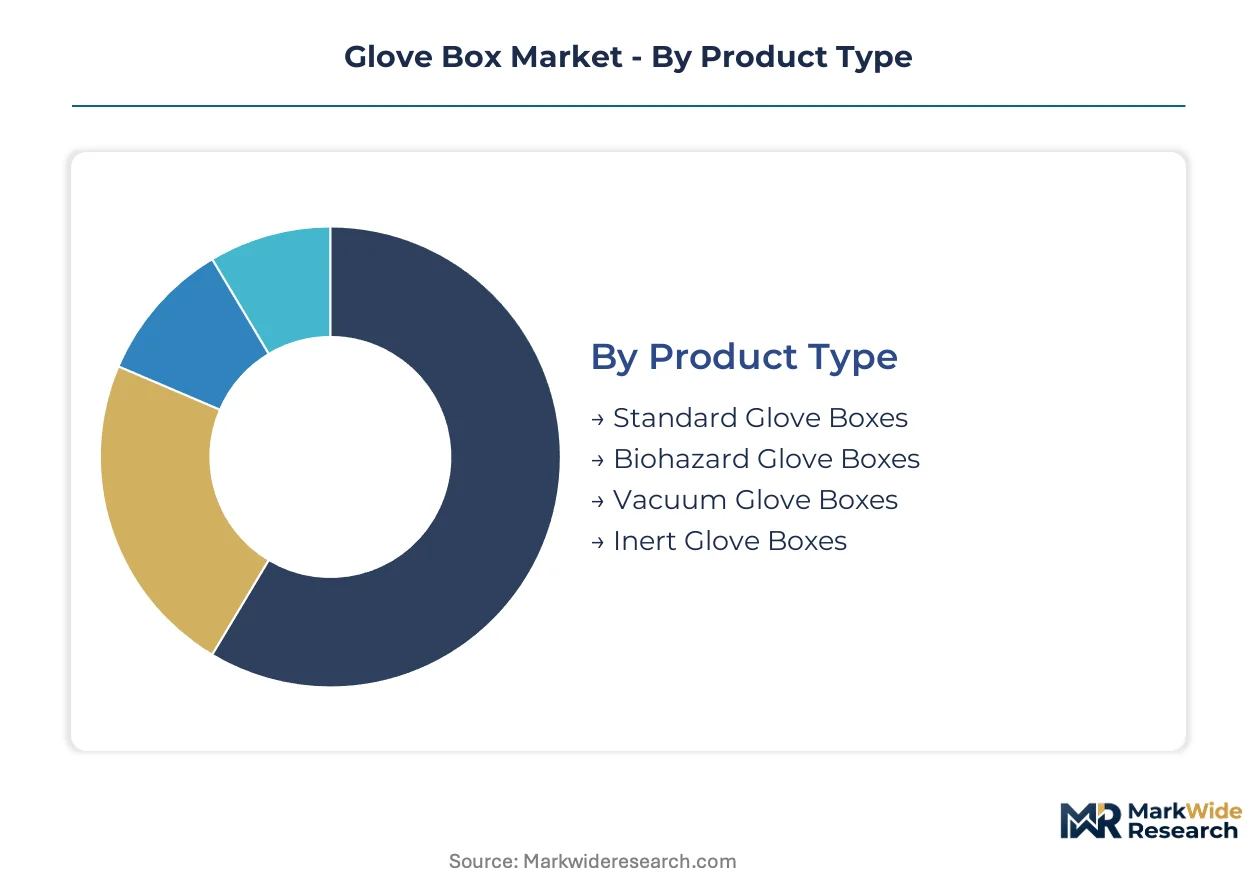
Glove box procurement patterns diverge sharply between high-volume standard installations and premium-configured specialized systems. Semiconductor and battery research facilities drive specification complexity upward, while academic and routine industrial buyers prioritize cost efficiency and rapid deployment.
Product Type:
Volume installations favor passive purge configurations, while premium demand concentrates in active atmosphere control with integrated monitoring.
- Inert Glove Boxes:These systems maintain oxygen levels below 1 ppm through continuous nitrogen or argon purging with closed-loop recirculation. Taiwan and South Korea semiconductor foundries specify these for advanced node wafer handling where atmospheric contamination destroys yield. REACH-compliant seal materials extend maintenance intervals but add 40-60% to gasket replacement costs.
- Vacuum Glove Boxes:Rotary vane or turbomolecular pump configurations achieve pressures below 10⁻³ mbar for aerospace material testing and advanced ceramics processing. Large-volume chambers for satellite component qualification represent the steepest expansion trajectory as space agency budgets accelerate.
- Standard Glove Boxes:Basic filtered-air enclosures serve routine pharmaceutical compounding and educational laboratories where contamination control requirements remain modest.
- Biohazard Glove Boxes:HEPA-filtered negative-pressure systems with validated containment for BSL-3 pathogen handling and potent pharmaceutical compound manipulation.
Today's leader: Inert Glove Boxes. Tomorrow's challenger: Vacuum Glove Boxes.
Material:
Corrosion resistance and decontamination protocol compatibility separate premium material selections from economy alternatives.
- Stainless Steel:Grade 316L construction dominates corrosive chemical environments and radiopharmaceutical applications where repeated decontamination cycles degrade polymer alternatives. Germany and Japan concentrate high-grade alloy supply, creating procurement vulnerability for enclosure fabricators.
- Acrylic:Transparent thermoplastic enables visual process monitoring in battery research and OLED development where operators must detect material changes. South Korean display manufacturers specify optical-grade acrylic for moisture-sensitive organic semiconductor handling.
- Polycarbonate:Impact-resistant polymer serves educational and routine industrial settings where chemical exposure remains limited.
- Polypropylene:Chemical-resistant thermoplastic competes in budget-conscious pharmaceutical compounding operations.
Stainless Steel commands premium pricing. Acrylic gains share fastest in optically demanding applications.
End User:
Regulatory stringency and research intensity determine specification tiers across customer categories.
- Pharmaceuticals:FDA cGMP and OSHA containment standards mandate validated isolation systems with environmental monitoring and data integrity documentation. US manufacturers face upgrade pressure for 1990s-era isolators to meet current potent compound exposure limits.
- Research Laboratories:National laboratory networks in the United States and Germany consolidate procurement through shared-user facilities, displacing individual investigator purchases. South Korean government institutes pioneered this model most extensively.
- Chemical Industry:Germany's chemical corridor specialty polymer and battery material R&D labs require hermetically sealed manipulation for solid-state electrolyte development.
- Academia:Budget-constrained universities prioritize modular systems with rapid reconfiguration between inert, vacuum, and filtered air modes.
Pharmaceuticals anchor revenue concentration. Research Laboratories reshape procurement economics.
Application:
Process criticality and contamination risk define equipment configuration requirements.
- Containment:Personnel protection systems with negative pressure and HEPA filtration for hazardous material handling in pharmaceutical and nuclear medicine settings. France and Belgium radiopharmaceutical expansion drives specialized demand with limited incumbent competition.
- Material Handling:Semiconductor wafer and battery component manipulation where machine vision and haptic feedback interfaces enable precision without direct manual contact. Taiwan foundries pilot these configurations for 3nm node development.
- Isolation:Separation of sensitive materials from atmospheric exposure in OLED and lithium battery research.
- Glove Box Inerting:Active atmosphere replacement for oxygen and moisture-sensitive operations.
Containment captures premium pricing. Material Handling integrates fastest with automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting glove box procurement toward jurisdictions with streamlined equipment qualification pathways. Manufacturers exploit compliance arbitrage between REACH-heavy European requirements and faster FDA clearance timelines in North America. Production investment follows research subsidy concentration.
United States
Pharmaceutical manufacturers face OSHA-mandated upgrades for legacy isolators handling potent compounds. FDA cGMP guidelines compress equipment validation timelines for sterile containment systems. Massachusetts and North Carolina biotech clusters drive specification complexity for biohazard-rated enclosures.
Germany
Bavaria-based precision engineering dominates European supply for high-integrity containment systems. ECHA REACH restrictions on perfluorinated substances accelerate seal material substitution programs. The chemical corridor spanning Ludwigshafen to Leverkusen anchors demand for corrosive-environment stainless steel configurations.
South Korea
Display manufacturers expand cleanroom footprints for OLED production requiring sub-ppm moisture control. MFDS pharmaceutical manufacturing standards elevate isolation equipment specifications for domestic drug production. Government-funded institutes in Daejeon pioneered shared-user facility models that consolidate procurement.
Taiwan
Semiconductor foundries compress equipment qualification cycles from 18 months to under 12 months for advanced node production. Industrial Technology Research Institute programs subsidize next-generation containment technology adoption. Hsinchu Science Park concentration drives premium inert atmosphere system demand.
India
PLI scheme incentives for advanced chemistry cell production attract gigafactory investments in Gujarat and Tamil Nadu. CDSCO pharmaceutical regulations tighten containment requirements for active pharmaceutical ingredient manufacturing. Research clusters in Hyderabad and Bengaluru require localized supply chains for battery material development.
Glove Box Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular reconfiguration capabilities and predictive maintenance integration. The vendor base stratifies across three archetypes: vertically integrated European specialists, North American biohazard containment focused operations, and Asia-Pacific volume fabricators. Consolidation pressure concentrates among mid-scale operators lacking certified cleanroom integration expertise. Dominant competitive moves include backward integration into seal and gasket manufacturing and technology licensing partnerships for atmosphere control systems.
Among German fabricators, MBRAUN GmbH anchors the premium-tier European supply position through its Bavarian manufacturing base. Labconco Corporation exemplifies the North American biohazard specialization archetype with pharmaceutical cleanroom focus. Jacomex occupies a distinct position serving nuclear and radiopharmaceutical containment requirements with advanced filtration integration.
| Leading Market Players |
|---|
| Labconco Corporation |
| MBRAUN GmbH |
| Jacomex |
| Cleatech LLC |
| Terra Universal Inc. |
| Vacuum Atmospheres Company |
| GS GLOVEBOX Systemtechnik GmbH |
| Coy Laboratory Products Inc. |
| Plas-Labs Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between FDA-validated pharmaceutical containment and standard laboratory enclosures manifests in both pricing power and supply chain sourcing strategies. Premium-tier manufacturers command captive supply relationships for 316L stainless steel and perfluoroelastomer seals, while commodity fabricators compete on acrylic sourcing and nitrile gasket availability.
Pricing Analysis
Distributor margins of 15-25% separate direct OEM procurement from channel-mediated sales in the United States and Germany. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 14644 cleanroom classification and OSHA containment validation tiers. Cost compression in standard acrylic configurations is intensifying because South Korean and Taiwanese volume fabricators are expanding export capacity. Academic buyers exhibit highest price sensitivity; radiopharmaceutical and semiconductor foundry buyers prioritize qualification speed over unit cost.
Supply Chain Analysis
ISO 14644 and FDA cGMP qualification gating restricts qualified supplier pools to fabricators with certified cleanroom integration capabilities. High-grade 316L stainless steel concentrates in Germany and Japan; perfluoroelastomer seals draw from specialized chemical suppliers in the United States and Germany. Single-source vulnerability exists for REACH-compliant fluoropolymer formulations facing regulatory sunset clauses. Distribution runs through regional equipment integrators serving pharmaceutical and semiconductor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA containment standard enforcement and FDA cGMP upgrade mandates generate replacement demand regardless of underlying research cycle volatility.
For Market Incumbents: Hedge against margin erosion in standard acrylic lines by securing backward integration into seal manufacturing and predictive maintenance platform development. Modular reconfiguration capabilities defend position against emerging entrants offering rapid-deployment architectures. Capacity addition in India addresses PLI-scheme battery manufacturing demand while reducing exposure to European REACH compliance cost inflation. For New Entrants and Emerging Players: Enter via radiopharmaceutical isolation systems in France and Belgium where incumbent competition remains limited and ANSM licensing requirements create qualification barriers for established generalists. Battery material R&D shared-user facilities in India and Germany represent the most penetrable segment. A go-to-market angle anchored in digital twin integration and predictive maintenance contracts differentiates against transaction-focused legacy vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale operators lack certified cleanroom integration expertise and struggle to qualify for pharmaceutical and semiconductor procurement lists. Long-term viability favors vertically integrated specialists with captive seal manufacturing and atmosphere control system IP. The signal to watch is qualification timeline compression below 12 months for advanced node semiconductor applications, indicating procurement power concentration among qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captive supply of REACH-compliant fluoropolymer seals insulates margin from ECHA regulatory cost shocks. |
| Predictive Maintenance Platform Launch | Remote monitoring contracts with Taiwan foundries extend customer lifetime value beyond equipment sale. |
| Digital Twin Integration Partnership | Machine vision and haptic feedback convergence enables 3nm node wafer handling without direct manual contact. |
| Regional Manufacturing Footprint in India | Localized assembly addresses PLI-scheme gigafactory demand in Gujarat and Tamil Nadu battery corridors. |
| Radiopharmaceutical Containment Certification | ANSM-aligned filtration integration opens France and Belgium nuclear medicine expansion segments. |
Research Approach
Multiple input streams — primary interviews with cleanroom equipment procurement managers, containment system maintenance directors, and pharmaceutical manufacturing engineers; secondary validation through FDA 483 observation databases, ECHA REACH substance restriction timelines, and SEMI equipment market disclosures — were reconciled through bottom-up installation tracking and top-down expenditure analysis.
Historical qualification cycle data were cross-referenced against panel input from semiconductor foundry procurement leads and battery research facility directors. Segmentation dimensions modeled include product type, material grade, end-user regulatory tier, and application criticality across the projection horizon. CAGRs were derived from equipment shipment trajectories and research facility capex pipelines, with specific weighting for lithium battery and OLED manufacturing capacity expansion schedules.
Inputs from OSHA enforcement databases and MFDS pharmaceutical manufacturing standards were available through the study window; gaps in real-time semiconductor foundry procurement timelines introduce uncertainty bands around advanced node adoption assumptions. Forecasts reflect documented qualification compression trends and regulatory upgrade mandates. A model refresh is warranted upon material change in REACH perfluorinated substance restriction implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market