
 Automotive Exterior LED Lighting Market | 2026-2036
Automotive Exterior LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exterior LED Lighting Market Analytics
OEM procurement is pivoting toward fewer, larger-tier supplier contracts with integrated electronics capability. Koito Manufacturing Co., Ltd. leverages its vertical manufacturing footprint across headlamp assembly. Valeo SA anchors European supply relationships through its matrix LED programming. HELLA GmbH & Co. KGaA competes on adaptive front-lighting software integration.
Automotive exterior LED lighting comprises semiconductor-based solid-state illumination modules engineered for vehicle exteriors, typically operating at 12V-48V with luminous efficacy exceeding 100 lumens per watt, designed to enhance nighttime visibility and pedestrian detection. Headlights and taillights command the largest value pools given their regulatory-mandated presence and premium styling differentiation. Electric vehicles represent the fastest-growing application segment as platform voltages and energy budgets favor LED architectures. RGB and dynamic lighting technologies capture expanding share as automakers deploy signature light sequences for brand recognition.
NHTSA in the United States, ECE regulations under UN-ECE frameworks, and China's GB standards collectively enforce photometric performance, glare limits, and electromagnetic compatibility for exterior LED systems. These frameworks elevate engineering barriers while accelerating replacement cycles as compliance deadlines tighten. Stakeholders must monitor how software-defined lighting functions trigger reclassification debates between vehicle safety and consumer electronics regulatory domains.
Market Dynamics
Platform electrification is compressing headlamp development cycles as 48V architectures demand new thermal management and optical efficiency standards from legacy 12V suppliers.
Growth Catalysts
- ECE R48 Visibility Mandates:Europe's regulatory framework mandates minimum luminous intensity and beam pattern uniformity, forcing automakers to upgrade halogen and xenon systems to LED modules.
- China EV Production Scaling:Domestic electric vehicle manufacturers are specifying full-LED exterior lighting as standard equipment across mass-market segments, creating concentrated demand pull.
- Matrix Beam Programming:Adaptive driving beam technology selectively masks oncoming traffic while maintaining high-beam illumination, delivering safety differentiation that commands pricing premiums.
Market Restraints
- Semiconductor Input Volatility:LED driver ICs and power management chips face supply concentration among Taiwanese and South Korean foundries, exposing module assemblers to allocation risk.
- Optical Design Complexity:Miniaturized projector systems require sub-micron tolerance in lens molding, limiting viable supplier pools to capital-intensive Tier 1s with captive tooling.
- Retrofit Substitution Limitation:Aftermarket LED conversion kits face NHTSA non-compliance penalties in the United States, constraining secondary market expansion.
Strategic Opportunities
- India Two-Wheeler Electrification:The country's FAME-II subsidy scheme and tightening BS-VI emission norms are accelerating LED headlamp adoption across scooter and motorcycle platforms.
- LiDAR Integration Convergence:Exterior lighting modules are incorporating embedded sensor housings, creating new value pools at the intersection of illumination and autonomous perception.
- Software-Defined Lighting:Over-the-air updatable beam patterns enable automakers to monetize feature unlocks and regional compliance adaptations post-sale.
Industry Challenges
- Photometric Calibration Talent Scarcity:Specialized optical engineers capable of integrating LED sources with free-form reflector designs command premium compensation, constraining R&D velocity at mid-tier suppliers.
- Homologation Timeline Compression:UN-ECE type approval processes for adaptive front-lighting systems now require extensive real-world glare validation, extending program schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exterior LED Lighting Market |
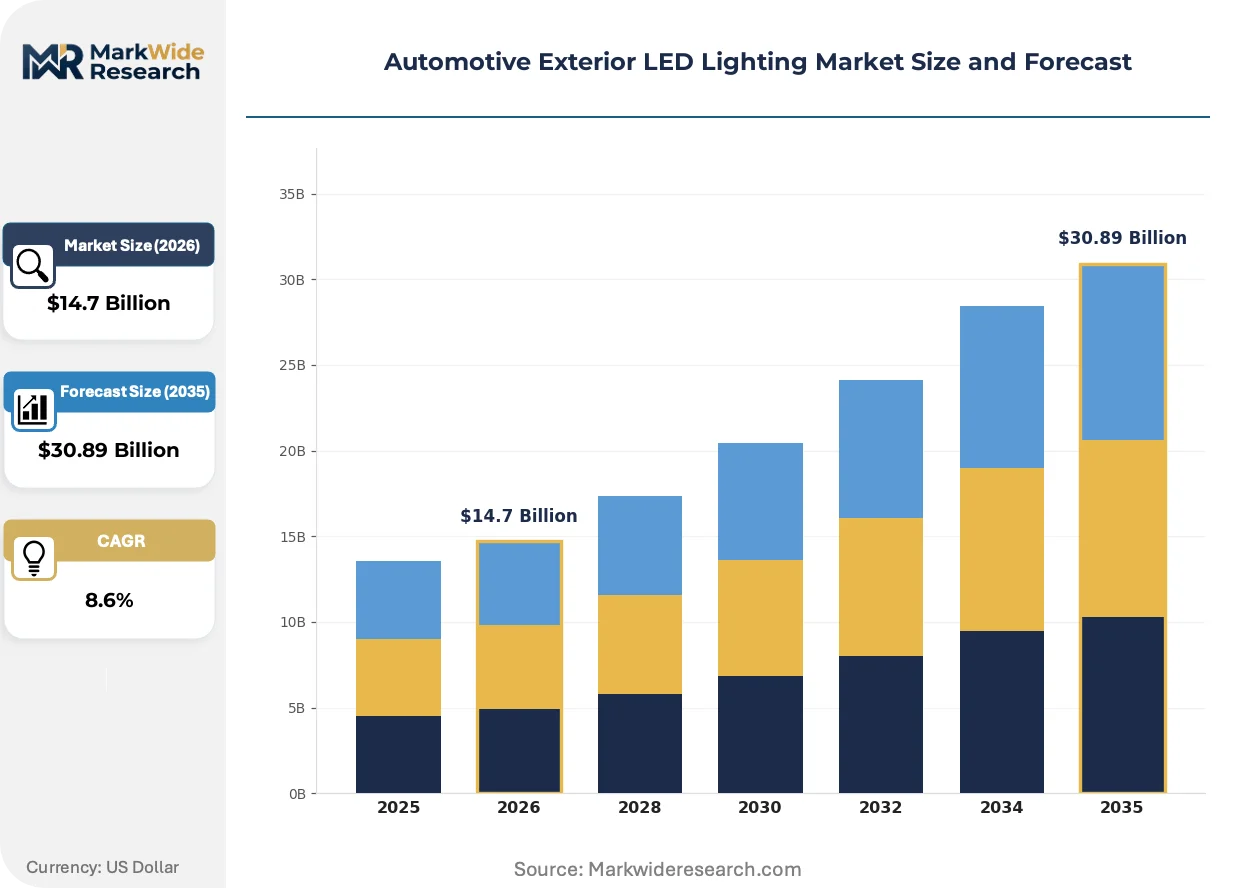
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Turn Signal Lights Technology: RGB, Dynamic Lighting, Adaptive Lighting, Standard LED Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Koito Manufacturing Co., Ltd., Valeo SA, HELLA GmbH & Co. KGaA, Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., Osram GmbH, Hyundai Mobis Co., Ltd., ZKW Group GmbH, Lumileds LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exterior LED Lighting Market Evolving Landscape
Digital light processing is replacing mechanical actuation in headlamp systems, compressing component counts while enabling real-time beam manipulation. Three developments dominate current engineering priorities.
Micro-LED arrays with individually addressable pixels are automating glare-free high-beam operation through machine-vision integration. Premium electric vehicle platforms from German and Chinese OEMs are adopting these systems at 3-5x the rate of mass-market internal combustion programs. This automation is collapsing the traditional separation between lighting hardware and ADAS perception stacks.
REACH substance restrictions on halogenated flame retardants are forcing housing material transitions to glass-filled polyamides and thermally conductive plastics. European suppliers face accelerated requalification timelines as ECHA adds new SVHC candidates annually. Module manufacturers with pre-validated material libraries capture disproportionate share of platform awards.
Fleet procurement of lighting-as-a-service is emerging in commercial vehicle segments, unbundling hardware ownership from maintenance and upgrade obligations. Logistics operators in Germany and the Netherlands are piloting contracts where suppliers retain asset title and guarantee lumen maintenance over 7-year lease terms. This model shifts technical risk to vendors while capturing total-cost advantages for high-utilization fleets.
Automotive Exterior LED Lighting Market Segmentation
Segmentation in automotive exterior LED lighting reveals how upgrade cycles, platform electrification, and regulatory mandates concentrate value across distinct technology tiers and supply chain positions. Understanding these divisions exposes where procurement power is shifting and which specifications command pricing premiums.
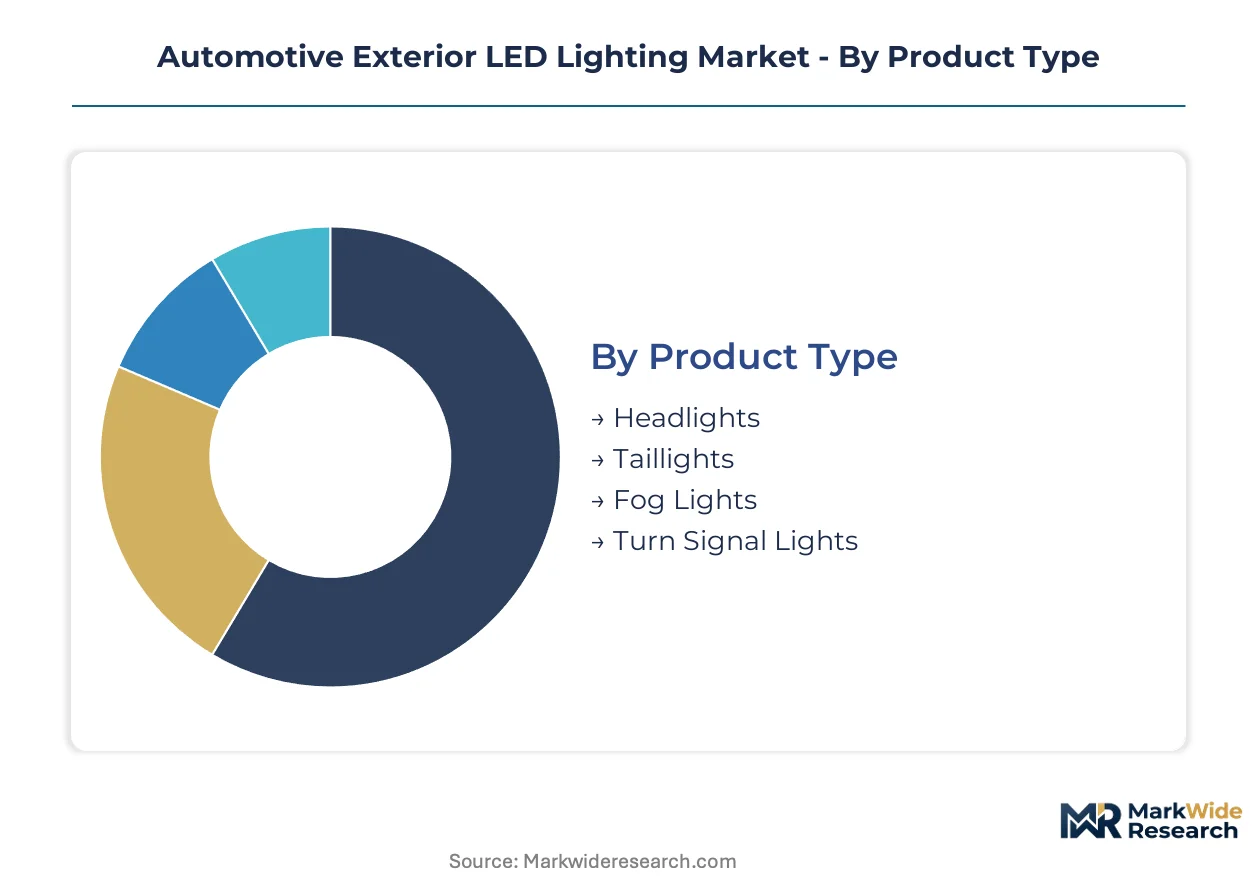
Product Type:
Replacement intensity varies sharply across exterior lighting positions, with regulatory mandates and styling differentiation driving divergent upgrade timelines.
- Headlights:Matrix and adaptive LED projector modules now dominate premium platform specifications, with German OEMs and Chinese EV manufacturers standardizing full-LED low-beam and high-beam systems. Thermal management requirements under 48V architectures are forcing housing redesigns that favor suppliers with integrated electronics capability.
- Taillights:Sequential and animated signature lighting functions have transformed rear illumination from compliance hardware into brand identity assets, with Chinese domestic brands deploying full-width LED light bars across mass-market segments. OLED and mini-LED implementations are penetrating luxury tier designs.
- Fog Lights:Dedicated fog lamp modules face displacement as adaptive headlight systems extend low-beam width, though commercial vehicle applications in India and Brazil maintain steady specification.
- Turn Signal Lights:Mirror-integrated and sequential sweep configurations are replacing static filament-based units, with dynamic activation patterns now mandated under ECE R48 for certain vehicle categories.
Headlights sit at the top of the volume ranking, with taillights climbing the fastest as signature lighting becomes standard equipment.
Technology:
Cost-to-performance positioning separates technologies into distinct specification tiers, with premium functions filtering down through platform generations.
- RGB:Multi-color addressable LEDs enable customizable accent lighting and brand-specific color temperatures, with Chinese EV startups deploying these systems for user-configurable exterior illumination. NHTSA glare compliance limits restrict certain color outputs to parking and startup sequences.
- Dynamic Lighting:Sequential activation and sweep patterns now appear across mid-tier passenger vehicles, with animation controllers integrated into body domain modules. Software-defined sequencing allows regional customization without hardware changes.
- Adaptive Lighting:Matrix beam systems with selective masking of oncoming traffic represent the performance ceiling, with German KBA type approval processes extending homologation timelines. Machine vision integration collapses the boundary between lighting and ADAS hardware.
- Standard LED:Fixed-pattern white LED modules dominate replacement demand and economy vehicle specifications, with chip-on-board designs from Korean and Taiwanese suppliers capturing volume production.
Standard LED holds the installed base advantage, though adaptive lighting is gaining share fastest as premium platform architectures proliferate.
Application:
Platform voltage and energy budget characteristics determine LED specification intensity across vehicle categories.
- Passenger Vehicles:C-segment and above platforms specify full-LED exterior lighting as standard, with German and Chinese OEMs leading matrix beam adoption. Styling differentiation through lighting signatures intensifies competitive positioning.
- Commercial Vehicles:Fleet procurement prioritizes lumen maintenance and service interval extension, with Dutch and German logistics operators piloting lighting-as-a-service contracts that transfer technical risk to suppliers.
- Two-Wheelers:India's FAME-II subsidy scheme and tightening BS-VI emission norms are accelerating LED headlamp adoption across scooter and motorcycle platforms, with domestic suppliers scaling projector module production.
- Electric Vehicles:Platform voltages and regenerative braking energy budgets favor LED architectures, with Chinese domestic manufacturers specifying full-LED exterior lighting across all market segments. Battery thermal management proximity influences headlamp housing material selection.
Passenger vehicles anchor current volume, while electric vehicles are expanding most quickly as platform architectures proliferate.
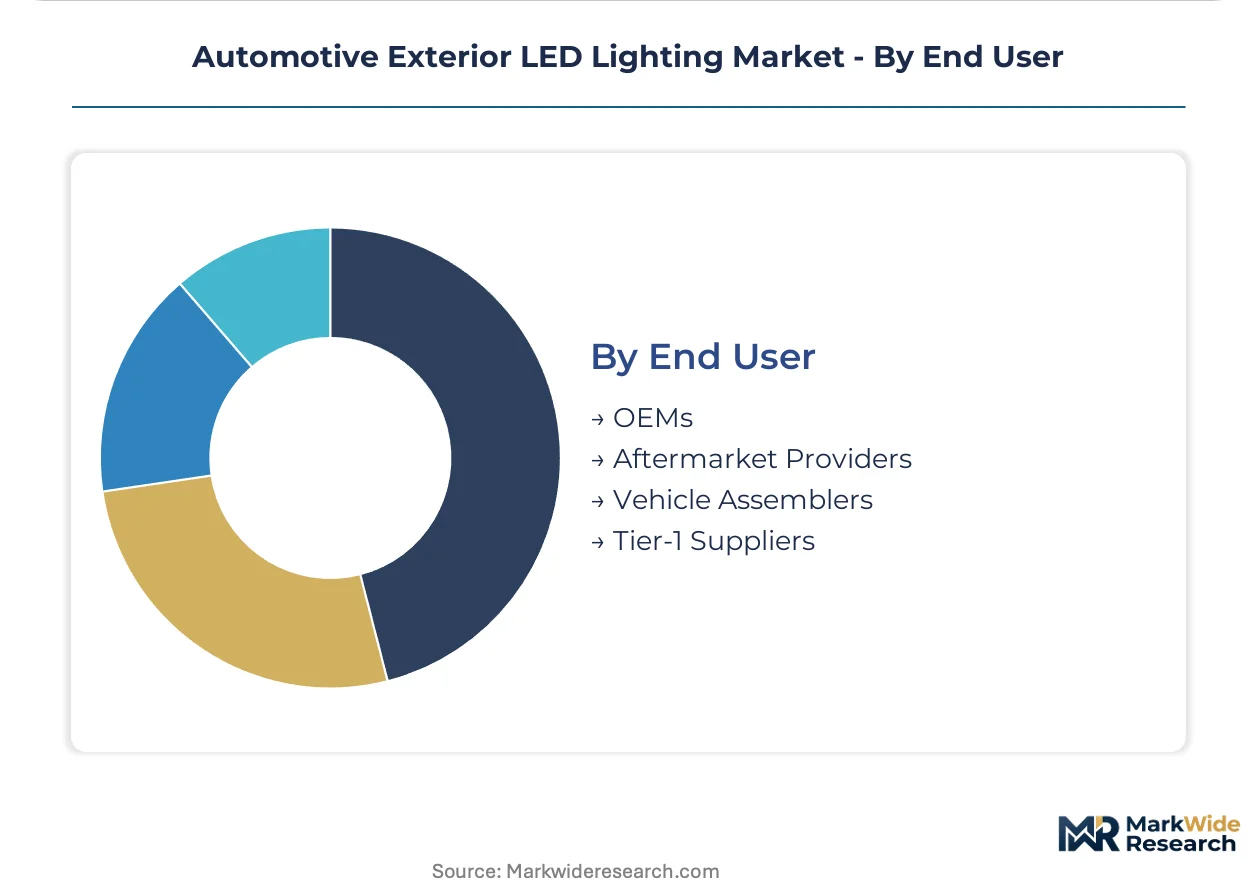
End User:
Supply chain position determines specification authority and technical integration requirements.
- OEMs:Brand-holding manufacturers increasingly specify software-defined lighting functions and over-the-air update capability, compressing Tier-1 supplier margins while retaining feature monetization rights.
- Aftermarket Providers:NHTSA non-compliance penalties constrain LED conversion kit expansion in the United States, though European regulatory frameworks permit broader retrofit authorization.
- Vehicle Assemblers:Contract manufacturing arrangements in emerging markets source complete lighting modules from integrated Tier-1 suppliers rather than managing component integration.
- Tier-1 Suppliers:Module manufacturers with captive electronics design, thermal simulation, and optical calibration capabilities capture disproportionate platform awards as development cycles compress.
Tier-1 suppliers dominate technical specification, with OEMs climbing fastest as software control becomes a competitive battleground.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in southern Germany and Japan's industrial corridors anchor technical specification authority. Procurement decisions concentrate where Tier-1 suppliers maintain captive thermal simulation and photometric calibration capabilities.
Germany
Matrix beam homologation expertise and KBA type-approval processes concentrate in Stuttgart and Munich industrial zones. ECE R48 mandates enforce minimum luminous intensity standards that accelerate LED upgrades from legacy halogen systems. Baden-Württemberg suppliers dominate adaptive front-lighting software integration for premium German OEM platforms.
China
Domestic EV manufacturers specify full-LED exterior lighting across mass-market segments, creating concentrated demand pull in Yangtze River Delta manufacturing hubs. GB standards enforce photometric performance and electromagnetic compatibility for exterior LED systems. Shenzhen and Shanghai clusters scale projector module production for two-wheeler and passenger vehicle platforms.
United States
NHTSA glare compliance limits and non-compliance penalties on aftermarket conversion kits shape OEM procurement patterns. Detroit-area engineering centers specify software-defined lighting functions with over-the-air update capability. Michigan-based Tier-1s integrate LED driver ICs with body domain modules for domestic automaker platforms.
Japan
JIS standards and METI industrial policy support LED adoption across hybrid and electric vehicle architectures. Nagoya and Tokyo metropolitan areas host concentrated optical design engineering for headlamp thermal management. Domestic suppliers leverage captive electronics capability to capture platform awards from Japanese OEM electrification programs.
India
FAME-II subsidy schemes and tightening BS-VI emission norms accelerate LED headlamp adoption across scooter and motorcycle platforms. BIS certification requirements elevate engineering barriers for module suppliers. Tamil Nadu and Gujarat manufacturing corridors scale domestic projector production for two-wheeler electrification.
Automotive Exterior LED Lighting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers. Market structure concentrates around integrated Tier-1s with captive electronics design, thermal simulation, and optical calibration capabilities. Three archetypes dominate: Japanese vertical manufacturers with in-house semiconductor packaging, European software-integrated lighting specialists, and Korean chaebol-affiliated module suppliers. Competitive moves center on strategic partnerships for LiDAR integration and geographic expansion into Indian two-wheeler electrification.
Within the Japanese vertical manufacturing tier, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. exemplify capital-intensive integration from LED chip packaging through headlamp assembly. European specialists Valeo SA and HELLA GmbH & Co. KGaA occupy positions emphasizing matrix LED programming and adaptive front-lighting software. Marelli Holdings Co., Ltd. represents the diversified automotive supplier archetype with cross-platform lighting module capability.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| Osram GmbH |
| Hyundai Mobis Co., Ltd. |
| ZKW Group GmbH |
| Lumileds LLC |
| Others |
Value Network & Pricing Analysis
Matrix LED programming and embedded sensor integration are compressing module economics while concentrating procurement power among Tier 1 suppliers with captive electronics capability. Chinese EV manufacturers' full-LED standard specifications and European ECE R48 compliance deadlines are simultaneously expanding volume scale and elevating performance thresholds that reshape supplier margins.
Pricing Analysis
Lighting-as-a-service contracts for commercial fleets unbundle hardware ownership from maintenance obligations, while transactional module sales dominate passenger vehicle procurement. Three-tier pricing structure across premium adaptive systems, standard full-LED configurations, and economy fixed-pattern modules separates matrix beam platforms from mass-market specifications. Price differentiation hinges on software-defined update capability and thermal management integration, with cost compression in standard LED tiers intensifying due to Korean and Taiwanese chip-on-board supplier expansion. Aftermarket providers exhibit highest price sensitivity from NHTSA non-compliance exposure, while German OEMs prioritize performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit coordinate hub-and-spoke patterns for finished module delivery to assembly plants. Manufacturing concentration centers on Germany, China, and Japan, with LED driver ICs and power management chips drawing from Taiwanese and South Korean foundry capacity. Aluminum thermal substrates, optical-grade polycarbonate, and flame-retardant polyamides constitute critical input dependencies. Single-source vulnerability in semiconductor foundry allocation represents the dominant structural risk. Distribution runs through Tier 1 direct-to-OEM channels with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
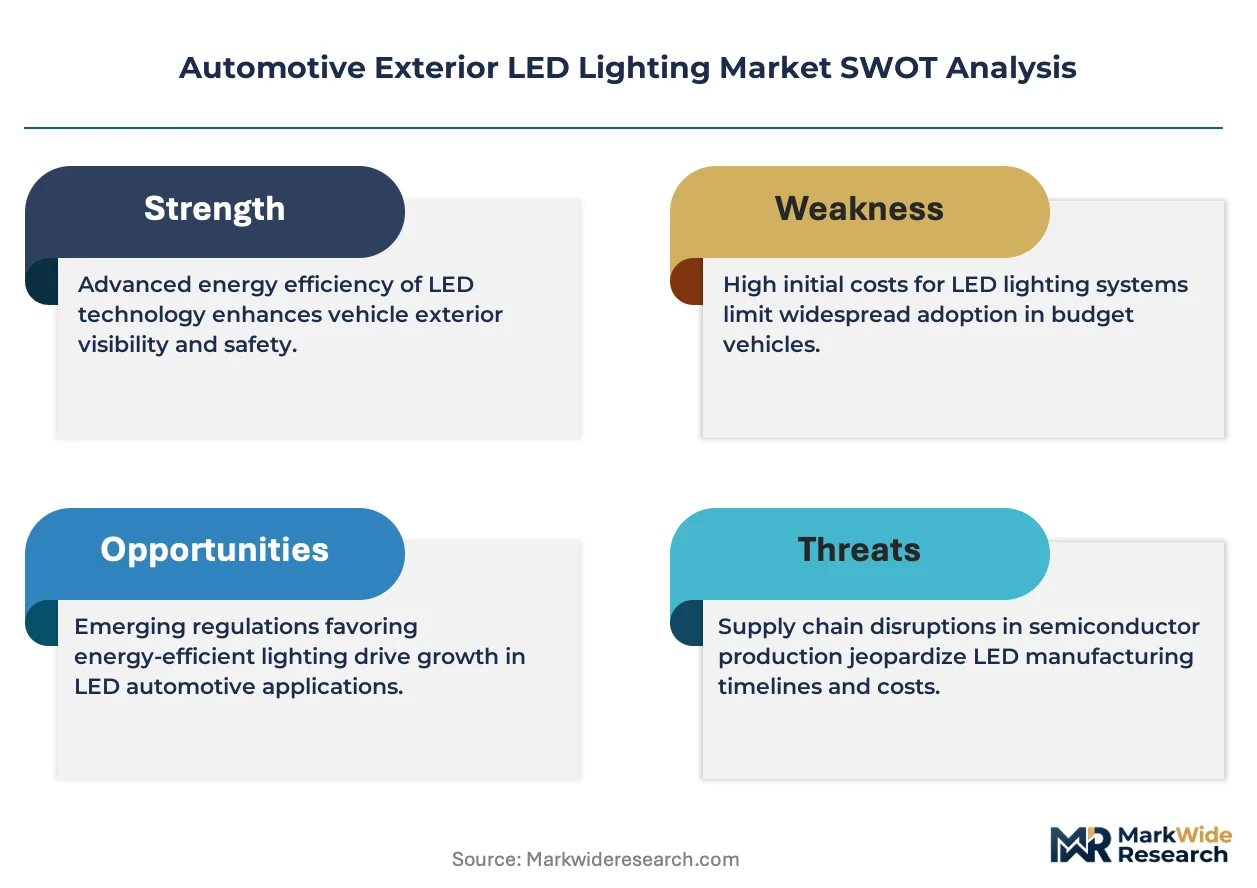
Automotive exterior LED lighting has transitioned into a late-cycle quality story where matrix beam adoption and software-defined functionality command sustainable premiums. Chinese EV platform standardization and European regulatory upgrade mandates are shifting procurement toward integrated suppliers with optical calibration and thermal simulation capabilities.
For Market Incumbents: Extend software-defined lighting roadmaps to capture over-the-air monetization rights before OEMs internalize beam programming. Deepen backward integration into LED driver IC design to offset Taiwanese foundry allocation risk. Prioritize LiDAR-embedded module development as autonomous perception hardware converges with illumination housings. Lock in long-term contracts with German OEMs ahead of KBA homologation timeline extensions.
For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched Tier 1 relationships for commercial vehicle lighting-as-a-service contracts. Target Indian two-wheeler electrification as the most penetrable segment, where FAME-II subsidies and BS-VI norms are displacing halogen suppliers without established LED projector expertise. Pursue white-label partnerships with domestic assemblers in Tamil Nadu and Gujarat manufacturing corridors.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier module suppliers lacking captive electronics design but holding validated optical calibration talent. Five-to-ten year viability favors integrated players with thermal simulation software and regional homologation expertise. Acquisition focus: Tier 2 specialists with free-form reflector engineering capabilities in southern Germany or Japan's Nagoya corridor. Signal to monitor: KBA and UN-ECE regulatory harmonization timelines for adaptive front-lighting approval.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Lighting Investment | Enables OEM monetization of beam pattern updates through over-the-air deployment. |
| LiDAR-Embedded Module Development | Captures autonomous perception value pools at the illumination-sensor convergence point. |
| Indian Two-Wheeler Manufacturing Footprint | Positions suppliers for FAME-II subsidy-driven LED headlamp specification acceleration. |
| Backward Integration into Driver IC Design | Reduces exposure to Taiwanese foundry allocation constraints for power management chips. |
| Lighting-as-a-Service Contract Structuring | Transfers technical risk to vendors while capturing fleet procurement preference in Germany and Netherlands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier 1 supplier procurement executives, OEM platform engineers, aftermarket distributors, and dealership operations managers across Germany, China, Japan, and the United States. Secondary validation drew from vehicle production databases, IHS Markit registration data, UN-ECE type approval filings, and customs records for LED module trade flows. Bottom-up segment modeling and top-down macroeconomic triangulation reconciled volume and value estimates.
Segment-weighting approaches distributed growth assumptions across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from regression analysis of historical specification penetration and forward projection of regulatory compliance deadlines. Industry-specific forecast inputs incorporated ECE R48 implementation timelines, Chinese EV platform rollout schedules, and semiconductor foundry capacity expansion announcements. Outputs were stress-tested against alternative scenarios for electrification adoption speed.
Semiconductor supply disruption, regulatory harmonization delays, and raw material cost volatility are the dominant revision risks for projection accuracy. Forecasts reflect documented assumptions regarding OEM procurement consolidation and software monetization capture rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Center Stack Display Market