
 Automotive Glove Compartment Market | 2026-2036
Automotive Glove Compartment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Glove Compartment Market Analysis
Buyer concentration among premium passenger vehicle OEMs is decoupling from traditional mass-market fleet contracts as electric vehicle startups and luxury sub-brands fragment procurement channels. Faurecia leverages its vertically integrated plastics and electronics portfolio to capture design-led glove compartment programs for European premium platforms. Lear Corporation anchors North American supply through its seating and electrical distribution expertise, which extends into integrated storage modules with embedded connectivity. Yanfeng Automotive Interiors dominates Asia-Pacific sourcing by controlling regional manufacturing scale and local OEM relationships.
An automotive glove compartment is a hinged, enclosed storage recess integrated into the passenger-side instrument panel, typically constructed from injection-molded polypropylene or acrylonitrile butadiene styrene composites with felt or foam lining to dampen rattles and protect contents; its primary purpose is to secure vehicle documents, personal items, and increasingly electronic devices within the occupant compartment. Lockable and modular product types are capturing the fastest expansion as OEMs specify theft-deterrent and reconfigurable interior architectures, while plastic materials sustain volume leadership due to cost efficiency and recyclability compliance. Heated and insulated feature variants are emerging at the premium margin pool as electric vehicle thermal management systems create surplus cabin conditioning capacity.
The EPA regulates volatile organic compound emissions from interior plastics through its automotive coating and composite material guidelines, while ECE R21 governs occupant head-impact safety for instrument panel protrusions in European type-approved vehicles. NHTSA's FMVSS 201 standard shapes United States glove compartment latch and edge-radius requirements to reduce injury risk during collisions. Stakeholders must monitor how evolving battery electric vehicle platform architectures redistribute instrument panel space and thermal budgets, because these redesigns will determine whether glove compartments shrink, relocate, or absorb new electronic and climate functions.
Market Dynamics
Electric vehicle platform architectures are redistributing instrument panel thermal budgets and spatial configurations, forcing glove compartment suppliers to redesign modules around battery cooling systems and relocated HVAC components.
Growth Catalysts
- REACH chemical compliance:European OEMs are accelerating material transitions to low-VOC polypropylene compounds that satisfy ECHA substance restrictions, creating specification pull for qualified Tier 1 suppliers.
- Modular reconfigurable interiors:Premium passenger vehicle platforms demand lockable storage modules with removable liners and integrated wireless charging pads.
- Germany-Japan-US engineering clusters:Final assembly concentration in these three markets concentrates procurement authority with regional platform engineering centers.
Market Restraints
- Polypropylene resin volatility:Feedstock cost fluctuations for injection-molded thermoplastics compress margin stability at contract-renewal cycles.
- Single-source tooling dependency:Complex multi-cavity molds for instrument panel integration limit supplier switching flexibility.
- Head-impact safety certification:ECE R21 and FMVSS 201 testing protocols add 8-14 month validation timelines for new latch geometries.
Strategic Opportunities
- Heated and insulated variants:Surplus thermal capacity from electric vehicle battery conditioning systems enables cabin-connected glove compartment climate features.
- Embedded connectivity modules:Convergence of USB-C power delivery and NFC authentication is opening specification slots for electronics-integrated storage units.
- Urban China premium EV startups:NIO, Li Auto, and XPeng platform architectures specify customizable interior modules with shorter development cycles than legacy OEMs.
Industry Challenges
- Cross-functional integration:Seating, electrical distribution, and thermal engineering teams now share glove compartment specification authority, complicating supplier interface management.
- Recyclability certification timelines:ISO 14021 environmental claims verification and EU end-of-life vehicle directive compliance require parallel material documentation streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Glove Compartment Market |
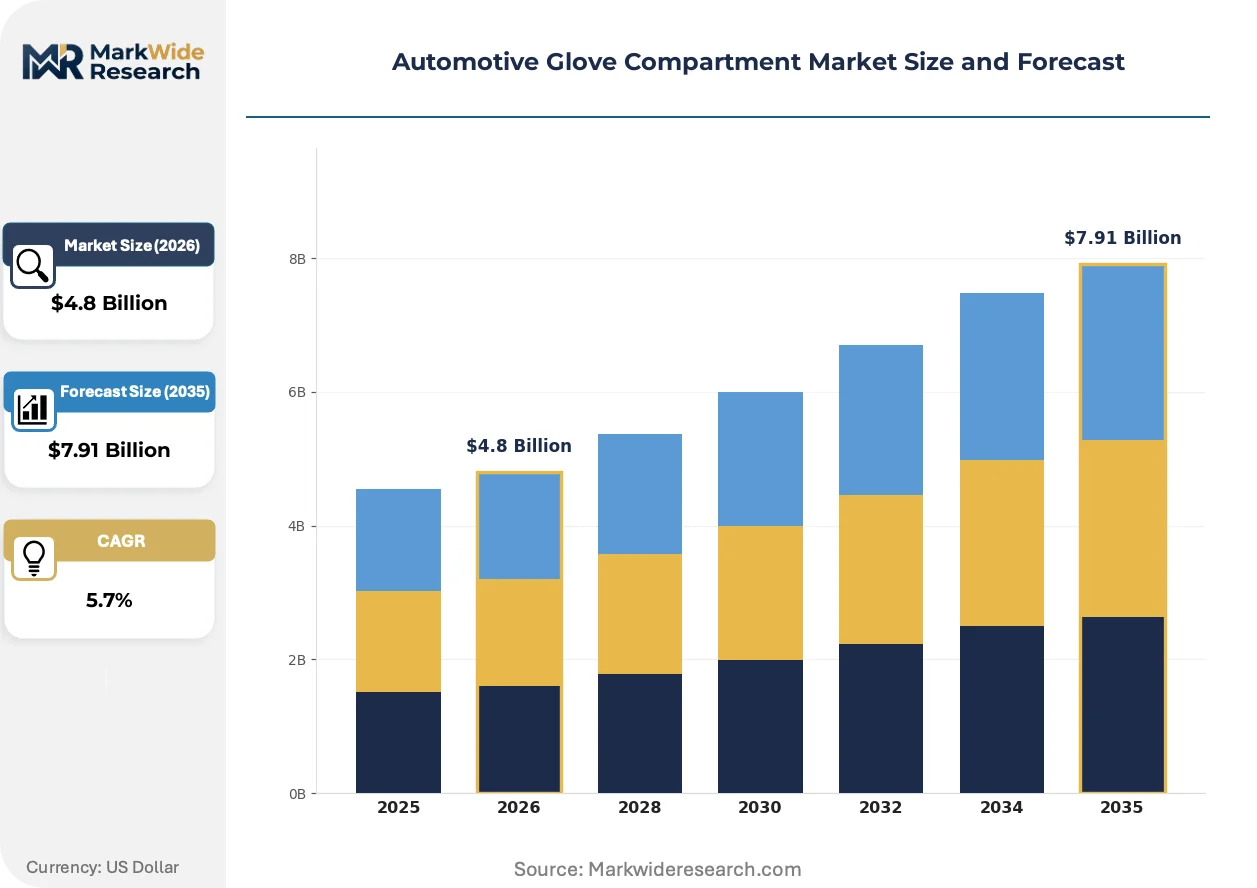
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Lockable, Modular, Customizable Material: Plastic, Leather, Fabric, Metal End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Custom Shops Feature: Heated, Insulated, Waterproof, Soundproof |
| Companies Covered | Faurecia, Lear Corporation, Magna International Inc, Toyoda Gosei, Hyundai Mobis, IAC Group, Grupo Antolin, Visteon Corporation, Yanfeng Automotive Interiors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Glove Compartment Market Emerging Trajectories
Instrument panel module suppliers are converging mechanical storage, thermal management, and power electronics into unified occupant-compartment units. This integration is compressing traditional component boundaries and elevating electrical architecture expertise as a procurement criterion.
Soft-touch thermoplastic elastomer overmolding is electrifying surface-quality expectations for premium glove compartment interfaces. German luxury OEMs have adopted dual-shot injection processes for haptic differentiation. This capability gap is separating qualified Tier 1 integrators from commodity plastics molders.
EPA automotive coating guidelines and ECE R21 head-impact protocols are tightening simultaneously across transatlantic supply chains. Dual-compliance engineering now consumes 15-20% of development budgets for new instrument panel programs. North American suppliers are consolidating validation testing in Michigan and Ontario facilities to reduce certification cycle redundancy.
Direct OEM-platform engineering relationships are displacing traditional Tier 1-Tier 2 specification hierarchies in glove compartment procurement. Electric vehicle startups in California and Shanghai are issuing module-level RFQs to specialized interior component houses, bypassing consolidated seating and electronics distributors. This channel fragmentation is most pronounced in premium battery electric vehicle segments where platform volumes remain below legacy scale thresholds.
Automotive Glove Compartment Market Segmentation
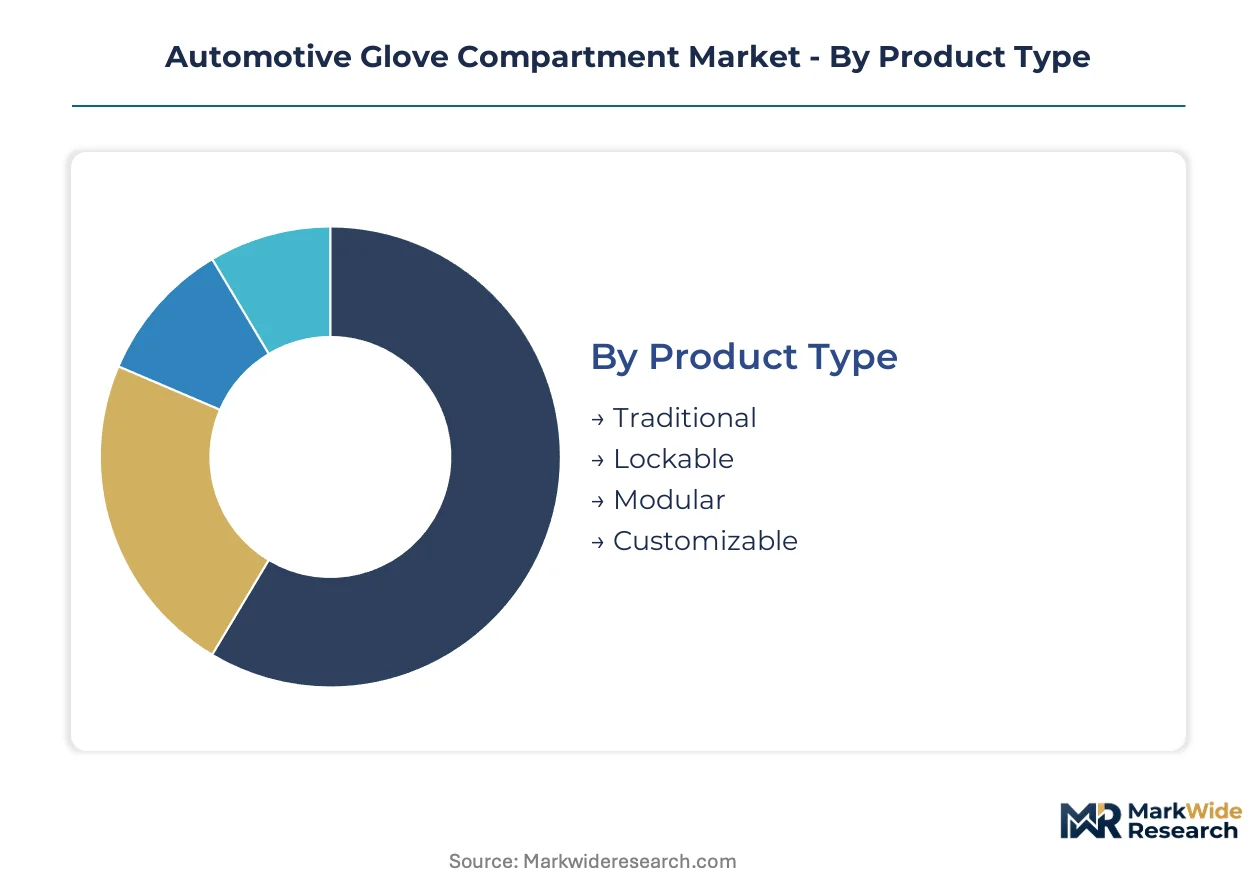
Glove compartment procurement splits across four distinct specification axes. Each dimension carries different margin profiles, certification burdens, and supplier qualification requirements that shape competitive positioning.
Product Type:
Engineering specifications define how storage modules integrate with instrument panel architectures and occupant safety systems.
- Traditional:Fixed-hinged enclosures with single-latch closure dominate mass-market vehicle platforms where cost engineering priorities override feature complexity. Demand concentrates in high-volume compact and mid-size segments across Germany, Japan, and the United States where OEMs prioritize tooling amortization across multi-year model cycles.
- Lockable:Key-cylinder or electronic-latch mechanisms deter theft of vehicle documents and personal devices. Premium passenger vehicle OEMs in Germany specify these for luxury sub-brands, driven by insurance industry pressure and residual value protection requirements.
- Modular:Removable liners and reconfigurable internal partitions accommodate varying cargo dimensions. Electric vehicle startups specify these for cabin flexibility.
- Customizable:Bespoke trim finishes and personalized embossing serve limited-production luxury and coachbuilt vehicles. Low volumes sustain artisan supplier networks.
Traditional leads on scale; lockable leads on momentum.
Material:
Substrate selection determines weight, recyclability compliance, and surface quality achievable within thermal budget constraints.
- Plastic:Injection-molded polypropylene and ABS composites deliver cost efficiency and REACH chemical compliance for high-volume production. European OEMs specify low-VOC compounds from qualified Tier 1 suppliers to satisfy ECHA substance restrictions.
- Leather:Full-grain and synthetic hides provide haptic differentiation for luxury vehicle interiors. German premium OEMs source these through seating supplier networks to ensure color and grain matching across cabin touchpoints.
- Fabric:Woven textiles and felt linings dampen rattles and protect delicate contents. Aftermarket providers favor these for repair and replacement applications.
- Metal:Aluminum and steel reinforcements strengthen lockable variants against forced entry. Custom shops specify these for security-focused vehicle modifications.
Plastic dominates manufacturing throughput; leather commands premium pricing power.
End User:
Channel structure determines specification authority, development cycle length, and volume forecasting reliability.
- OEMs:Original equipment manufacturers issue platform-level RFQs with 3-5 year production commitments and integrated instrument panel engineering requirements. Procurement authority concentrates in Germany, Japan, and United States engineering centers.
- Aftermarket Providers:Independent distributors and repair networks supply replacement units for collision repair and wear-related replacement. These channels bypass Tier 1 integrators and source directly from specialized molders.
- Vehicle Assemblers:Contract manufacturers and regional assembly plants purchase modules for knock-down kit production. Specifications follow parent OEM designs with limited localization.
- Custom Shops:Bespoke vehicle modifiers and coachbuilders commission one-off or small-batch glove compartments. These orders prioritize design flexibility over unit cost.
OEMs anchor volume planning; aftermarket providers expand addressable market reach.
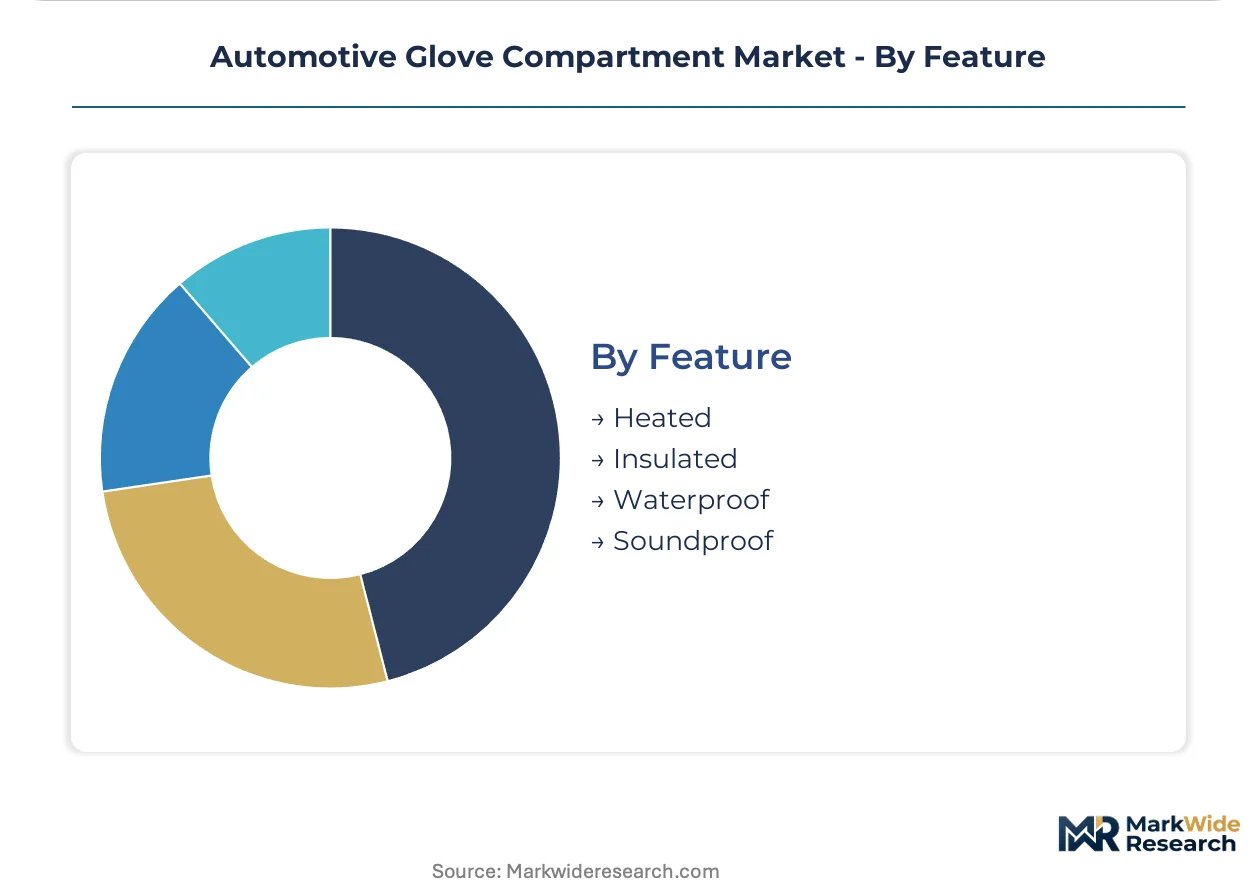
Feature:
Functional augmentation transforms storage modules into climate-managed, connected cabin assets.
- Heated:Electric resistance elements maintain beverage and device temperature using surplus thermal capacity from battery conditioning systems. NIO, Li Auto, and XPeng specify these for premium electric vehicle differentiation.
- Insulated:Foam-core construction and sealed gaskets extend temperature retention duration. German luxury OEMs integrate these with cabin thermal management for extended-range electric platforms.
- Waterproof:Gasketed seals and drainage channels protect contents from liquid intrusion. Aftermarket providers target off-road and marine vehicle applications.
- Soundproof:Multi-layer acoustic damping reduces road noise transmission through instrument panel cavities. Custom shops specify these for luxury vehicle conversions.
Heated variants gain share fastest; insulated builds longest development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium glove compartment engineering while the United States anchors high-volume production scale. Japan maintains specialized thermal management integration capabilities. Procurement authority concentrates where final vehicle assembly clusters intersect with Tier 1 supplier engineering centers.
Germany
Luxury sub-brands from BMW and Mercedes-Benz specify lockable modules with customizable trim finishes. ECE R21 head-impact safety standards and REACH chemical compliance from ECHA mandate low-VOC polypropylene compounds. Engineering centers in Stuttgart and Munich coordinate specification authority for European platform architectures.
United States
Detroit Three OEMs and electric vehicle startups in California drive demand for modular storage with embedded connectivity. NHTSA's FMVSS 201 standard governs latch and edge-radius requirements for occupant protection. Tier 1 supplier validation facilities in Michigan and Ontario consolidate transatlantic certification testing.
Japan
Toyota and Honda platform engineering teams integrate glove compartment modules with instrument panel thermal management systems. METI industrial standards and JIS quality protocols shape material specifications for domestic production. Nagoya-based suppliers coordinate with OEM engineering centers on heated and insulated variant development.
China
NIO, Li Auto, and XPeng specify reconfigurable interior modules with shorter development cycles than legacy OEMs. GB standards from SAMR and MIIT regulate interior component safety and material emissions. Yangtze River Delta manufacturing clusters around Shanghai concentrate regional sourcing for premium electric vehicle platforms.
South Korea
Hyundai Motor Group and Kia specify integrated storage modules for battery electric vehicle platforms. MFDS chemical safety guidelines and KATRI automotive testing protocols govern interior material compliance. Seoul Capital Area engineering centers coordinate procurement with Busan-Ulsan manufacturing corridors.
Automotive Glove Compartment Market Vendor Landscape
German producers anchor the premium tier through design-led engineering capabilities; North American specialists hold volume manufacturing scale. The supplier base organizes into three strategic archetypes: vertically integrated plastics-electronics houses, seating-and-electrical distributors extending into storage modules, and regional manufacturing specialists controlling local OEM relationships. Competitive dynamics center on backward integration into injection-molding tooling and strategic partnerships for connectivity module integration.
Within the integrated systems tier, Faurecia and Lear Corporation exemplify archetypes combining plastics manufacturing with electronics distribution. Yanfeng Automotive Interiors occupies a position representing Asia-Pacific regional scale advantages. These three anchors demonstrate how procurement channel fragmentation favors suppliers with cross-functional capabilities spanning mechanical storage, thermal engineering, and power electronics integration.
| Leading Market Players |
|---|
| Faurecia |
| Lear Corporation |
| Magna International Inc |
| Toyoda Gosei |
| Hyundai Mobis |
| IAC Group |
| Grupo Antolin |
| Visteon Corporation |
| Yanfeng Automotive Interiors |
| Others |
Supply Flow & Price Mechanics
REACH chemical compliance from ECHA gates both qualified supply and premium-tier pricing access, as European OEMs restrict procurement to Tier 1 suppliers with validated low-VOC polypropylene compound documentation. German luxury brands leverage this qualification bottleneck to sustain margin premiums on lockable modules with customizable finishes.
Pricing Analysis
Capacity additions in China are reshaping price floors for injection-molded storage modules as Yangtze River Delta manufacturers achieve scale economies. Three-tier pricing structure across premium, standard, and economy levels separates German design-led engineering from Asian volume manufacturing and aftermarket commodity supply. Cost compression in mass-market segments is intensifying because polypropylene resin volatility feeds directly into contract-renewal negotiations. Fleet procurement teams at Detroit Three OEMs exhibit highest price sensitivity; premium EV startups in California and Shanghai show lowest sensitivity for feature-integrated variants.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for platform-integrated instrument panel modules, bypassing traditional Tier 1-Tier 2 hierarchies. Manufacturing concentrates in Germany, China, and Japan where multi-cavity injection molding tooling and ECE R21 validation facilities cluster. Feedstock draws from petrochemical complexes in the US Gulf Coast, Middle East, and Northeast Asia. Single-source tooling dependency creates structural vulnerability when mold transfers require 8-14 month requalification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed GB standard requirements in China by a substantial margin, creating dual-sourcing opportunities for qualified suppliers.
For Market Incumbents: Acquire specialized injection-molding tooling assets in Busan-Ulsan corridors to anchor capacity for Hyundai-Kia electric vehicle platforms. Defend against California EV startups by embedding NFC authentication and USB-C power delivery into platform-standard modules. Prioritize certification investment for ECE R21 and FMVSS 201 dual compliance to maintain specification access across transatlantic programs.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in heated and insulated variants offers white-space entry for thermal engineering specialists. Target NIO, Li Auto, and XPeng procurement teams with 12-18 month development cycle advantages over legacy OEMs. Penetrate modular reconfigurable segments through direct platform engineering relationships that bypass consolidated seating distributors.
For Investors and Strategic Acquirers: Roll-up economics work for regional plastics-electronics integrators because procurement channel fragmentation favors cross-functional capability bundles. Five-to-ten year viability hinges on battery electric vehicle platform volumes sustaining instrument panel redesign cycles. Monitor specification authority shifts from seating suppliers to electrical distribution houses as embedded connectivity becomes standard.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling amortization burden for multi-OEM glove compartment programs across shared EV architectures. |
| Backward Integration into Tooling | Captures mold design expertise required for ECE R21 head-impact certification timelines. |
| Software-Defined Vehicle Investment | Enables over-the-air updates for electronic latch authentication and climate control algorithms. |
| Geographic Manufacturing Footprint | Positions suppliers within 500km of Stuttgart, Detroit, and Shanghai engineering centers. |
| Battery Supply Agreement | Secures thermal management system integration access for heated and insulated variant development. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and ECHA substance restriction updates. Bottom-up segment builds and top-down market sizing were cross-referenced for convergence.
Segment-weighting applied vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the projection horizon. CAGRs were derived from fitted growth curves against historical shipment data and OEM platform launch schedules. Forecast inputs incorporated battery electric vehicle penetration assumptions and instrument panel thermal budget reallocations.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook for heated glove compartment specifications. Forecasts reflect documented assumptions on REACH compliance timelines and ECE R21 certification cycle stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market