
 Automotive Smart Window Market | 2026-2036
Automotive Smart Window Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Window Market Analysis
Software-defined tint calibration delivered through over-the-air subscription tiers is pivoting how automakers monetize glazing systems. Gentex Corporation leverages its mirror-technology heritage to anchor electrochromic roof programs with Detroit-based OEMs. Saint-Gobain competes through vertical integration from float-glass production to coated smart substrates. Fuyao Glass Industry Group dominates replacement-channel supply through manufacturing scale and cost-optimized suspended-particle device output.
Automotive smart windows incorporate electroactive thin-film stacks—typically tungsten oxide cathodes paired with nickel oxide anodes separated by solid polymer electrolytes—that modulate visible and infrared transmission in response to electrical stimulus, primarily to reduce HVAC load and enhance occupant comfort. Electrochromic technology leads in value terms due to proven automotive durability and OEM qualification cycles, while suspended-particle devices occupy faster-growing retrofit and aftermarket channels where installation simplicity outweighs longevity premiums. Energy Management technology differentiates emerging platforms by integrating photovoltaic generation with tint-state logic, creating margin pools for suppliers who control both sensor hardware and control algorithms.
Federal Motor Vehicle Safety Standard 205 governs light-transmission minimums in the United States, constraining maximum tint states while NHTSA evaluates updated protocols for dynamic glazing. The EU Green Deal and CE marking requirements under the F-Gas Regulation are phasing down high-global-warming-potential blowing agents in insulating glass units, redirecting R&D toward vacuum-insulated and aerogel-interlayer alternatives. Stakeholders must monitor how EPA fuel-economy credit calculations treat smart-window HVAC savings versus the cost burden of dual-source power architectures in electric vehicle platforms.
Market Dynamics
Electrochromic roof installations are accelerating as luxury OEMs pursue factory-fit differentiation, while the EU Green Deal's cabin energy-efficiency mandates force material substitutions across glazing supply chains. This dual pressure from premium demand pull and regulatory compliance push is restructuring supplier-OEM relationships and investment priorities.
Growth Catalysts
- EU Green Deal cabin mandates:Energy-efficiency requirements for vehicle interiors are accelerating adoption of thermochromic and electrochromic alternatives to conventional tinted glass across European OEM platforms.
- Shanghai-Shenzhen EV corridor:China's electric vehicle manufacturing concentration generates concentrated demand for smart glazing systems that reduce HVAC load and extend battery range.
- Electroactive thin-film advances:Solid polymer electrolyte improvements are extending automotive durability cycles and qualifying new suppliers for OEM electrochromic programs.
Market Restraints
- Tungsten oxide supply concentration:Cathode material processing capacity clusters in East Asian refineries, exposing electrochromic stack producers to input volatility and geographic risk.
- Federal Motor Vehicle Safety Standard 205:NHTSA light-transmission minimums constrain maximum tint states and limit dynamic glazing performance in the US market.
- Dual-source power architectures:Electric vehicle platforms require redundant electrical systems for smart window operation, adding cost burden that compresses supplier margins.
Strategic Opportunities
- Photovoltaic-tint integration:Energy Management platforms combining PV generation with tint-state logic create new margin pools for suppliers controlling sensor hardware and algorithms.
- Aftermarket retrofit channels:Suspended-particle devices with simplified installation protocols are penetrating replacement markets where longevity premiums matter less than upfront cost.
- F-Gas Regulation phase-down:EU restrictions on high-global-warming-potential blowing agents are redirecting R&D toward vacuum-insulated and aerogel-interlayer alternatives for insulating glass units.
Industry Challenges
- OEM qualification timelines:Electrochromic durability testing cycles extend 24-36 months, compressing supplier cash conversion and limiting technology refresh rates.
- Control algorithm IP fragmentation:Proprietary tint-state logic and over-the-air calibration systems are generating licensing disputes between mirror-heritage suppliers and independent glass manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Window Market |
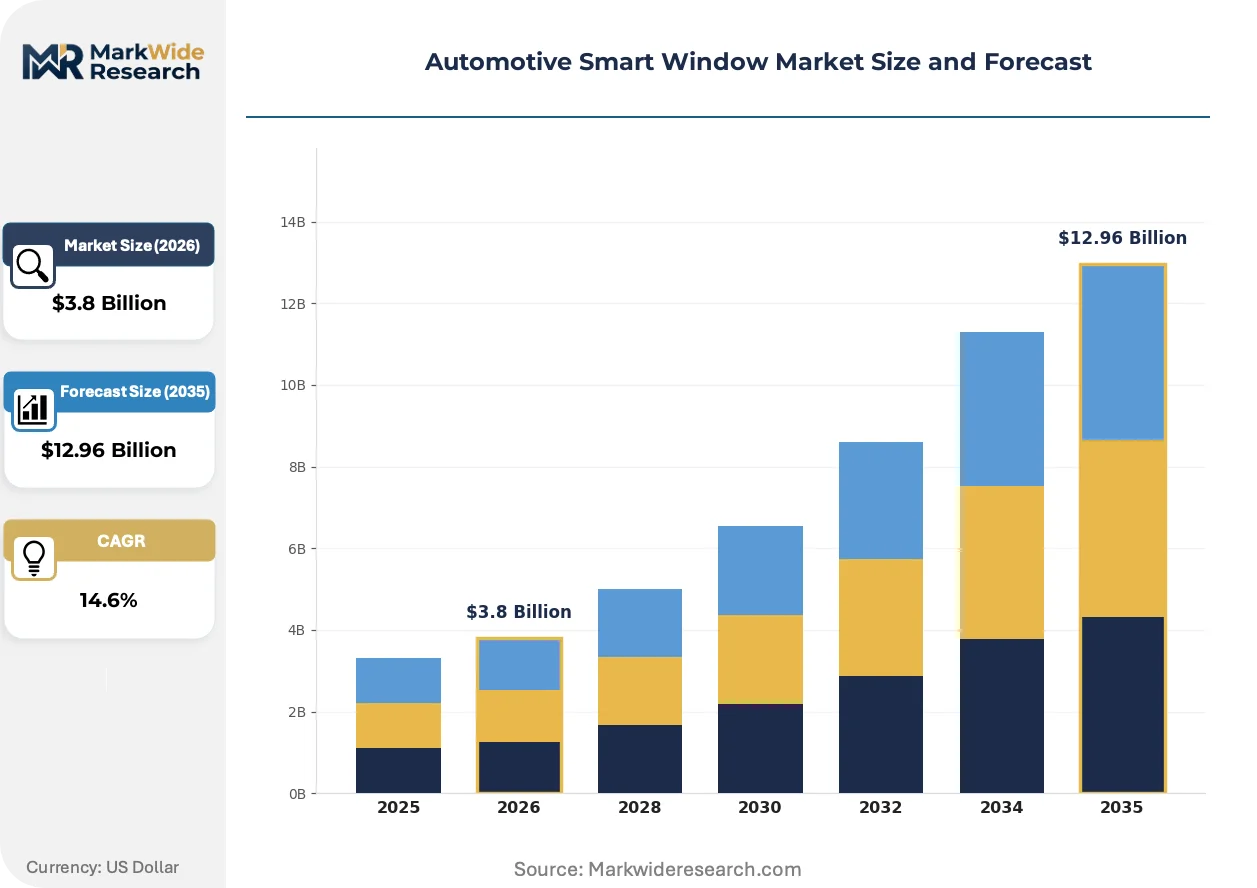
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic, Photochromic, Thermochromic, Suspended Particle Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Electric Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Technology: Smart Tinting, Automatic Control, Adaptive Glazing, Energy Management |
| Companies Covered | Saint-Gobain, Gentex Corporation, AGC Inc., Nippon Sheet Glass Company Limited, Corning Incorporated, Fuyao Glass Industry Group, Magna International, Merck KGAA, Research Frontiers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Window Market Emerging Trajectories
Software-defined functionality is displacing hardware-centric value capture in automotive glazing, with subscription monetization models and integrated energy management systems redefining supplier competitiveness.
Photovoltaic-integrated smart glass is converging with electrochromic tint-state logic to create self-powered cabin climate control systems. Tier 1 suppliers are embedding silicon thin-film cells directly into roof glazing substrates. This convergence is compressing the traditional separation between glazing and solar suppliers into unified energy-management platform competitions.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in insulating glass units, forcing manufacturers toward vacuum-insulated panel and aerogel interlayer technologies. Glass processors must requalify thermal performance certifications under new test protocols. European OEMs are responding by consolidating supplier panels to those with certified low-GWP material chains.
Fleet procurement of smart glazing is unbundling hardware from calibration services, with commercial vehicle operators demanding outcome-based HVAC load reduction contracts rather than component purchases. Leasing companies are absorbing upfront glazing premiums in exchange for guaranteed energy savings. This shift is most visible in Germany's corporate fleet channel, where total-cost-of-ownership transparency drives specification decisions.
Automotive Smart Window Market Segmentation
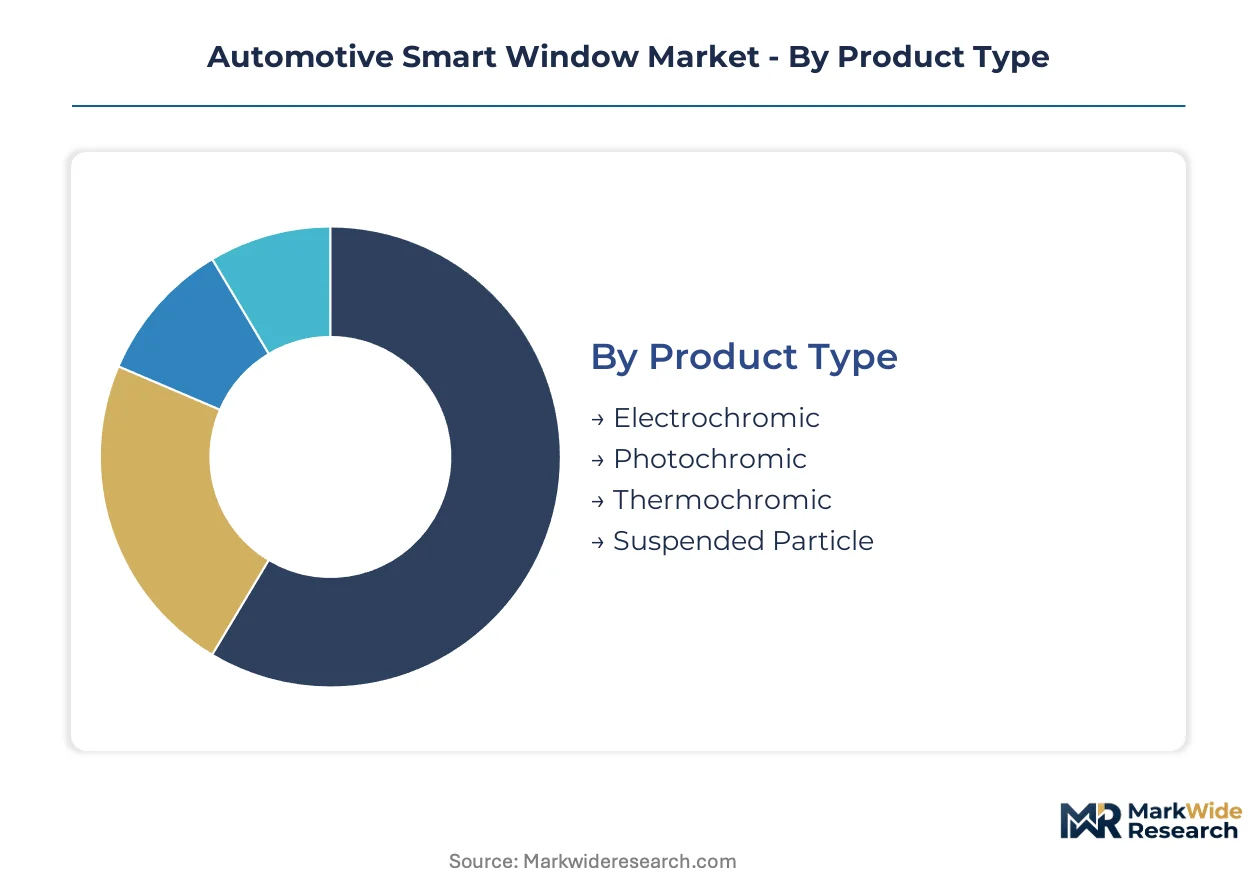
Technology-material pairings and installation-channel economics create divergent margin profiles across the automotive smart window market. Segmentation reveals how electrochromic durability premiums command factory-fit positions while suspended-particle simplicity unlocks aftermarket volume.
Product Type:
Thin-film electroactive stacks differentiate on cathode-anode chemistry and electrolyte stability, separating premium OEM qualification from retrofit accessibility.
- Electrochromic:Tungsten oxide cathodes paired with nickel oxide anodes through solid polymer electrolytes modulate infrared and visible transmission with proven automotive durability cycles. Demand concentrates with luxury German and US automakers pursuing factory-fit roof differentiation, constrained by 24-36 month OEM qualification timelines that compress supplier cash conversion.
- Suspended Particle:Polymer-dispersed liquid crystal films with simplified wiring architectures enable faster installation without vacuum-sealed assembly requirements. Aftermarket channels in China's replacement market absorb the bulk of volume, where Fuyao Glass cost-optimized output outweighs longevity premiums for vehicle owners.
- Photochromic:Silver halide microcrystals embedded in glass substrates respond to ultraviolet intensity without electrical control systems.
- Thermochromic:Vanadium dioxide phase-change coatings transition at specific temperature thresholds, qualifying under EU Green Deal cabin efficiency mandates for passive thermal management.
Mature deployment sits with electrochromic technology in premium factory-fit programs. Newer deployment is concentrated in suspended-particle retrofit channels.
Application:
Vehicle-class specifications diverge on thermal-load reduction priorities and electrical architecture redundancy requirements.
- Luxury Cars:Electrochromic roof installations anchor competitive positioning for German marques, with Gentex Corporation programs supplying Detroit-based OEMs through multi-year platform commitments.
- Electric Vehicles:Dual-source power architectures for smart window operation add cost burden that compresses supplier margins, though HVAC load reduction extends battery range for Shanghai-Shenzhen corridor manufacturers.
- Passenger Vehicles:Mid-range segment adoption depends on module cost reduction through scaled polymer electrolyte production.
- Commercial Vehicles:Fleet procurement unbundles hardware from calibration services, with German corporate leasing companies absorbing upfront premiums for guaranteed energy savings contracts.
Volume concentration tracks with electric vehicle manufacturing expansion. Margin expansion is steepest in luxury factory-fit specifications.
End User:
Channel economics separate component-margin capture from outcome-based service monetization.
- OEMs:Direct supplier relationships with electrochromic stack producers require certified automotive durability testing and multi-year platform integration cycles.
- Fleet Operators:Commercial vehicle demand centers on HVAC load reduction guarantees rather than hardware purchases, restructuring supplier revenue toward performance contracts.
- Aftermarket Providers:Suspended-particle device distribution through replacement channels emphasizes installation speed over longevity certification.
- Individual Consumers:Retail demand responds to software-defined tint calibration subscriptions delivered through over-the-air updates.
Procurement authority is consolidating with fleet operators. Pricing power is fragmenting across individual consumer subscription tiers.
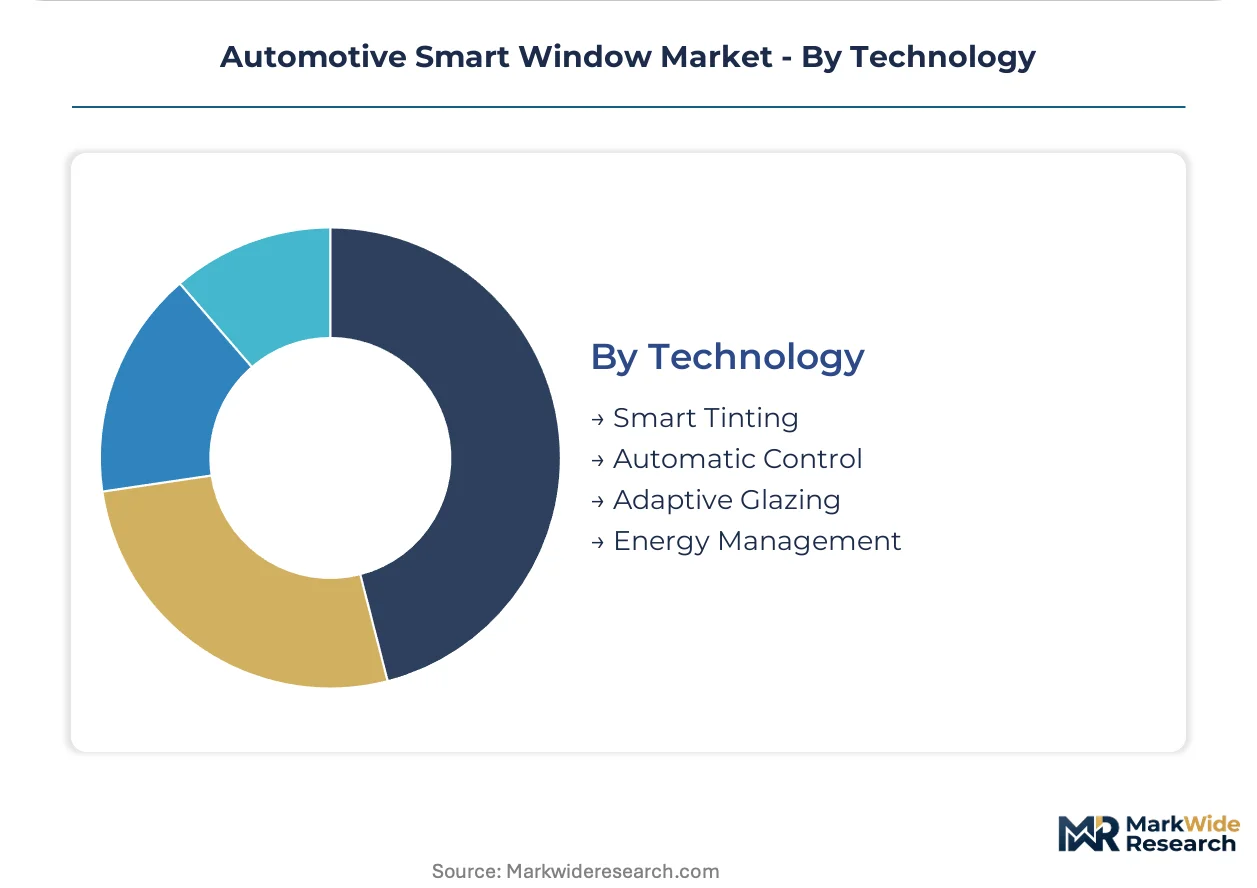
Technology:
Control-system integration separates hardware-centric value capture from algorithm-driven recurring revenue.
- Energy Management:Photovoltaic-tint convergence embeds silicon thin-film cells directly into roof substrates, compressing traditional separations between glazing and solar suppliers into unified platform competitions.
- Smart Tinting:Electroactive film stacks with manual or automated control interfaces dominate current OEM specifications through proven reliability data.
- Automatic Control:Sensor-integrated tint-state logic responds to ambient light and cabin temperature without occupant intervention.
- Adaptive Glazing:Multi-zone tint calibration enables differential opacity across vehicle glazing surfaces.
Revenue model innovation is concentrated in energy management platforms. Hardware-only deployment persists in basic smart tinting specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of automotive smart window substrates while Germany and the United States consume premium electrochromic systems for luxury vehicle programs. This production-consumption divide shapes supplier location decisions and qualification strategies across major markets.
China
Shanghai and Shenzhen anchor electric vehicle manufacturing corridors generating concentrated demand for HVAC-reducing glazing systems. MIIT dual carbon goals accelerate cabin energy-efficiency specifications in domestic EV platforms. Yangtze River Delta glass processors scale suspended-particle device output for cost-optimized aftermarket channels.
Germany
Luxury OEMs in Bavaria and Baden-Württemberg expand factory-fit electrochromic roof installations as competitive differentiators. EU Green Deal cabin mandates under F-Gas Regulation phase-down requirements redirect supplier R&D toward vacuum-insulated alternatives. Corporate fleet operators in North Rhine-Westphalia absorb upfront glazing premiums through guaranteed energy savings contracts.
United States
Detroit-based OEMs anchor electrochromic roof programs through multi-year platform commitments with heritage mirror-technology suppliers. NHTSA Federal Motor Vehicle Safety Standard 205 constrains maximum tint states and limits dynamic glazing performance. Southeast manufacturing corridors test dual-source power architectures for electric vehicle smart window integration.
Japan
Automotive glass fabricators in Kansai and Chubu regions supply electroactive thin-film stacks to regional OEM qualification programs. METI energy-efficiency guidelines for vehicle interiors support thermochromic coating adoption. Kyushu-based processors develop solid polymer electrolyte improvements for extended automotive durability cycles.
South Korea
Seoul Capital Area battery-electric vehicle manufacturers specify smart glazing systems to extend driving range through reduced HVAC load. Domestic suppliers integrate sensor-embedded tint-state logic with automated cabin climate control. Busan-Ulsan industrial complexes host float-glass production feeding coated smart substrate fabrication.
Automotive Smart Window Market Vendor Landscape
Top-tier vendors anchor factory-fit electrochromic programs with luxury OEMs, while mid-scale fabricators compete through cost-optimized suspended-particle output for aftermarket channels. The vendor base separates into three strategic archetypes: mirror-heritage electrochromic specialists, vertically integrated float-glass producers, and polymer-dispersed liquid crystal device manufacturers. Competitive moves concentrate on backward integration into cathode material processing and technology licensing arrangements for control algorithm IP.
Among heritage automotive suppliers, Gentex Corporation and Saint-Gobain occupy positions reflecting distinct strategic orientations. Gentex exemplifies the mirror-technology lineage pivoting toward electrochromic roof systems through Detroit OEM relationships. Saint-Gobain represents upstream integration from float-glass production through coated substrate fabrication. Fuyao Glass Industry Group anchors the scale-driven tier serving replacement channels where manufacturing volume outweighs longevity premiums.
| Leading Market Players |
|---|
| Saint-Gobain |
| Gentex Corporation |
| AGC Inc. |
| Nippon Sheet Glass Company Limited |
| Corning Incorporated |
| Fuyao Glass Industry Group |
| Magna International |
| Merck KGAA |
| Research Frontiers |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's cabin energy-efficiency mandates gate qualified supply and premium-tier pricing access for electrochromic roof programs, forcing OEMs to absorb certification premiums while aftermarket channels compete on suspended-particle device cost. This regulatory filter concentrates margin capture with certified suppliers who control cathode material processing and solid polymer electrolyte fabrication.
Pricing Analysis
Margin tightening in factory-fit electrochromic tiers reflects 24-36 month OEM qualification cycles that compress supplier cash conversion. Three-tier pricing structure across premium, standard, and economy levels separates Gentex-Saint-Gobain certified programs from Fuyao aftermarket volume and uncertified retrofit imports. Price differentiation hinges on automotive durability certification and cathode-anode chemistry grade. Fleet operators in Germany absorb upfront premiums through guaranteed energy savings contracts, while China's replacement-channel buyers prioritize installation speed over longevity.
Supply Chain Analysis
Refurbishment flows for electrochromic roof modules remain underdeveloped, creating stranded value in luxury vehicle end-of-life channels. Tungsten oxide cathode processing concentrates in Chinese and South Korean refineries, with nickel oxide anode supply anchored in Japanese and German specialty chemical plants. Solid polymer electrolyte production draws from Merck KGAA and regional Asian compounders. Single-source vulnerability in tungsten oxide exposes stack producers to input volatility. Distribution runs through Tier 1 supplier direct contracts with OEM platform engineers and aftermarket channels via Fuyao's replacement network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where cathode material processing and control algorithm IP determine who captures recurring revenue from software-defined tint calibration.
For Market Incumbents: Deepen backward integration into tungsten oxide refining to offset East Asian supply concentration, while securing multi-year platform commitments with Detroit-based OEMs before suspended-particle retrofit channels erode factory-fit attach rates. Mirror-heritage suppliers must defend algorithm licensing revenue against independent glass manufacturers developing proprietary tint-state logic. For New Entrants and Emerging Players: Launch via outcome-based HVAC load reduction contracts with German corporate fleet operators, where total-cost-of-ownership transparency outweighs component branding. The most penetrable white-space sits in thermochromic vanadium dioxide coatings for EU Green Deal passive thermal management compliance, bypassing electrochromic qualification timelines entirely. For Investors and Strategic Acquirers: Photovoltaic-tint integration announcements from Tier 1 suppliers signal the leading indicator that energy management platforms are compressing traditional glazing-solar supplier boundaries. Long-term viability favors acquirers of solid polymer electrolyte specialists with certified automotive durability data, not hardware-only film fabricators. Watch for MIIT dual carbon goal acceleration in China's EV corridor as the inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive tungsten oxide supply insulates Gentex and Saint-Gobain from East Asian refinery volatility. |
| Photovoltaic-Tint Platform Convergence | Silicon thin-film cell embedding merges glazing and solar supplier competitions into unified energy management. |
| Software-Defined Subscription Tiering | Over-the-air tint calibration monetization shifts value capture from hardware sales to recurring algorithm revenue. |
| F-Gas Regulation R&D Pivot | Vacuum-insulated panel development requalifies thermal performance for EU OEM consolidated supplier panels. |
| Fleet Outcome-Based Contracting | Guaranteed energy savings contracts with German leasing companies restructure supplier revenue toward performance. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and solid polymer electrolyte compounders. Vehicle production databases, NHTSA safety standard dockets, EU F-Gas Regulation compliance registries, and MIIT dual carbon policy announcements formed the documentary backbone. Bottom-up volume modeling across electrochromic, suspended-particle, and thermochromic technology tiers triangulated against top-down OEM platform commitment aggregation.
Data-stream reconciliation across factory-fit installation tracking, aftermarket channel shipment records, and cathode material trade flows calibrated segment-level growth trajectories over the projection horizon. Segmentation dimensions modeled included vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from technology adoption curve analysis weighted by qualification timeline constraints and regulatory mandate enforcement schedules. Photovoltaic integration attach rates and subscription monetization penetration served as automotive-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for thermochromic passive coatings displacing electrochromic active systems would alter the outlook. Forecasts reflect assumptions about EU Green Deal enforcement timing, NHTSA dynamic glazing protocol updates, and tungsten oxide supply chain stability. Practitioners should monitor MIIT policy acceleration, F-Gas Regulation phase-down compliance deadlines, and OEM dual-source power architecture standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market