
 Russia Automotive Adaptive Lighting System Market | 2026-2036
Russia Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Adaptive Lighting System Market Analytics
Fleet operators are unwinding their historical preference for static halogen headlamps and migrating toward adaptive LED configurations. HELLA KGaA Hueck & Co leverages its European engineering heritage to anchor premium OEM supply relationships in Russia. Valeo Group competes through localized production capabilities that reduce import dependency for Russian automakers. Koito Manufacturing Co Ltd specializes in matrix lighting modules that address the country's severe winter visibility challenges.
Russia Automotive Adaptive Lighting Systems comprise electronically controlled headlamp assemblies that modulate beam pattern, intensity, and direction in response to vehicle speed, steering angle, and ambient conditions, typically employing LED or laser sources with sensor fusion architectures. These systems primarily enhance driver safety during low-visibility operations on poorly maintained rural roads and urban corridors with erratic street illumination. LED technology leads installed volume due to cost efficiency and TR CU compliance ease, while matrix lighting captures margin concentration as domestic OEMs seek differentiation in the premium segment. Halogen retains residual share in aftermarket channels serving older vehicle parc, though xenon faces displacement from laser alternatives in flagship platforms.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) administers TR CU 018/2011 harmonization with UNECE Regulations 48 and 123, which govern adaptive front lighting system homologation and electromagnetic compatibility. The Ministry of Industry and Trade enforces localization requirements that pressure foreign suppliers to establish joint ventures or contract manufacturing within the Eurasian Economic Union. Stakeholders must monitor Rosstandart's anticipated alignment with revised UNECE protocols and assess whether domestic semiconductor sourcing constraints will force architectural simplification in next-generation controller designs.
Market Dynamics
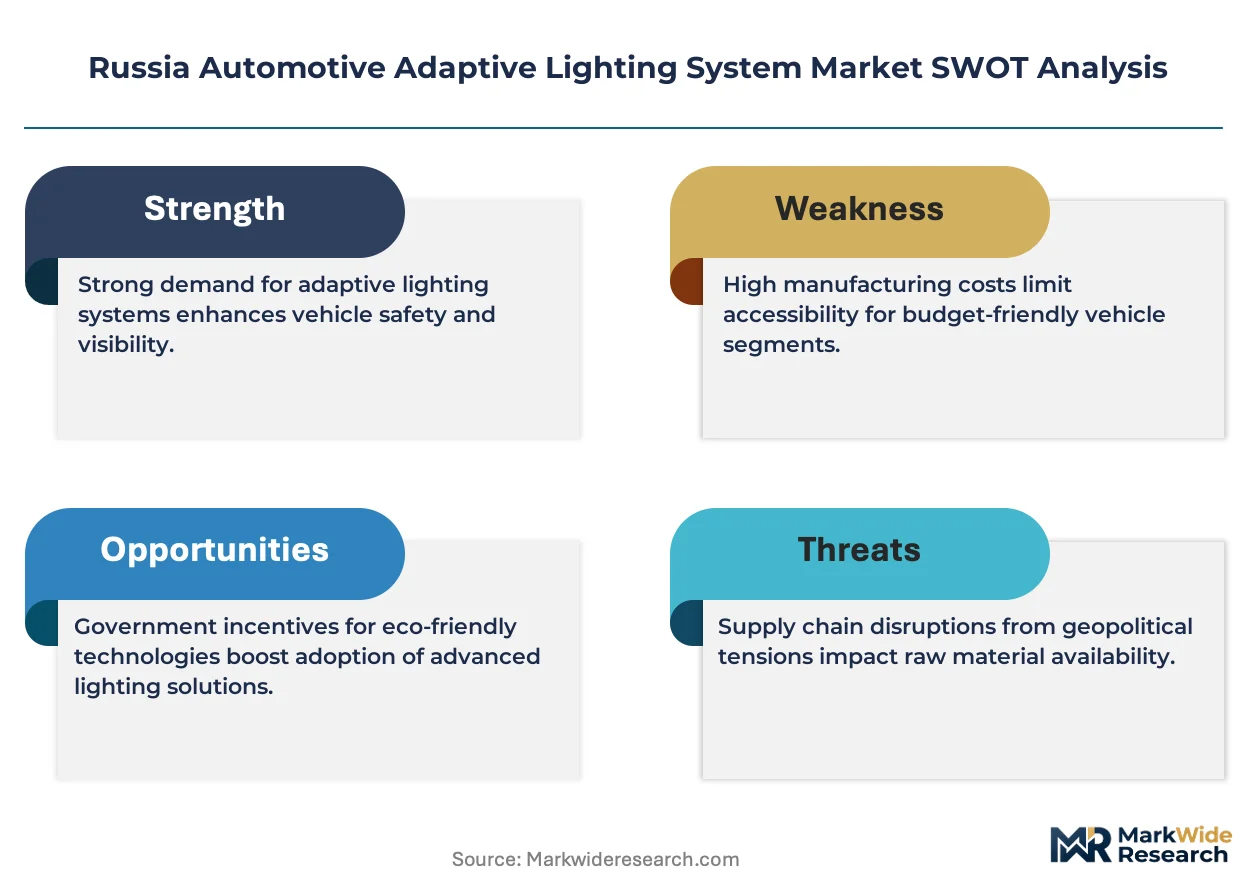
Matrix LED architectures are compressing module margins while forcing controller suppliers to consolidate software stacks around unified sensor fusion platforms. Rosstandart's phased alignment with UNECE R123 revisions is accelerating homologation costs for Tier-2 module integrators.
Growth Catalysts
- TR CU 018/2011 Harmonization:Russia's technical regulation mandates adaptive beam performance thresholds that legacy halogen systems cannot satisfy, compelling fleet-wide LED retrofits in commercial vehicle segments.
- Moscow-Central Federal District Premium Clustering:Concentrated luxury vehicle sales in this corridor create predictable demand pull for matrix lighting configurations with dynamic cornering capabilities.
- Laser Diode Maturation:Improved thermal management in laser sources enables longer-throw illumination suited to Siberian and Far Eastern Federal Districts with sparse street lighting infrastructure.
Market Restraints
- Controller Semiconductor Import Dependency:Sourcing constraints for automotive-grade microcontrollers from Asian foundries force architectural simplification in adaptive driving beam logic.
- Homologation Cost Concentration:Eurasian Economic Union certification requirements concentrate testing expenditure among Moscow-based validation laboratories, excluding regional suppliers.
- Xenon Aftermarket Substitute Persistence:Lower-cost HID retrofit kits retain residual share in older vehicle parc maintenance, delaying full LED transition in price-sensitive segments.
Strategic Opportunities
- Volga Federal District Fleet Penetration:Underpenetrated commercial logistics corridors in Nizhny Novgorod and Kazan present whitespace for adaptive LED standardization in heavy truck configurations.
- Sensor-LiDAR Convergence:Integration of adaptive lighting controllers with emerging autonomous perception stacks creates bundled architecture opportunities for next-generation premium platforms.
- EAEU Localization Incentives:Ministry of Industry and Trade contract manufacturing requirements favor joint venture structures that reduce import duty exposure for foreign module suppliers.
Industry Challenges
- Embedded Software Talent Scarcity:Shortage of automotive lighting firmware engineers with UNECE R48 compliance experience delays controller development cycles for domestic Tier-2 suppliers.
- Legacy CAN Bus Integration Friction:Adaptive module retrofits into pre-2018 vehicle architectures require protocol bridge hardware that complicates warranty liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Adaptive Lighting System Market |
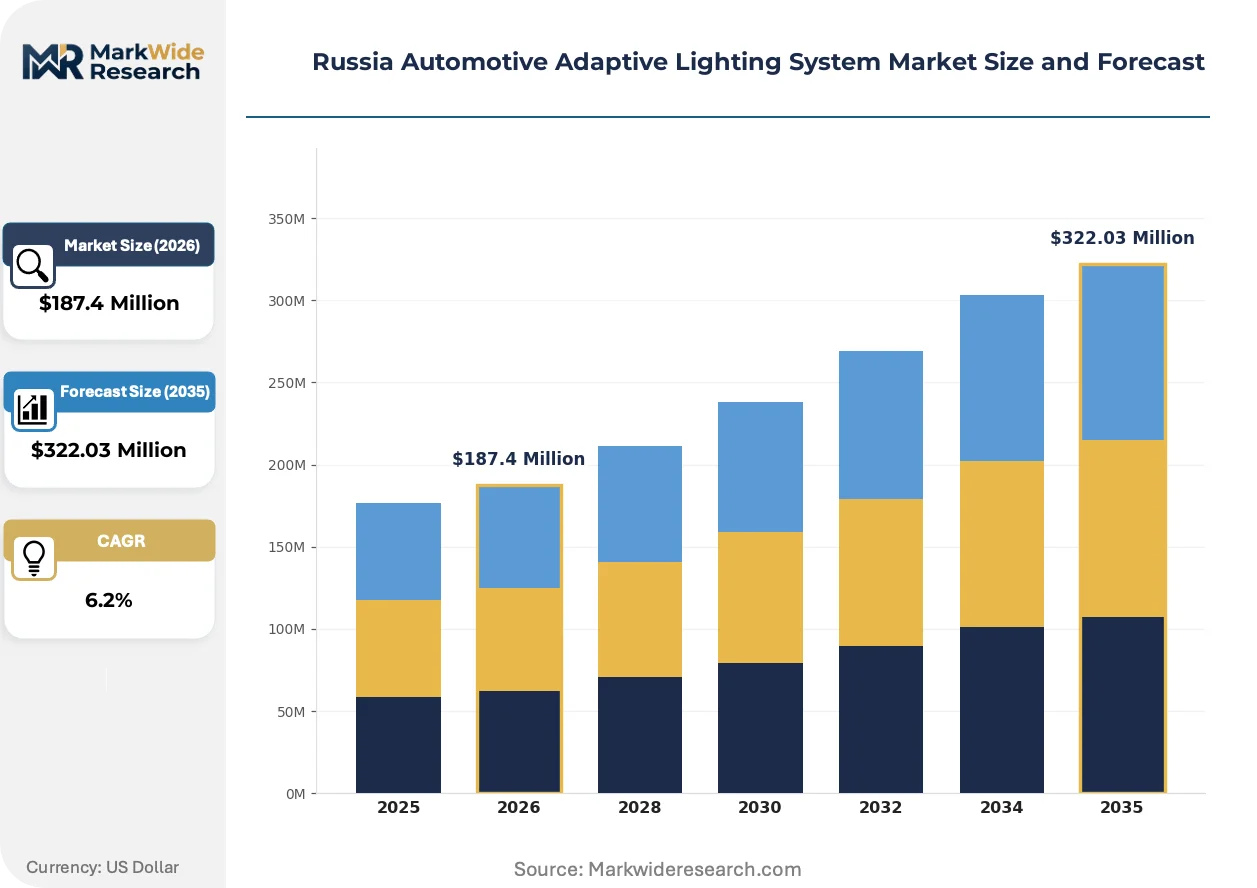
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $322.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hue Adjustment, Beam Steering, Dynamic Cornering, Matrix Lighting Technology: LED, Laser, Halogen, Xenon Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Light Trucks End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators |
| Companies Covered | Stanley Electric Co Ltd, Hyundai Mobis, HELLA KGaA Hueck & Co, Koninklijke Philips N.V., Magneti Marelli SpA, Valeo Group, Osram, Texas Instruments, Koito Manufacturing Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Adaptive Lighting System Market Evolving Landscape
Digital light processing is redrawing competitive boundaries between lamp integrators and semiconductor suppliers. Three distinct vectors are compressing traditional value capture models.
Matrix LED technology is fragmenting the supplier landscape by decoupling optical design from electronic control. Domestic OEMs in the premium passenger segment are adopting pixel-level beam modulation faster than anticipated. This acceleration is fragmenting procurement relationships as automakers source controllers separately from lens assemblies.
Rosstandart's anticipated adoption of revised UNECE R123 protocols will tighten electromagnetic compatibility testing for adaptive front lighting systems. The regulation will force controller suppliers to redesign shielding architectures. Premium segment manufacturers with existing EAEU validation infrastructure are pre-positioning compliance documentation.
Fleet procurement is consolidating around total-cost-of-ownership metrics that weight energy efficiency against maintenance intervals. Commercial vehicle operators in the Central Federal District are unbundling lighting system sourcing from full-vehicle contracts. This behavioral shift is most visible in Moscow-based logistics companies operating 24-hour distribution networks.
Russia Automotive Adaptive Lighting System Market Segmentation
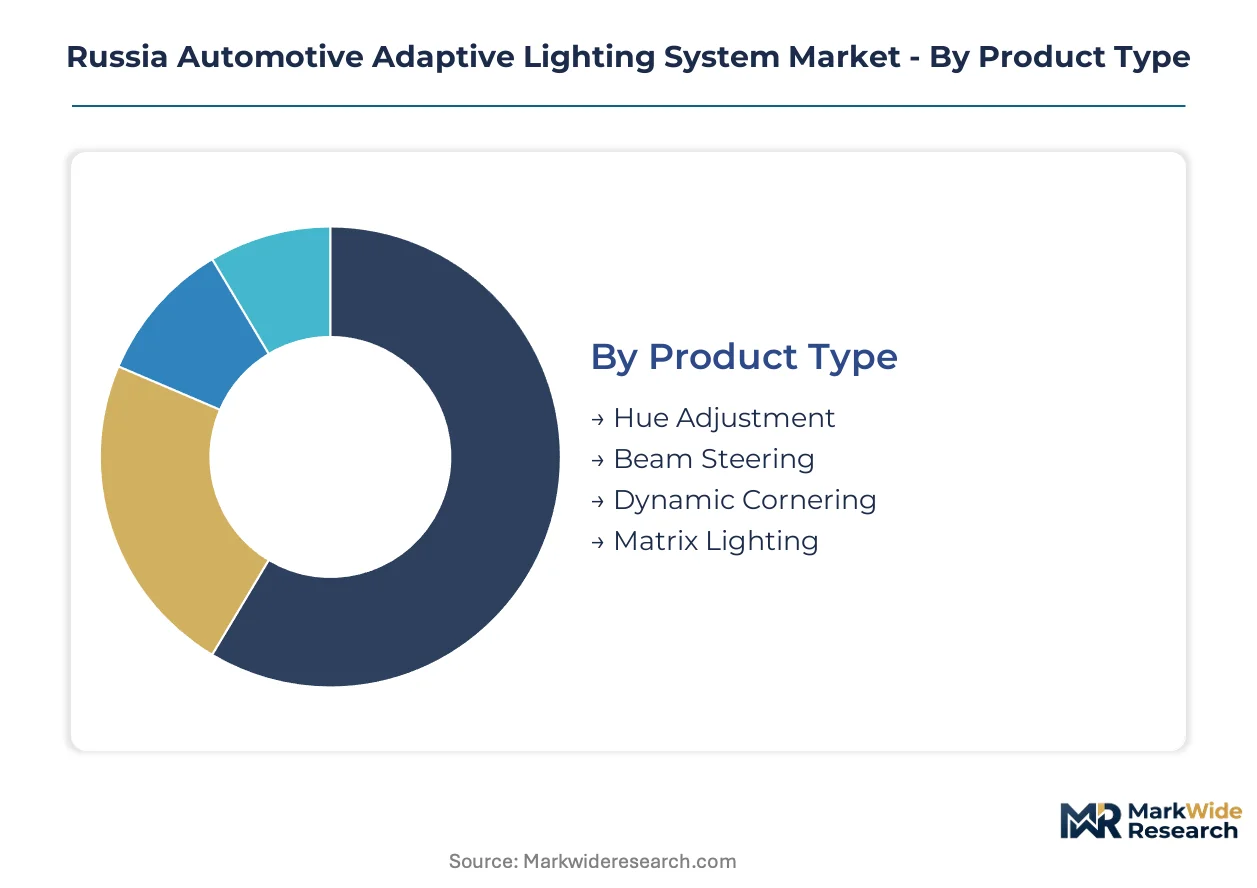
Adaptive lighting procurement patterns diverge sharply between domestic OEM integration programs and aftermarket retrofit channels serving Russia's aging vehicle parc. Segment boundaries reflect this bifurcation, with technology choices tracking regulatory compliance timelines versus cost-driven replacement cycles.
Product Type:
Domestic OEM supply concentrates in electronically sophisticated modules that satisfy TR CU 018/2011 homologation, while aftermarket demand gravitates toward simpler retrofit solutions for legacy platforms.
- Matrix Lighting:Pixel-level beam modulation enables selective masking of oncoming vehicles without full high-beam deactivation. Moscow-based premium OEMs specify these modules for flagship sedans targeting the Central Federal District's concentrated luxury demand.
- Dynamic Cornering:Steering-angle-responsive horizontal beam pivoting addresses visibility gaps on poorly maintained rural roadways. Nizhny Novgorod and Kazan fleet operators in the Volga Federal District are standardizing these modules for heavy truck configurations.
- Beam Steering:Electronically controlled vertical and horizontal adjustment for load compensation and grade changes.
- Hue Adjustment:Color temperature modulation for varying weather conditions and tunnel transitions.
Matrix lighting commands the established base. The steepest expansion runs through dynamic cornering modules.
Technology:
Cost tier stratification separates premium laser deployments from volume LED standardization, with residual halogen serving price-sensitive aftermarket maintenance.
- LED:Solid-state illumination with instant response and simplified thermal management satisfies TR CU compliance at lowest total system cost. Domestic OEMs specify LED architectures across mid-premium passenger vehicle lines.
- Laser:Coherent light sources achieve 600-meter throw distances with reduced power draw. Siberian and Far Eastern Federal District commercial operators specify laser modules for routes with sparse street lighting infrastructure.
- Halogen:Tungsten-halogen retains residual share in aftermarket channels serving pre-2015 vehicle parc.
- Xenon:High-intensity discharge faces displacement from laser alternatives in flagship platforms.
LED architectures anchor volume deployment. Laser sources are climbing the fastest in premium commercial applications.
Application:
Customer type divergence separates fleet procurement standardization from individual owner upgrade patterns across vehicle categories.
- Passenger Vehicles:Premium sedans and SUVs in Moscow's luxury cluster drive matrix module specification. Domestic OEMs bundle adaptive lighting in trim packages targeting the Central Federal District.
- Commercial Vehicles:Heavy trucks and long-haul tractors in 24-hour distribution networks require durable adaptive configurations. Fleet operators unbundle lighting sourcing from full-vehicle contracts.
- Light Trucks:Mid-duty logistics vehicles in regional corridors.
- Motorcycles:Two-wheel adaptive systems remain nascent in Russian homologation frameworks.
Passenger vehicles retain volume concentration. Commercial vehicle retrofits are gaining share fastest in underpenetrated corridors.
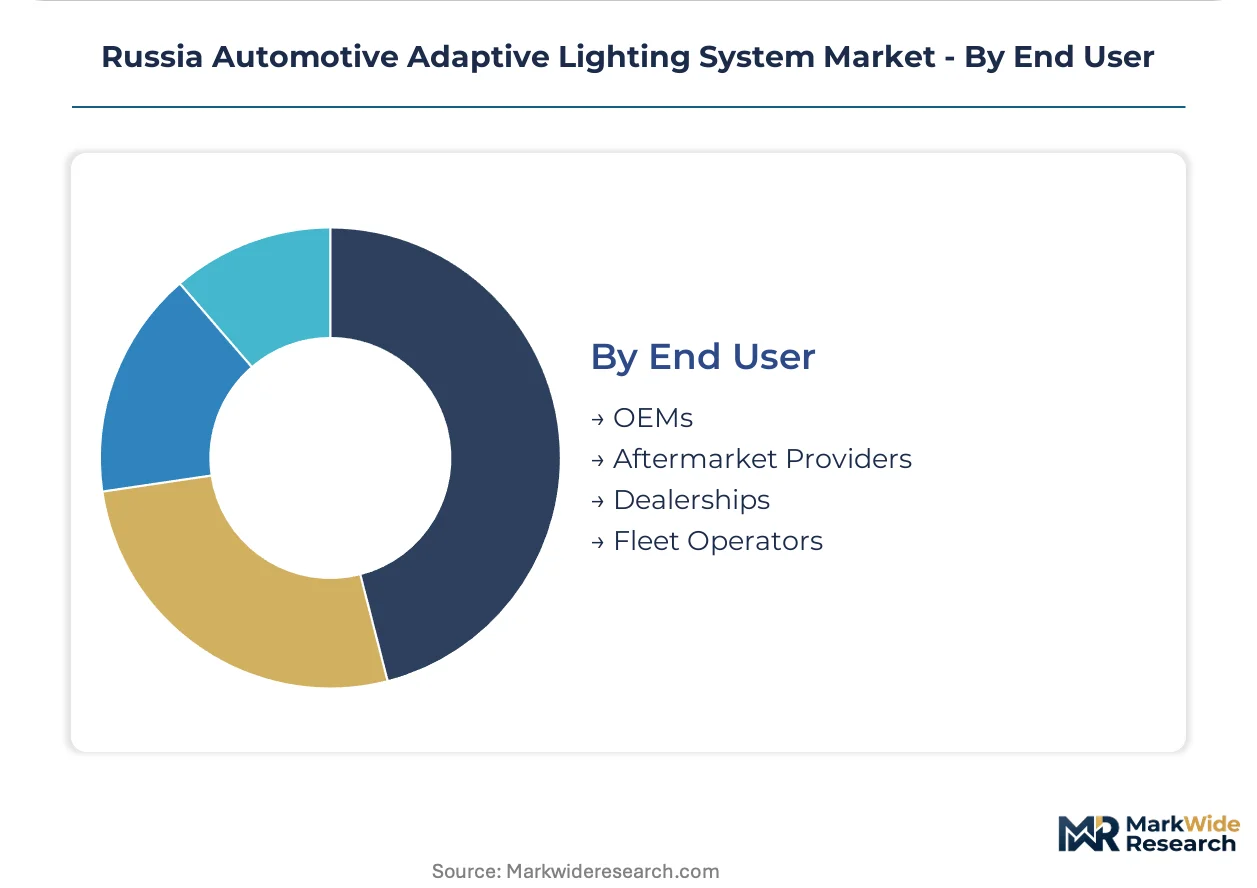
End User:
Supply concentration shapes procurement access, with EAEU localization requirements favoring joint venture structures over direct import relationships.
- OEMs:Domestic premium vehicle manufacturers specify adaptive modules at platform design stage. Ministry of Industry and Trade localization mandates pressure foreign suppliers toward contract manufacturing within the Eurasian Economic Union.
- Fleet Operators:Commercial logistics companies operating Moscow-based distribution networks consolidate procurement around total-cost-of-ownership metrics weighting energy efficiency against maintenance intervals.
- Aftermarket Providers:Independent retrofit specialists serve older vehicle parc with simplified controller architectures.
- Dealerships:Authorized service channels handle warranty-compliant module replacement.
OEM integration commands technology leadership. Fleet operator direct procurement is expanding most quickly as unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Siberian Railway and Baikal-Amur Mainline anchor Russia's east-west logistics spine, concentrating automotive component distribution through corridor cities that link European manufacturing zones to Pacific port access.
Central Federal District
Moscow's luxury vehicle cluster drives matrix lighting specification for premium sedans and SUVs. Rosstandart administers TR CU 018/2011 homologation through Moscow-based validation laboratories, concentrating certification costs in the capital. The Moscow-Nizhny Novgorod industrial corridor hosts domestic OEM assembly plants standardizing adaptive LED configurations.
Volga Federal District
Nizhny Novgorod and Kazan anchor heavy truck manufacturing for 24-hour distribution networks requiring durable adaptive lighting. Fleet operators in this corridor unbundle lighting procurement from full-vehicle contracts, creating direct supplier relationships. The region's logistics density favors dynamic cornering modules for poorly maintained rural roadways.
Siberian Federal District
Novosibirsk serves as the rail hub for component distribution to Far Eastern markets. Sparse street lighting infrastructure across Siberian corridors drives laser diode specification for extended throw distances. The Ministry of Industry and Trade localization incentives pressure foreign suppliers toward joint ventures with regional fabricators.
Far Eastern Federal District
Vladivostok's Pacific port handles import flows for Asian-sourced semiconductor controllers. Severe winter visibility challenges and limited grid infrastructure favor energy-efficient LED architectures with simplified thermal management. Regional fleet operators prioritize maintenance interval optimization over upfront module cost.
Northwestern Federal District
St. Petersburg's Baltic port facilities support European supplier logistics for HELLA and Valeo distribution networks. The city's automotive engineering base supplies firmware talent for adaptive driving beam controller development. Northwestern clusters face compressed margins from matrix LED procurement fragmentation.
Russia Automotive Adaptive Lighting System Market Competitive Landscape
Concentration sits with diversified automotive electronics conglomerates and specialized lighting module fabricators. The supplier base organizes around three archetypes: European engineering heritage firms, Asian volume manufacturers with localized production, and semiconductor controller specialists. Competitive dynamics center on EAEU joint venture formation and sensor fusion software stack consolidation.
Within the European heritage tier, HELLA KGaA Hueck & Co and Valeo Group exemplify suppliers leveraging established OEM relationships to anchor premium platform specification. Koito Manufacturing Co Ltd represents the Asian specialist archetype, occupying a position focused on matrix module engineering for severe climate applications. These three names illustrate how geographic origin and technical specialization stratify competitive positioning across Russia's adaptive lighting procurement channels.
| Leading Market Players |
|---|
| Stanley Electric Co Ltd |
| Hyundai Mobis |
| HELLA KGaA Hueck & Co |
| Koninklijke Philips N.V. |
| Magneti Marelli SpA |
| Valeo Group |
| Osram |
| Texas Instruments |
| Koito Manufacturing Co Ltd |
| Others |
Value Network & Pricing Analysis
Capacity utilization at EAEU-based controller assembly plants shapes both supply concentration and price floors for adaptive lighting modules. Domestic OEM procurement contracts leverage scale thresholds to compress per-unit costs, while semiconductor sourcing constraints from Asian foundries prevent downward price mobility in the controller tier.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from individual aftermarket purchases. Three-tier pricing stratifies across matrix LED configurations, dynamic cornering modules, and basic adaptive LED retrofits, with certification grade under TR CU 018/2011 as the primary differentiation driver. Cost compression in the controller tier is intensifying because of microcontroller import dependency, though Moscow-based premium OEMs show minimal price sensitivity compared to Volga Federal District fleet operators.
Supply Chain Analysis
Inbound logistics costs through Vladivostok's Pacific port and St. Petersburg's Baltic corridor fluctuate with container availability on Asia-Europe trade lanes. Controller semiconductor supply concentrates in Taiwan, South Korea, and China, while optical lens assemblies draw from German and Czech fabrication facilities. Single-source vulnerability sits with automotive-grade microcontroller supply from Asian foundries. Distribution runs through Moscow-based validation laboratories and regional OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's automotive adaptive lighting market is emerging from a cyclical trough driven by fleet renewal cycles in commercial logistics corridors. Recovery momentum hinges on Ministry of Industry and Trade localization incentives accelerating EAEU joint venture formation.
For Market Incumbents: Secure EAEU validation infrastructure pre-positioning ahead of Rosstandart's UNECE R123 alignment. Anchor controller software stack consolidation around unified sensor fusion platforms to defend against margin compression from matrix LED procurement fragmentation. Prioritize joint venture structures with domestic Tier-2 suppliers to satisfy localization mandates.
For New Entrants and Emerging Players: TR CU 018/2011 certification fast-tracks through Moscow-based homologation laboratories create entry pathways for regional fleet operators in the Volga Federal District. Target underpenetrated heavy truck configurations in Nizhny Novgorod and Kazan corridors. Lead with dynamic cornering modules that address poorly maintained rural roadway visibility gaps.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controller specialists with embedded software capabilities and existing EAEU compliance documentation. Long-term viability rests on sensor-LiDAR convergence for autonomous platform integration. Watch Rosstandart's UNECE protocol adoption timeline as the inflection signal for homologation cost concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| EAEU Joint Venture Formation | Ministry of Industry and Trade localization mandates reduce import duty exposure for foreign module suppliers. |
| Controller Software Stack Consolidation | Unified sensor fusion platforms address embedded software talent scarcity in UNECE R48 compliance. |
| Matrix LED Controller Sourcing Separation | Domestic OEMs fragment procurement relationships by sourcing controllers separately from lens assemblies. |
| Volga Federal District Fleet Penetration | Nizhny Novgorod and Kazan logistics corridors present whitespace for adaptive LED standardization. |
| Sensor-LiDAR Integration Development | Adaptive lighting controller convergence with autonomous perception stacks creates bundled architecture opportunities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, fleet operations directors, and Rosstandart homologation specialists. Secondary validation drew from vehicle production databases, EAEU customs records, UNECE regulatory filings, and Ministry of Industry and Trade localization policy documents. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
The forecasting boundary spans the projection horizon from baseline market sizing through terminal value estimation. Segmentation dimensions modeled include product type, technology tier, vehicle application, and end-user procurement channel, with additional granularity on regional production cluster alignment. CAGRs were derived from regression analysis of historical adoption curves and regulatory compliance phase-in schedules, incorporating controller semiconductor availability constraints and fleet renewal cycle timing.
Underlying assumptions cover EAEU political stability, continued TR CU 018/2011 enforcement, and microcontroller supply normalization, with deviation risk concentrated in Rosstandart regulatory alignment timing and import substitution policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market