
 Automotive Woven Upholstery Market | 2026-2036
Automotive Woven Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Woven Upholstery Market Insights
Mexico's expanding automotive assembly corridor is reshaping regional sourcing patterns for woven upholstery. Lear Corporation leverages its vertically integrated cut-and-sew operations to supply seat cover programs across Guanajuato and Puebla. Toyota Boshoku anchors its North American woven fabric strategy through dedicated technical textile lines serving hybrid and electric platforms. Adient PLC competes on finishing technology, operating proprietary coating lines that meet OEM flammability specifications without halogenated additives.
Automotive woven upholstery comprises engineered textile fabrics manufactured on looms with specified warp and weft densities, typically ranging from 200 to 800 denier, designed for abrasion resistance exceeding 50,000 Martindale cycles and UV stability for interior automotive applications. The primary purpose is to provide durable, aesthetically controllable surface materials that withstand occupant contact, thermal cycling, and cleaning chemicals while enabling design differentiation across vehicle price tiers. Seat covers dominate value capture within the product type dimension, absorbing disproportionate engineering resources due to direct passenger contact and visibility requirements. Polyester leads the material category by volume, though blend compositions incorporating recycled content are gaining specification share as OEM sustainability targets tighten. OEMs represent the most concentrated end-user channel, with long-term supply agreements locking in multi-year volume commitments that aftermarket suppliers cannot replicate.
EPA standards on volatile organic compound emissions from automotive interior materials directly constrain adhesive and finishing chemistries available to woven upholstery producers. REACH substance restrictions and the EU Green Deal's circular economy requirements are accelerating substitution of virgin petroleum-based fibers with recycled and bio-sourced alternatives in European supply chains. NHTSA flammability protocols under FMVSS 302 maintain baseline safety thresholds that all North American-bound products must satisfy regardless of material innovation. Stakeholders must monitor how diverging regulatory timelines across EPA, REACH, and emerging state-level extended producer responsibility laws will fragment compliance costs and sourcing geography decisions.
Market Dynamics
Luxury electric vehicle OEMs are forcing a recalibration of material specifications across woven upholstery supply chains, prioritizing recycled content thresholds and carbon footprint transparency that legacy petroleum-based fiber systems cannot satisfy.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding recycled content targets for automotive textiles are redirecting R&D budgets toward chemical recycling infrastructure and bio-based nylon pilot lines.
- Battery electric vehicle platforms:Extended range architectures generate interior thermal management demands that technical woven fabrics address through engineered breathability and moisture-wicking structures.
- Stuttgart-Munich supplier clustering:Germany's integrated Tier 1 technical textile corridors compress development cycles through co-located fiber extrusion, weaving, and finishing capabilities.
Market Restraints
- Recycled polyester feedstock volatility:Post-consumer PET bottle collection rates fluctuate with oil price swings, creating input cost instability for sustainable fiber claims.
- REACH substance authorization delays:ECHA's evolving restricted substance list forces reformulation of flame-retardant finishing chemistries mid-contract, freezing specification approvals.
- Technical textile weaving concentration:High-speed air-jet loom capacity clusters in Germany and Japan, exposing buyers to single-source geographic risk during freight disruptions.
Strategic Opportunities
- Mexico automotive assembly corridor expansion:Guanajuato and Puebla production hubs lack localized woven upholstery finishing capacity, creating greenfield investment openings for cut-and-sew integration.
- Extended producer responsibility frameworks:France's AGEC law and pending EU textile EPR schemes reward suppliers with closed-loop take-back infrastructure.
- Digital textile printing convergence:On-demand color and pattern customization at loom-stage eliminates inventory risk for low-volume premium vehicle programs.
Industry Challenges
- Automotive color matching certification:OEM specification cycles require 18-24 month lab dip approvals, compressing innovation windows against fast-fashion textile timelines.
- Flammability testing backlog:FMVSS 302 and ECE R118 protocol harmonization delays strand multi-market products in redundant certification queues.
- Polymer science talent scarcity:Bio-based nylon and recycled PET molecular engineering expertise concentrates in European chemical conglomerates, constraining independent supplier technical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Woven Upholstery Market |
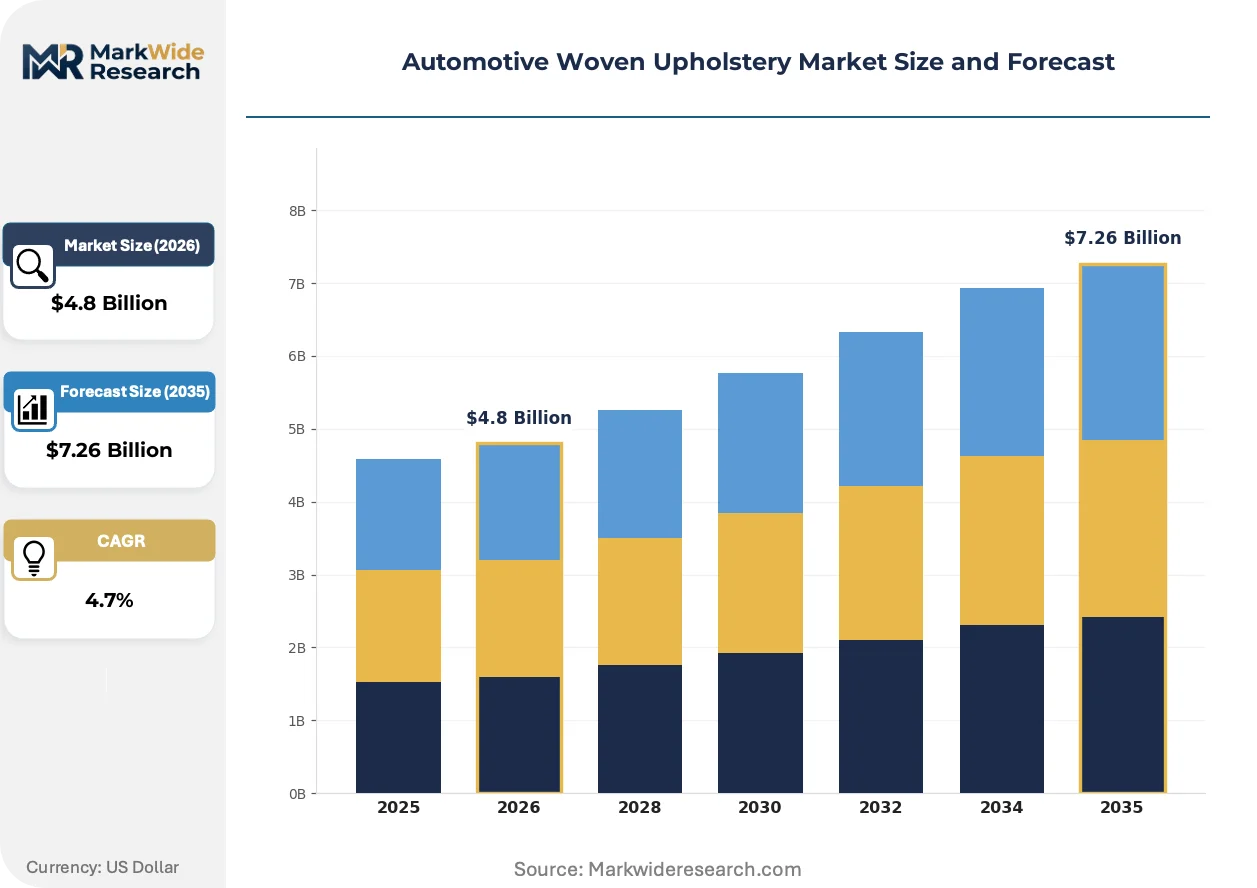
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seat Covers, Headliners, Door Panels, Carpets Material: Polyester, Nylon, Cotton, Blend Manufacturing Stage: Weaving, Finishing, Quality Testing, Assembly End User: OEMs, Aftermarket Suppliers, Automotive Dealerships, Vehicle Assemblers |
| Companies Covered | Lear Corporation, Adient PLC, Toyota Boshoku Corporation, Forvia SE, Seiren Co. Ltd, Sage Automotive Interiors, Grammer AG, The Haartz Corporation, Acme Mills Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Woven Upholstery Market Trends and Innovations
Woven upholstery supply chains are bifurcating between premium sustainable specifications and cost-optimized conventional materials, with regulatory compliance costs accelerating this segmentation.
Solution-dyed polyester filament technology is collapsing the traditional piece-dye finishing step by integrating colorant at extrusion, eliminating water-intensive dye baths. Luxury EV seating programs specify this process for lot-to-lot consistency. The technology is collapsing capital requirements for mid-scale weaving operations while locking in chemical recyclability through single-polymer construction.
REACH substance restrictions are tightening allowable limits on halogenated flame retardants in automotive interior applications. ECHA's 2025-2027 authorization sunset timeline forces reformulation toward phosphorus-nitrogen synergists and intumescent coatings. European OEMs are responding by pre-qualifying alternative chemistries two model cycles ahead of mandate deadlines.
Fleet operators and mobility-as-a-service platforms are compressing upholstery replacement cycles from seven-year passenger vehicle norms to 24-36 month intervals for high-utilization ride-hail vehicles. This pattern concentrates demand in abrasion-resistant 600-800 denier constructions with modular fastener systems. The shift is most visible in North American urban mobility deployments where seat cover refresh contracts now outpace traditional OEM supply agreements.
Automotive Woven Upholstery Market Segmentation
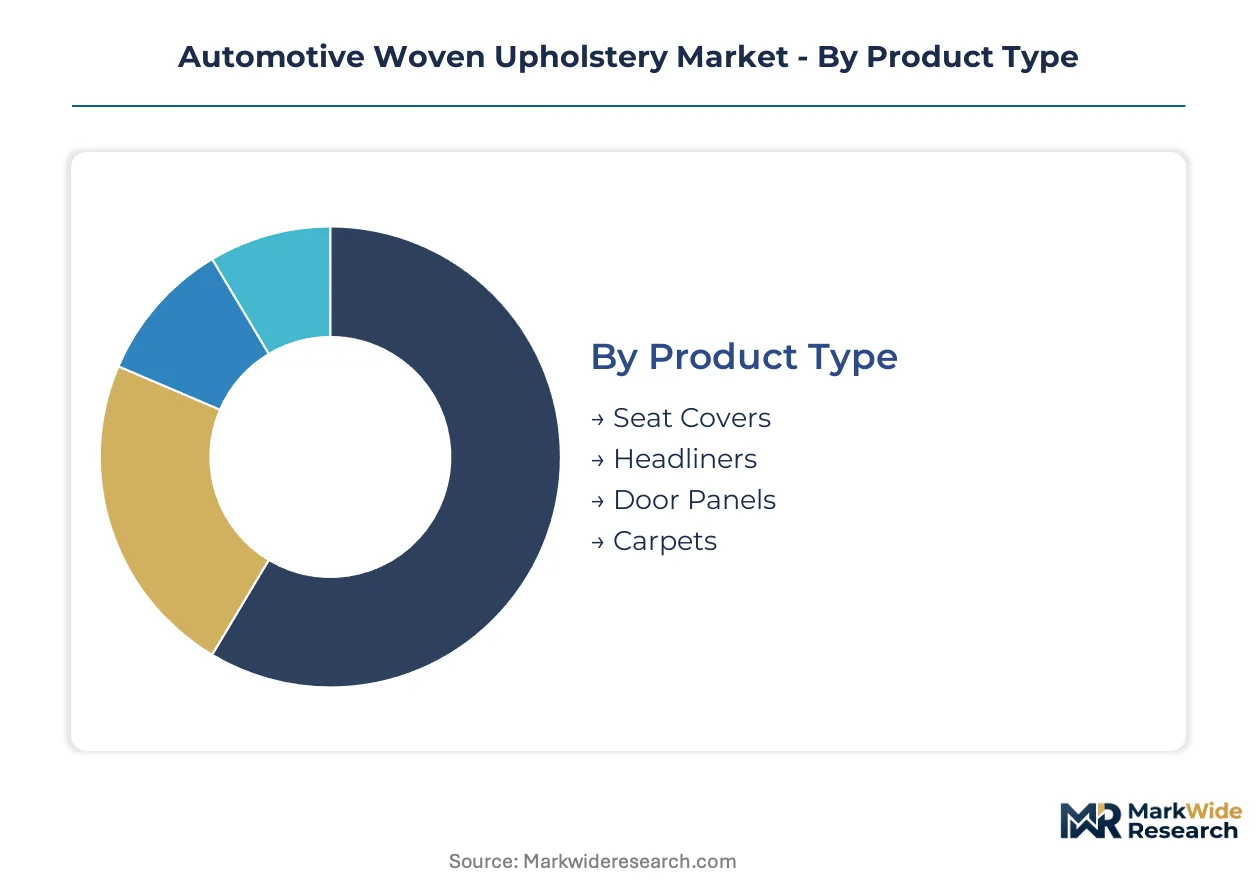
Woven upholstery specifications fragment across vehicle programs based on occupant contact intensity, thermal exposure, and visibility requirements. Segment-specific cycle times—from 18-month OEM seat cover approvals to 6-month aftermarket refresh programs—determine supplier capacity allocation and margin capture.
Product Type:
Seat cover programs rotate through specification cycles fastest due to direct passenger contact and OEM design differentiation priorities, while headliner and carpet platforms sustain longer production runs across model generations.
- Seat Covers:Engineered fabrics face 50,000+ Martindale abrasion cycles with solution-dyed polyester filaments specified for luxury EV platforms demanding lot-to-lot color consistency. Stuttgart-Munich Tier 1 clusters concentrate development resources here, compressing lab dip approvals through co-located weaving and finishing.
- Headliners:Lower denier constructions prioritize acoustic dampening and thermal insulation over surface durability, with specifications locked 24-36 months ahead of vehicle launch. Germany's integrated technical textile corridors dominate prototype-to-production transitions for premium cabin programs.
- Door Panels:Secondary contact surfaces tolerate 30,000-40,000 cycle specifications with faster approval timelines.
- Carpets:Tufted and needle-punched constructions predominate; woven applications concentrate in cargo areas and premium footwell zones.
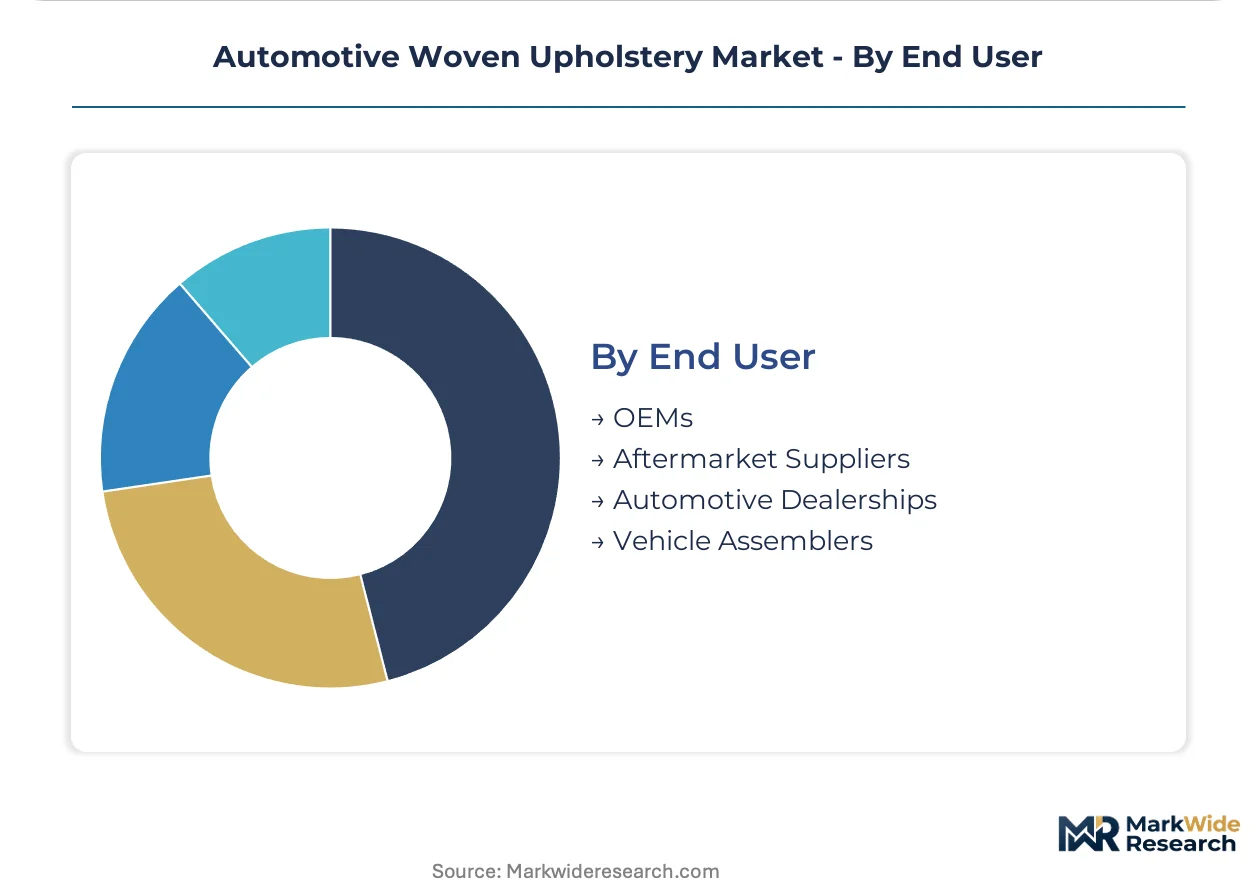
Seat covers dominate installed base value capture. Headliners are where expansion concentrates for acoustic-thermal multifunction fabrics.
Material:
Cost tiers separate feedstock categories, with virgin petroleum-based fibers occupying economy specifications while recycled and bio-sourced alternatives command premium positioning under EU Green Deal compliance frameworks.
- Polyester:Solution-dyed filament technology eliminates water-intensive piece-dye finishing, locking in chemical recyclability through single-polymer construction. REACH substance restrictions are accelerating substitution toward post-consumer PET feedstocks, though collection rate volatility creates input cost instability.
- Nylon:Bio-based pilot lines from European chemical conglomerates target 600-800 denier abrasion-resistant specifications for high-utilization fleet vehicles. Polymer science talent scarcity constrains independent supplier technical staffing for molecular engineering programs.
- Cotton:Natural fiber applications retreat to heritage luxury programs with limited volume scale.
- Blend:Multi-fiber constructions balance cost and performance across mid-tier vehicle specifications.
Polyester dominates installed base tonnage. Nylon is where specification share climbs fastest for durability-critical applications.
Manufacturing Stage:
Supply concentration varies sharply across process steps, with weaving capacity clustering in Germany and Japan while finishing and assembly disperse toward customer proximity.
- Weaving:High-speed air-jet loom capacity concentrates in Stuttgart-Munich corridors and Japanese technical textile centers, exposing buyers to single-source geographic risk. Mexico's Guanajuato-Puebla automotive corridor lacks localized woven upholstery capacity, creating greenfield investment openings.
- Finishing:Proprietary coating lines differentiate competitors on flammability performance without halogenated additives. ECHA's 2025-2027 authorization sunset timeline forces mid-contract reformulation, freezing specification approvals.
- Quality Testing:FMVSS 302 and ECE R118 protocol harmonization delays strand multi-market products in redundant certification queues.
- Assembly:Cut-and-sew operations follow vehicle assembly geography, with vertically integrated Tier 1s capturing margin through captive finishing-to-assembly workflows.
Weaving dominates capital intensity and geographic concentration. Finishing is where competitive differentiation and regulatory compliance costs concentrate.
End User:
Customer type determines contract structure, with OEMs locking multi-year volume commitments that aftermarket channels cannot replicate.
- OEMs:Long-term supply agreements specify recycled content thresholds and carbon footprint transparency that legacy fiber systems cannot satisfy. Battery electric vehicle platforms generate interior thermal management demands addressed through engineered breathability structures.
- Aftermarket Suppliers:24-36 month replacement cycles for ride-hail fleet operators concentrate demand in modular fastener systems and abrasion-resistant constructions.
- Automotive Dealerships:Service department upholstery refresh programs operate on compressed procurement timelines with limited specification control.
- Vehicle Assemblers:Contract manufacturers source through OEM-directed supply agreements with limited independent sourcing authority.
OEMs dominate specification authority and value capture. Aftermarket suppliers are where volume expansion concentrates for high-utilization mobility platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance restrictions under REACH are recalibrating supplier investment priorities across European automotive textile corridors. Regional procurement patterns now diverge between jurisdictions with binding recycled content mandates and markets where conventional specifications still dominate.
Germany
Luxury electric vehicle programs from Stuttgart-based OEMs are specifying solution-dyed polyester filaments with carbon footprint documentation. EU Green Deal circular economy requirements are accelerating chemical recycling infrastructure investment around Munich. The Stuttgart-Munich technical textile corridor concentrates high-speed air-jet loom capacity with co-located fiber extrusion and finishing operations.
United States
NHTSA flammability protocols under FMVSS 302 maintain baseline safety thresholds for all interior materials. EPA volatile organic compound emission standards are constraining adhesive chemistries available to domestic finishing operations. The Southeast automotive assembly belt lacks localized woven upholstery weaving capacity, forcing reliance on imported technical textiles from Germany and Japan.
Mexico
Guanajuato and Puebla production hubs are expanding seat cover assembly operations for North American-bound vehicles. The country's national environmental regulator is aligning automotive interior material standards with EPA reference frameworks. Greenfield investment openings exist for cut-and-sew integration with captive finishing lines serving hybrid and electric platforms.
Japan
METI industrial policy is supporting bio-based nylon pilot lines targeting 600-800 denier abrasion specifications. Japanese technical textile centers concentrate proprietary weaving technology for moisture-wicking interior structures. Toyota Boshoku anchors domestic woven fabric strategy through dedicated technical textile lines serving regional OEM platforms.
China
MIIT dual carbon goals are redirecting polyester feedstock sourcing toward post-consumer PET collection infrastructure. GB standards for automotive interior flammability are harmonizing with ECE R118 protocols for export-bound production. Yangtze River Delta chemical conglomerates are scaling molecular engineering capacity for recycled and bio-sourced fiber alternatives.
Automotive Woven Upholstery Market Competitive Landscape
Capability concentration sits with integrated Tier 1 specialists possessing in-house weaving and finishing assets; scale advantage sits with diversified automotive suppliers with captive assembly operations. The vendor base separates into three archetypes: European technical textile specialists with REACH-compliant chemical recycling infrastructure, Japanese diversified suppliers with proprietary loom technology, and North American assembly-integrated players with cut-and-sew proximity to vehicle plants. Dominant competitive moves include backward integration into fiber extrusion to secure recycled content claims and geographic expansion toward Mexico's automotive corridor to compress logistics costs.
Within the assembly-integrated tier, Lear Corporation and Adient PLC exemplify scale-driven positioning through vertically controlled cut-and-sew workflows. Toyota Boshoku Corporation represents the Japanese diversified supplier archetype with technical textile specialization. These three anchors demonstrate how competitive positioning stratifies between proximity-based assembly integration and upstream material technology control.
| Leading Market Players |
|---|
| Lear Corporation |
| Adient PLC |
| Toyota Boshoku Corporation |
| Forvia SE |
| Seiren Co. Ltd |
| Sage Automotive Interiors |
| Grammer AG |
| The Haartz Corporation |
| Acme Mills Company |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese high-speed air-jet loom capacity compresses pricing power for North American buyers while simultaneously forcing three-tier spreads between REACH-compliant sustainable specifications, conventional technical grades, and economy blend constructions. This geographic chokepoint rewards integrated Tier 1s with captive weaving assets while exposing non-integrated assemblers to freight-driven cost volatility.
Pricing Analysis
German-sourced solution-dyed polyester filaments command substantial premiums over Asian conventional grades due to carbon footprint documentation and lot-to-lot consistency guarantees. Pricing stratifies across premium, standard, and economy tiers based on recycled content thresholds and flammability certification levels. Cost compression in the standard tier is intensifying because post-consumer PET bottle collection rate volatility feeds directly into fiber input costs. Fleet operators and mobility-as-a-service platforms exhibit the highest price sensitivity due to compressed 24-36 month replacement cycles, while luxury electric vehicle OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced textile manufacturing equipment limit loom technology transfer outside established German and Japanese production corridors. Raw material flows draw from post-consumer PET collection networks, bio-based nylon pilot lines, and virgin petroleum-based fiber extrusion. Single-source vulnerability concentrates in Stuttgart-Munich weaving clusters where high-speed air-jet capacity anchors global technical textile output. Distribution runs through vertically integrated Tier 1 cut-and-sew operations positioned adjacent to vehicle assembly plants in Guanajuato, Puebla, and the Southeast United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer science expertise for bio-based nylon molecular engineering concentrates in European chemical conglomerates, leaving independent suppliers and new market participants exposed to talent acquisition bottlenecks and R&D staffing constraints.
For Market Incumbents: Harden specification control through backward integration into chemical recycling infrastructure and captive fiber extrusion assets. Lock in multi-year volume commitments with OEMs ahead of ECHA's 2025-2027 flame-retardant authorization sunset timeline. Prioritize co-located weaving and finishing capacity in the Stuttgart-Munich corridor to compress 18-24 month lab dip approval cycles. For New Entrants and Emerging Players: Establish a beachhead in Mexico's Guanajuato-Puebla automotive corridor where localized woven upholstery finishing capacity remains underdeveloped. Target aftermarket fleet refresh programs for ride-hail and mobility-as-a-service platforms with modular fastener systems and abrasion-resistant 600-800 denier constructions. Pursue partnerships with established Japanese technical textile centers to access proprietary moisture-wicking loom technology. For Investors and Strategic Acquirers: European technical textile specialists with REACH-compliant chemical recycling infrastructure and co-located fiber-to-fabric production represent the most defensible acquisition archetype. Monitor ECHA substance authorization timelines as the critical inflection signal—reformulation mandates that freeze specification approvals will accelerate consolidation among finishing-dependent suppliers. Material shifts in post-consumer PET collection infrastructure economics or bio-based nylon scale-up timelines would require updated calibration.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | Secures recycled content claims for EU Green Deal compliance ahead of binding mandates. |
| Mexico Cut-and-Sew Integration | Captures logistics cost advantages in Guanajuato-Puebla corridor serving North American hybrid and electric platforms. |
| Solution-Dyed Filament Scale-Up | Eliminates water-intensive piece-dye finishing while locking in single-polymer chemical recyclability for luxury EV programs. |
| Phosphorus-Nitrogen Flame Retardant Pre-Qualification | Positions suppliers ahead of ECHA's halogenated additive authorization sunset timeline. |
| Digital Textile Printing Convergence | Enables on-demand color customization at loom-stage for low-volume premium vehicle programs without inventory risk. |
Research Methodology
Initial hypotheses were tested against primary input from Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and technical textile R&D leads and refined through secondary validation against vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from publicly listed automotive suppliers. Bottom-up segment sizing triangulated with top-down market value reconstruction across material, product type, and end-use dimensions.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from elasticity-adjusted growth curves incorporating OEM platform launch schedules and regulatory compliance timeline impacts. Forecast inputs included battery electric vehicle adoption trajectories and REACH substance restriction implementation phases.
Sensitivities concentrate around post-consumer PET collection rate volatility, ECHA authorization timeline shifts, and Mexican automotive assembly expansion pace. Forecasts reflect documented assumptions regarding fiber feedstock availability and regulatory harmonization progress. Material shifts in EU Green Deal recycled content mandate stringency or bio-based nylon commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
United States Car Bumper Guard Market