
 North America Automotive Interior Materials Market | 2026-2036
North America Automotive Interior Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Interior Materials Market Analytics
Multi-source procurement for seat foam and trim textiles is shifting toward vertically integrated captive supply among tier-one suppliers. Lear Corporation leverages its North American seating footprint to control resin-to-assembly pathways. Adient PLC anchors its position through dedicated just-in-time plants adjacent to Detroit Three assembly complexes. Magna International competes by extending its interiors division into thermoplastic composite structures for lightweight door panels.
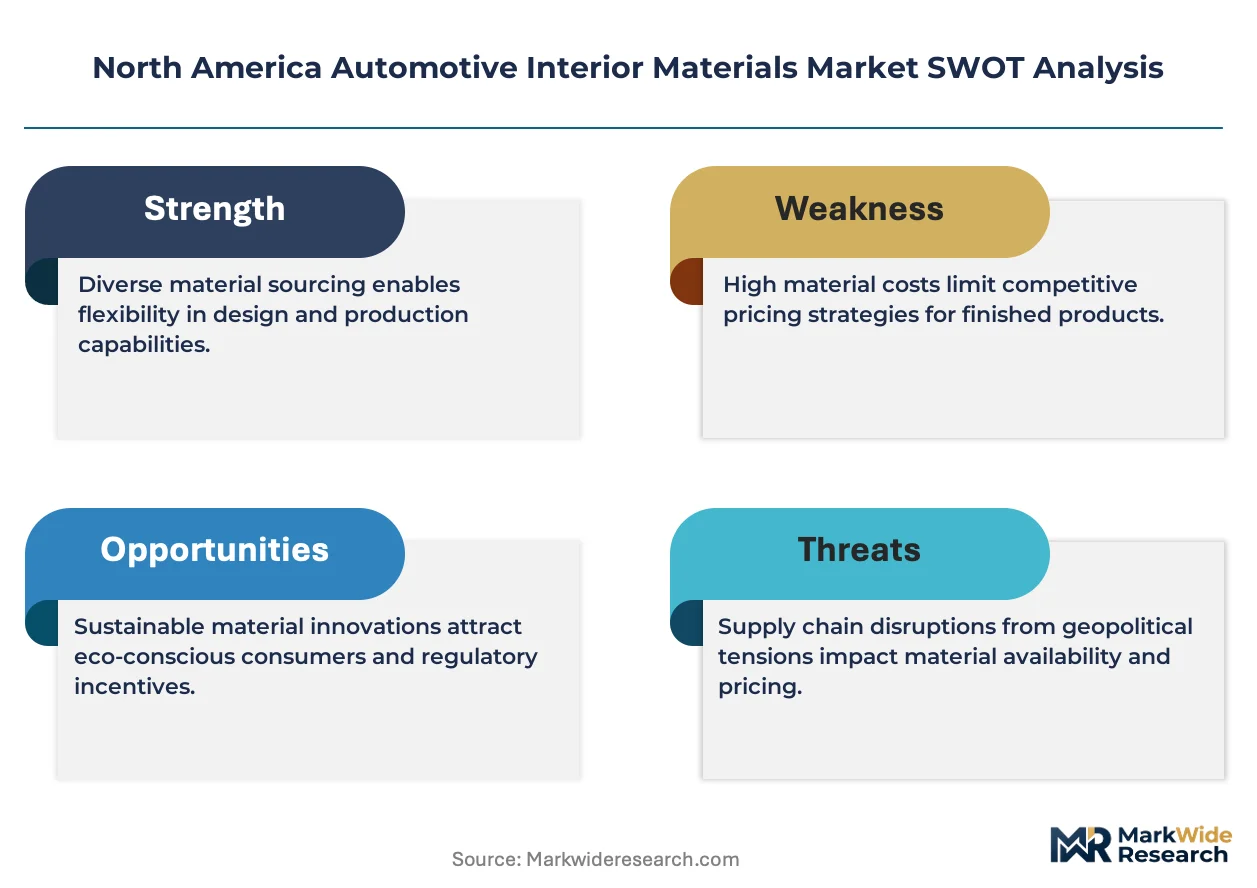
Automotive interior materials encompass engineered textiles, polymer foams, synthetic leathers, and decorative surfaces specified for cabin occupant contact, thermal comfort, and crash safety performance. Polyurethane foam densities range from 25 to 80 kilograms per cubic meter depending on seat cushion versus bolster applications, with flame-retardant additives meeting federal motor vehicle safety standards for burn resistance. Leather and vinyl surfaces command the highest margin pools in material type segmentation due to premium vehicle configuration rates, while eco-friendliness features are gaining specification share as OEM sustainability targets harden. Component fabrication and assembly stages concentrate value capture, whereas raw material processing remains more fragmented across commodity chemical suppliers.
NHTSA Federal Motor Vehicle Safety Standard 302 governs interior material flammability, while EPA regulations under the Toxic Substances Control Act restrict certain phthalate plasticizers in vinyl applications. Health Canada aligns with US standards through its Motor Vehicle Safety Regulations, creating harmonized compliance burdens for cross-border suppliers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and pending revisions to federal volatile organic compound emission limits for cabin air quality.
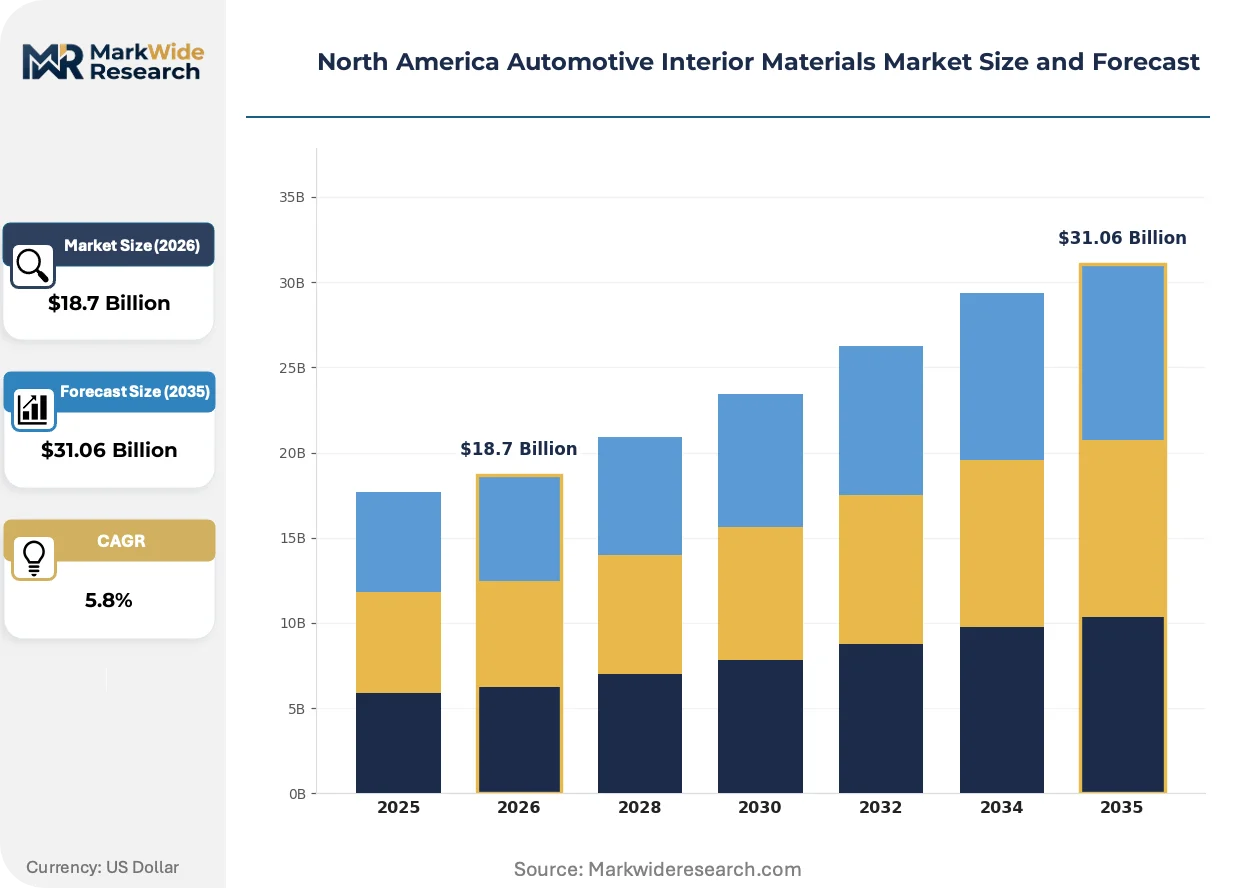
Market Dynamics
Captive supply consolidation among tier-one seating suppliers is compressing procurement pathways across the US Great Lakes automotive corridor, locking resin-to-assembly control within vertically integrated production networks.
Growth Catalysts
- EPA Tailpipe Standards:Tightening federal emission rules are accelerating specification of lightweight thermoplastic composites for door panels and instrument clusters to reduce vehicle mass.
- Polyurethane Foam Density Optimization:Seat cushion engineering at 25-80 kg/m³ density ranges is enabling dual-function thermal comfort and crash energy management in electric vehicle platforms.
- California Extended Producer Responsibility:Pending state-level frameworks for material recyclability are pulling recycled content specifications into premium vehicle configurations ahead of federal mandates.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane resin and synthetic leather precursor costs fluctuate with US Gulf Coast propylene and MDI supply disruptions, compressing margin pools for commodity interior components.
- NHTSA FMVSS 302 Compliance Burden:Federal flammability testing protocols for burn resistance create extended validation timelines for new material formulations, delaying supplier qualification cycles.
- Phthalate Plasticizer Substitution Costs:EPA Toxic Substances Control Act restrictions on legacy vinyl softeners force reformulation investments without immediate pricing recovery mechanisms.
Strategic Opportunities
- Indiana Just-in-Time Corridor:Greenfield seating component plants adjacent to Detroit Three assembly complexes in Kokomo and Fort Wayne offer captive supply positioning with sub-50-mile logistics loops.
- Health Canada Harmonization:Aligned Motor Vehicle Safety Regulations create single-qualification pathways for cross-border material suppliers serving Ontario assembly plants.
- Bio-Based Synthetic Leather:Mycelium and agricultural waste-derived surface materials are converging with OEM sustainability scorecard requirements to open specification slots in luxury electric vehicle interiors.
Industry Challenges
- Flame-Retardant Chemistry Expertise Gap:Formulation chemists capable of balancing FMVSS 302 compliance with volatile organic compound emission limits remain concentrated among legacy polyurethane suppliers, constraining new market entry.
- Multi-Material Bonding Certification:Crash safety validation for thermoplastic composite-to-foam-to-textile laminates requires extended sled testing protocols that compress program timing for model-year changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Interior Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Fabric, Vinyl, Foam End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Product Feature: Durability, Aesthetic Appeal, Fire Resistance, Eco-Friendliness Manufacturing Stage: Raw Material Processing, Component Fabrication, Assembly, Quality Control |
| Companies Covered | Adient PLC, Lear Corporation, Faurecia, Grupo Antolin, Toyota Boshoku Corporation, Magna International, Yanfeng Automotive Interiors, Grammer AG, International Automotive Components, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Interior Materials Market Evolving Landscape
Material science advances are compressing the traditional separation between structural performance and cabin aesthetics, forcing suppliers to engineer single components that satisfy crash safety, thermal comfort, and sustainability specifications simultaneously.
Recycled polyethylene terephthalate fiber production is converging with automotive textile specifications to enable closed-loop seat fabric supply chains. Tier-one suppliers in Michigan and Ohio are integrating post-consumer plastic feedstock into yarn spinning operations for OEM sustainability reporting. This convergence is compressing virgin polymer demand while creating certification dependencies on third-party recycled content verification systems.
NHTSA Federal Motor Vehicle Safety Standard 302 revisions under interagency review are expanding burn testing protocols to include smolder resistance for electric vehicle battery thermal event scenarios. Seat foam suppliers face reformulation mandates for phosphorus-based intumescent additives. The US domestic supply base is responding by accelerating in-house combustion testing laboratory investments to reduce third-party validation bottlenecks.
Buyer specification behavior is fragmenting across Detroit Three, Tesla, and Lucid procurement organizations with divergent sustainability scoring methodologies. Traditional commodity bidding for seat trim textiles is giving way to lifecycle assessment-based supplier scorecards that weight carbon footprint above unit pricing. This pattern is most visible in California and Washington state vehicle registration corridors where consumer-facing sustainability claims drive OEM marketing differentiation.
North America Automotive Interior Materials Market Segmentation
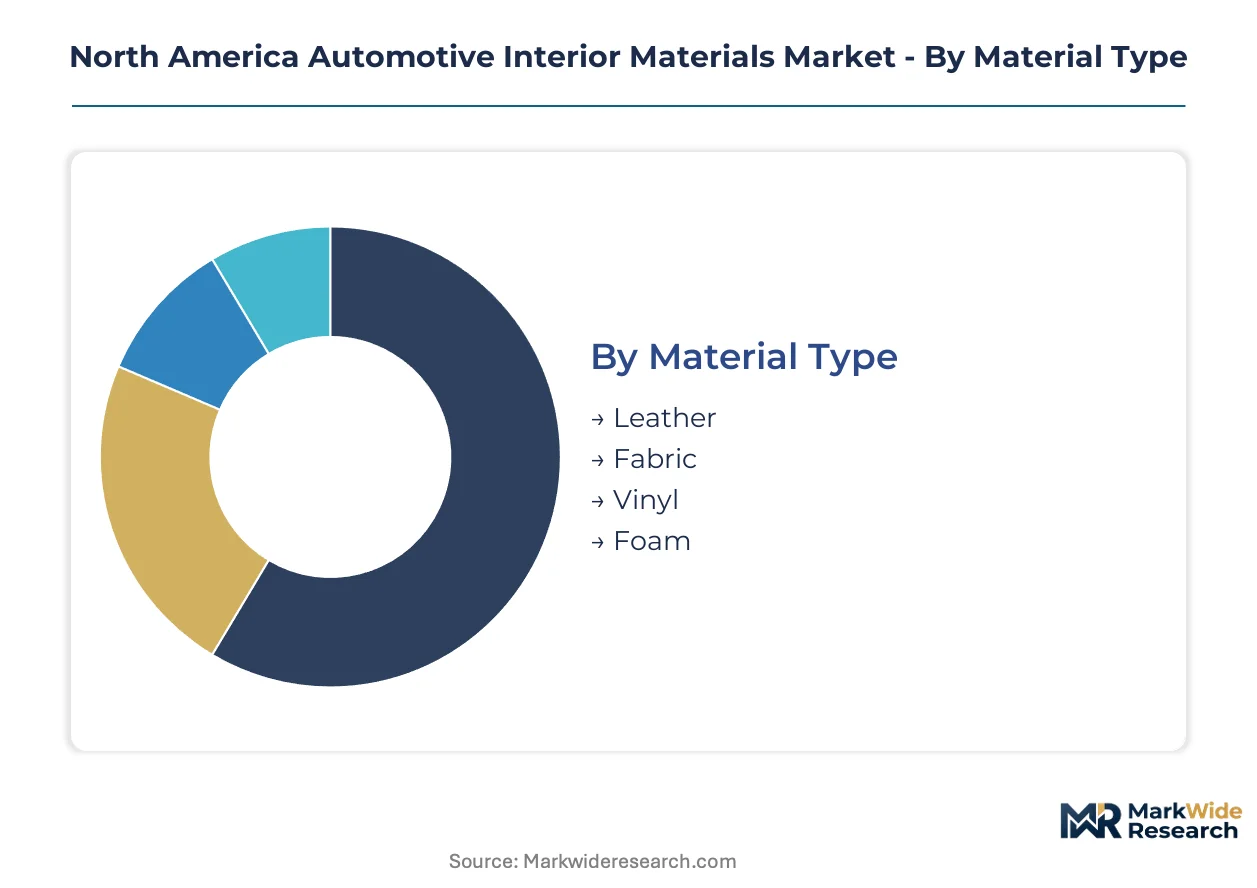
Interior material specifications fragment across certification regimes, with NHTSA FMVSS 302 flammability standards governing foam selections and EPA TSCA chemical restrictions filtering vinyl formulations. Procurement pathways diverge between captive OEM supply chains and aftermarket distribution channels, each carrying distinct validation burdens and margin structures.
Material Type:
FMVSS 302 burn resistance certification applies universally across all four material classes, though leather and vinyl face additional EPA phthalate scrutiny while foam carries NHTSA crash-energy management obligations.
- Foam:Polyurethane formulations at 25-80 kg/m³ density ranges serve dual functions in seat cushions and bolsters, with phosphorus-based intumescent additives now mandatory for electric vehicle battery thermal event scenarios. Michigan and Ohio suppliers dominate captive production for Detroit Three seating programs.
- Leather:Premium hide processing commands the highest margin pools in material type segmentation, with sustainability scorecards from California-registered OEMs pulling recycled content and traceability certifications into specification requirements ahead of federal mandates.
- Fabric:Engineered textiles from recycled polyethylene terephthalate fiber are converging with closed-loop supply chain requirements in Great Lakes manufacturing corridors.
- Vinyl:Synthetic leather precursors face reformulation investments as EPA TSCA restrictions on legacy plasticizers force substitution without immediate pricing recovery mechanisms.
Leading the category by volume: Foam. Growing fastest: Leather.
End User:
Procurement authority concentrates differently across the value chain, with OEMs wielding sustainability scorecard power while tier-one suppliers control resin-to-assembly pathways through backward integration.
- Tier-1 Suppliers:Lear Corporation, Adient PLC, and Magna International anchor captive supply networks through just-in-time plants adjacent to Detroit Three assembly complexes, locking in sub-50-mile logistics loops across Indiana and Michigan.
- OEMs:Tesla and Lucid procurement organizations apply divergent lifecycle assessment methodologies that weight carbon footprint above unit pricing, fragmenting traditional commodity bidding patterns for seat trim textiles.
- Vehicle Assemblers:Final assembly operations in the US Great Lakes corridor specify material bundles through consolidated tier-one contracts rather than direct raw material procurement.
- Aftermarket Providers:Independent distribution channels serve collision repair and vehicle refurbishment demand outside captive OEM supply chains, with less stringent certification requirements but compressed margin structures.
Controlling procurement volume: Tier-1 Suppliers. Expanding most quickly: OEMs.
Product Feature:
Feature prioritization splits across regulatory compliance, consumer-facing marketing claims, and long-term durability engineering, with electric vehicle platforms forcing convergence of previously separate performance attributes.
- Fire Resistance:NHTSA Federal Motor Vehicle Safety Standard 302 governs burn testing protocols, with pending revisions expanding smolder resistance requirements for battery thermal event scenarios and accelerating in-house combustion laboratory investments among domestic foam suppliers.
- Eco-Friendliness:California extended producer responsibility frameworks and OEM sustainability targets are pulling mycelium and agricultural waste-derived surface materials into luxury electric vehicle interior specifications.
- Durability:Abrasion resistance and UV stability specifications concentrate value capture in component fabrication stages rather than raw material processing.
- Aesthetic Appeal:Premium vehicle configuration rates drive leather and vinyl surface selections, with tactile quality and visual grading systems filtering supplier qualification.
Highest specification priority: Fire Resistance. Gaining share fastest: Eco-Friendliness.
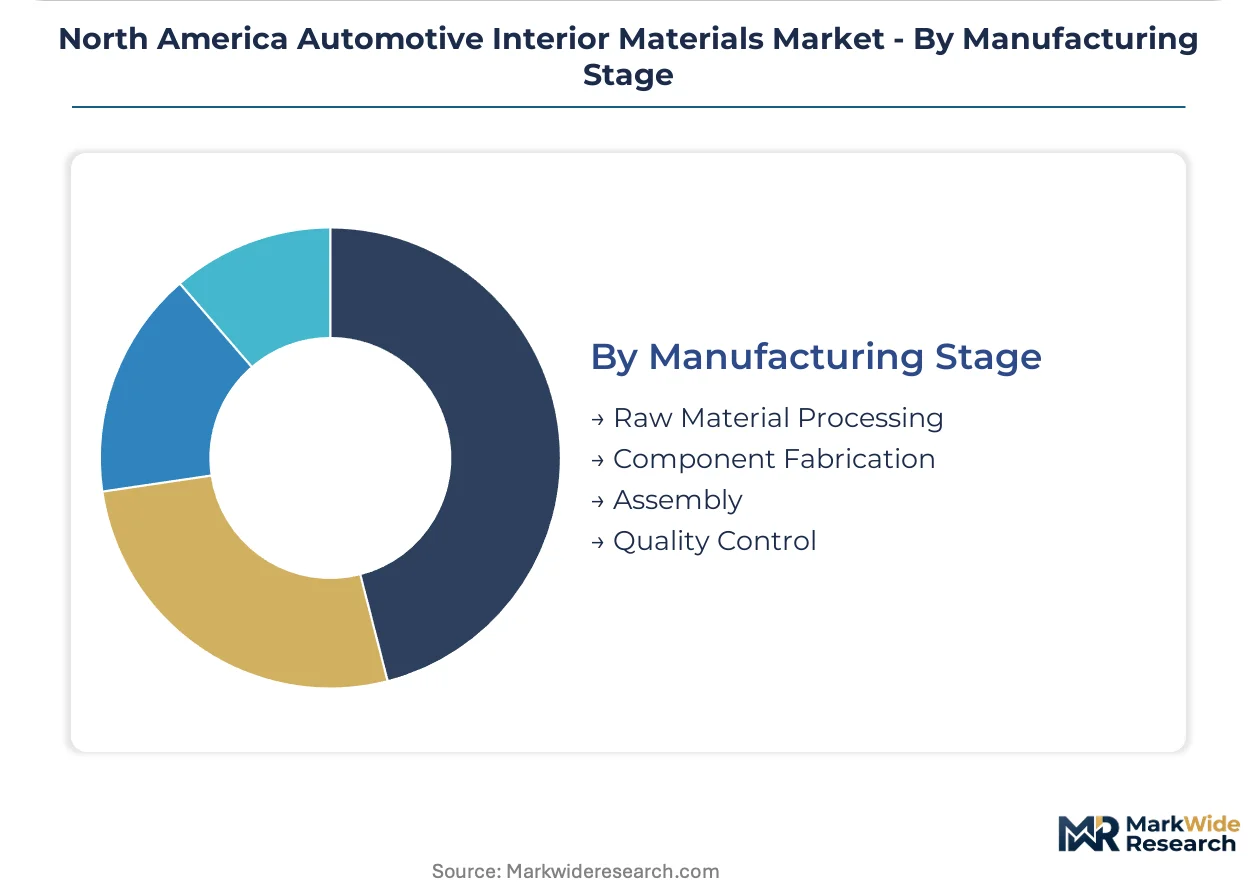
Manufacturing Stage:
Value capture concentrates in downstream fabrication and assembly operations, while raw material processing remains fragmented across commodity chemical suppliers with thinner margin pools.
- Component Fabrication:Thermoplastic composite structures for lightweight door panels and instrument clusters represent the primary margin concentration point, with Magna International extending its interiors division to capture specification slots for EPA tailpipe-driven mass reduction programs.
- Assembly:Seat cushion-to-bolster integration and multi-material bonding certification for crash safety validation require extended sled testing protocols that compress program timing for model-year changeovers.
- Raw Material Processing:Polyurethane resin and synthetic leather precursor production fluctuates with US Gulf Coast propylene and MDI supply disruptions, constraining input cost stability for downstream operations.
- Quality Control:Third-party recycled content verification systems and volatile organic compound emission testing create certification dependencies that filter supplier entry.
Capturing highest margins: Component Fabrication. Steepest expansion trajectory: Assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Gulf Coast petrochemical feedstock availability anchors polyurethane resin supply chains for North American automotive interior production, with propylene and MDI pricing volatility propagating through Great Lakes manufacturing corridors.
United States
EPA tailpipe standards and NHTSA FMVSS 302 revisions are accelerating lightweight thermoplastic composite adoption across Michigan, Ohio, and Indiana assembly plants. The US Great Lakes automotive corridor concentrates captive seating supply networks within sub-50-mile logistics loops of Detroit Three facilities.
Canada
Health Canada Motor Vehicle Safety Regulations harmonize with US standards, enabling single-qualification pathways for cross-border material suppliers. Ontario assembly plants in Windsor and Oshawa integrate with US tier-one supplier networks, particularly for just-in-time foam and textile delivery systems.
Mexico
Expanding vehicle assembly capacity in Nuevo León and Bajío Region states is pulling interior component fabrication southward from US border zones. Mexican automotive manufacturing growth under USMCA trade provisions supports resin-to-assembly investments by multinational seating suppliers.
North America Automotive Interior Materials Market Competitive Landscape
Captive supply consolidation dominates the current landscape, compressing procurement pathways into vertically integrated production networks. Tier-one seating suppliers control resin-to-assembly pathways through backward integration into polyurethane foam and synthetic leather precursor operations. Three strategic archetypes anchor competitive positioning: integrated seating system providers, modular interior component specialists, and raw material-to-finish surface vertically integrated players. M&A activity and geographic co-location with OEM assembly plants represent the dominant competitive moves.
Within the integrated seating system tier, Lear Corporation and Adient PLC exemplify archetype leaders through their North American manufacturing footprints. Magna International occupies a position among modular component specialists extending into thermoplastic composite structures. These three entities represent the consolidated core of tier-one supply relationships with Detroit Three, Tesla, and Lucid procurement organizations.
| Leading Market Players |
|---|
| Adient PLC |
| Lear Corporation |
| Faurecia |
| Grupo Antolin |
| Toyota Boshoku Corporation |
| Magna International |
| Yanfeng Automotive Interiors |
| Grammer AG |
| International Automotive Components |
| Others |
Value Network & Pricing Analysis
Captive supply consolidation among Lear Corporation, Adient PLC, and Magna International anchors both procurement control and margin capture across the US Great Lakes automotive corridor. This backward integration into polyurethane foam and synthetic leather precursor operations locks resin-to-assembly pathways within sub-50-mile logistics loops, compressing third-party supplier pricing power while insulating tier-one margins from commodity volatility.
Pricing Analysis
Service bundling separates qualified suppliers from commodity competitors, with NHTSA FMVSS 302 compliance testing and volatile organic compound certification included in long-term supply agreements rather than unbundled add-ons. Three-tier pricing structure across premium, standard, and economy levels tracks leather grade, foam density specification, and recycled content verification tier. Cost compression in vinyl formulations is intensifying because EPA TSCA phthalate substitution investments lack immediate pass-through mechanisms. Aftermarket providers exhibit highest price sensitivity due to thin margin structures, while OEM sustainability scorecards suppress pure price competition among captive tier-one networks.
Supply Chain Analysis
Freight cost minimization drives geographic clustering, with just-in-time seating component plants concentrated in Kokomo and Fort Wayne, Indiana within sub-50-mile delivery radius of Detroit Three assembly complexes. Raw material supply draws from US Gulf Coast propylene and MDI production, Michigan and Ohio foam fabrication, and Ontario textile spinning operations. Single-source vulnerability concentrates in phosphorus-based intumescent additive supply for electric vehicle battery thermal event compliance. Distribution runs through tier-one supplier direct-to-assembly plant contracts, bypassing independent distributor networks for original equipment specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA Federal Motor Vehicle Safety Standard 302 functions as a cost-of-compliance moat, with extended burn testing validation timelines and in-house combustion laboratory investments filtering out undercapitalized entrants. This regulatory barrier protects qualified incumbents while forcing new market participants to absorb qualification costs before revenue generation.
For Market Incumbents: Acquire in-house combustion testing capabilities to eliminate third-party validation bottlenecks and compress supplier qualification cycles for model-year changeovers. Extend backward integration into recycled polyethylene terephthalate fiber spinning to capture closed-loop supply chain premiums from California-registered OEM sustainability scorecards. Consolidation of phosphorus-based intumescent additive formulation expertise protects against emerging Chinese specialty chemical entrants. For New Entrants and Emerging Players: California Extended Producer Responsibility frameworks open a window for mycelium-derived surface material specialists to penetrate luxury electric vehicle interior specifications ahead of federal mandates. Target aftermarket collision repair channels with FMVSS 302-certified foam alternatives that bypass captive OEM supply chain lock-in. Lead with sustainability certification as the go-to-market wedge against commodity vinyl competitors facing EPA TSCA reformulation cost disadvantages. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational seating suppliers seeking Indiana and Michigan just-in-time plant footprints. Long-term viability favors tier-one suppliers with demonstrated NHTSA compliance track records and OEM sustainability scorecard alignment. Watch for inflection in state-level extended producer responsibility adoption beyond California as signal for recycled content specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Precursor Production | Captures resin-to-assembly margin pools while insulating Lear Corporation and Adient PLC from US Gulf Coast MDI price volatility. |
| In-House Combustion Testing Laboratory Investment | Compresses NHTSA FMVSS 302 validation timelines for new formulations and accelerates electric vehicle platform qualification cycles. |
| Recycled Content Verification Partnership | Enables closed-loop seat fabric supply chains aligned with California OEM sustainability reporting requirements and pending EPR frameworks. |
| Indiana Just-in-Time Plant Expansion | Positions Magna International within sub-50-mile logistics loops of Detroit Three assembly complexes for thermoplastic composite door panel programs. |
| Bio-Based Synthetic Leather Development | Converges mycelium and agricultural waste-derived surfaces with Tesla and Lucid lifecycle assessment-based procurement methodologies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and foam formulation chemists. EPA enforcement databases, NHTSA defect investigation filings, and vehicle production registries from IHS Markit supplied quantitative benchmarks. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive interior content-per-vehicle analysis.
Granularity-level modeling deployed vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the projection horizon. CAGRs derived from segment-level volume and value build-ups incorporating electric vehicle platform penetration assumptions and lightweighting specification trends. Forecast inputs included EPA tailpipe standard stringency trajectories and NHTSA FMVSS 302 revision timing assumptions.
The model assumes a particular technology adoption path; alternative pathways for bio-based synthetic leather commercialization would alter the outlook for premium material specification shares. Forecasts reflect assumptions about regulatory harmonization between US and Canadian standards, electric vehicle production ramp rates, and petrochemical feedstock price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Auto Dimming Mirror Market