
 Global Bearing Isolators Market | 2026-2036
Global Bearing Isolators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bearing Isolators Market Foresight
Process industry maintenance teams are rotating away from reactive seal replacement toward predictive specification of bearing isolators in new capital equipment. AESSEAL dominates aftermarket technical service networks across European chemical corridors. Timken Company leverages integrated bearing-isolator systems to anchor long-term supply agreements with power generation OEMs. Parker Hannifin Corporation competes through hydrodynamic seal expertise in oil and gas upstream applications.
Bearing isolators are non-contact sealing devices engineered with precision-machined labyrinth grooves or magnetic flux fields to exclude contaminants and retain lubricants in rotating equipment, typically operating at surface speeds exceeding 25 m/s in continuous-duty industrial environments. Labyrinth bearing isolators sustain the largest installed base due to proven reliability in pump and motor applications with minimal maintenance overhead. Magnetic bearing isolators are capturing specification share in high-speed turbomachinery where zero-contact operation eliminates mechanical wear and extends mean time between overhauls.
EPA emissions standards for process equipment leakage and REACH substance restrictions on traditional seal elastomers are forcing material transitions toward fluoropolymer and advanced ceramic compositions. FDA sanitary design requirements in food processing plants are creating dual-certification demand for isolators that satisfy both 3-A hygienic standards and IP69K washdown ratings. Stakeholders must monitor how IEC 60034-30-1 efficiency class upgrades for rotating electrical machines will rewrite isolator thermal and friction specifications in next-generation equipment procurement.
Market Dynamics
Chemical manufacturing plants in Germany's industrial heartland are accelerating specification upgrades for bearing isolators as EU Green Deal machinery efficiency mandates tighten seal performance requirements across European process industries.
Growth Catalysts
- EU Green Deal efficiency mandates:Machinery performance standards are forcing European process industries to upgrade rotating equipment seals, expanding specification opportunities for advanced isolator designs.
- Predictive maintenance adoption:Process industry maintenance teams are rotating from reactive seal replacement toward predictive specification of bearing isolators in new capital equipment procurement cycles.
- FDA sanitary design requirements:Food processing facilities are creating dual-certification demand for isolators satisfying both 3-A hygienic standards and IP69K washdown ratings.
Market Restraints
- Fluoropolymer input cost volatility:REACH substance restrictions on traditional seal elastomers are forcing material transitions toward advanced ceramic and fluoropolymer compositions with unstable supply pricing.
- Specialized manufacturing concentration:Precision-machined labyrinth groove production capabilities cluster among a limited supplier base in Germany and the United States.
- High-speed turbomachinery technical barriers:Magnetic flux field engineering expertise remains scarce, limiting zero-contact isolator penetration in critical turbomachinery applications.
Strategic Opportunities
- Power generation OEM long-term agreements:Integrated bearing-isolator system suppliers are anchoring decade-spanning supply contracts with equipment manufacturers seeking lifecycle cost reduction.
- IEC 60034-30-1 efficiency class upgrades:Rotating electrical machine efficiency standards are rewriting thermal and friction specifications, creating procurement windows for next-generation isolator designs.
- Oil and gas upstream hydrodynamic specialization:Hydrodynamic seal expertise is capturing specification share in remote extraction environments where maintenance access is severely constrained.
Industry Challenges
- Precision machining skill scarcity:Labyrinth groove manufacturing requires specialized CNC programming capabilities that competing industrial sectors are absorbing from the talent pool.
- Dual-certification compliance timelines:Simultaneous 3-A hygienic and IP69K validation processes extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bearing Isolators Market |
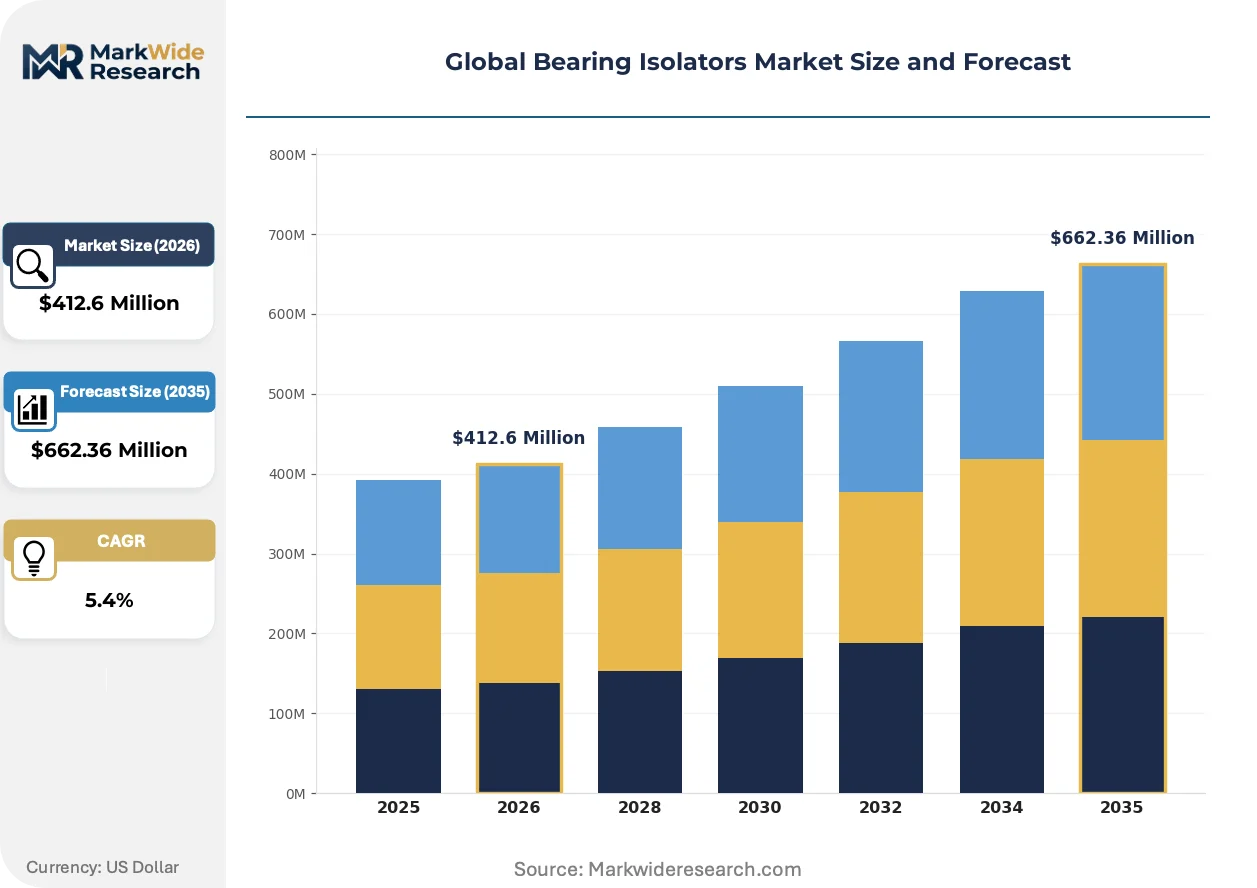
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labyrinth Bearing Isolators, Magnetic Bearing Isolators, Shielded Bearing Isolators, Contactless Bearing Isolators Technology: Sealing Technology, Magnetic Repulsion, Spring-Loaded Mechanism, Hydrodynamic Seals, Mechanical Face Seals Application: Pumps, Compressors, Turbines, Gearboxes, Industrial Fans End User: Power Generation Facilities, Oil & Gas Processors, Chemical Manufacturing Plants, Pulp & Paper Mills, Food Processing Plants |
| Companies Covered | Timken Company, Flowserve Corporation, Parker Hannifin Corporation, AESSEAL, John Crane, Garlock Sealing Technologies, Inpro/Seal, SKF Group, EagleBurgmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bearing Isolators Market Shifts & Advancements
Advanced material compositions and non-contact sealing architectures are fragmenting traditional isolator categories as end-users demand application-specific performance optimization rather than universal designs.
Magnetic bearing isolator technology is fragmenting the high-speed turbomachinery segment. Zero-contact operation eliminates mechanical wear and extends mean time between overhauls. Specifiers in power generation and chemical processing are prioritizing magnetic designs for continuous-duty applications exceeding 25 m/s surface speeds.
REACH substance restrictions are compressing the installed base of traditional elastomeric seals. EPA emissions standards for process equipment leakage are reinforcing material transition timelines. European chemical corridors are responding fastest, with fluoropolymer and ceramic compositions displacing legacy compounds in pump and motor retrofits.
Specification authority is migrating from maintenance departments to capital equipment engineering teams. Long-term supply agreements with OEMs are displacing spot aftermarket purchasing. Germany's industrial heartland exhibits this shift most acutely, where predictive specification now dominates new equipment procurement.
Global Bearing Isolators Market Segmentation
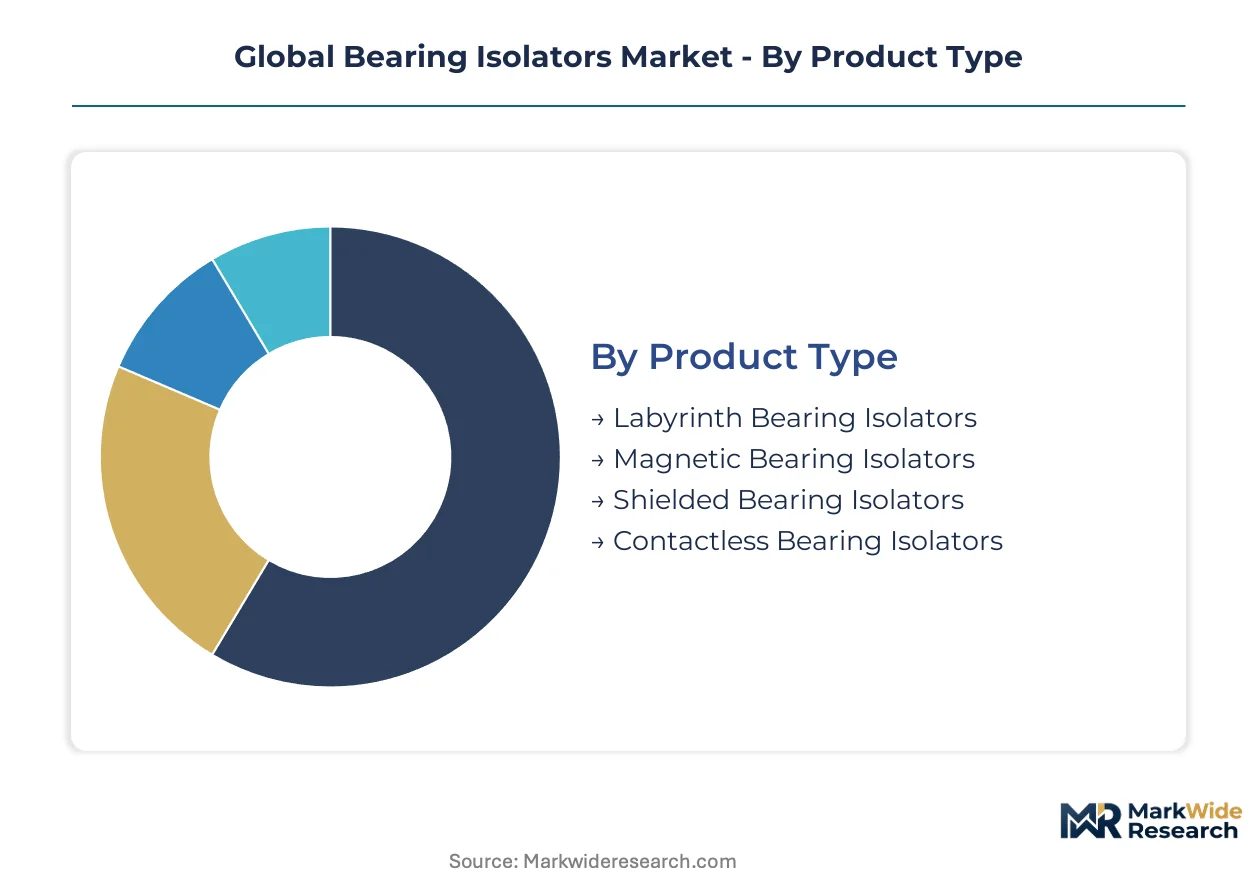
Bearing isolator specification varies sharply by duty cycle, contaminant exposure, and maintenance accessibility across industrial verticals. Segmentation reveals where labyrinth designs dominate installed base economics versus where magnetic architectures command premium positioning in turbomachinery.
Product Type:
Labyrinth designs concentrate manufacturing in Germany and the United States for domestic OEM supply, while magnetic isolators flow through export channels serving Asian power generation markets.
- Labyrinth Bearing Isolators:Precision-machined spiral grooves create tortuous paths that exclude particulates without contacting rotating shafts. Demand clusters in German chemical corridors where REACH-mandated material upgrades are accelerating retrofit cycles in continuous-duty pump applications.
- Magnetic Bearing Isolators:Flux-field architectures suspend sealing faces without mechanical contact, eliminating wear entirely. Japanese and South Korean power utilities specify these for gas turbine generators operating above 25 m/s where maintenance access requires multi-year intervals.
- Shielded Bearing Isolators:Metallic shields provide cost-effective contamination control in moderate-speed gearboxes across Indian textile manufacturing.
- Contactless Bearing Isolators:Air-gap or fluid-film designs serve food processing washdown environments requiring IP69K ratings without elastomer degradation.
Labyrinth bearing isolators hold the largest share; momentum sits with magnetic designs in high-speed turbomachinery.
Technology:
Cost tier stratification separates commodity sealing from precision-engineered magnetic and hydrodynamic systems commanding 3-5x price multiples.
- Sealing Technology:Conventional elastomeric lip seals and O-ring configurations retain lubricant through radial contact pressure. Pulp and paper mills in the US Pacific Northwest specify these for stock pump rebuilds where capital constraints limit specification upgrades.
- Magnetic Repulsion:Permanent magnet arrays maintain consistent gap geometry regardless of thermal expansion or pressure differentials. Saudi Aramco and ADNOC upstream facilities deploy these in remote wellhead compressors where helicopter maintenance costs dominate lifecycle economics.
- Spring-Loaded Mechanism:Mechanical face seals with metallic springs compensate for wear in refinery hydrocracking pumps.
- Hydrodynamic Seals:Pressure-generated fluid films support oil and gas subsea applications.
- Mechanical Face Seals:Paired lapped surfaces handle abrasive slurries in Brazilian mining operations.
Sealing technology commands volume leadership; magnetic repulsion climbs fastest in critical turbomachinery.
Application:
Customer type fragmentation splits specification authority between maintenance departments seeking aftermarket interchangeability and OEM engineering teams designing integrated systems.
- Pumps:ANSI and API process pumps represent the largest installed base for bearing isolator retrofits. German BASF and Bayer facilities are standardizing on labyrinth-magnetic hybrid designs to satisfy EU Green Deal efficiency mandates while maintaining parts commonality.
- Compressors:Centrifugal and reciprocating compression equipment demands zero-leakage sealing for EPA emissions compliance. US Gulf Coast petrochemical complexes specify fluoropolymer-faced isolators for fugitive methane control under tightening state-level regulations.
- Turbines:Steam and gas turbine generators require thermal stability across 200°C+ bearing housings.
- Gearboxes:Industrial gear reducers prioritize cost-effective shielded configurations.
- Industrial Fans:Material handling and HVAC applications tolerate moderate contamination exposure.
Pumps anchor specification volume; compressors drive fastest technology upgrading.
End User:
Application maturity separates early-adopting power generation from price-sensitive pulp and paper sectors lagging in predictive maintenance adoption.
- Power Generation Facilities:Combined-cycle gas turbine and nuclear plants specify magnetic isolators for decade-long maintenance intervals. EDF in France and Kansai Electric in Japan have anchored long-term supply agreements with integrated bearing-isolator system suppliers.
- Oil & Gas Processors:Upstream extraction and downstream refining operations prioritize hydrodynamic expertise for remote environments. Shell's Permian Basin operations and Equinor's Johan Sverdrup field specify zero-contact designs where platform access costs exceed equipment premiums.
- Chemical Manufacturing Plants:Corrosive process streams demand ceramic and fluoropolymer material transitions.
- Pulp & Paper Mills:Stock preparation and dryer sections balance contamination resistance with budget constraints.
- Food Processing Plants:USDA and FDA sanitary requirements drive dual 3-A and IP69K certification demand.
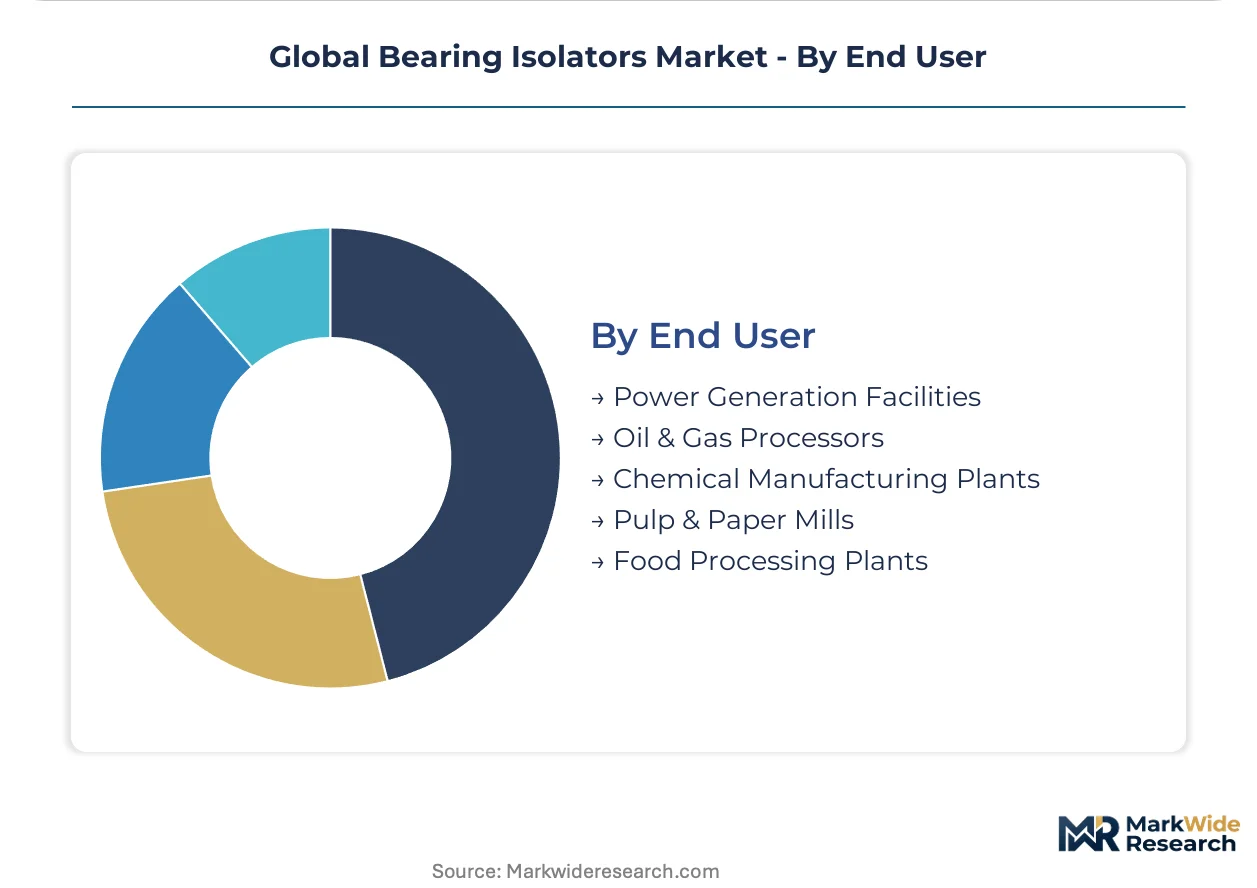
Power generation facilities hold the largest specification share; chemical manufacturing plants exhibit steepest expansion trajectory under EU regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's dominance in precision-machined bearing isolator supply. Port infrastructure at Rotterdam and Antwerp channels fluoropolymer feedstocks into European chemical manufacturing clusters.
Germany
BASF Ludwigshafen and Bayer Leverkusen facilities drive specification upgrades for labyrinth-magnetic hybrid designs. EU Green Deal machinery efficiency mandates tighten seal performance requirements through ECHA-enforced REACH substance restrictions. The Rhine-Neckar industrial corridor concentrates OEM retrofit demand from pump and motor manufacturers.
United States
EPA emissions standards for process equipment leakage accelerate fluoropolymer-faced isolator adoption in Gulf Coast petrochemical complexes. FDA sanitary design requirements create dual-certification demand for food processing facilities in California's Central Valley. Permian Basin upstream operations prioritize zero-contact designs where helicopter maintenance costs dominate lifecycle economics.
Japan
Combined-cycle gas turbine generators above 25 m/s surface speeds specify magnetic bearing isolators for decade-long maintenance intervals. METI efficiency standards for rotating electrical machines rewrite thermal specifications in procurement cycles. Kansai Electric anchors long-term supply agreements with integrated system suppliers across Osaka-Kobe industrial zones.
China
MIIT dual carbon goals and GB standards for industrial energy efficiency force material transitions in Yangtze River Delta pump manufacturing. State-owned power utilities specify magnetic isolators for remote western coal and gas turbine installations. Sinopec refineries in Shandong Province deploy hydrodynamic seals under tightening provincial emissions controls.
Saudi Arabia
SFDA process safety regulations and ADNOC upstream requirements prioritize zero-contact isolators in remote wellhead compressors. NEOM northwest development zone specifications mandate predictive maintenance architectures from project inception. Eastern Province offshore platforms specify magnetic repulsion designs where platform access costs exceed equipment premiums.
Global Bearing Isolators Market Competitive Landscape
Concentration sits with integrated bearing system suppliers and precision-machining specialists. The vendor base stratifies across three tiers: multinational industrial conglomerates with captive sealing divisions, mid-cap specialists focused on labyrinth groove manufacturing, and regional fabricators serving aftermarket replacement cycles. Two dominant competitive moves anchor strategic positioning: long-term supply agreements with power generation OEMs spanning decade-long maintenance intervals, and backward integration into fluoropolymer compound formulation to stabilize input cost exposure.
Among integrated industrial conglomerates, Timken Company and Parker Hannifin Corporation exemplify the bearing-isolator system supplier archetype. AESSEAL occupies a position within the precision-machining specialist tier. These three entities represent distinct geographic and capability concentrations: Timken anchors North American power generation supply chains, Parker Hannifin leverages hydrodynamic expertise in oil and gas upstream applications, and AESSEAL dominates aftermarket technical service networks across European chemical corridors. Each exemplifies how specification authority migration from maintenance departments to OEM engineering teams rewards integrated system offerings over component sales.
| Leading Market Players |
|---|
| Timken Company |
| Flowserve Corporation |
| Parker Hannifin Corporation |
| AESSEAL |
| John Crane |
| Garlock Sealing Technologies |
| Inpro/Seal |
| SKF Group |
| EagleBurgmann |
| Others |
Supply & Pricing Matrix
Capacity utilization at precision-machining centers in Germany's Rhine-Neckar corridor anchors price floors for labyrinth bearing isolators, while fluoropolymer compound formulation scale in the United States creates tiered sourcing economics that fragment procurement strategies across OEM and aftermarket channels.
Pricing Analysis
Volume-discount tiering structures separate power generation OEMs anchoring decade-long supply agreements from spot-market maintenance buyers in pulp and paper sectors. Three-tier pricing stratifies across magnetic repulsion systems, precision-machined labyrinth designs, and shielded economy configurations. Price differentiation rests on IEC 60034-30-1 efficiency certification grade and REACH-compliant material composition. Cost compression in standard labyrinth tiers intensifies because competing industrial sectors absorb CNC programming talent from the precision-machining pool. Chemical manufacturing plants exhibit lowest price sensitivity due to EU Green Deal compliance deadlines, while Indian textile operations prioritize cost-effective shielded configurations.
Supply Chain Analysis
Rotterdam-Antwerp port infrastructure underwrites fluoropolymer feedstock distribution into European chemical manufacturing clusters. Precision-machined labyrinth groove production concentrates in Germany and the United States, while magnetic flux field engineering capabilities cluster in Japan and South Korea. Raw material dependencies draw from PTFE resin supply, rare-earth magnet arrays, and advanced ceramic substrates. Single-source vulnerability sits with specialized CNC programming capabilities for spiral groove geometry. Distribution runs through OEM direct supply agreements and aftermarket technical service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as predictive maintenance adoption migrates specification authority from maintenance departments to capital equipment engineering teams, compressing replacement cycles and expanding procurement windows for integrated bearing-isolator systems.
For Market Incumbents: Shield aftermarket service revenue streams by anchoring long-term supply agreements with power generation OEMs seeking lifecycle cost reduction. Deepen backward integration into fluoropolymer compound formulation to stabilize input cost exposure against REACH-mandated material transitions. Prioritize certification investment for simultaneous 3-A hygienic and IP69K validation to capture food processing specification share. For New Entrants and Emerging Players: Differentiate on hydrodynamic seal expertise for oil and gas upstream applications where remote maintenance access constraints command premium positioning. Target chemical manufacturing corridors in Germany's industrial heartland where EU Green Deal machinery efficiency mandates are accelerating retrofit cycles. Pursue white-space in magnetic bearing isolator specification for Asian power generation markets through export channel partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-machining specialists with captive aftermarket technical service networks across European chemical corridors. Long-term viability over the projection horizon favors integrated bearing-isolator system suppliers with OEM engineering team relationships. Watch IEC 60034-30-1 efficiency class upgrade procurement cycles as the inflection signal for next-generation isolator design demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | REACH substance restrictions force material transitions toward captive supply of ceramic and fluoropolymer compositions. |
| Long-term Supply Agreement with Power Generation OEMs | EDF and Kansai Electric anchor decade-spanning contracts for magnetic isolator systems in combined-cycle gas turbines. |
| Dual-Certification Investment for Food Processing | Simultaneous 3-A hygienic and IP69K validation captures specification share in California Central Valley processing facilities. |
| Predictive Maintenance Architecture Partnership | NEOM development zone mandates condition-monitoring integration from project inception in Saudi Eastern Province. |
| Hydrodynamic Expertise Acquisition | Remote wellhead compressor applications at ADNOC upstream facilities prioritize zero-contact designs where helicopter maintenance costs dominate. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across chemical manufacturing and power generation facilities; and secondary validation through customs and trade data, SEC filings, IEC standard documentation, and ECHA REACH substance restriction databases. Bottom-up equipment installation counts triangulated against top-down market sizing from industrial production indices.
Across the analysis window, the forecasting framework modeled product type segmentation by labyrinth versus magnetic versus shielded architectures, technology tier by sealing versus magnetic repulsion versus hydrodynamic systems, application vertical by pumps versus compressors versus turbines, and end-user industry by power generation versus chemical manufacturing versus oil and gas. CAGRs derived from equipment replacement cycle analysis and regulatory mandate compliance timelines. Industry-specific inputs included EU Green Deal machinery efficiency mandate enforcement schedules and EPA emissions standard leakage thresholds.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or stable fluoropolymer feedstock pricing would require recalibration. Forecasts reflect documented assumptions about specification authority migration velocity and REACH material transition timelines. Practitioners should keep alternative scenarios live as IEC efficiency class upgrade procurement cycles and Asian power generation capacity additions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Lifts Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Speed Bump Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Timing Gear Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Diesel Oxidation Catalyst Market