
 Mexico Automotive Sunroof Market | 2026-2036
Mexico Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Sunroof Market Foresight
Querétaro-based sunroof component suppliers is decoupling from legacy metal-frame sourcing as polycarbonate glazing capacity expands across central Mexico. Webasto SE leverages its established Puebla manufacturing footprint to anchor panoramic roof supply for German OEM platforms assembled locally. Magna International competes through integrated sealing and mechatronics expertise that sustains factory-installed contracts with Detroit-based automakers operating maquiladora plants.
An automotive sunroof is a movable or fixed transparent or opaque panel installed in a vehicle roof, typically constructed from tempered glass, polycarbonate resin, or aluminum composites with integrated drainage channels, anti-pinch sensors, and UV-filtering interlayers, designed to admit natural light, enhance cabin ventilation, or expand perceived interior volume. Glass technology dominates factory-installed revenue due to scratch resistance and acoustic performance demanded by premium OEM specifications, while polycarbonate material captures retrofit and aftermarket growth through weight reduction advantages that support fuel economy targets. Electric technology leads installation type value pools as OEMs phase out manual crank mechanisms, though solar-integrated variants remain nascent pending thermal management validation in Mexico's high-altitude climate zones.
NOM-001-SCFI standards administered by Mexico's Secretariat of Economy govern electrical system safety for powered sunroof mechanisms, compelling suppliers to certify motor torque-limiting and obstruction-detection firmware. PROFEPA environmental guidelines restrict volatile organic compound emissions from adhesive bonding processes used in glass-to-frame assembly, pushing manufacturers toward water-based urethane systems. Stakeholders must monitor evolving NOM-020-ENER energy efficiency regulations that could mandate solar-reflective glazing properties on sunroof-equipped vehicles sold in Mexican territory.
Market Dynamics
Polycarbonate glazing adoption is fragmenting supplier hierarchies across Mexico's central automotive corridor as OEMs pursue weight reduction targets without sacrificing panoramic roof penetration rates.
Growth Catalysts
- NOM-001-SCFI electrical safety mandates:The Secretariat of Economy's torque-limiting and obstruction-detection requirements for powered sunroof mechanisms are accelerating factory-installed electric sunroof penetration across SUV and luxury sedan assembly lines.
- Querétaro polycarbonate capacity expansion:Localized resin processing infrastructure is reducing import dependency for lightweight glazing substrates serving fuel economy-focused OEM platforms.
- Aguascalientes-Guanajuato production clustering:Premium interior content scaling at these OEM assembly plants is concentrating demand for advanced sunroof systems with integrated mechatronics and acoustic interlayers.
Market Restraints
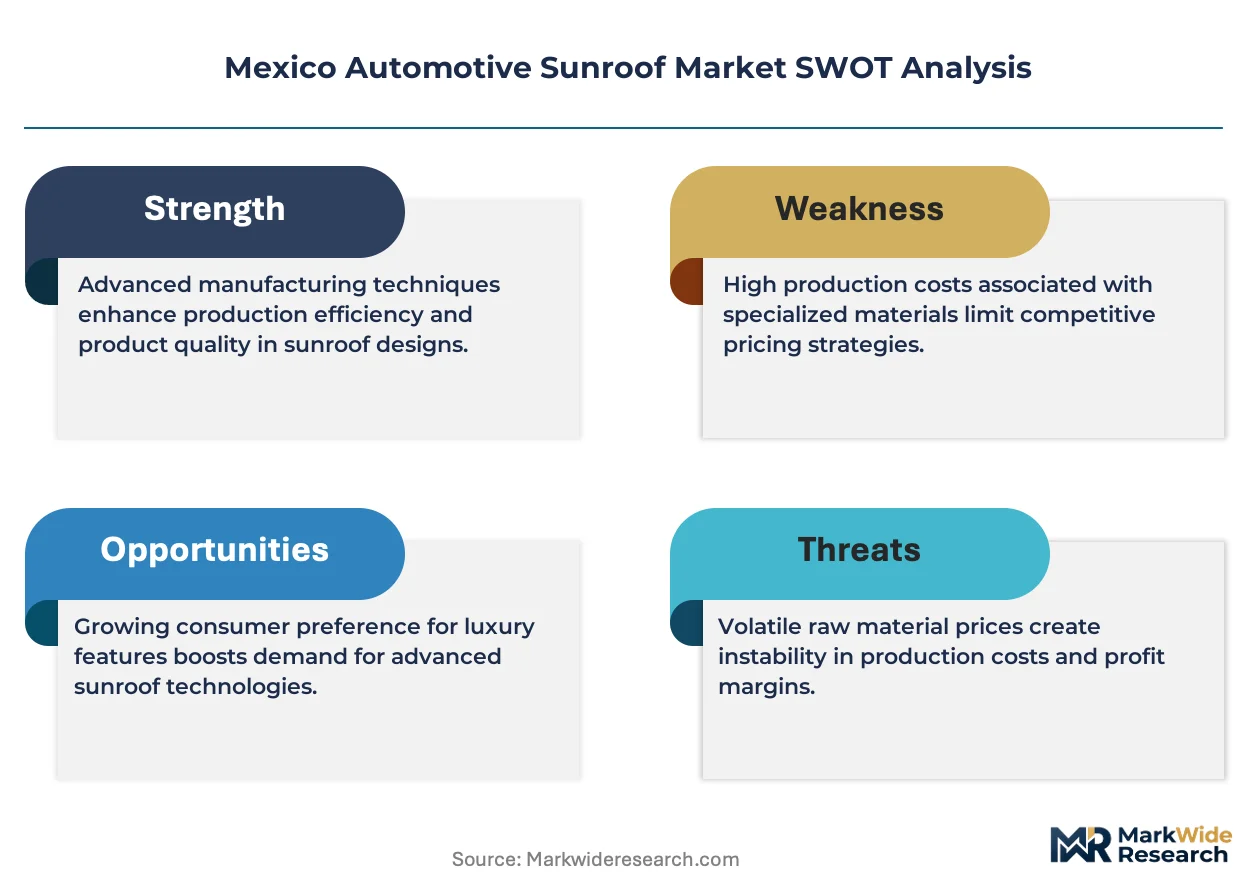
- Petrochemical feedstock volatility:Polycarbonate resin pricing sensitivity to global propylene and bisphenol-A markets compresses margin predictability for glazing component suppliers.
- Webasto-Magna duopoly concentration:Factory-installed contract concentration between these two anchor suppliers limits pricing leverage for tier-two sealing and drainage subsystem vendors.
- Solar-integrated thermal validation gaps:High-altitude climate performance uncertainty around photovoltaic-embedded glazing delays OEM adoption timelines pending extended field testing.
Strategic Opportunities
- Baja California aftermarket retrofit channel:Cross-border vehicle personalization demand from US consumers creates unmet service capacity for polycarbonate sunroof installations in Tijuana-Ensenada corridor workshops.
- NOM-020-ENER energy efficiency trajectory:Anticipated solar-reflective glazing mandates for sunroof-equipped vehicles would mandate technology refresh cycles creating first-mover advantage for low-emissivity coating specialists.
- Water-based urethane adhesive convergence:PROFEPA VOC emission restrictions on legacy bonding chemistry is unifying environmental compliance with acoustic performance engineering for frame-to-glass assembly processes.
Industry Challenges
- Mechatronics firmware certification timelines:NOM-001-SCFI motor control algorithm validation protocols extend product development cycles by 8-14 months for obstruction-detection system suppliers.
- Drainage channel integration complexity:Legacy metal-frame tooling retooling requirements for polycarbonate-compatible sealing geometries strain capital allocation at tier-two stamping operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Sunroof Market |
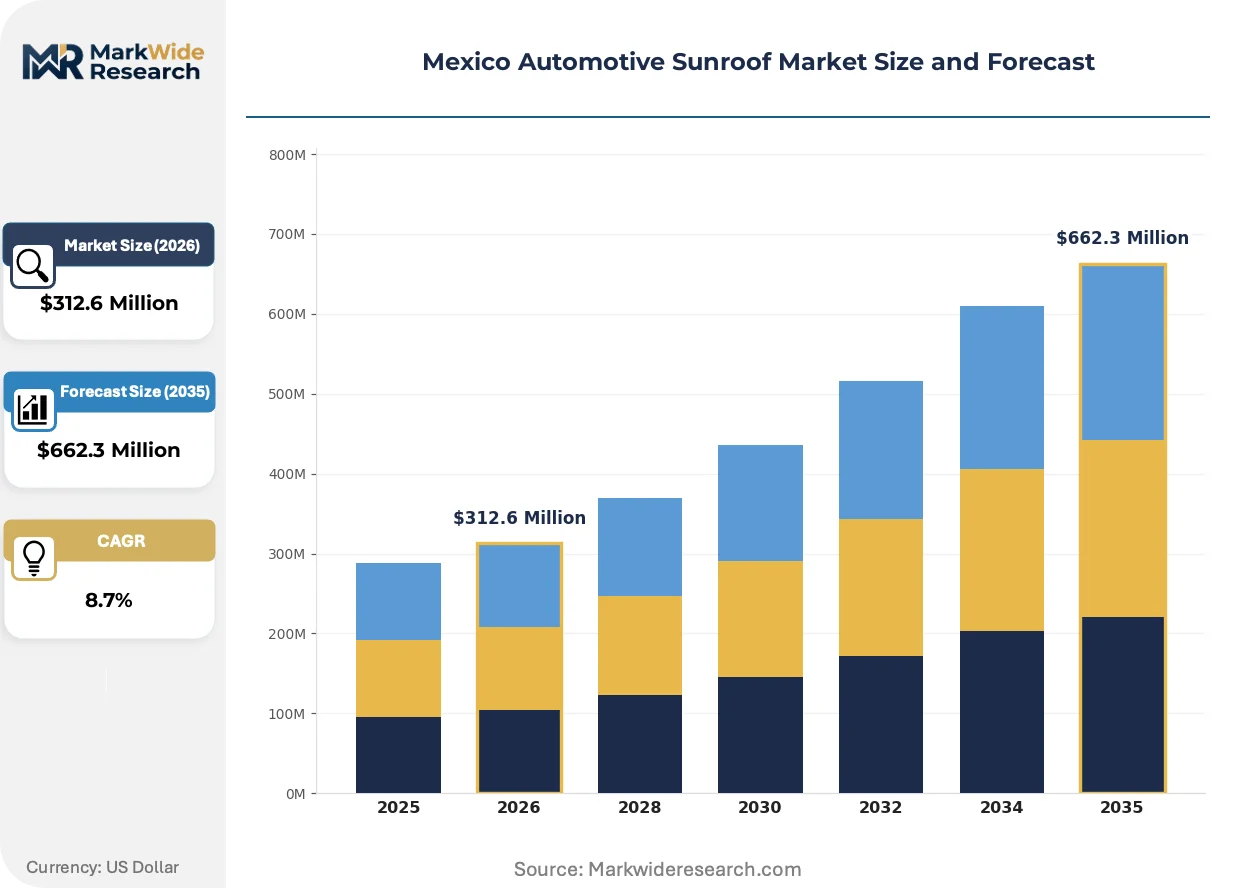
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Material: Glass, Fiberglass, Polycarbonate, Metal Technology: Electric, Manual, Panoramic, Solar Installation Type: Factory Installed, Aftermarket, Custom, Retrofit |
| Companies Covered | Aisin Seiki Co. Ltd., CIE Automotive SA, Donghee Industrial Co. Ltd., Inalfa Roof Systems Group BV, Webasto SE, Magna International, Yachiyo Industry, Inteva Products, Johnan America Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Sunroof Market Shifts & Advancements
Material substitution and regulatory compression are simultaneously reconfiguring supplier capabilities and OEM specification patterns across Mexico's sunroof value chain.
Polycarbonate resin formulations with UV-stabilized interlayers are unifying weight reduction targets with acoustic performance requirements previously exclusive to tempered glass constructions. German OEM platforms assembled at Puebla operations are adopting these substrates at accelerated specification rates. This material transition is unifying previously separate supplier tiers into direct competition for factory-installed contracts.
PROFEPA environmental guidelines restricting volatile organic compound emissions from adhesive bonding processes are compelling manufacturers to abandon solvent-based urethane systems. Water-based alternatives now dominate new equipment qualification programs at major assembly plants. Glass-to-frame subsystem suppliers serving the Aguascalientes corridor are restructuring production lines to meet these bonding chemistry requirements.
Fleet procurement managers at Detroit-based automakers operating maquiladora plants are compressing supplier qualification cycles to match accelerated platform refresh timelines. Traditional three-year vendor validation protocols are contracting toward 18-month windows. This behavioral shift is most visible in Guanajuato state where integrated sealing-mechanism suppliers face compressed testing schedules for anti-pinch sensor integration.
Mexico Automotive Sunroof Market Segmentation
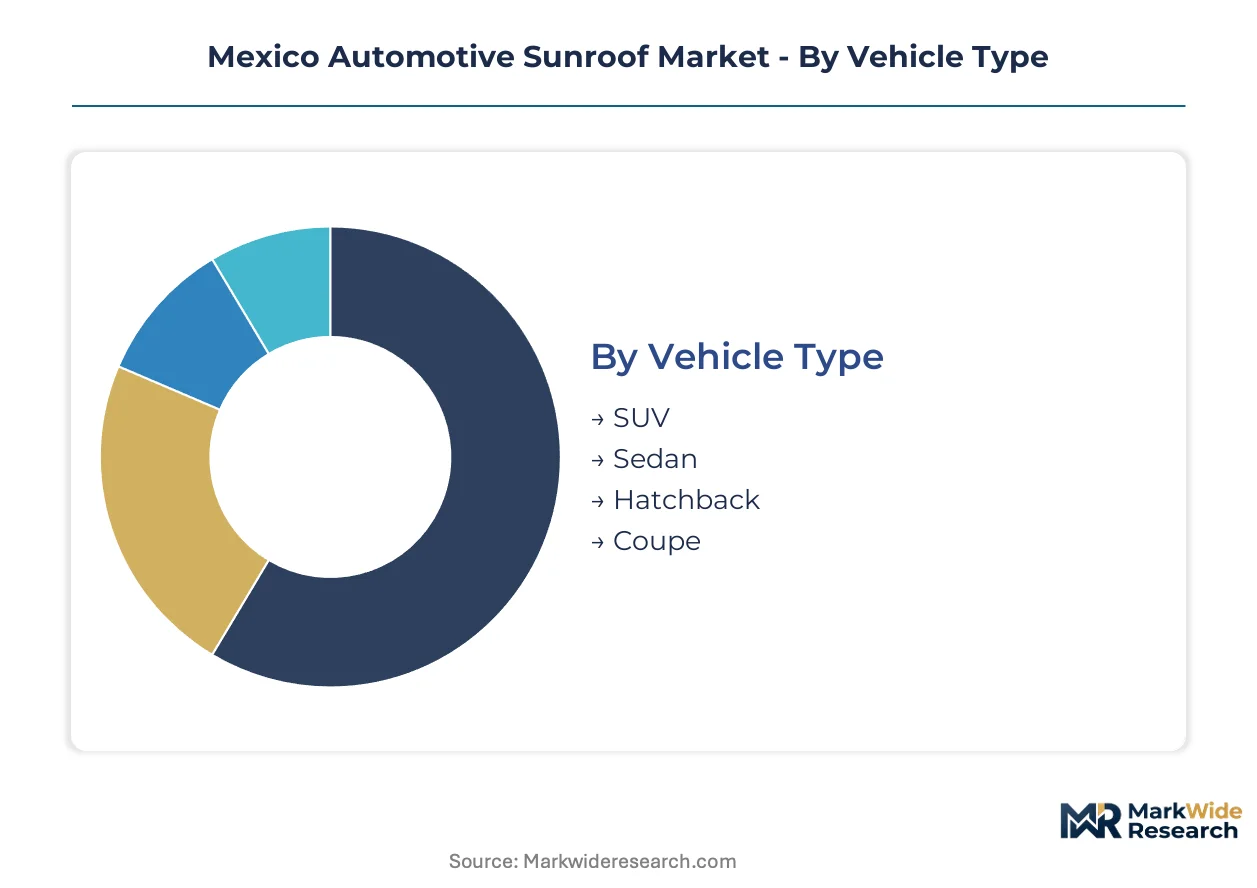
Segmentation in Mexico's automotive sunroof market reveals how NOM-001-SCFI electrical safety mandates and PROFEPA environmental guidelines differentially burden each category. Suppliers must align certification pathways with specific material, technology, and installation requirements to secure factory-installed contracts at Aguascalientes and Guanajuato assembly plants.
Vehicle Type:
SUV and sedan platforms carry distinct certification loads under Mexico's electrical safety framework, with panoramic roof penetration rates driving compliance investment priorities.
- SUV:Tempered glass panoramic systems dominate this segment, with factory-installed electric mechanisms requiring NOM-001-SCFI motor torque-limiting certification. Demand concentrates at German OEM platforms assembled in Puebla and Detroit-based automaker operations in Guanajuato, where premium interior content scaling mandates acoustic interlayer specifications.
- Sedan:Polycarbonate glazing adoption accelerates in luxury sedan production lines serving North American export channels. PROFEPA VOC restrictions on adhesive bonding processes compel water-based urethane system qualification at Querétaro-based component suppliers.
- Hatchback:Compact factory-installed configurations prioritize weight reduction targets through reduced glass thickness specifications.
- Coupe:Limited-volume specialty applications concentrate at custom retrofit workshops in the Tijuana-Ensenada corridor.
SUV sits at the top of the volume ranking, with Sedan climbing the fastest.
Material:
Raw material selection directly determines environmental compliance pathways and acoustic performance engineering requirements across Mexico's central automotive corridor.
- Glass:Tempered constructions with UV-filtering interlayers retain factory-installed revenue leadership due to scratch resistance specifications demanded by premium OEM platforms. German automakers at Puebla operations specify these substrates for panoramic roof applications requiring acoustic dampening.
- Polycarbonate:UV-stabilized resin formulations unify weight reduction targets with fuel economy mandates. Localized capacity expansion across Querétaro reduces import dependency for bisphenol-A feedstock, though petrochemical pricing volatility compresses margin predictability.
- Fiberglass:Niche aftermarket applications in Baja California retrofit channels serve cross-border vehicle personalization demand.
- Metal:Legacy aluminum composite frames face retooling pressure as polycarbonate-compatible sealing geometries displace traditional stamping operations.
Glass captures the highest factory-installed value, while Polycarbonate expands most quickly through fuel economy-focused OEM platforms.
Technology:
Electrification mandates and thermal management validation gaps create divergent product development timelines across powered sunroof categories.
- Electric:Powered mechanisms with obstruction-detection firmware dominate installation type value pools as OEMs phase out manual crank systems. NOM-001-SCFI certification protocols extend development cycles by 8-14 months for motor control algorithm validation.
- Panoramic:Multi-panel glass configurations concentrate demand among SUV and luxury sedan production lines. Webasto SE leverages its Puebla manufacturing footprint to anchor supply for German OEM platforms requiring integrated mechatronics.
- Manual:Crank-operated systems retreat to economy vehicle segments and aftermarket replacement channels.
- Solar:Photovoltaic-embedded glazing remains nascent pending thermal management validation in Mexico's high-altitude climate zones.
Electric leads technology value capture, with Panoramic gaining share fastest through premium platform specification rates.
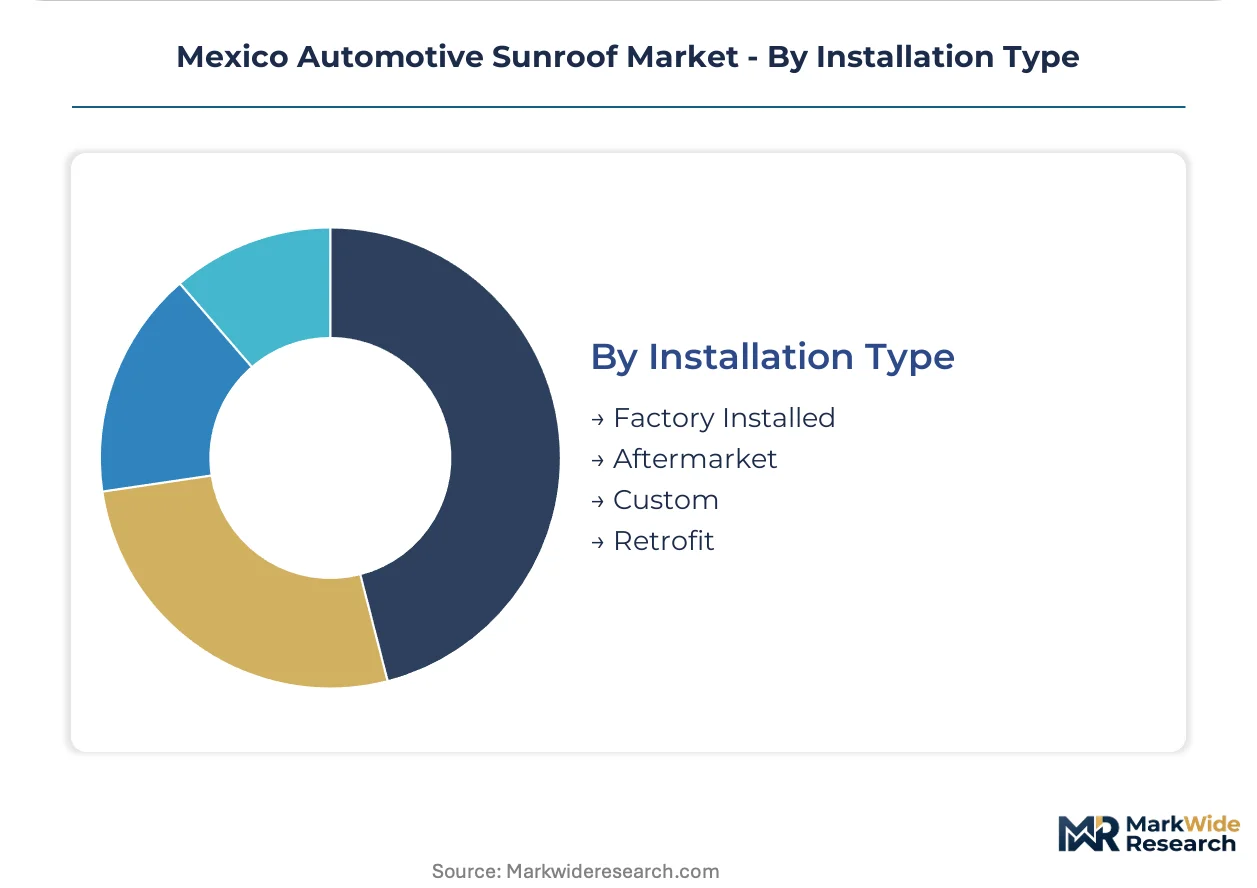
Installation Type:
Channel selection determines regulatory exposure and margin structure, with factory-installed contracts commanding integrated sealing-mechanism qualification.
- Factory Installed:OEM assembly plant contracts require Magna International's integrated sealing and mechatronics expertise for Detroit-based automaker maquiladora operations. Compressed supplier qualification cycles—contracting from three-year to 18-month windows—strain anti-pinch sensor integration timelines at Guanajuato sealing subsystem vendors.
- Aftermarket:Polycarbonate retrofit installations capture cross-border demand from US consumers seeking vehicle personalization services. Tijuana-Ensenada corridor workshops face unmet service capacity for lightweight glazing substrate installations.
- Custom:Specialty configurations serve limited-production coupe platforms with non-standard roof aperture geometries.
- Retrofit:Existing vehicle modification demand concentrates in Baja California border zones.
Factory Installed commands the value pool, with Aftermarket showing steepest expansion trajectory through polycarbonate retrofit adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward Mexico's central automotive corridor exploits a cost-of-compliance gap against US regulatory stringency, positioning assembly plants in Aguascalientes and Guanajuato as primary beneficiaries of NOM-001-SCFI electrical safety harmonization with North American technical standards.
Aguascalientes
German OEM assembly operations drive tempered glass panoramic demand for premium SUV platforms serving North American export channels. NOM-001-SCFI torque-limiting certification requirements concentrate supplier investment at factory-installed sealing subsystem vendors. The state's automotive cluster anchors Webasto SE manufacturing footprint for integrated mechatronics supply.
Guanajuato
Detroit-based automaker maquiladora operations scale luxury sedan production with polycarbonate glazing adoption accelerating through fuel economy mandates. PROFEPA VOC restrictions on adhesive bonding compel water-based urethane qualification at tier-two component suppliers. Silao-León industrial corridor hosts compressed 18-month supplier validation cycles for anti-pinch sensor integration.
Querétaro
Localized polycarbonate resin processing infrastructure reduces import dependency for bisphenol-A feedstock serving lightweight glazing specifications. The Secretariat of Economy's energy efficiency trajectory signals future NOM-020-ENER solar-reflective glazing mandates. El Marqués aerospace-automotive supplier overlap transfers precision sealing expertise to sunroof frame assembly operations.
Puebla
Volkswagen Group manufacturing complex sustains highest-volume German OEM sunroof specification rates in Mexican territory. NOM-001-SCFI obstruction-detection firmware validation extends product development cycles by 8-14 months for motor control algorithm suppliers. The metropolitan area's historic automotive concentration supports backward integration into glass-to-frame subsystem production.
Baja California
Cross-border aftermarket retrofit demand from US consumers concentrates polycarbonate installation capacity in Tijuana-Ensenada corridor workshops. PROFEPA environmental guidelines apply differentially to service operations versus OEM assembly, creating regulatory arbitrage for vehicle personalization services. Unmet service capacity persists for lightweight glazing substrate modifications.
Mexico Automotive Sunroof Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue polycarbonate-compatible sealing geometries as material substitution fragments legacy supplier hierarchies. Factory-installed contract concentration between two anchor suppliers limits pricing leverage for tier-two vendors. Three archetypes define competitive positioning: integrated mechatronics specialists, regional glazing substrate processors, and cross-border aftermarket service operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification windows compress.
Among Germany-based fabricators, Webasto SE occupies a position exemplifying integrated panoramic roof supply for premium OEM platforms. Magna International represents the North American archetype through sealing and mechatronics expertise sustaining Detroit automaker relationships. Japanese-origin suppliers including Aisin Seiki Co. Ltd. and Yachiyo Industry sit within the precision component tier, anchoring factory-installed contracts through motor control and frame assembly specialization.
| Leading Market Players |
|---|
| Aisin Seiki Co. Ltd. |
| CIE Automotive SA |
| Donghee Industrial Co. Ltd. |
| Inalfa Roof Systems Group BV |
| Webasto SE |
| Magna International |
| Yachiyo Industry |
| Inteva Products |
| Johnan America Inc. |
| Others |
Supply & Pricing Matrix
Factory-installed versus aftermarket channel bifurcation creates divergent margin architectures across Mexico's sunroof value chain, with NOM-001-SCFI certification tiers compressing pricing power at the premium end while polycarbonate retrofit demand sustains looser price discipline in Baja California service workshops. This tier divergence manifests in supply chain configurations: certified electric mechanism suppliers concentrate around Aguascalientes-Guanajuato OEM corridors, whereas lightweight glazing substrate distributors fragment across unaffiliated Tijuana-Ensenada installers.
Pricing Analysis
Distributor margins for aftermarket polycarbonate installations run substantially wider than direct-to-OEM contract discounts, reflecting unmet service capacity in Baja California border zones. Three-tier pricing structure across premium, standard, and economy levels separates NOM-001-SCFI-certified electric panoramic systems from manual crank configurations and uncertified retrofit substrates. Cost compression in polycarbonate resin feedstock is intensifying because propylene and bisphenol-A pricing volatility, squeezing margin predictability for Querétaro-based glazing processors. Detroit-based automaker procurement teams demonstrate lowest price sensitivity, prioritizing integrated sealing-mechanism reliability over per-unit cost negotiation.
Supply Chain Analysis
Workforce availability constraints in central Mexico's automotive corridor—particularly precision mechatronics technicians around Puebla and Silao-León—shape supplier location decisions more than raw material proximity. Geographic supply concentration centers on Germany for integrated panoramic roof systems, Japan for motor control algorithms, and domestic Querétaro operations for UV-stabilized polycarbonate resin. Raw material dependencies draw from South Korean bisphenol-A processing, US adhesive chemistry for water-based urethane systems, and German sealing component engineering. Single-source vulnerability around Webasto-Magna duopoly concentration limits tier-two vendor pricing leverage. Distribution runs through OEM assembly plant direct delivery for factory-installed contracts, with aftermarket channels fragmenting across unaffiliated Baja California workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NOM-001-SCFI electrical safety mandates mechanically expand factory-installed electric sunroof penetration, converting compliance burden into demand generation across SUV and luxury sedan assembly lines.
For Market Incumbents: Anticipate polycarbonate glazing substitution disrupting legacy glass-dominant specification patterns at German OEM platforms, eroding acoustic performance differentiation moats. Defensive consolidation moves should prioritize backward integration into Querétaro resin processing capacity and accelerated NOM-020-ENER solar-reflective glazing R&D to capture anticipated energy efficiency mandate cycles. Certification investment in water-based urethane bonding systems aligns PROFEPA compliance with acoustic engineering requirements. For New Entrants and Emerging Players: Water-based adhesive chemistry expertise offers a technology-first wedge into tier-two sealing subsystem qualification at Guanajuato stamping operations retooling for polycarbonate-compatible geometries. White-space targets include Baja California aftermarket retrofit capacity expansion for US cross-border personalization demand and NOM-001-SCFI motor control algorithm validation services compressing 18-month supplier cycles. Go-to-market positioning should emphasize thermal management validation capabilities for nascent solar-integrated glazing segments. For Investors and Strategic Acquirers: Consolidation pressure builds where polycarbonate capacity expansion fragments legacy metal-frame supplier hierarchies and PROFEPA environmental guidelines accelerate water-based urethane adoption curves. Long-term viability favors integrated mechatronics specialists with captive sealing expertise and NOM-001-SCFI certification track records over pure-play glazing substrate processors. Acquisition target archetypes include Querétaro-based precision frame assemblers with aerospace-automotive supplier overlap. Signal to watch: NOM-020-ENER draft regulation release timing, which would mandate technology refresh cycles and first-mover advantage capture for low-emissivity coating specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Polycarbonate Capacity Expansion | Querétaro resin localization reduces import dependency for bisphenol-A feedstock serving fuel economy mandates. |
| NOM-001-SCFI Certification Investment | Obstruction-detection firmware validation extends development cycles but secures factory-installed contract access. |
| Water-Based Urethane Transition | PROFEPA VOC restrictions unify environmental compliance with acoustic performance engineering requirements. |
| Aftermarket Retrofit Channel Development | Baja California workshop capacity addresses unmet US cross-border vehicle personalization demand. |
| Solar-Reflective Glazing R&D | NOM-020-ENER trajectory anticipation creates first-mover positioning for anticipated energy efficiency mandates. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement managers, aftermarket distributors in Baja California, and PROFEPA environmental compliance officers combined with secondary validation from vehicle registration databases, customs trade records for polycarbonate resin imports, NOM-001-SCFI certification filings, and SEC 10-K disclosures from listed automotive suppliers. Triangulation across these sources calibrated volume and value estimates.
Historical trendline analysis of panoramic roof penetration rates by vehicle class informed projection modeling across the analysis window. Segmentation dimensions modeled include vehicle type, material substrate, technology mechanism, and installation channel, with additional granularity on OEM tier and regional production cluster. CAGRs derived from fitted growth curves applied to baseline production volumes, incorporating NOM-001-SCFI mandate phase-in schedules and polycarbonate adoption elasticity parameters as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, NOM-020-ENER regulatory finalization timing, and solar-integrated thermal validation results in high-altitude climate zones. Forecasts reflect documented assumptions around OEM platform refresh cycles and supplier qualification compression trends. Material deviation in NOM-020-ENER mandate scope, polycarbonate resin pricing trajectories, or Webasto-Magna contract renegotiation patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market