
 France Automotive Adaptive Lighting System Market | 2026-2036
France Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Adaptive Lighting System Market Foresight
Premium OEM buyers is unwinding the historical dominance of mass-market fleet procurement in France's adaptive lighting landscape. Valeo Group leverages its Seville-based manufacturing footprint to anchor European supply of matrix LED modules. HELLA KGaA Hueck & Co competes through specialized sensor fusion architectures that integrate camera and radar inputs. Magneti Marelli SpA dominates software calibration for dynamic bending algorithms across Stellantis vehicle platforms.
France Automotive Adaptive Lighting Systems comprise electronically controlled headlamp assemblies that adjust beam pattern, intensity, and direction in real time based on vehicle speed, steering angle, and detected traffic conditions. These systems typically operate at voltages between 12V and 48V architectures, with matrix LED arrays containing 50-100 individually addressable segments per headlamp unit. Camera-Based technology leads current installations due to mature image processing pipelines and established supply chains, while Glare-Free High Beam configurations represent the fastest-expanding segment as French consumers prioritize night-time driving comfort ratings. OEMs capture the dominant margin pool through bundled platform integration, whereas Aftermarket Installers occupy a narrower niche focused on retrofitting premium systems into existing vehicle fleets.
France's implementation of EU General Safety Regulation mandates intelligent speed assistance and advanced driver distraction warning systems, which indirectly accelerates adaptive lighting integration as part of broader sensor suites. The country's national type approval authority aligns with ECE R48 and ECE R123 standards governing headlamp beam patterns and adaptive front lighting system performance. Stakeholders must monitor how France's transposition of the EU AI Act into national law affects algorithmic decision-making in camera-based beam adjustment systems.
Market Dynamics
EU General Safety Regulation mandates are compressing integration timelines for adaptive lighting systems across French vehicle platforms, forcing Tier-1 suppliers to accelerate sensor fusion architectures ahead of 2026 compliance deadlines.
Growth Catalysts
- ECE R123 Standards:France's alignment with ECE R123 adaptive front lighting system performance requirements creates mandatory upgrade cycles across OEM platforms, ensuring sustained replacement demand.
- Matrix LED Arrays:Camera-based beam segmentation technology enables precise glare-free operation, attracting premium passenger vehicle manufacturers seeking night-time comfort differentiation.
- Île-de-France Cluster:Concentrated automotive R&D infrastructure around Paris-Saclay and Renault's technical centers accelerates prototype-to-production cycles for domestic suppliers.
Market Restraints
- Semiconductor Input Volatility:Indium gallium nitride wafer supply constraints and PMIC shortage exposure create bill-of-materials instability for LED driver modules.
- Single-Source Calibration Risk:Magneti Marelli's captive control over Stellantis dynamic bending algorithms creates platform-lock dependency for competing lighting system integrators.
- EU AI Act Friction:Algorithmic transparency requirements for camera-based beam adjustment systems impose documentation burdens that extend type approval timelines.
Strategic Opportunities
- Rhône-Alpes Manufacturing Corridor:Underpenetrated commercial vehicle adaptive lighting installations around Lyon and Saint-Étienne production hubs offer fleet retrofit potential.
- LiDAR Convergence:Integration of solid-state LiDAR with existing camera-radar sensor stacks enables predictive beam adjustment before oncoming vehicles enter camera detection range.
- Aftermarket Channel Expansion:Specialized installers in Bordeaux and Toulouse are developing mobile calibration services for premium retrofit systems, bypassing traditional dealer networks.
Industry Challenges
- Embedded Software Talent Scarcity:Shortage of engineers proficient in AUTOSAR Adaptive Platform and functional safety ISO 26262 compliance delays algorithm development cycles.
- Legacy 12V Architecture Integration:Older vehicle electrical systems lack the power budget and data bandwidth for full matrix LED operation, forcing costly harness upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Adaptive Lighting System Market |
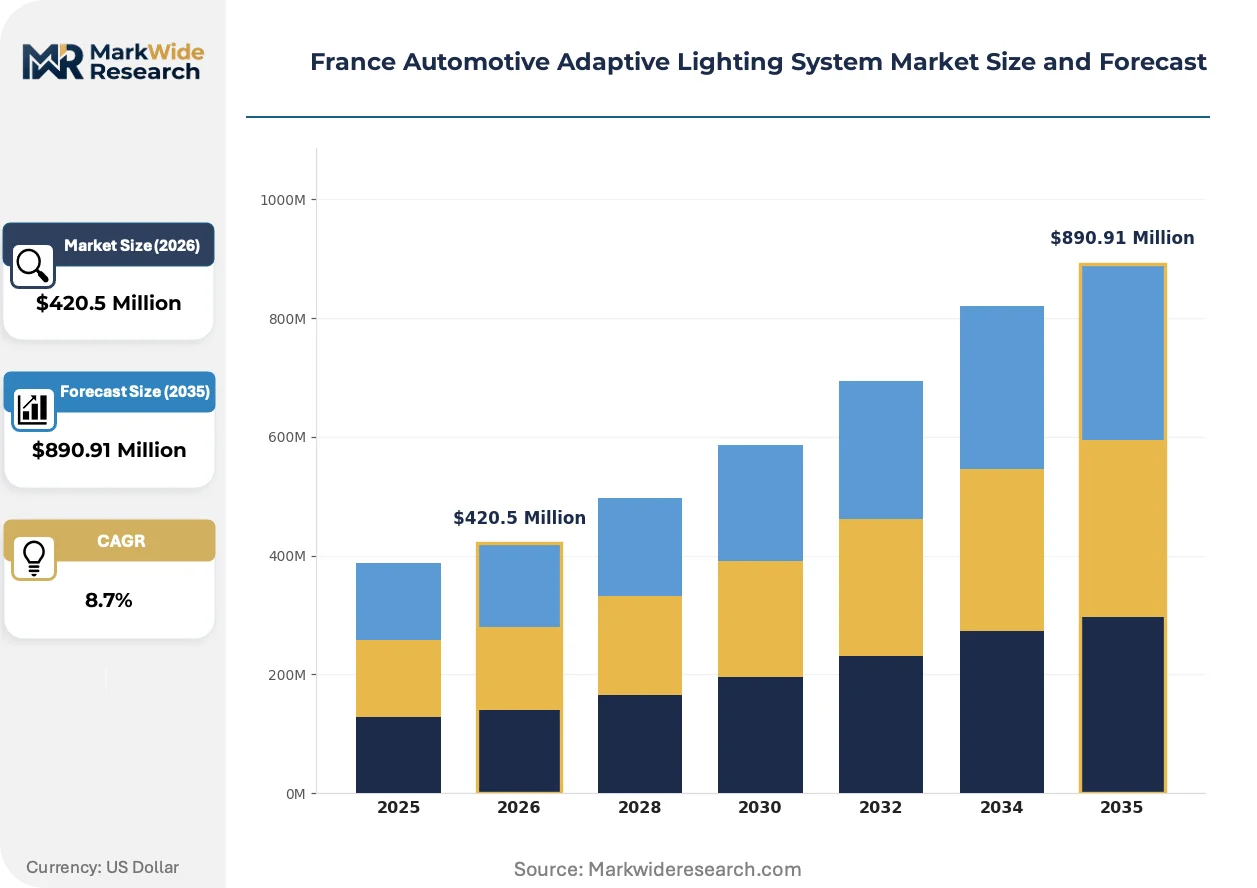
| Market Size in 2026 | $420.5 Million |
| Market Size in 2035 | $890.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
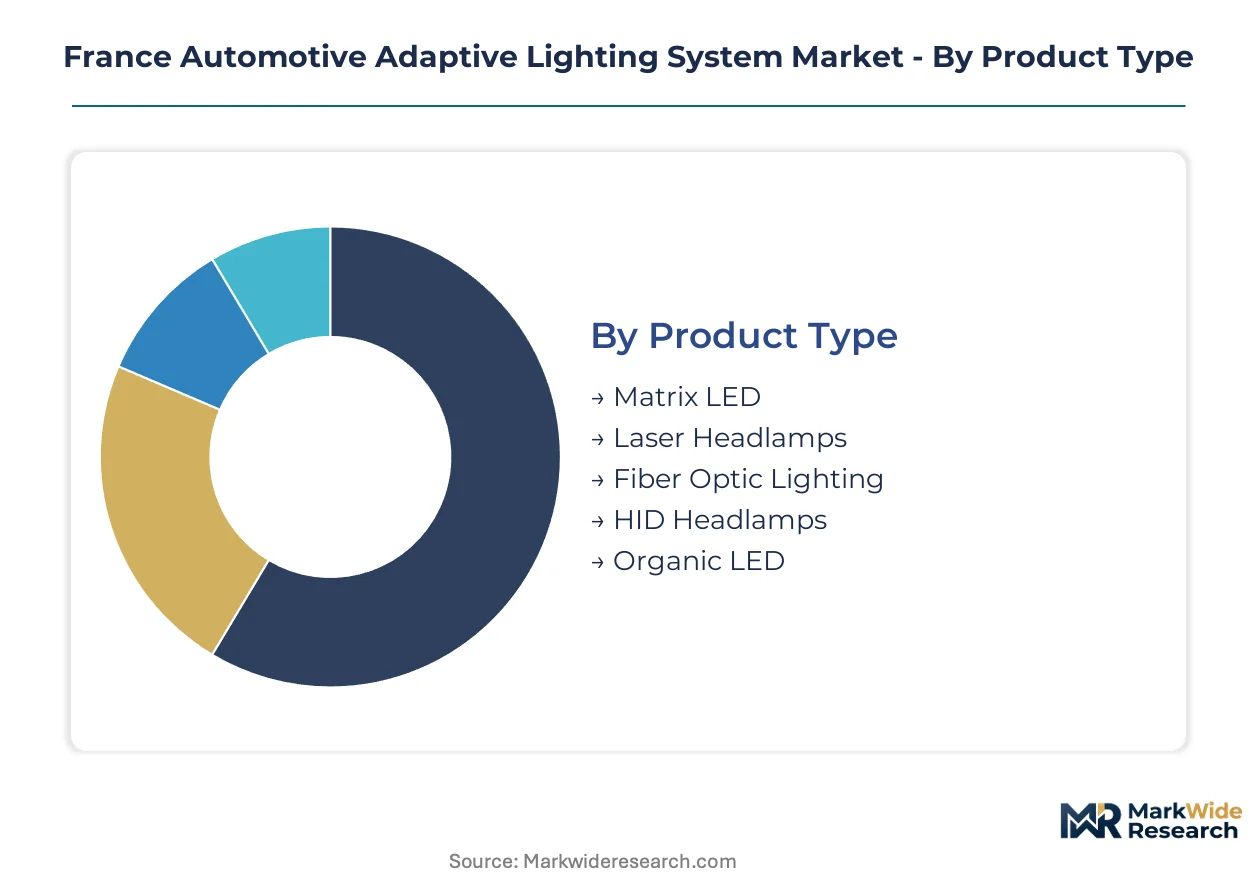
| Segmentation | Product Type: Matrix LED, Laser Headlamps, Fiber Optic Lighting, HID Headlamps, Organic LED Technology: Sensor-Based, Camera-Based, Adaptive Beam, Dynamic Bending, Glare-Free High Beam Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Emergency Vehicles, Construction Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Installers, Vehicle Assemblers |
| Companies Covered | Valeo Group, HELLA KGaA Hueck & Co, Magneti Marelli SpA, Koito Manufacturing Co Ltd, Stanley Electric Co Ltd, Osram Licht AG, Koninklijke Philips N.V., Hyundai Mobis, Texas Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Adaptive Lighting System Market Shifts & Advancements
Digital light processing is actively reshaping beam pattern control in French automotive lighting, replacing mechanical actuators with solid-state solutions that enable faster response times and reduced component count.
Micro-LED pixel arrays containing 25,000 individually addressable elements are displacing conventional matrix LED configurations in flagship vehicle programs. Premium OEM buyers in the Île-de-France cluster specify these systems for their superior resolution and absence of mechanical failure modes. The shift is compressing supplier margins on mid-tier LED module categories while concentrating value capture in semiconductor foundry partnerships.
France's transposition of the EU AI Act into national law through ANSM and CNIL guidance imposes algorithmic audit requirements on camera-based beam adjustment systems. Manufacturers must now document decision pathways for glare-free zone activation, adding compliance overhead to software development. Stellantis and Renault platforms are responding by segregating safety-critical lighting functions from infotainment domain controllers to isolate certification scope.
Fleet procurement managers at French leasing companies are unbundling adaptive lighting from standard equipment packages, creating à-la-carte option structures that shift volume risk to end customers. This pattern concentrates in corporate fleet channels serving Paris-based financial services firms, where total cost of ownership calculations now treat lighting systems as discrete line items rather than bundled platform features.
France Automotive Adaptive Lighting System Market Segmentation
Adaptive lighting architectures in France fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct margin pools, regulatory exposure profiles, and supply chain dependencies that shape procurement decisions across the Île-de-France and Rhône-Alpes corridors.
Product Type:
ECE R123 compliance timelines and ANSM type approval protocols differentiate product categories by certification burden and software documentation intensity.
- Matrix LED:These assemblies contain 50-100 individually addressable segments per headlamp unit, operating across 12V to 48V electrical architectures. French premium passenger vehicle manufacturers concentrate procurement around Paris-Saclay R&D clusters, driven by night-time driving comfort ratings and EU General Safety Regulation integration mandates. Established volume favors Matrix LED; emerging adoption favors Laser Headlamps.
- Laser Headlamps:Diode-pumped solid-state sources deliver extended throw distances beyond 600 meters at reduced power consumption. Development programs at Renault's technical centers and Stellantis platforms in Poissy are accelerating validation cycles, constrained by indium gallium nitride wafer supply volatility and PMIC shortage exposure.
- Fiber Optic Lighting:Remote phosphor architectures enable styling flexibility for signature daytime running lamps.
- HID Headlamps:Xenon arc discharge systems retain presence in legacy fleet retrofit channels.
- Organic LED:Thin-film electroluminescent panels enable conformable surface illumination for concept-to-production pipelines.
Cost tier stratification separates premium semiconductor-dependent categories from legacy electromechanical alternatives.
Technology:
Sensor fusion complexity and algorithmic decision pathway documentation under France's EU AI Act transposition create divergent development overhead across technology categories.
- Camera-Based:Mature image processing pipelines with established supply chains dominate current French installations. The technology leverages CMOS sensors and convolutional neural networks for real-time traffic participant detection, with demand concentrating in OEM bundled platform integrations serving corporate fleet channels around Paris-based financial services firms.
- Glare-Free High Beam:Dynamic zone deactivation algorithms adjust beam patterns without mechanical actuators. French consumers prioritize this configuration for night-time driving comfort differentiation, with fastest-expanding installation rates across Stellantis and Renault premium vehicle programs. Volume concentration sits with Camera-Based; steepest expansion trajectory belongs to Glare-Free High Beam.
- Sensor-Based:Radar and ultrasonic fusion architectures provide redundancy for adverse weather operation.
- Adaptive Beam:Speed-correlated beam range adjustment responds to vehicle dynamics without steering input.
- Dynamic Bending:Steering-angle-correlated horizontal beam pivoting for cornering illumination.
Application maturity separates camera-dependent comfort features from emerging predictive architectures.
Application:
Vehicle category determines electrical architecture compatibility and sensor suite integration depth.
- Passenger Vehicles:Full matrix LED operation with 48V mild-hybrid electrical systems enables complete feature activation. French premium OEM buyers in the Île-de-France cluster specify micro-LED pixel arrays containing 25,000 individually addressable elements for flagship programs, concentrating procurement through Valeo Group's Seville-anchored European supply network.
- Commercial Trucks:Fleet procurement managers at French leasing companies are unbundling adaptive lighting from standard equipment packages, creating à-la-carte option structures. Underpenetrated installations around Lyon and Saint-Étienne production hubs offer retrofit potential for specialized installers developing mobile calibration services.
- Two-Wheelers:Compact form factor constraints limit sensor fusion complexity.
- Emergency Vehicles:Specialized priority signaling integration with blue light systems.
- Construction Equipment:Ruggedized housing requirements for off-road vibration exposure.
Margin capture differs between OEM bundled platforms and aftermarket retrofit channels.
End User:
Position in value chain determines software calibration control and type approval liability exposure.
- OEMs:Captive platform integration captures dominant margin pools through bundled sensor suites and proprietary dynamic bending algorithms. Stellantis and Renault maintain direct relationships with semiconductor foundries for LED driver module sourcing, isolating safety-critical lighting functions from infotainment domain controllers to streamline EU AI Act certification scope.
- Tier-1 Suppliers:Valeo Group, HELLA KGaA Hueck & Co, and Magneti Marelli SpA compete through specialized sensor fusion architectures and software calibration capabilities. Magneti Marelli's captive control over Stellantis dynamic bending algorithms creates platform-lock dependency that limits competing integrator access.
- Aftermarket Installers:Narrow niche focused on premium system retrofitting into existing vehicle fleets.
- Vehicle Assemblers:Contract manufacturing arrangements for platform derivative production.
Supply chain leverage concentrates with OEMs and captive Tier-1 relationships; service margin potential favors aftermarket channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German lighting system exports flow into French OEM assembly plants along the Rhine-Rhône logistics corridor, while Spanish-manufactured LED modules from Valeo's Seville facility supply the Île-de-France cluster.
Germany
Premium vehicle manufacturers in Munich and Stuttgart drive specification intensity for matrix LED arrays. KBA type approval protocols for adaptive front lighting systems establish reference standards that French regulators frequently adopt. HELLA KGaA Hueck & Co anchors development activity in Lippstadt, concentrating sensor fusion R&D for camera-radar integration architectures.
Spain
Renault-Nissan production volumes in Barcelona and Valladolid generate steady component demand for adaptive bending modules. EU General Safety Regulation implementation timelines compress supplier delivery schedules across the Iberian Peninsula. Valeo's Seville manufacturing footprint serves as the primary European supply node for matrix LED modules destined for French vehicle platforms.
Italy
Stellantis engineering centers in Turin and Modena coordinate dynamic bending algorithm calibration for shared vehicle architectures. ECE R123 compliance documentation from Italian homologation bodies supports parallel French type approval processes. Magneti Marelli's captive software control over Stellantis platforms creates cross-border technology dependencies.
United Kingdom
Luxury automotive engineering consultancies around Gaydon and Milton Keynes specify glare-free high beam configurations for export programs. DVSA alignment with ECE regulations enables streamlined dual-homologation for French market entry. Specialized aftermarket calibration service providers in the Midlands develop mobile retrofit capabilities targeting French fleet channels.
Belgium
Port of Antwerp logistics infrastructure handles indium gallium nitride wafer imports for LED driver module production. Federal Public Service Mobility and Transport enforces EU vehicle safety regulation transposition that mirrors French ANSM protocols. Brussels-based fleet leasing headquarters influence option bundling decisions that propagate into French corporate procurement patterns.
France Automotive Adaptive Lighting System Market Competitive Landscape
Player mix skews toward vertically integrated European automotive suppliers with captive semiconductor partnerships and software calibration capabilities. Market structure concentrates around three dominant archetypes: full-system integrators controlling sensor fusion architectures, LED module specialists with foundry relationships, and software calibration houses with platform-specific algorithm lock-in. Competitive dynamics center on backward integration into LED driver semiconductor sourcing and strategic partnerships with CMOS image sensor vendors.
Among France-anchored system integrators, Valeo Group exemplifies the full-architecture archetype through its Seville-anchored European supply network. HELLA KGaA Hueck & Co and Magneti Marelli SpA occupy positions as specialist competitors, with the latter representing platform-lock dependency through captive control over Stellantis dynamic bending algorithms. These three entities collectively illustrate how supply chain leverage concentrates with suppliers possessing both manufacturing scale and software calibration depth.
| Leading Market Players |
|---|
| Valeo Group |
| HELLA KGaA Hueck & Co |
| Magneti Marelli SpA |
| Koito Manufacturing Co Ltd |
| Stanley Electric Co Ltd |
| Osram Licht AG |
| Koninklijke Philips N.V. |
| Hyundai Mobis |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with indium gallium nitride wafer foundries lock in both LED driver module supply access and three-year price visibility for French Tier-1 integrators, insulating procurement teams from PMIC spot-market volatility while compressing margin flexibility for smaller aftermarket installers.
Pricing Analysis
Matrix LED-to-micro-LED pricing gaps currently separate three distinct technology tiers in the French market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under ECE R123 and ANSM type approval protocols, with OEM bundled platforms commanding least price sensitivity due to captive software calibration control. Cost compression in mid-tier LED module categories is intensifying because micro-LED pixel arrays are displacing conventional matrix configurations in flagship programs. Aftermarket retrofit channels exhibit highest price sensitivity, forcing specialized installers in Bordeaux and Toulouse toward mobile calibration service models.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp elevates inbound logistics costs for indium gallium nitride wafer shipments originating from Taiwanese and South Korean foundries. French adaptive lighting supply chains draw from Spanish LED module assembly at Valeo's Seville facility, German sensor fusion component production, and Italian software calibration centers. Single-source vulnerability concentrates in Magneti Marelli's captive control over Stellantis dynamic bending algorithms. Distribution runs through Rhine-Rhône logistics corridors into Île-de-France OEM assembly plants and Rhône-Alpes commercial vehicle production hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Automotive Adaptive Lighting System Market functions as a defensive-moat story where regulatory entrenchment through ECE R123 and EU AI Act compliance documentation creates formidable barriers to algorithmic substitution for new entrants.
For Market Incumbents: Shield platform-lock positions by deepening backward integration into CMOS image sensor vendor partnerships and accelerating AUTOSAR Adaptive Platform certification investment ahead of EU AI Act audit requirements. Magneti Marelli's captive Stellantis algorithms represent the reference threat model; Valeo Group's Seville manufacturing scale offers the counter-lever for volume defense. For New Entrants and Emerging Players: ANSM fast-track certification pathways for glare-free high beam configurations offer the most penetrable entry vector into underpenetrated commercial vehicle fleets around Lyon and Saint-Étienne. White-space targets concentrate in mobile calibration services for premium retrofit systems and LiDAR-convergent predictive beam architectures. A dealer-network-bypass go-to-market angle through direct fleet procurement relationships minimizes incumbent channel control. For Investors and Strategic Acquirers: Capital is best deployed toward software calibration houses with platform-specific algorithm lock-in and foundry-tied LED module specialists across the 5-10 year viability window. Acquisition target archetypes include Tier-1 suppliers possessing both AUTOSAR functional safety depth and ECE R123 homologation track records. Semiconductor input volatility in indium gallium nitride wafers serves as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Stellantis and Renault consolidate dynamic bending algorithms across shared vehicle architectures to streamline ANSM certification scope. |
| Software-Defined Vehicle Investment | Segregation of safety-critical lighting functions from infotainment domain controllers accelerates EU AI Act compliance documentation. |
| Battery Supply Agreement | 48V mild-hybrid electrical system partnerships enable full matrix LED operation in next-generation passenger vehicle programs. |
| Geographic Manufacturing Footprint | Valeo's Seville facility anchors European supply of matrix LED modules for Île-de-France OEM assembly plants. |
| Charging Infrastructure Partnership | Rhône-Alpes fleet retrofit channels develop mobile calibration services bypassing traditional dealer networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and ANSM type approval specialists. Secondary validation drew from ECE R123 homologation databases, EU General Safety Regulation implementation timelines, vehicle production statistics, and semiconductor trade flow records. Bottom-up volume triangulation against top-down value estimates anchored forecast integrity.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, technology architecture, vehicle application, and end-user position in the value chain. CAGRs were derived from regression analysis of historical adoption curves and regulatory mandate compliance schedules. Industry-specific inputs included ECE R48 and ECE R123 implementation timelines, EU AI Act transposition progress through CNIL guidance, and LED content-per-vehicle trajectories across Stellantis and Renault platforms.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable semiconductor foundry capacity; material deviation in indium gallium nitride wafer supply or AI Act audit scope expansion would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market