
 Japan Domestic Courier, Express, and Parcel (CEP) Market | 2026-2036
Japan Domestic Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Domestic Courier, Express, and Parcel (CEP) Market Insights
Subscription-based recurring delivery services is repositioning how Japanese carriers monetize customer relationships beyond per-shipment fees. Yamato Holdings Co., Ltd. leverages its Kuroneko Membership program to lock in residential volume. SG Holdings Co., Ltd. sustains competitiveness through dense intercity trucking networks that feed express parcel hubs. Japan Post Holdings Co., Ltd. anchors rural coverage with its unmatched post office footprint across Japan's remote islands and mountain corridors.
Domestic courier, express, and parcel services comprise time-definite transportation of goods under 70 kilograms via integrated hub-and-spoke networks, temperature-controlled vehicles, and real-time tracking systems designed for commercial and residential fulfillment. Same-day delivery commands premium positioning in dense metropolitan corridors where slot reservations and narrow delivery windows justify higher per-unit economics. Scheduled delivery segments serving appliance and furniture retailers carry thicker margins due to specialized handling requirements and reverse logistics integration.
METI's Work Style Reform caps on driver overtime, alongside the Ministry of Land, Infrastructure, Transport and Tourism's modal shift policies, are forcing carriers to automate sorting facilities and expand rail-sea intermodal corridors. The Consumer Affairs Agency's cooling-off rules for e-commerce returns amplify demand for frictionless reverse logistics infrastructure. Stakeholders must weigh capital allocation between autonomous delivery pilots and locker network densification as labor availability tightens.
Market Dynamics
METI's Work Style Reform caps on driver overtime are compressing labor availability across Japan's parcel networks, forcing carriers to automate sorting facilities and densify automated locker infrastructure in Greater Tokyo and Osaka corridors.
Growth Catalysts
- Scheduled delivery windows:E-commerce platforms are expanding same-day and narrow-slot reservations across Kanto prefectures, creating premium revenue streams for carriers serving appliance and furniture retailers.
- METI logistics efficiency mandates:Government pressure to reduce empty truck miles is accelerating rail-sea intermodal corridor investments that lower per-unit transportation costs.
- Automated parcel lockers:Network densification in high-rise residential zones is reducing failed delivery attempts and cutting last-mile labor intensity.
Market Restraints
- Driver labor scarcity:METI overtime regulations limit available hours per operator, constraining network capacity expansion without proportional automation investment.
- Intermodal infrastructure gaps:Limited rail freight terminal access in peripheral prefectures outside Kanto and Kansai corridors restricts modal shift economics.
- Real estate compression:Urban land scarcity in Tokyo and Osaka drives up hub facility costs, squeezing margin structures for volume-focused operators.
Strategic Opportunities
- Hokkaido and Tohoku locker networks:Underpenetrated northern prefectures present first-mover advantages for automated pickup point density.
- Reverse logistics integration:Consumer Affairs Agency cooling-off rules for e-commerce returns create demand for frictionless return infrastructure.
- Temperature-controlled last-mile:Pharmaceutical and fresh food e-commerce expansion opens specialized handling segments with thicker margins.
Industry Challenges
- Legacy system integration:Carriers must reconcile decades-old tracking infrastructure with real-time API demands from platform retailers.
- Sorting automation capex:Hub robotics deployment requires substantial capital outlay amid compressed delivery fee competition.
- Route optimization talent:Scarcity of data scientists capable of deploying AI-driven dynamic routing across Japan's complex addressing system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Domestic Courier, Express, and Parcel (CEP) Market |
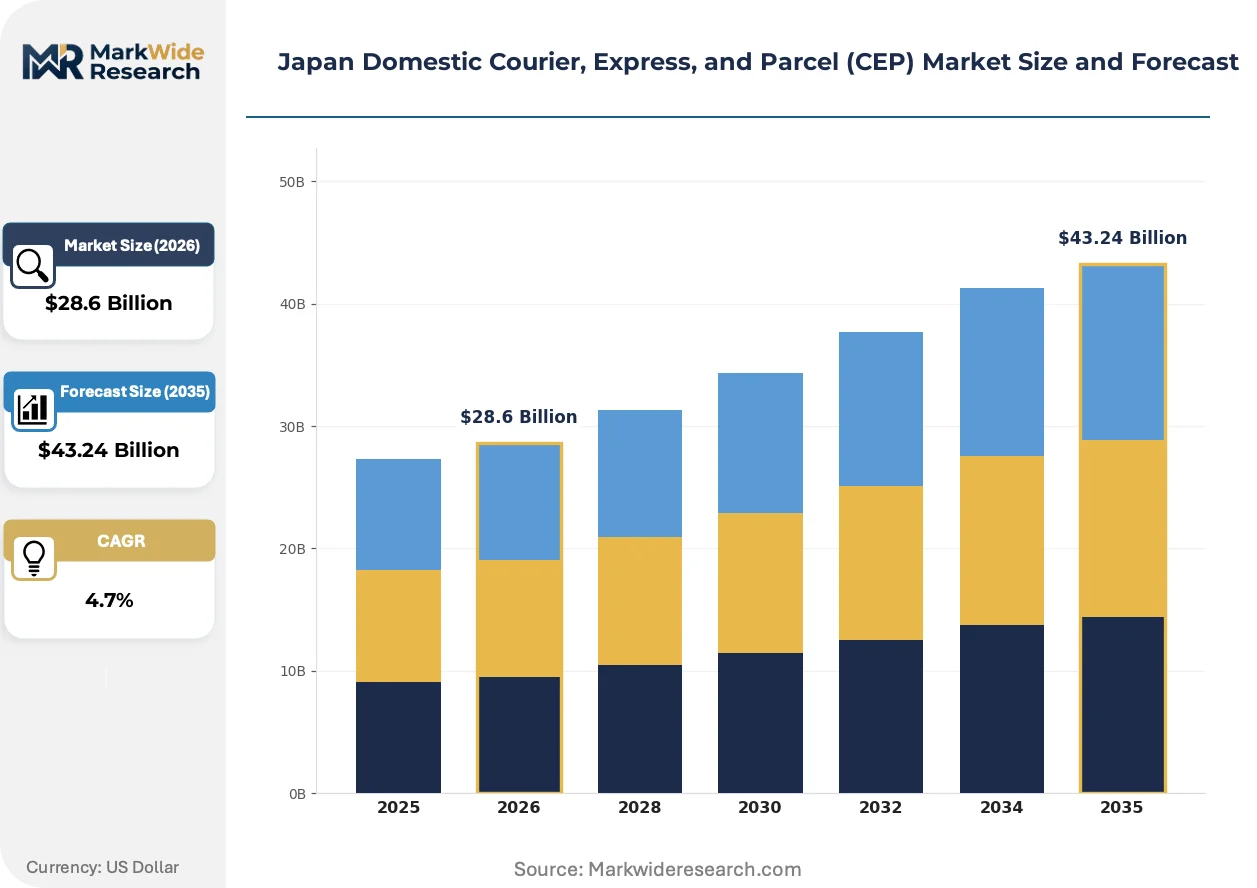
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, Scheduled Delivery Customer Type: Businesses, E-commerce, Individuals, Government Agencies Package Size: Small, Medium, Large, Extra Large Delivery Channel: Direct-to-Door, Pickup Points, Lockers, Retail Partners |
| Companies Covered | Yamato Holdings Co., Ltd., SG Holdings Co., Ltd., Japan Post Holdings Co., Ltd., Nippon Express Holdings, Seino Holdings Co., Ltd., FedEx, DHL, United Parcel Service, Fukuyama Transporting Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Domestic Courier, Express, and Parcel (CEP) Market Trends and Innovations
Japan's CEP sector is undergoing operational recalibration as labor constraints meet platform retailer demands for precision delivery windows. Three developments are restructuring competitive capability.
Dynamic route optimization software is unifying dispatch decisions across previously siloed hub operations. Major platform retailers are mandating API integration for slot-level visibility. This compression of planning cycles is enabling same-day service economics in dense metropolitan corridors.
METI's modal shift policies are redirecting long-haul volume from road to rail-sea corridors connecting Honshu with Kyushu and Shikoku. Industrial shippers of bulky goods face mandatory reporting on transportation emissions. Coastal feeder networks and inland rail terminals are absorbing capital allocation previously directed toward highway fleet expansion.
Subscription delivery memberships are displacing per-shipment purchasing among residential consumers. Platform retailers are bundling free delivery into annual loyalty programs. This shift is most pronounced in Greater Tokyo, where household penetration of recurring delivery services exceeds other prefectures.
Japan Domestic Courier, Express, and Parcel (CEP) Market Segmentation
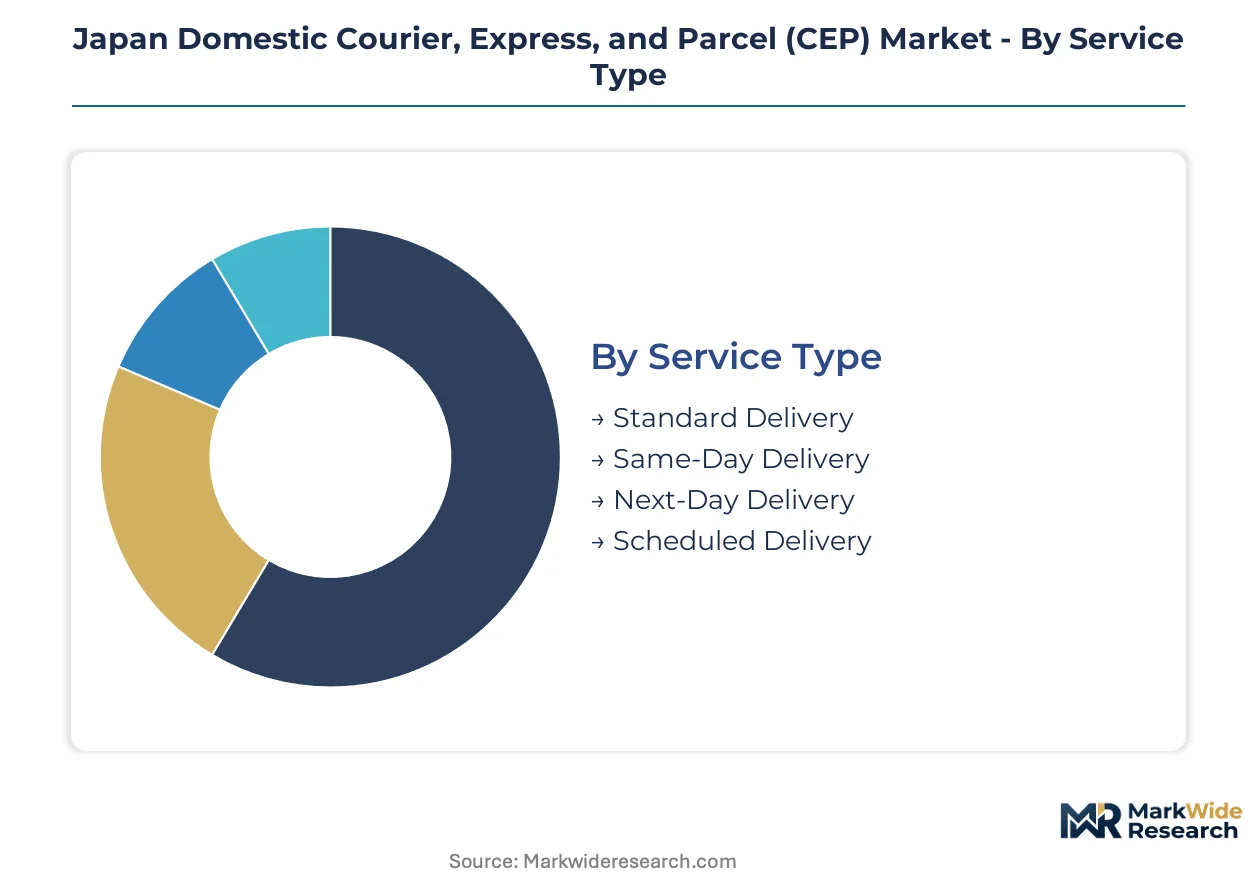
Service differentiation determines carrier profitability in Japan's CEP sector, where narrow delivery windows and specialized handling create distinct margin tiers. Understanding how demand fragments across service models, customer profiles, and infrastructure choices enables precise capacity allocation and pricing strategy.
Service Type:
Upgrade cycles in delivery speed expectations are shortening as platform retailers compete on fulfillment precision, pushing carriers to develop tiered service portfolios that capture premium willingness-to-pay.
- Standard Delivery:Two-to-three-day transit via consolidated hub-and-spoke networks serves cost-sensitive B2B shippers and non-urgent residential orders. Volume concentrates in intercity corridors connecting Osaka, Nagoya, and Tokyo where density supports daily consolidation runs.
- Same-Day Delivery:Slot-reserved fulfillment within metropolitan boundaries commands the highest per-unit economics in Japan's CEP sector. Demand clusters in Greater Tokyo's 23 wards and central Osaka, where e-commerce platforms use narrow windows as competitive differentiation.
- Next-Day Delivery:Overnight hub sorting and early-morning dispatch meets mid-tier urgency requirements for regional retailers and corporate procurement. This segment absorbs volume from businesses balancing speed against freight expenditure.
- Scheduled Delivery:Time-definite arrival windows with specialized handling for appliances and furniture carry thicker margins due to reverse logistics integration and installation coordination. METI efficiency mandates favor this segment's consolidation potential.
Standard Delivery sits at the top of the volume ranking, with Same-Day Delivery climbing the fastest as platform retailers narrow fulfillment promises.
Customer Type:
Customer procurement sophistication varies sharply, with enterprise accounts negotiating annual contracts against transactional residential purchasing that responds to subscription bundling.
- Businesses:Corporate shippers with integrated supply chains demand API connectivity and consolidated billing across multiple origin points. Manufacturing clusters in Aichi and Kanagawa prefectures generate recurring B2B volume.
- E-commerce:Platform retailers drive the steepest expansion trajectory through fulfillment outsourcing and same-day service mandates. Their volume concentrates in Kanto and Kansai urban corridors where consumer density supports frequent pickup cycles.
- Individuals:Residential consumers increasingly purchase through membership programs rather than per-shipment fees, locking in carrier relationships. Subscription penetration runs highest in Tokyo metropolitan households.
- Government Agencies:Public sector procurement favors incumbent operators with established security clearances and rural coverage obligations. Japan Post Holdings anchors this segment through its unmatched post office infrastructure.
E-commerce commands the largest revenue pool, while Individuals are gaining share fastest as subscription models displace transactional purchasing.
Package Size:
Handling economics shift dramatically with parcel dimensions, determining whether automated sorting or manual intervention dominates the fulfillment path.
- Small:Envelopes and shoebox-scale parcels flow through automated sortation with minimal labor touchpoints. Pharmaceutical and cosmetics e-commerce favor this category for locker compatibility.
- Medium:Standard carton dimensions represent the volume core of Japan's parcel networks, optimized for conveyor systems and residential door delivery. Apparel and electronics retail drives sustained demand.
- Large:Bulky items requiring two-person handling or specialized vehicles carry elevated per-unit costs and longer delivery windows. Appliance retailers in scheduled delivery segments dominate this tier.
- Extra Large:Furniture and fitness equipment shipments depend on appointment-based delivery with assembly services, creating the thickest margin structure across package categories.
Medium parcels anchor volume rankings, with Small packages expanding most quickly as pharmaceutical and fresh-food e-commerce densifies.
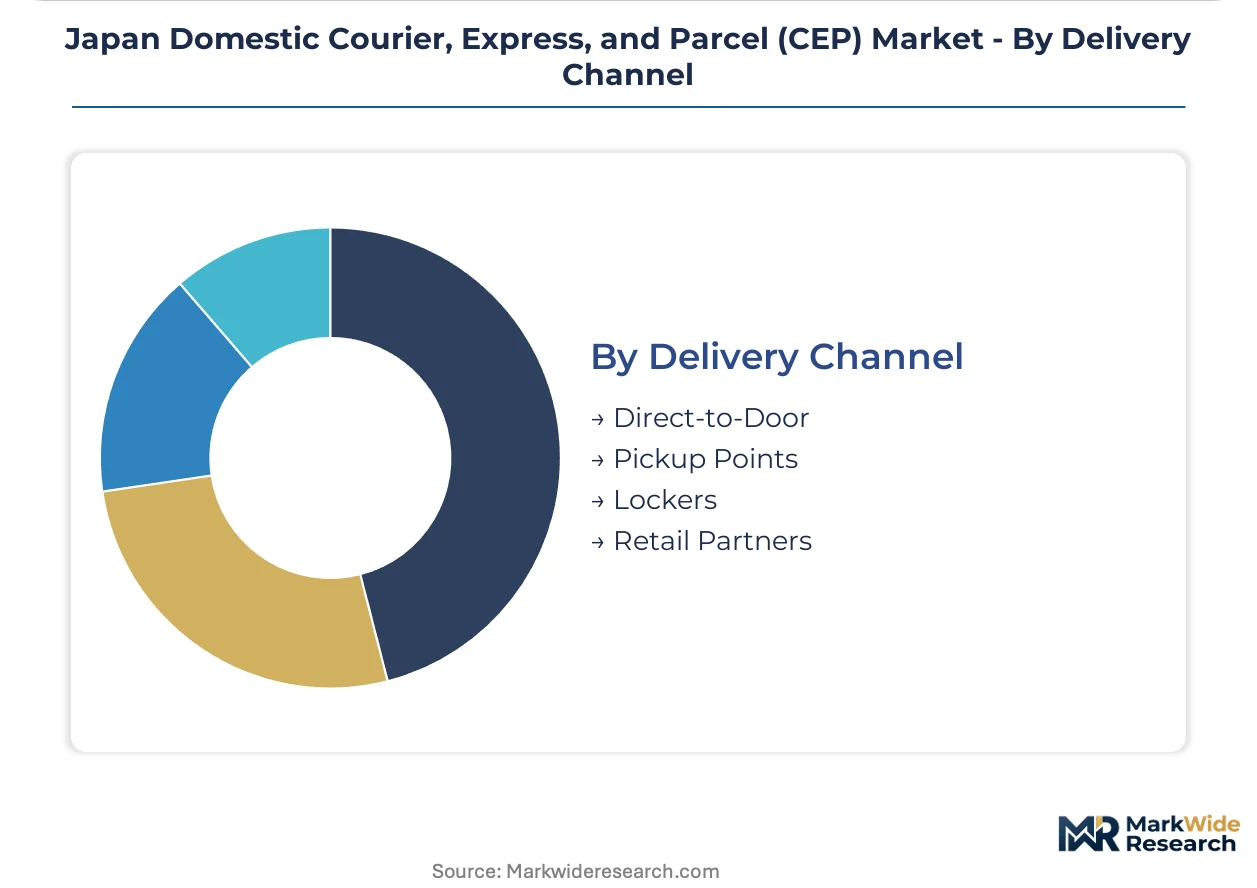
Delivery Channel:
Last-mile infrastructure investment is reallocating capital from direct delivery capacity toward fixed pickup infrastructure that reduces failed attempts and labor exposure.
- Direct-to-Door:Residential doorstep delivery remains the default expectation but faces cost pressure from driver hour constraints under METI Work Style Reform. High-rise Tokyo apartments with concierge services sustain economics.
- Pickup Points:Convenience store partnerships and dedicated carrier locations offer flexibility for working households. Yamato Holdings and SG Holdings maintain dense networks in commercial districts.
- Lockers:Automated parcel terminals in residential complexes and transit hubs eliminate redelivery costs and support 24-hour retrieval. Network densification concentrates in Greater Tokyo and Osaka corridors.
- Retail Partners:Supermarket and drugstore chains extend carrier reach into neighborhood catchments without dedicated facility investment. Rural prefectures rely heavily on this channel for coverage extension.
Direct-to-Door retains volume leadership, though Lockers are climbing fastest as real estate developers integrate terminals into new residential construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's parcel density exceeds Japan's rural coverage depth, while both markets confront identical driver hour constraints. National postal incumbents anchor last-mile infrastructure across developed Asian and European economies. METI-style efficiency mandates now appear in modified form from Berlin to Seoul.
Kanto
Greater Tokyo's 23 wards generate the steepest same-day delivery premiums in Japan's CEP sector. METI Work Style Reform caps compress driver availability across Saitama, Chiba, and Kanagawa prefectures. Automated locker networks concentrate in Shinjuku and Shibuya high-rise corridors where failed delivery costs exceed terminal depreciation.
Kansai
Osaka's merchant culture sustains dense pickup point partnerships with convenience store chains. The Ministry of Land, Infrastructure, Transport and Tourism's modal shift policies redirect inter-island volume toward Kobe port rail terminals. Kyoto's historic district restrictions force bicycle-based last-mile solutions in central wards.
Chubu
Nagoya's automotive supplier clusters generate scheduled delivery contracts with narrow assembly-line windows. Aichi prefecture's manufacturing density supports dedicated B2B route optimization. Toyota City's just-in-time parts networks demand sub-hour delivery precision from integrated carriers.
Kyushu
Fukuoka's startup ecosystem attracts platform retailer fulfillment outsourcing from Seoul and Shanghai. The Kanmon Strait ferry corridor absorbs long-haul volume under METI emissions reporting requirements. Saga and Nagasaki prefectures rely on retail partner networks for rural coverage extension.
Hokkaido
Sapporo's winter logistics infrastructure handles temperature-controlled pharmaceutical volumes for northern Japan. Japan Post Holdings maintains unmatched post office coverage across remote island chains. Underpenetrated locker density in Asahikawa and Hakodate presents first-mover network expansion potential.
Japan Domestic Courier, Express, and Parcel (CEP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated carriers dominating scheduled delivery while platform retailers outsource fulfillment to third-party networks. The market structures around three tiers: postal incumbents with rural coverage obligations, private express carriers with metropolitan density, and global integrators feeding international corridors. Two competitive moves define current positioning: locker network densification in high-rise zones and rail-sea intermodal corridor investments. Carriers defend margin structures through subscription membership programs that lock in residential volume.
Among Japan-based integrated logistics groups, Yamato Holdings Co., Ltd., SG Holdings Co., Ltd., and Japan Post Holdings Co., Ltd. occupy distinct archetype positions. Yamato exemplifies the subscription-model carrier through residential membership programs. SG Holdings represents intercity trucking-to-express integration. Japan Post anchors universal service obligations across remote prefectures where private carriers withdraw. These three structures illuminate how labor constraints and platform retailer demands reshape competitive capability without requiring identical strategic responses.
| Leading Market Players |
|---|
| Yamato Holdings Co., Ltd. |
| SG Holdings Co., Ltd. |
| Japan Post Holdings Co., Ltd. |
| Nippon Express Holdings |
| Seino Holdings Co., Ltd. |
| FedEx |
| DHL |
| United Parcel Service |
| Fukuyama Transporting Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Same-day premium divergence from standard delivery economics manifests in both carrier rate cards and hub infrastructure deployment across Greater Tokyo. METI Work Style Reform caps compress driver availability, forcing carriers to recover labor scarcity costs through slot-reservation premiums while automating sortation in Kanto corridors.
Pricing Analysis
Capacity additions in automated locker networks are reshaping price floors for residential last-mile services. Three-tier pricing structure across premium, standard, and economy levels separates same-day slot reservations from next-day scheduled windows from deferred consolidation runs. Price differentiation stems from delivery speed guarantees and reverse logistics bundling. Pricing pressure stems from platform retailer consolidation of fulfillment spend. E-commerce platforms exhibit highest price sensitivity; appliance retailers with installation requirements show lowest.
Supply Chain Analysis
Sorting equipment supply rests on German and Japanese automation specialists, with conveyor systems and robotic arms flowing through Kobe and Yokohama port terminals. Hub construction materials draw from domestic steel producers and Chinese electrical component suppliers. Single-source vulnerability concentrates in AI-driven route optimization software licensed from US and Israeli vendors. Distribution runs through hub-and-spoke networks anchored in Osaka, Nagoya, and Tokyo with rail-sea feeder connections to Kyushu and Hokkaido.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's logistics efficiency mandates compound carrier investment requirements, with emissions reporting obligations and modal shift policies creating sustained infrastructure demand across the analysis window.
For Market Incumbents: Extend automated locker density into underpenetrated Tohoku and Hokkaido corridors before competitors establish fixed cost advantages. Fortify subscription membership programs to lock in residential volume against platform retailer fulfillment consolidation. Deepen backward integration into rail-sea intermodal assets to defend margin position as highway driver hours contract.
For New Entrants and Emerging Players: Begin with temperature-controlled pharmaceutical last-mile services in Sapporo and Fukuoka, where specialized handling requirements create barrier-protected niches. Target scheduled delivery segments for appliance retailers, where installation coordination and reverse logistics integration deter pure-play competitors. Pursue API-first integration with mid-tier platform retailers seeking alternatives to incumbent carrier networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where automated sorting capex requirements outstrip regional carrier cash generation. Long-term viability favors carriers with locked-in subscription revenue and intermodal asset control. Acquisition target archetype: mid-size operators with dense Kanto pickup point networks and undeveloped locker infrastructure. Watch METI emissions enforcement intensity as inflection signal for modal shift investment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Locker Network Densification | Reduces failed delivery costs and METI overtime exposure in Tokyo high-rise corridors. |
| Rail-Sea Intermodal Investment | Aligns carrier infrastructure with MLIT modal shift policies and emissions reporting mandates. |
| Subscription Membership Expansion | Locks in residential volume through Kuroneko-style recurring revenue models. |
| Reverse Logistics Integration | Captures Consumer Affairs Agency cooling-off rule compliance demand from e-commerce platforms. |
| Temperature-Controlled Fleet Buildout | Opens pharmaceutical and fresh-food segments with thicker handling margins. |
Research Methodology
Multiple input streams — carrier operations executives, e-commerce platform logistics directors, METI regulatory affairs specialists, and automated equipment procurement managers — were reconciled with secondary validation from MLIT transport statistics, Japan Post Holdings annual disclosures, and customs intermodal trade data. Bottom-up volume modeling across service tiers, customer segments, and regional corridors was triangulated against top-down market sizing from macroeconomic freight indicators.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery speed tier, customer procurement sophistication, package handling requirements, and last-mile infrastructure type. CAGRs were derived from trend extrapolation of subscription penetration, locker network deployment curves, and modal shift volume migration. Forecast inputs incorporated METI Work Style Reform implementation pace and platform retailer fulfillment outsourcing decisions.
Several conditions sit outside the modeled scope, including unforeseen regulatory relaxation, breakthrough autonomous vehicle deployment, and macroeconomic shocks to consumer discretionary spending. Forecasts reflect assumptions about labor availability constraints and technology adoption curves. A small set of named triggers warrants ongoing watch: METI enforcement intensity, platform retailer vertical integration moves, and rail freight terminal capacity expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
France Last Mile Delivery Market