
 Automotive Door Panel Market | 2026-2036
Automotive Door Panel Market Size, Share, and Industry Trends Forecast 2026-2036
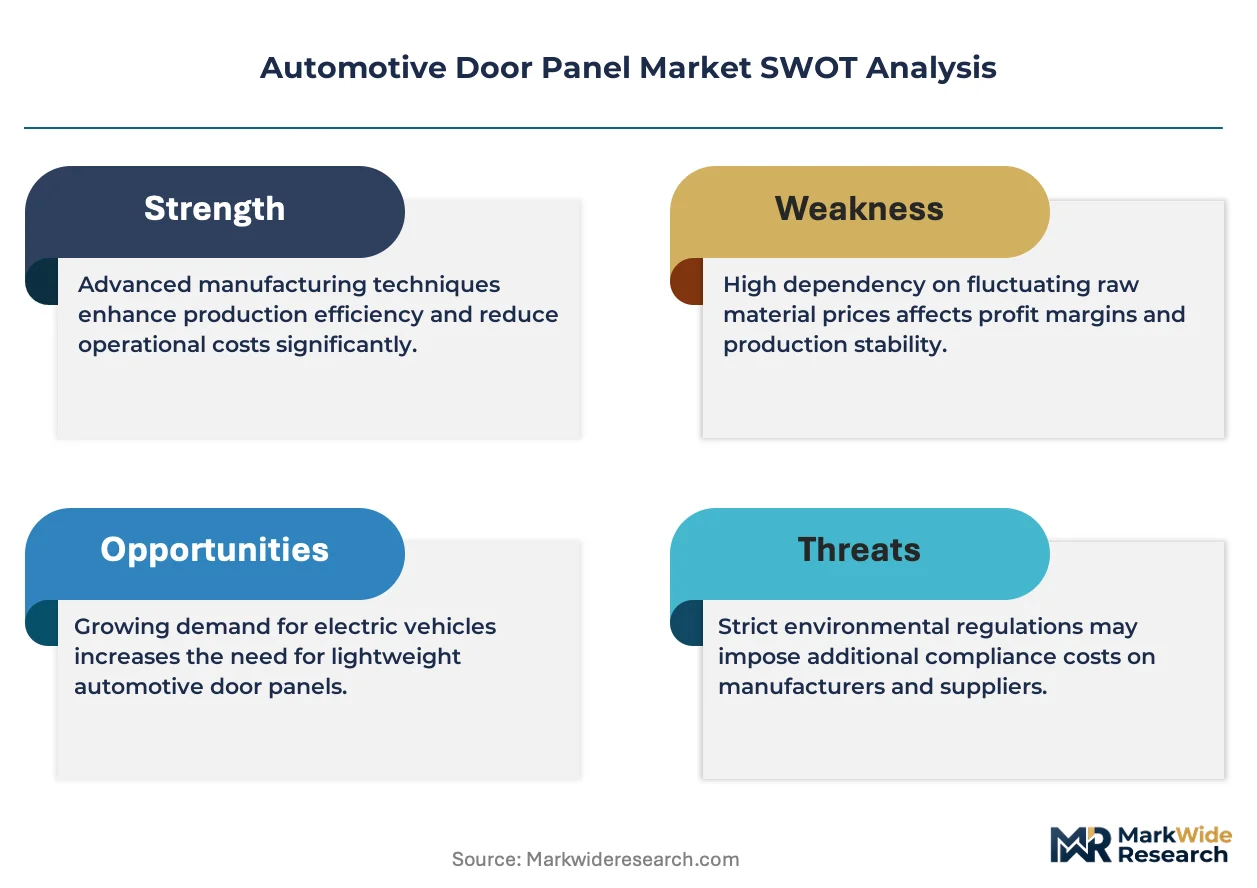
Automotive Door Panel Market Analysis
Mexico is narrowing its cost advantage as a North American door panel sourcing hub amid rising labor rates and nearshoring congestion. Grupo Antolin leverages its Spanish-Mexican manufacturing footprint to sustain just-in-sequence deliveries to Volkswagen and Stellantis assembly lines. Toyota Boshoku anchors its position through captive supply relationships within the Toyota Group hierarchy. Brose competes on mechatronic integration, embedding window regulators and latch systems directly into door panel modules.
An automotive door panel constitutes the interior trim assembly that seals the door cavity, integrates armrests, switch bezels, and speaker housings, and typically comprises a carrier substrate of polypropylene or steel overlaid with foam-backed vinyl, fabric, or leather surfacing. Its primary purpose spans occupant protection, NVH attenuation, and cabin aesthetic completion. Plastic carriers dominate volume production for mass-market vehicles, while composite substrates represent the fastest-growing material category as OEMs pursue gram-level weight reduction targets. OEM direct sourcing occupies the largest value pool, though Tier-1 Suppliers are consolidating design-to-build responsibility for modular door systems.
EPA fuel economy standards and NHTSA safety requirements in the United States pressure manufacturers toward lighter, crash-compatible door architectures. ECHA REACH restrictions on phthalates and flame retardants constrain material selection across European supply chains. China's GB standards for interior air quality and MIIT new energy vehicle mandates collectively reshape formulation priorities for suppliers serving domestic OEMs. Stakeholders must monitor how divergent regional chemical regulations fragment material platforms and force parallel qualification tracks.
Market Dynamics
Lightweight composite substrates are displacing conventional polypropylene carriers as electric vehicle platforms impose gram-level weight reduction mandates across door panel architectures. This material transition compresses legacy supply chains while forcing parallel qualification tracks for crash-compatible formulations.
Growth Catalysts
- EPA Fuel Economy Standards:US manufacturers accelerate aluminum and carbon fiber-reinforced polymer adoption to meet corporate average fuel economy thresholds. Door panels represent high-impact weight reduction targets.
- Premium EV Platforms:Battery electric vehicle architectures prioritize interior space efficiency and range extension through structural component lightweighting. Composite door modules integrate thermal management and wiring channels.
- China MIIT New Energy Vehicle Mandates:Domestic OEM procurement specifications favor low-density material platforms with recycled content quotas. Suppliers reformulate polypropylene compounds to meet GB interior air quality standards.
Market Restraints
- Steel Price Volatility:Hot-rolled coil input costs fluctuate with energy-intensive European smelter curtailments. Metal carrier producers face margin compression during contract renegotiation cycles.
- ECHA REACH Phthalate Restrictions:Plasticizer substitution in vinyl surfacing compounds requires complete reformulation. Qualification timelines extend 18-24 months for alternative plasticizer platforms.
- Polypropylene Supply Concentration:Middle Eastern and US Gulf Coast petrochemical clusters control upstream propylene monomer flows. Regional production disruptions propagate through compounding tiers.
Strategic Opportunities
- India PLI Scheme for Auto Components:Component-level production-linked incentives attract door panel module investments serving Maruti Suzuki and Hyundai domestic assembly.
- Biomaterial Convergence:Natural fiber-reinforced thermoplastics merge with recycled polymer streams. Hemp and flax fiber suppliers partner with Tier-1 molders for carbon-negative positioning.
- Direct OEM Sourcing Consolidation:Volkswagen Group and Stellantis integrate design-to-build responsibility for complete door systems. Modular suppliers capture higher value pools through mechatronic integration.
Industry Challenges
- Multi-Material Bonding Expertise:Composite-to-metal hybrid assemblies require adhesive process engineers and thermal expansion modeling capabilities scarce in traditional trim shops.
- Dual-Chemistry Qualification Burden:Suppliers maintain parallel material platforms for REACH-compliant European supply and cost-optimized Asian production. Testing redundancy strains R&D budgets.
- Crash Simulation Cycle Compression:OEMs demand finite element analysis validation within 12-week program gates. Smaller molders lack in-house simulation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Panel Market |
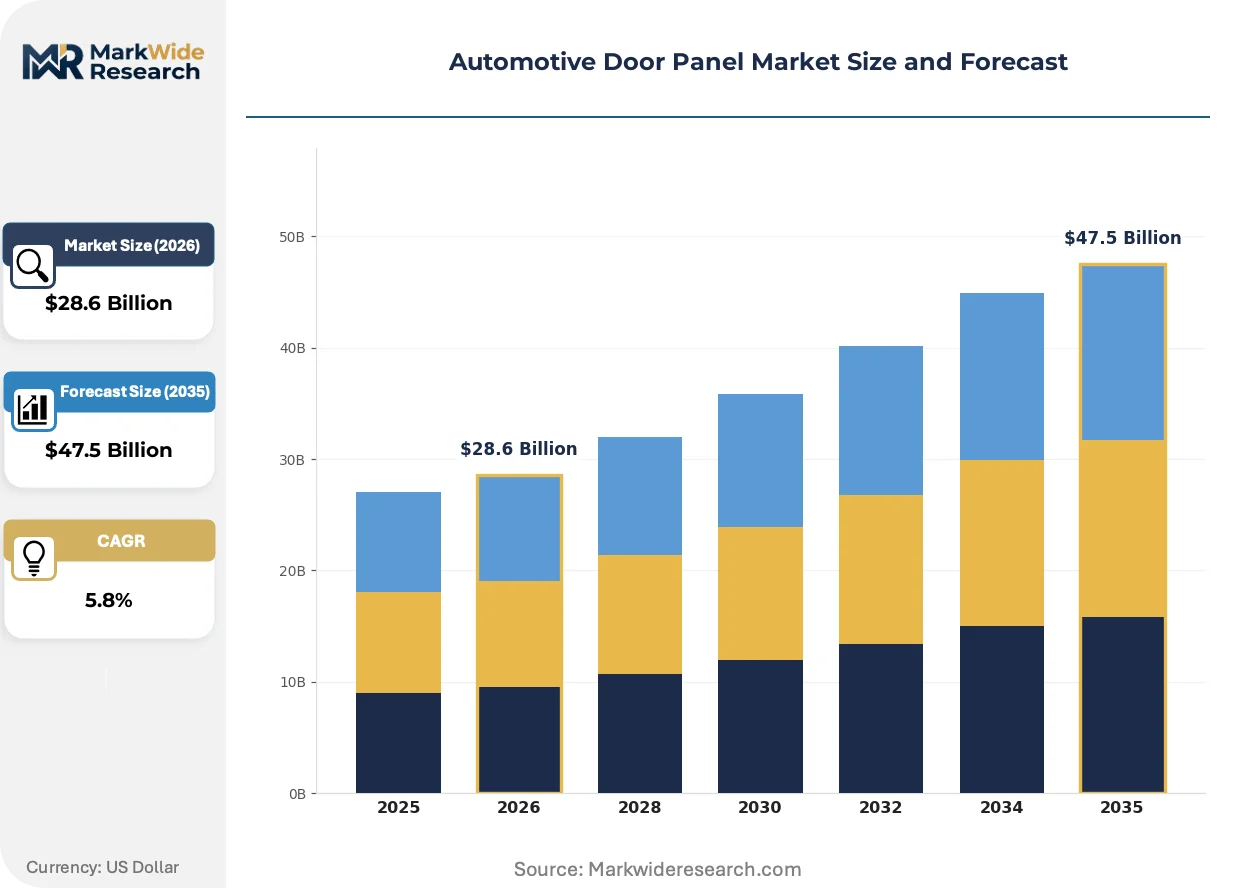
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Composite, Wood End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Functionality: Structural, Aesthetic, Insulation, Soundproofing Installation Method: Adhesive, Bolt-On, Clip-On, Integrated |
| Companies Covered | Grupo Antolin, Brose, Draexlmaier Group, Hayashi Telempu Corporation, IAC Group, TS Tech, Kasai Kogyo, Reydel Automotive France SAS, Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Panel Market Emerging Trajectories
Digital twin workflows and generative design tools are compressing traditional prototyping cycles while enabling topology-optimized carrier structures previously unmanufacturable through conventional tooling.
Topology-optimized carrier substrates replace uniform-thickness stampings with lattice-reinforced geometries. BMW and Mercedes-Benz production programs adopt generative-designed aluminum carriers for flagship electric sedans. This approach is virtualizing physical crash testing through correlated finite element models, reducing prototype iterations by sixty percent.
REACH SVHC candidate list expansion to include additional flame retardants forces systematic substance screening across European supply chains. Compounders must maintain updated safety data sheets and substitution roadmaps for brominated and phosphorus-based additives. Premium German OEMs now require full material disclosure to 0.1 percent thresholds, shifting procurement criteria toward certified clean formulations.
Fleet operators and mobility service providers now specify standardized door panel architectures across multiple vehicle programs to simplify aftermarket service. Rental car aggregators and ride-hail fleet managers prioritize interchangeable trim components over model-specific differentiation. This specification consolidation is most visible in North American commercial fleet procurement, where TCO-driven purchasing compresses design variety.
Automotive Door Panel Market Segmentation
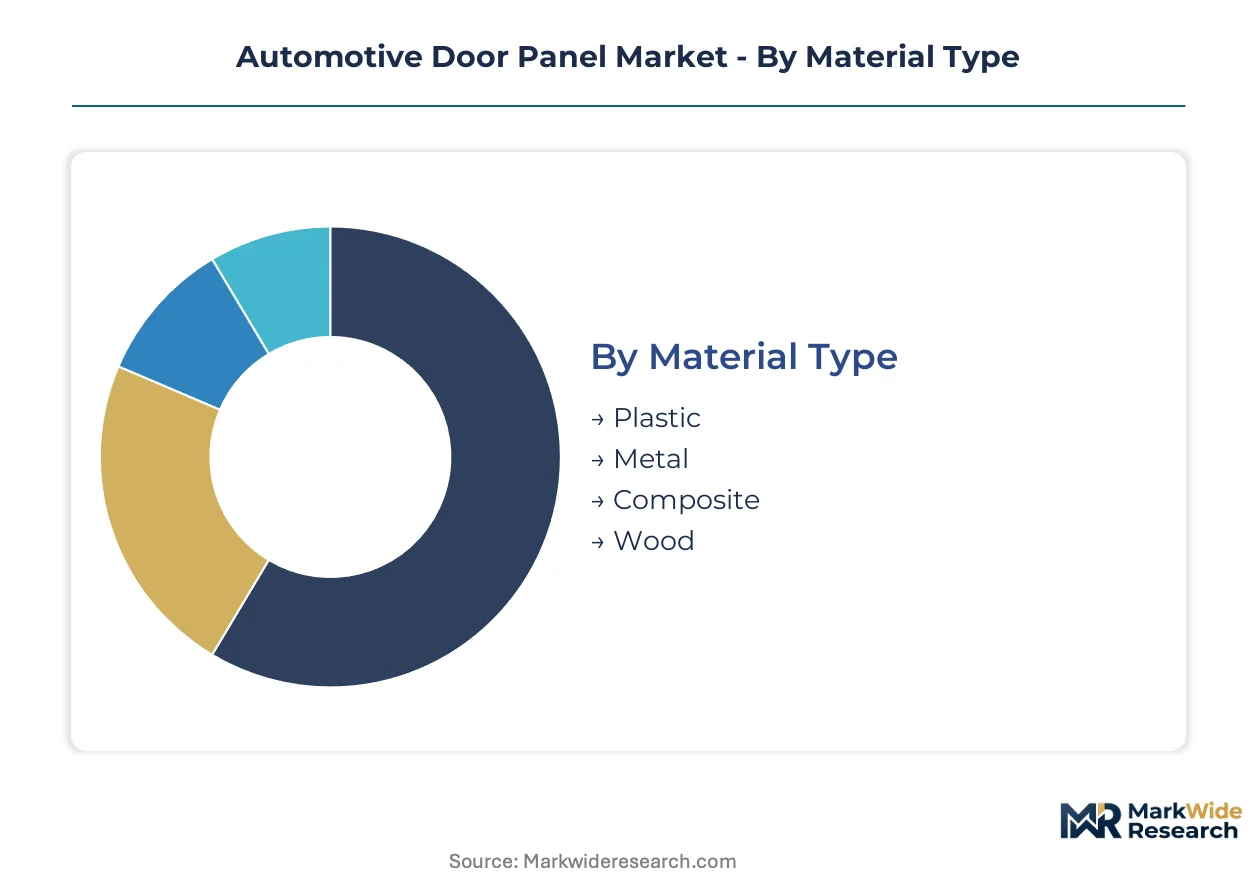
Automotive door panel segmentation reveals how material science, supply chain position, and functional integration create distinct competitive arenas. Suppliers must align capabilities with the specific performance thresholds and qualification timelines each segment demands.
Material Type:
Cost tier determines raw material sourcing strategies and tooling amortization profiles across door panel production.
- Plastic:Polypropylene carriers dominate mass-market volume through injection-molded substrates with foam-backed vinyl surfacing. Chinese domestic OEM procurement under MIIT mandates accelerates reformulation for GB interior air quality compliance.
- Composite:Carbon fiber-reinforced and natural fiber thermoplastic hybrids achieve gram-level weight reduction for electric vehicle platforms. European REACH phthalate restrictions force parallel qualification tracks for bio-based resin systems.
- Metal:Steel stampings retain cost efficiency for commercial vehicle and economy passenger car segments.
- Wood:Veneer and real wood trim serve ultra-premium flagship sedans with artisan finishing requirements.
Plastic commands the established base. The steepest expansion runs through Composite.
End User:
Customer type shapes design authority, module complexity, and contract duration across the value chain.
- OEMs:Volkswagen Group and Stellantis consolidate design-to-build responsibility for complete door systems, capturing direct sourcing value pools. Their module specifications integrate thermal management channels and wiring harness routing for battery electric architectures.
- Tier-1 Suppliers:Brose and Grupo Antolin leverage mechatronic integration expertise to embed window regulators, latch mechanisms, and switch assemblies within panel modules. Their just-in-sequence delivery contracts with German and Spanish assembly plants require sub-4-hour replenishment cycles.
- Vehicle Assemblers:Contract manufacturers and EV startups procure pre-validated door modules to compress program development timelines.
- Aftermarket Providers:Fleet operators and mobility services specify standardized trim architectures to simplify service intervals and parts inventory.
OEMs retain design authority and value capture. Tier-1 Suppliers are climbing the fastest through module integration scope expansion.
Functionality:
Application priority determines material selection, testing protocols, and regulatory exposure for door panel systems.
- Structural:Crash-compatible carriers must satisfy NHTSA side-impact requirements and ECE R95 regulations through controlled deformation geometries. Aluminum and composite hybrids undergo 12-week finite element validation cycles for OEM program gates.
- Insulation:Thermal barrier layers integrate with HVAC system efficiency targets for electric vehicle range optimization. BMW flagship electric sedants specify multi-layer foam constructions with aerogel interlayers.
- Aesthetic:Surface finishing quality defines cabin premium perception through grain matching, color stability, and haptic response.
- Soundproofing:NVH attenuation materials address road noise intrusion as tire specifications widen and aerodynamic optimization reduces wind noise masking.
Structural functionality commands the established base. Insulation is gaining share fastest as thermal management priorities intensify for electric platforms.
Installation Method:
Supply concentration and assembly plant automation levels dictate attachment technology selection.
- Integrated:Complete door modules arrive at assembly lines with pre-installed hardware, wiring, and trim components. Grupo Antolin's Spanish-Mexican footprint serves Volkswagen and Stellantis plants with sub-hour sequencing precision.
- Clip-On:Snap-fit attachment enables field-replaceable trim panels for fleet service efficiency. Rental car aggregators in North American commercial procurement specify this architecture for TCO minimization.
- Adhesive:Structural bonding joins dissimilar material hybrids requiring thermal expansion modeling expertise scarce in traditional trim operations.
- Bolt-On:Mechanical fastening retains service accessibility for heavy-duty commercial vehicle applications.
Integrated installation commands the established base. Clip-On architectures are expanding most quickly through fleet operator specification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel economy standards and NHTSA safety requirements in the United States pressure manufacturers toward lighter, crash-compatible door architectures. ECHA REACH restrictions on phthalates and flame retardants constrain material selection across European supply chains. China's GB standards for interior air quality and MIIT new energy vehicle mandates collectively reshape formulation priorities for suppliers serving domestic OEMs.
United States
Domestic OEM procurement specifications prioritize aluminum and carbon fiber-reinforced polymer adoption to meet corporate average fuel economy thresholds. EPA regulations on vehicle emissions intensify gram-level weight reduction mandates across door panel architectures. Detroit's automotive corridor concentrates module assembly operations serving Ford, General Motors, and Stellantis production lines with just-in-sequence delivery contracts.
Germany
Premium electric vehicle platforms from BMW and Mercedes-Benz expand composite door panel specifications for flagship sedan programs. ECHA REACH SVHC candidate list expansion forces systematic substance screening for brominated and phosphorus-based flame retardants. The Stuttgart-Munich industrial axis anchors Tier-1 supplier engineering centers where Brose and Draexlmaier Group integrate mechatronic systems into modular door assemblies.
China
Domestic OEM procurement under MIIT new energy vehicle mandates accelerates reformulation for GB interior air quality compliance with recycled content quotas. SAMR market surveillance on automotive component safety tightens qualification timelines for imported material platforms. The Yangtze River Delta cluster around Shanghai concentrates molding operations serving BYD, NIO, and Tesla Gigafactory Shanghai with sub-4-hour replenishment cycles.
Mexico
Nearshoring congestion and rising labor rates narrow cost advantages as a North American sourcing hub for door panel modules. NHTSA safety requirements propagate through cross-border supply chains serving US assembly plants. The Bajío Region and Nuevo León host Grupo Antolin manufacturing footprints sustaining just-in-sequence deliveries to Volkswagen and Stellantis assembly lines with Spanish-Mexican operational integration.
Japan
Toyota Boshoku anchors supply relationships through captive procurement within the Toyota Group hierarchy for Camry and Lexus door panel programs. METI carbon neutrality roadmaps accelerate natural fiber-reinforced thermoplastic development for weight-sensitive electric platforms. The Aichi Prefecture cluster around Nagoya concentrates interior component engineering where Hayashi Telempu and Kasai Kogyo maintain OEM-direct supply contracts.
Automotive Door Panel Market Vendor Landscape
Full-system integrators and component specialists split the market along the design-to-build boundary. Consolidation pressures concentrate module-level responsibility among Tier-1 suppliers with mechatronic capabilities, while smaller molders retreat to carrier substrate fabrication. Three archetypes dominate: captive automotive group suppliers, independent modular system integrators, and regional trim-focused fabricators. Competitive moves center on backward integration into resin compounding and geographic expansion through plant co-location with OEM assembly networks.
Within the captive supplier tier, Toyota Boshoku Corporation exemplifies group-affiliated supply structures. Among independent modular specialists, Brose and Grupo Antolin occupy positions defined by mechatronic integration breadth and Spanish-Mexican manufacturing footprint respectively. These three anchors illustrate how competitive positioning diverges between hierarchy-embedded supply relationships and open-market module competition.
| Leading Market Players |
|---|
| Grupo Antolin |
| Brose |
| Draexlmaier Group |
| Hayashi Telempu Corporation |
| IAC Group |
| TS Tech |
| Kasai Kogyo |
| Reydel Automotive France SAS |
| Toyota Boshoku Corporation |
| Others |
Supply Flow & Price Mechanics
Middle Eastern and US Gulf Coast petrochemical clusters control upstream propylene monomer flows, concentrating margin capture with resin compounders while downstream door panel molders face compressed spreads during contract renegotiations. This upstream concentration forces Tier-1 suppliers to defend value pools through module integration rather than material arbitrage.
Pricing Analysis
Geographic price spreads between Chinese domestic OEM procurement and European premium fleet specifications exceed three-to-one ratios across comparable polypropylene carrier substrates. Contract-based long-term offtake agreements dominate volume procurement, though spot purchases spike during Middle Eastern production disruptions. Price differentiation hinges on GB interior air quality certification grade and mechatronic integration depth. Cost compression in mass-market plastic tiers is intensifying because MIIT recycled content quotas force reformulation investments without corresponding price recovery mechanisms. Fleet operators and mobility services exhibit highest price sensitivity, while German premium OEMs prioritize certified clean formulations over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for composite substrate suppliers serving dual-region OEM programs. Manufacturing concentrates in China, Germany, and Mexico, with raw material dependencies spanning Saudi Arabian propylene, German automotive-grade steel, and Japanese carbon fiber tow. The network rests on just-in-sequence delivery contracts requiring sub-4-hour replenishment cycles to assembly plants. Distribution runs through Tier-1 module integrators co-located with OEM production clusters rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM direct sourcing consolidation at Volkswagen Group and Stellantis has shifted bargaining power upstream, fragmenting margin pools among suppliers without module integration capabilities. This buyer-power concentration demands strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Build adhesive process engineering moats around multi-material bonding expertise for composite-to-metal hybrid assemblies. Brose and Grupo Antolin demonstrate how embedding window regulators and latch systems directly into door panel modules captures design-to-build responsibility. Defend against emerging natural fiber-reinforced thermoplastic specialists by securing hemp and flax fiber supply partnerships. Prioritize backward integration into resin compounding to control formulation roadmaps for REACH-compliant European supply and cost-optimized Asian production.
For New Entrants and Emerging Players: India's component-level production-linked incentives represent the most penetrable geographic entry point for door panel module investments serving Maruti Suzuki and Hyundai domestic assembly. Target biomaterial convergence segments where hemp and flax fiber suppliers partner with Tier-1 molders for carbon-negative positioning. Pursue fleet operator specifications for standardized clip-on trim architectures across North American commercial procurement, where TCO-driven purchasing compresses design variety and rewards interchangeable component suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite substrate manufacturing as topology-optimized carrier structures require generative design tooling and correlated finite element modeling infrastructure. Long-term viability over the next decade favors acquirers of mechatronic-capable module integrators with established OEM direct relationships. Target acquisition profiles center on Tier-1 suppliers with Spanish-Mexican manufacturing footprints sustaining just-in-sequence delivery precision. Watch for finite element analysis validation cycle compression below 12-week program gates as the inflection signal forcing consolidation among simulation-deficient molders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | REACH-compliant formulation control reduces dual-chemistry qualification burden for European supply chains. |
| Geographic Manufacturing Footprint Expansion | Co-location with OEM assembly networks in Mexico's Bajío Region sustains just-in-sequence delivery contracts. |
| Mechatronic Module Integration | Embedding window regulators and latch systems captures higher value pools through design-to-build responsibility consolidation. |
| Biomaterial Supply Partnerships | Hemp and flax fiber alliances enable carbon-negative positioning for natural fiber-reinforced thermoplastic development. |
| Topology-Optimized Carrier Investment | Generative design tooling adoption reduces prototype iterations for BMW and Mercedes-Benz flagship electric sedan programs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, dealership operations managers, and resin compounding technical leads. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA fuel economy compliance filings, ECHA REACH substance screening records, and MIIT new energy vehicle procurement specifications. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across material type, end user, functionality, and installation method dimensions.
Calibration approaches anchored volume and value outputs to disclosed OEM program volumes and supplier contract values across the projection horizon. Segmentation modeling spanned vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from slope analysis of segment-level growth trajectories. Industry-specific forecast inputs incorporated MIIT recycled content quota implementation timelines and ECHA SVHC candidate list expansion schedules.
Practitioners should monitor regulatory divergence between REACH-compliant European supply and cost-optimized Asian production for early signals of material platform fragmentation. Forecasts reflect assumptions regarding OEM direct sourcing consolidation continuity and electric vehicle platform lightweighting intensity. Material shifts in EPA fuel economy standard stringency or ECHA flame retardant restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Power Sunroof Market