
 Automotive Drawer Slides Market | 2026-2036
Automotive Drawer Slides Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Drawer Slides Market Outlook
The split between premium and commodity tiers is recalibrating as OEMs demand corrosion-resistant steel slides with integrated soft-close mechanisms while aftermarket buyers prioritize cost-optimized aluminum alternatives. Accuride International leverages its captive steel rolling capacity to anchor supply for North American truck platforms. Hettich differentiates through European-certified damping systems that sustain premium pricing in German luxury vehicle programs.
Automotive drawer slides are precision-engineered linear motion mechanisms, typically fabricated from cold-rolled steel or extruded aluminum with ball-bearing or roller-carriage architectures, designed to enable controlled extension and retraction of storage compartments under dynamic vehicle loads and vibration profiles. Heavy-duty slides dominate commercial vehicle applications where load ratings exceed 227 kilograms, while full extension variants capture the fastest growth trajectory as emergency and utility fleets demand complete drawer access without cab egress. Steel retains volume leadership in OEM channels, though aluminum is displacing legacy materials in electric vehicle platforms where mass reduction carries direct range implications.
NHTSA Federal Motor Vehicle Safety Standards govern interior projection and head-impact criteria that constrain slide geometry and release-mechanism design, while EPA corrosion testing protocols shape material selection and surface treatment specifications for under-seat and cargo-bay deployments. Stakeholders must monitor evolving FMVSS amendments for autonomous vehicle cabin reconfigurations, as removable storage modules may trigger novel occupant-restraint integration requirements that reshape slide mounting interfaces and load-path engineering.
Market Dynamics
Commercial vehicle electrification is compressing material specifications as fleet operators demand drawer slides that withstand thermal cycling from battery packs while maintaining crashworthiness under NHTSA protocols.
Growth Catalysts
- FMVSS 302 Flammability Standards:OEMs are upgrading to fire-retardant polymer-coated slides to meet federal interior burn-rate requirements, creating specification pull across heavy-duty truck platforms.
- Emergency Fleet Modernization:Fire departments and ambulance builders in Texas and Michigan are retrofitting apparatus with full-extension slides for rapid equipment access.
- Cold-Rolled Steel Advancement:Domestic mills are delivering higher-yield grades that reduce slide profile thickness without sacrificing load ratings.
Market Restraints
- Aluminum Price Volatility:LME aluminum fluctuations above historical bands are squeezing margin structures for extruded-slide fabricators serving cost-sensitive aftermarket channels.
- Supply Concentration in Great Lakes Region:Three captive steel-rolling facilities control North American coil supply for precision slide stampings, creating single-source vulnerability.
- Load-Path Engineering Constraints:NHTSA head-impact criteria limit mounting-point geometry, forcing redesign cycles that extend platform validation timelines.
Strategic Opportunities
- Autonomous Vehicle Cabin Reconfiguration:Removable storage modules for robo-taxi fleets will require quick-release slide interfaces that integrate with occupant-restraint systems.
- Indian Commercial Vehicle Build-Out:Tata Motors and Ashok Leyland are expanding cabin comfort specifications, opening specification windows for corrosion-resistant slides in monsoon climates.
- EPA Corrosion Testing Protocols:Accelerated salt-spray mandates are disqualifying legacy zinc-plated products, creating upgrade cycles for stainless-steel and polymer-coated alternatives.
Industry Challenges
- Multi-Physics Simulation Talent:Slide designers capable of modeling simultaneous vibration, thermal, and crash-load scenarios command premium compensation that mid-tier suppliers struggle to match.
- Platform-Specific Certification Burden:Each OEM truck program requires unique FMVSS validation documentation, fragmenting engineering resources across low-volume custom builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Drawer Slides Market |
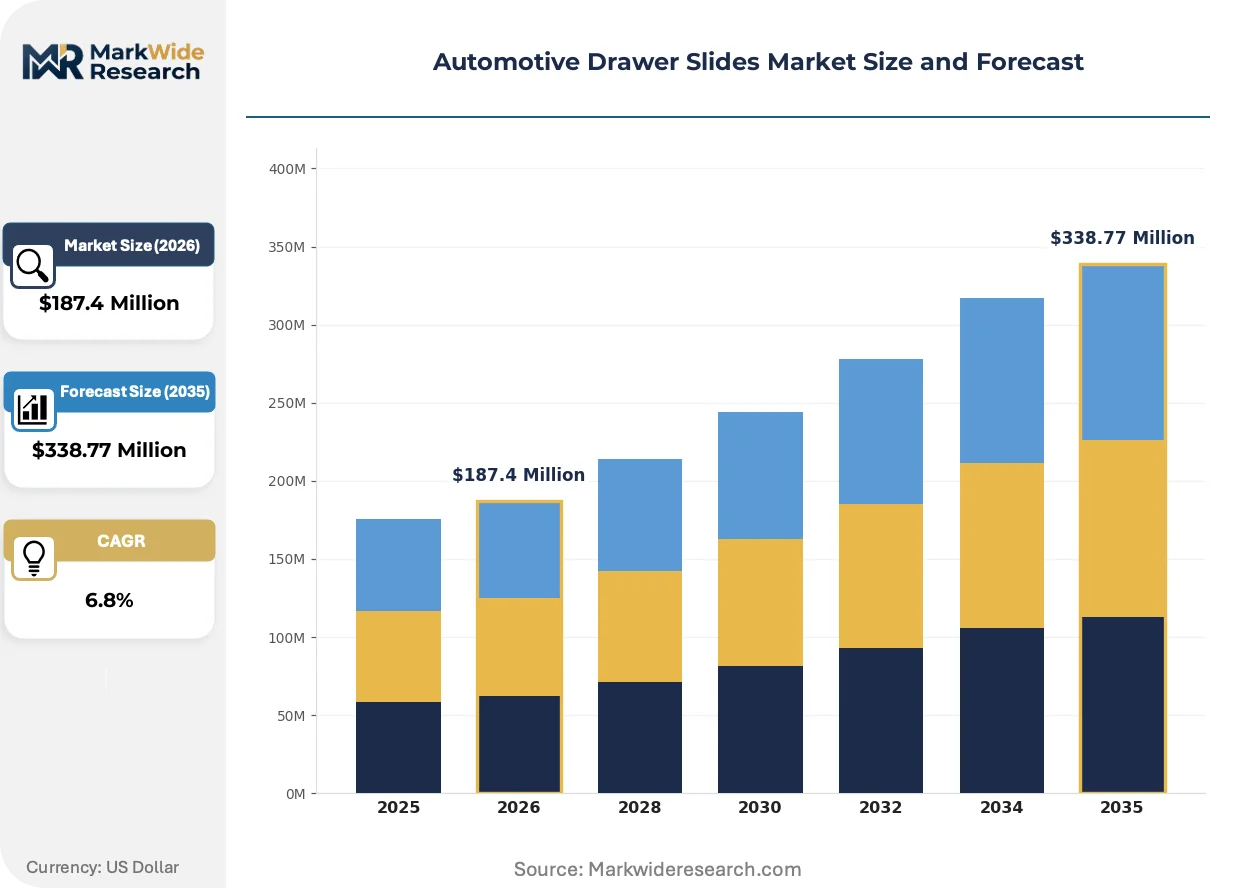
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Slides, Medium-Duty Slides, Light-Duty Slides, Full Extension Slides Installation Type: Top Mount, Side Mount, Under Mount, Bottom Mount Material: Steel, Aluminum, Plastic, Composite End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | Accuride International, Hettich, Blum Inc, King Slide Works, Knape & Vogt Manufacturing Company, Fulterer, Grass America, Sugatsune America, Jonathan Engineered Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Drawer Slides Market Strategic Shifts
Material science breakthroughs and regulatory recalibration are converging to redefine performance benchmarks for vehicular storage hardware.
Polymer-composite slide bearings are absorbing thermal expansion stresses from electric vehicle battery compartments while eliminating galvanic corrosion risks. Fleet conversion shops in California are specifying these hybrids for refrigerated delivery vans where traditional steel-aluminum interfaces degrade rapidly. The technology is absorbing specification share from plated-steel alternatives in temperature-cycled applications.
REACH substance restrictions on hexavalent chromium are forcing European suppliers to migrate toward trivalent and thin-film coating technologies. Surface treatment houses in Germany are investing in plasma-electrolytic oxidation lines to maintain corrosion resistance without restricted chemistries. German luxury OEMs are responding by tightening supplier qualification windows to eighteen months.
Direct procurement from fleet conversion specialists is compressing traditional distribution layers. Upfitters in Michigan and Texas are establishing captive specification teams that bypass regional distributors and negotiate mill-direct steel pricing. This pattern is most pronounced in emergency vehicle segments where build-to-order cycles demand configuration flexibility that stocked inventory cannot support.
Automotive Drawer Slides Market Segmentation
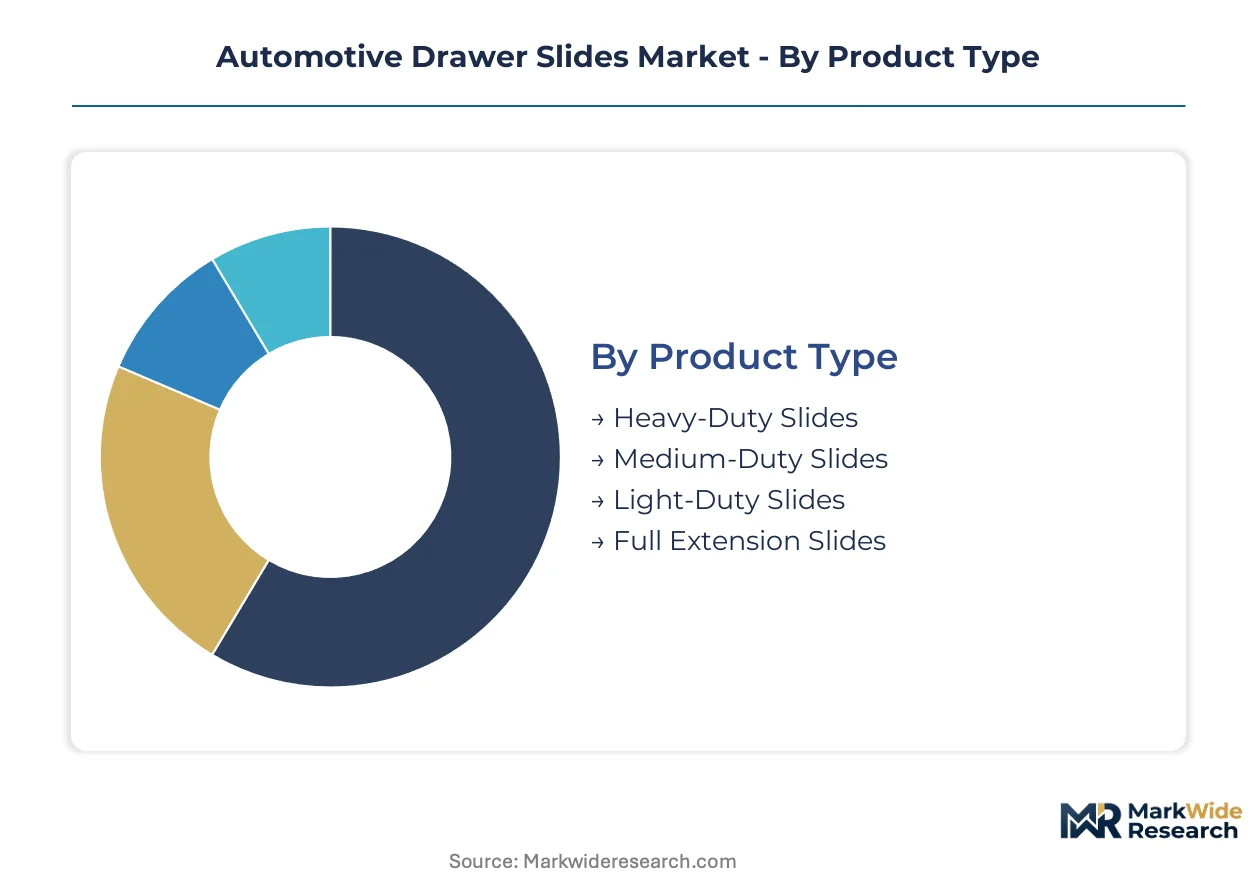
Automotive drawer slide segmentation maps directly to divergent certification burdens across commercial and passenger vehicle channels. Each category carries distinct FMVSS validation requirements, material compliance protocols, and end-user specification workflows that reshape supplier economics.
Product Type:
FMVSS 302 flammability testing and NHTSA head-impact criteria apply unevenly across load ratings, with heavy-duty variants facing the most rigorous documentation cycles.
- Heavy-Duty Slides:Fabricated from cold-rolled steel with ball-bearing carriages rated above 227 kilograms. Fleet conversion shops in Texas demand these for emergency vehicle upfits where complete equipment access must survive crash loads.
- Full Extension Slides:Enable 100 percent drawer travel without cab egress through telescoping rail architectures. Michigan-based ambulance builders specify these for rapid medical equipment retrieval under tight NHTSA interior projection limits.
- Medium-Duty Slides:Serve commercial van upfits with 100-200 kilogram ratings and integrated soft-close damping.
- Light-Duty Slides:Aluminum variants dominate passenger glove box and center console applications where mass reduction takes priority.
Leading the category by volume: Heavy-Duty Slides. Growing fastest: Full Extension Slides.
Installation Type:
Mounting geometry dictates load-path engineering complexity and platform-specific tooling investments, with side-mount configurations commanding premium engineering margins.
- Side Mount:Dominates commercial truck cabins where structural rail attachment distributes dynamic loads across cab frame members. OEMs in the United States specify these for heavy-duty platforms requiring FMVSS 302-compliant fire resistance.
- Top Mount:Enables under-seat storage modules in electric vehicles where battery thermal cycling demands corrosion-resistant interfaces. Fleet operators in California prefer these for refrigerated delivery van retrofits.
- Under Mount:Concealed rail architecture supports premium interior aesthetics in German luxury vehicle programs.
- Bottom Mount:Legacy configuration retained in aftermarket channels for cost-sensitive replacement demand.
Side Mount captures the highest engineering margins. Top Mount is climbing the fastest on electric vehicle platform adoption.
Material:
Surface treatment chemistry and substrate selection trigger divergent EPA corrosion testing and REACH substance compliance pathways.
- Steel:Cold-rolled grades with zinc or polymer coatings retain OEM channel dominance. Domestic mills in the Great Lakes region supply higher-yield grades that reduce profile thickness without sacrificing load ratings under NHTSA protocols.
- Aluminum:Extruded profiles displace legacy materials in electric vehicle platforms where mass reduction carries direct range implications. LME price volatility squeezes margin structures for aftermarket fabricators.
- Plastic:Polymer-composite bearings absorb thermal expansion stresses from battery compartments while eliminating galvanic corrosion risks.
- Composite:Hybrid constructions emerging for temperature-cycled applications in refrigerated transport.
Steel leads by installed base. Aluminum is expanding most quickly on electrification-driven lightweighting mandates.
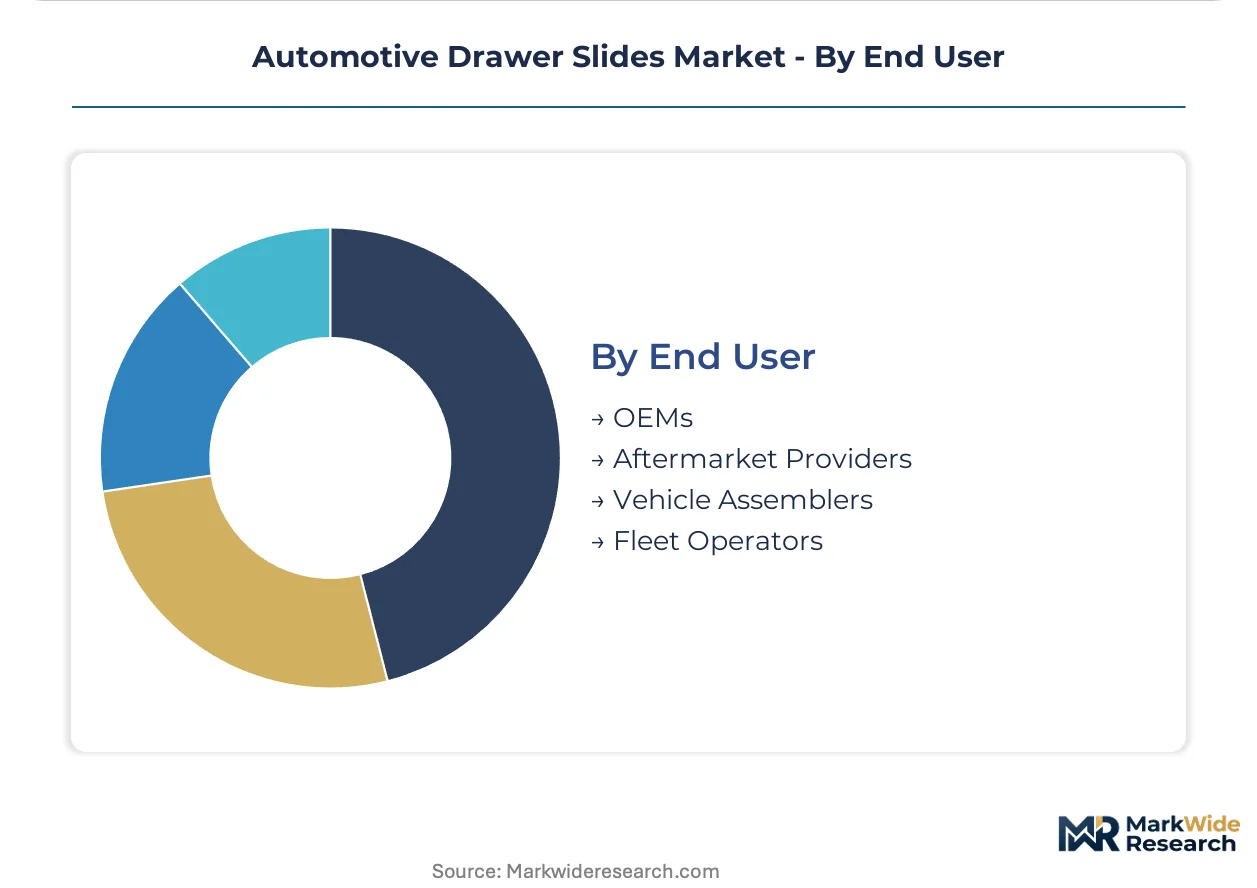
End User:
Procurement authority fragmentation creates tiered pricing structures across direct OEM supply, fleet conversion, and aftermarket replacement channels.
- OEMs:Direct platform integration demands 18-24 month qualification cycles with unique FMVSS validation documentation per truck program. Steel slides with integrated damping command specification preference.
- Fleet Operators:Emergency and utility fleets in Texas and Michigan drive full-extension slide demand through build-to-order upfit cycles that bypass traditional distribution layers.
- Aftermarket Providers:Cost-optimized aluminum alternatives serve price-sensitive replacement demand through regional distributor networks.
- Vehicle Assemblers:Contract manufacturers serving Indian commercial vehicle build-outs specify corrosion-resistant slides for monsoon climate durability.
OEMs lead by contract value. Fleet Operators are gaining share fastest on direct procurement compression of distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's fleet conversion corridor anchors North American demand for heavy-duty drawer slides, with upfitters in Warren and Livonia driving specification pull for crash-rated storage systems in emergency vehicle platforms.
United States
Emergency fleet modernization in Texas and Michigan consumes full-extension slides rated above 227 kilograms for rapid equipment access. NHTSA Federal Motor Vehicle Safety Standards govern interior projection limits that constrain mounting-point geometry. Fleet operators in Houston and Dallas bypass traditional distribution layers to negotiate mill-direct steel pricing for build-to-order ambulance upfits.
Germany
Luxury OEM programs demand under-mount concealed rail architectures with European-certified damping systems. REACH substance restrictions on hexavalent chromium force migration toward trivalent coating technologies. Surface treatment houses in Stuttgart and Munich invest in plasma-electrolytic oxidation lines to maintain corrosion resistance without restricted chemistries.
China
Commercial vehicle electrification compresses material specifications as domestic OEMs prioritize mass-reduction strategies for battery-electric platforms. GB standards and MIIT regulations shape domestic certification pathways for cabin interior components. Precision slide fabricators in the Yangtze River Delta supply cold-rolled steel variants to regional truck manufacturers expanding export programs.
India
Tata Motors and Ashok Leyland expand cabin comfort specifications, opening procurement windows for corrosion-resistant slides in monsoon climate durability. BIS certification requirements govern material compliance for commercial vehicle interior hardware. Vehicle assemblers in Maharashtra and Tamil Nadu specify stainless-steel alternatives to displace legacy zinc-plated products in temperature-cycled applications.
Japan
Automotive OEMs integrate polymer-composite slide bearings to absorb thermal expansion stresses from battery compartments in electric vehicle platforms. METI industrial policy supports lightweighting mandates that accelerate aluminum displacement of legacy steel materials. Precision component suppliers in the Nagoya industrial corridor deliver integrated soft-close mechanisms for premium center console applications.
Automotive Drawer Slides Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered supply structures. Steel-rolling facilities with captive coil supply anchor OEM channel relationships through eighteen-month qualification cycles. Three strategic archetypes dominate: integrated mills controlling upstream material flow, specialized damping-system engineers commanding premium pricing, and regional fabricators serving cost-sensitive aftermarket replacement demand. Competitive moves concentrate on backward integration into steel rolling capacity and geographic expansion through fleet conversion direct procurement relationships.
Among North American fabricators, Accuride International occupies a position within the integrated-production archetype, while Hettich GmbH exemplifies the European-certified damping-system specialist tier. King Slide Works represents the Asia-Pacific scale-driven segment. These three anchors illustrate how supplier economics fragment across material control, regulatory certification, and regional manufacturing density rather than converging on uniform competitive strategies.
| Leading Market Players |
|---|
| Accuride International |
| Hettich |
| Blum Inc |
| King Slide Works |
| Knape & Vogt Manufacturing Company |
| Fulterer |
| Grass America |
| Sugatsune America |
| Jonathan Engineered Solutions |
| Others |
Value Chain & Pricing Dynamics
Fleet conversion shops in Texas and Michigan demanding mill-direct steel pricing for build-to-order emergency vehicle upfits are compressing traditional distribution markups and forcing suppliers to absorb logistics costs or cede specification control to captive procurement teams.
Pricing Analysis
Load-rating certification anchors value-based pricing, with FMVSS 302-compliant heavy-duty slides commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates OEM-grade steel slides with integrated damping from aftermarket aluminum variants and bare-bones replacement hardware. Cost compression in the aftermarket tier is intensifying because LME aluminum volatility above historical bands squeezes extruded-slide fabricator margins. Fleet operators exhibit the highest price sensitivity, while German luxury OEMs accept premium positioning for European-certified damping systems.
Supply Chain Analysis
Regional distribution centers in the Great Lakes corridor feed precision stamping operations through hub-and-spoke patterns anchored by captive steel-rolling facilities. Coil supply draws from domestic mills in Michigan, Ohio, and Indiana, with surface treatment chemistries sourced from German and Japanese specialty chemical houses. Single-source vulnerability concentrates in three Great Lakes rolling mills controlling North American precision slide substrate. Distribution runs through direct procurement relationships with fleet upfitters bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive steel-rolling capacity to secure substrate supply and defend specification relationships through eighteen-month OEM qualification cycles.
For Market Incumbents: Acquire cold-rolled steel rolling assets to anchor substrate supply for North American truck platforms. Lock in multi-year coating chemistry contracts with German surface treatment houses before REACH restriction windows tighten. Defend against emerging polymer-composite substitutes by accelerating fire-retardant certification timelines under FMVSS 302 protocols. For New Entrants and Emerging Players: Begin with corrosion-resistant stainless-steel alternatives targeting Indian commercial vehicle build-outs where monsoon climate durability creates specification openings. Focus on Tata Motors and Ashok Leyland expansion programs as the most penetrable demand cluster. Establish direct technical sales presence in Maharashtra and Tamil Nadu vehicle assembly corridors rather than distributor relationships. For Investors and Strategic Acquirers: The window for entry favors integrated mills with captive coil supply and established OEM qualification documentation. Five-to-ten-year viability rests on backward integration depth rather than component-level specialization. Watch NHTSA autonomous vehicle cabin reconfiguration rulemaking as the signal for quick-release slide interface demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Captive coil supply secures eighteen-month OEM qualification relationships against spot-market volatility. |
| Fire-Retardant Coating Certification | FMVSS 302 compliance opens heavy-duty truck platform specifications previously closed to uncertified competitors. |
| Direct Fleet Procurement Relationships | Texas and Michigan upfitter bypass of distribution layers captures margin compression from build-to-order cycles. |
| Polymer-Composite Bearing Development | Temperature-cycled electric vehicle battery compartments favor hybrids over galvanic-corrosion-prone steel-aluminum interfaces. |
| Plasma-Electrolytic Oxidation Investment | German surface treatment houses maintain corrosion resistance without REACH-restricted hexavalent chromium chemistries. |
Study Parameters
Document review covered NHTSA FMVSS amendment dockets, EPA corrosion testing protocols, and REACH substance restriction filings, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, fleet conversion shop operations managers, and aftermarket distribution channel heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, steel mill shipment reports, and aluminum trade flow statistics. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions across the analysis window.
Segmentation outputs reflect modeling across product type, installation configuration, material substrate, and end-user procurement channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical specification rates against fleet electrification penetration curves and commercial vehicle build-out trajectories. Load-rating certification timelines and surface treatment chemistry transition schedules served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; heavy-duty OEM-channel volumes carry tighter precision than fragmented aftermarket replacement demand. Forecasts reflect documented assumptions regarding NHTSA rulemaking schedules, LME aluminum price bands, and REACH enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market