
 South Africa Automotive Thermoplastic Polymer Composites Market | 2026-2036
South Africa Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Thermoplastic Polymer Composites Market Analytics
Parts distribution from Durban and Port Elizabeth into OEM assembly plants is rewriting supply chain economics for composite feedstock. DuPont de Nemours leverages its polymer science heritage to anchor technical partnerships with tier-one suppliers in Rosslyn and Uitenhage. Celanese Corporation competes through specialized polyamide grades engineered for under-the-hood thermal stability. SABIC dominates regional resin supply with backward integration into propylene feedstock from its Saudi operations.
Automotive thermoplastic polymer composites combine continuous or discontinuous fiber reinforcement—typically glass or carbon—with thermoplastic matrices such as polypropylene, polyamide, polycarbonate, or ABS, processed via injection molding, extrusion, thermoforming, or blow molding to achieve specific strength-to-weight ratios and recyclability. These materials serve primarily to reduce vehicle mass while maintaining structural integrity and enabling end-of-life material recovery. Polypropylene leads product type demand due to its cost position and established recycling infrastructure across the Western Cape and KwaZulu-Natal manufacturing corridors. Electric vehicles represent the fastest-expanding end user category as battery pack enclosures and thermal management housings drive specification upgrades. Injection molding captures the dominant technology share for interior components where dimensional precision and surface finish requirements are most stringent.
The National Regulator for Compulsory Specifications and the South African Bureau of Standards shape material approval pathways through mandatory vehicle safety and environmental compliance testing, while OEM internal sustainability protocols increasingly require recycled content thresholds in composite specifications. South Africa's automotive production and development programme incentives further condition sourcing decisions by linking duty rebates to local value-add benchmarks. Stakeholders must monitor evolving EU-SADC trade agreement rules of origin and their cascading impact on composite material qualification for export-bound vehicle platforms.
Market Dynamics
The National Regulator for Compulsory Specifications is compressing material qualification timelines while mandating higher recycled content thresholds, forcing compounders to revalidate formulations against crashworthiness and thermal stability benchmarks simultaneously.
Growth Catalysts
- Electric vehicle battery enclosures:Gauteng-based OEMs specify glass-reinforced polypropylene for thermal management housings to offset battery pack mass.
- Automotive Production and Development Programme:Duty rebates tied to local value-add benchmarks incentivize domestic compounding capacity expansion.
- Injection molding automation:Tier-one suppliers in Rosslyn deploy robotic cell integration to reduce cycle times for interior component production.
Market Restraints
- Propylene feedstock concentration:SABIC's Saudi supply dominance creates single-source exposure for regional resin procurement.
- Carbon fiber cost structure:Continuous fiber grades remain economically inaccessible for mass-market light truck applications.
- Recyclability verification friction:The South African Bureau of Standards lacks harmonized testing protocols for multi-material composite streams.
Strategic Opportunities
- KwaZulu-Natal manufacturing corridor:Underutilized compounding capacity near Durban port infrastructure offers export platform potential.
- EU-SADC rules of origin alignment:Composite material qualification for export-bound vehicle platforms opens duty-advantaged supply contracts.
- Hybrid natural fiber blends:Sisal and hemp reinforcement integration addresses sustainability protocols while reducing glass fiber dependence.
Industry Challenges
- Polymer processing technician scarcity:Specialized skills for long-fiber thermoplastic molding remain concentrated in Uitenhage and Rosslyn industrial clusters.
- Multi-material bonding certification:OEM validation timelines for dissimilar substrate adhesion extend qualification cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Thermoplastic Polymer Composites Market |
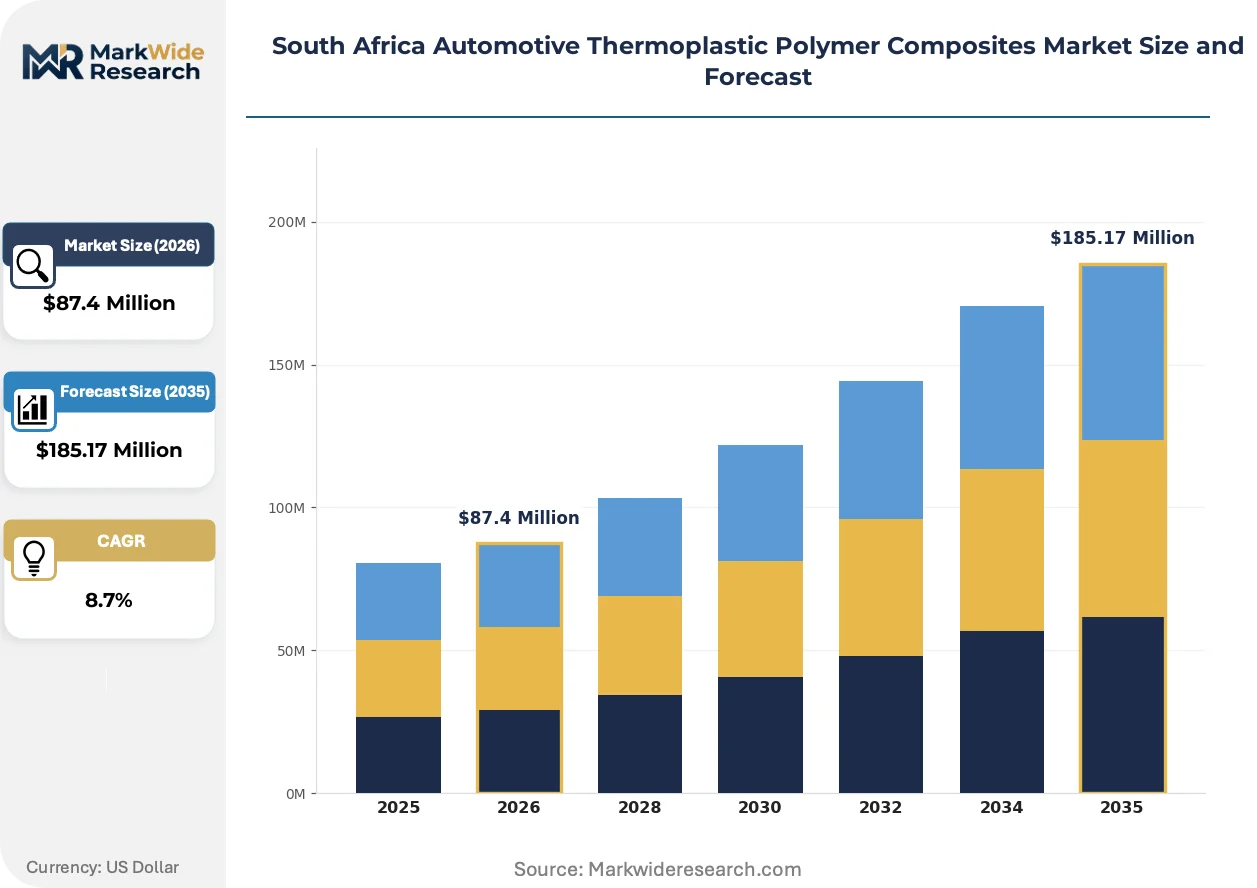
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Polycarbonate, Acrylonitrile Butadiene Styrene End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Light Trucks Technology: Injection Molding, Extrusion, Thermoforming, Blow Molding Application: Interior Components, Exterior Panels, Structural Parts, Under-the-Hood Components |
| Companies Covered | 3B Fiberglass, DuPont de Nemours, Celanese Corporation, Arkema Group, Technocompound GmbH, Cytex Industries Inc, Polyone Corporation, Hexcel Corporation, SABIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Thermoplastic Polymer Composites Market Evolving Landscape
Material science convergence with automated manufacturing is compressing development cycles while regulatory pressure on recyclability is redefining specification criteria across the value chain.
Long-fiber-reinforced thermoplastic direct compounding is rendering obsolete conventional pellet-based supply chains. Tier-one suppliers in the Western Cape corridor are adopting in-line extrusion to fiber lengths exceeding 25 millimeters for structural interior components. This shift is compressing logistics costs and enabling real-time formulation adjustments based on OEM lot-specific requirements.
The National Regulator for Compulsory Specifications has enacted mandatory recycled content disclosure for vehicle interior trim components. Compounders must now submit third-party verified mass balance documentation prior to platform qualification. Suppliers serving export-bound assembly in Port Elizabeth are prioritizing post-industrial polypropylene stream integration to preempt EU regulatory alignment pressures.
Fleet procurement departments are consolidating specification authority previously dispersed across engineering and purchasing functions. Single-point material approval gates in Gauteng OEM headquarters are compressing supplier negotiation cycles while elevating technical service capabilities as selection criteria. This concentration is most visible in battery electric vehicle programs where thermal management material decisions carry platform-wide warranty implications.
South Africa Automotive Thermoplastic Polymer Composites Market Segmentation
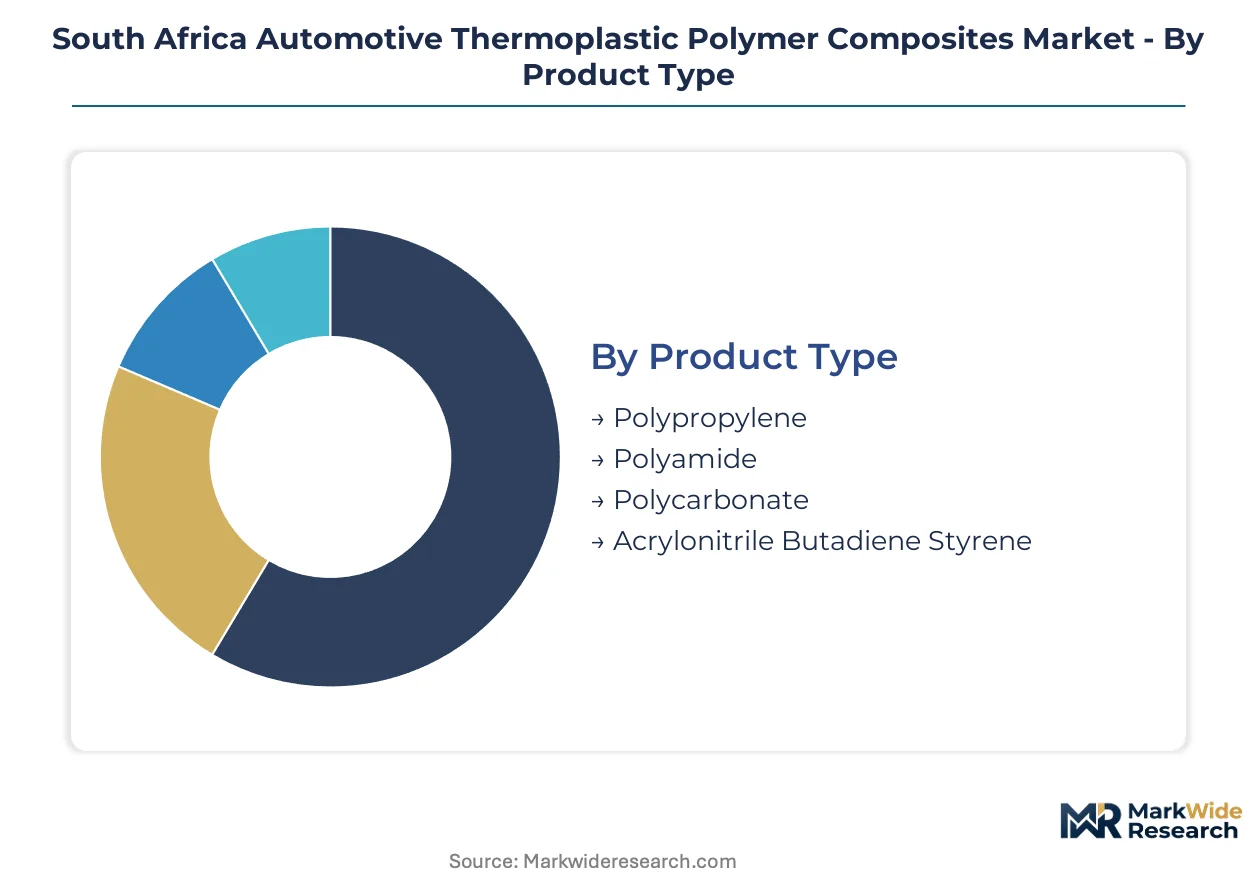
Segmentation reveals how material specifications diverge across South Africa's automotive value chain. Technical requirements for battery enclosures differ sharply from interior trim standards, while processing economics favor injection molding for high-volume Gauteng assembly.
Product Type:
After-sales service intensity varies dramatically by resin chemistry—polypropylene compounds require routine reformulation support, while specialized polyamide grades demand thermal stability troubleshooting at OEM technical centers.
- Polypropylene:Glass-reinforced formulations dominate interior applications with established recycling infrastructure across Western Cape and KwaZulu-Natal corridors. Rosslyn assembly plants specify this grade for dashboard carriers and door panels where cost efficiency and post-consumer recyclability intersect.
- Polyamide:Engineered for under-the-hood thermal stability in battery management systems and engine bay components. Gauteng-based electric vehicle programs drive specification upgrades as thermal management housing requirements intensify.
- Polycarbonate:Optical-grade clarity serves instrument cluster lenses and transparent trim elements with UV stabilization protocols.
- Acrylonitrile Butadiene Styrene:Surface finish quality supports decorative interior elements where paintability and scratch resistance matter.
By volume, Polypropylene leads. By growth pace, Polyamide is gaining share fastest as thermal management demands escalate.
End User:
Volume concentration shapes procurement patterns—passenger vehicle platforms generate batch production economics, while electric vehicle programs demand lot-specific qualification cycles.
- Passenger Vehicles:High-volume interior component specifications dominate compounding capacity allocation across Uitenhage and Rosslyn supplier parks. Tier-one molders achieve cycle time compression through robotic cell integration for door panels and seat structures.
- Electric Vehicles:Battery pack enclosures and thermal management housings require glass-reinforced polypropylene with flame-retardant grades. The National Regulator for Compulsory Specifications mandates crashworthiness validation for these structural applications.
- Commercial Vehicles:Durability specifications prioritize abrasion resistance for cabin interiors with extended service life requirements.
- Light Trucks:Payload-optimized structural components balance weight reduction with cost discipline in fleet procurement cycles.
Passenger Vehicles anchor volume throughput. Electric Vehicles show the steepest expansion trajectory as Gauteng OEMs accelerate platform launches.
Technology:
Capital intensity separates processing tiers—injection molding cell automation commands premium tooling investment, while extrusion lines serve commodity profiles.
- Injection Molding:Robotic integration enables dimensional precision for complex interior geometries with cycle times compressed below 60 seconds. Tier-one suppliers in the Western Cape corridor deploy long-fiber direct compounding for structural seat carriers.
- Extrusion:Continuous profile production serves bumper beams and structural reinforcements with fiber orientation control.
- Thermoforming:Sheet-based processing produces large exterior panels with moderate tooling cost for low-volume commercial vehicle applications.
- Blow Molding:Hollow structural elements including fluid reservoirs and ducting components with blow-pin precision requirements.
Injection Molding captures the dominant equipment footprint. Thermoforming is expanding most quickly for exterior panel lightweighting initiatives.
Application:
Specification authority concentrates differently by vehicle zone—interior trim decisions flow through single-point procurement gates, while structural applications require cross-functional engineering validation.
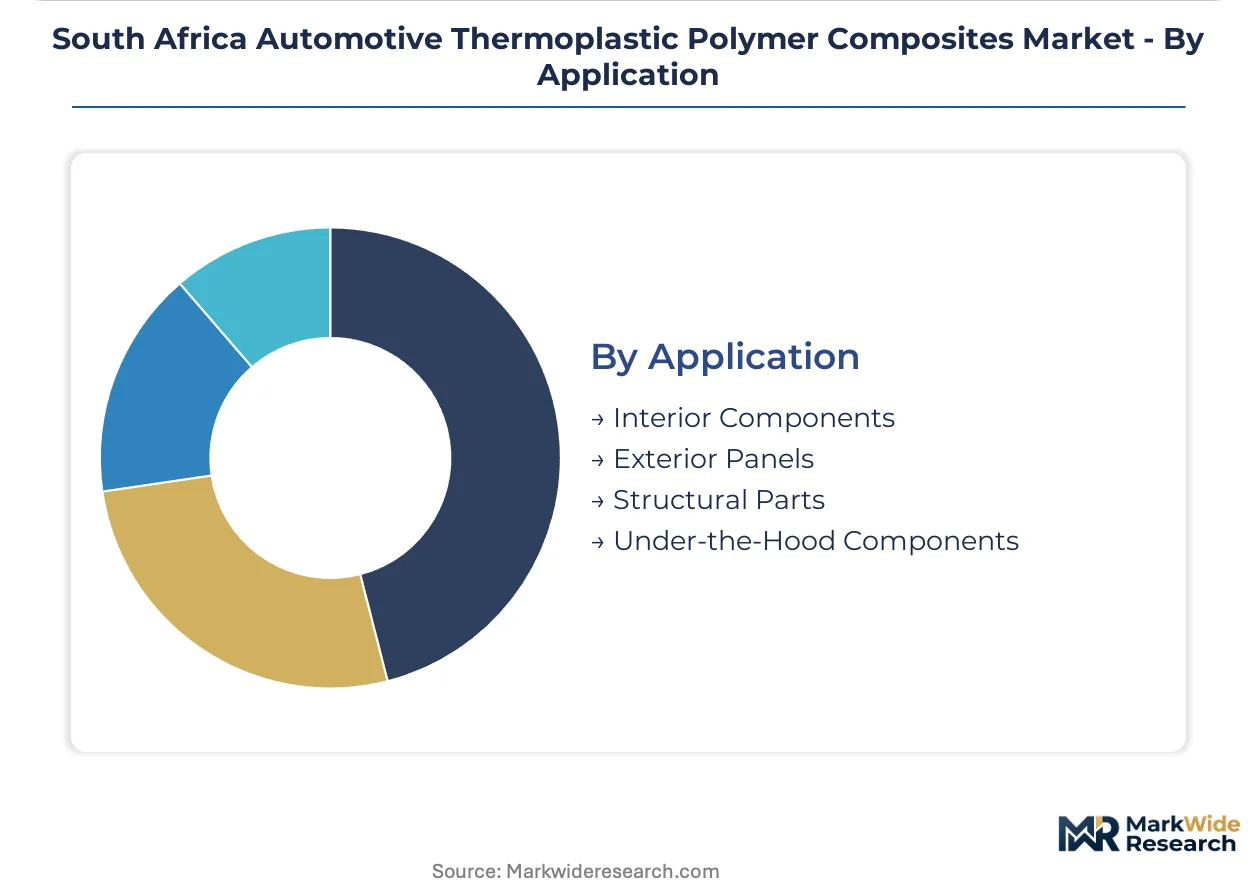
- Interior Components:Dashboard carriers, door panels, and seat structures demand Class A surface finish with recycled content disclosure mandated by the National Regulator for Compulsory Specifications. Post-industrial polypropylene stream integration satisfies mass balance verification requirements.
- Under-the-Hood Components:Thermal management housings and battery enclosures require continuous service temperature resistance above 120°C. Electric vehicle programs in Gauteng specify glass-reinforced grades with OEM warranty implications.
- Exterior Panels:Fender liners and bumper fascias balance impact resistance with paint adhesion properties.
- Structural Parts:Load-bearing reinforcements demand long-fiber reinforcement exceeding 25 millimeters for crash energy management.
Interior Components command the broadest compounding volume. Under-the-Hood Components are climbing the fastest as thermal management specifications intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Durban-Gauteng freight rail corridor and N3 highway link underpin South Africa's automotive materials distribution, moving composite feedstock from KwaZulu-Natal port terminals to inland assembly clusters.
Gauteng Province
Electric vehicle battery enclosure demand from Rosslyn and Silverton assembly plants drives specification upgrades for glass-reinforced polypropylene. The National Regulator for Compulsory Specifications enforces crashworthiness validation for thermal management housings. Tshwane supplier parks concentrate tier-one injection molding capacity for interior components.
Western Cape
Long-fiber thermoplastic direct compounding adoption accelerates for structural seat carriers and dashboard substrates. The South African Bureau of Standards mandates recycled content disclosure for interior trim qualification. Cape Town-Stellenbosch manufacturing corridor hosts specialized compounding operations serving export-bound platforms.
Eastern Cape
Port Elizabeth vehicle assembly generates batch production economics for bumper beam and exterior panel extrusion. Automotive Production and Development Programme duty rebates condition local value-add thresholds for composite sourcing. Uitenhage supplier cluster maintains concentrated polymer processing technician skills.
KwaZulu-Natal
Durban port infrastructure enables propylene resin import and compound export positioning. Underutilized compounding capacity near harbor terminals offers duty-advantaged supply contract potential for EU-SADC trade corridor alignment. Richards Bay industrial zone attracts backward-integrated resin distribution investments.
South Africa Automotive Thermoplastic Polymer Composites Market Competitive Landscape
On the supply side, the industry is bifurcated between resin producers with feedstock control and specialized compounders with formulation expertise. DuPont de Nemours anchors technical partnerships through polymer science heritage, while SABIC dominates regional resin supply. Celanese Corporation occupies the specialized polyamide tier for thermal stability applications. Competitive moves concentrate on strategic partnerships with tier-one suppliers and capacity expansion near OEM assembly clusters.
Among global resin and compound producers, DuPont de Nemours, SABIC, and Celanese Corporation exemplify the three archetypes shaping supply dynamics. DuPont de Nemours represents the integrated materials science conglomerate with heritage technical partnerships. SABIC anchors the feedstock-integrated supply position through propylene backward integration. Celanese Corporation occupies the specialized engineering polymer tier with thermal stability focus. Each archetype addresses distinct specification vectors across interior, under-the-hood, and structural applications.
| Leading Market Players |
|---|
| 3B Fiberglass |
| DuPont de Nemours |
| Celanese Corporation |
| Arkema Group |
| Technocompound GmbH |
| Cytex Industries Inc |
| Polyone Corporation |
| Hexcel Corporation |
| SABIC |
| Others |
Value Network & Pricing Analysis
SABIC's Saudi propylene feedstock dominance compresses pricing tier spreads while tethering regional compounders to single-source resin procurement. This concentration forces tier-one suppliers to absorb volatility pass-through or renegotiate long-term offtake terms, reshaping both cost structures and inventory positioning across Gauteng assembly corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specialized polyamide thermal stability grades from commodity polypropylene compounds. Price differentiation hinges on certification grade under National Regulator for Compulsory Specifications protocols and volume scale for OEM platform contracts. Cost compression in standard-grade polypropylene is intensifying because SABIC's regional resin supply commands premium logistics premiums. Fleet procurement departments at light truck OEMs exhibit highest price sensitivity, while electric vehicle thermal management programs show lowest sensitivity due to warranty-critical performance requirements.
Supply Chain Analysis
Tariff exposure between South Africa and EU member states dominates supply chain risk calculus for export-bound composite qualification. Feedstock sourcing draws from Saudi Arabia for propylene monomer, China for glass fiber roving, and Germany for specialized compounding equipment. Single-source vulnerability concentrates in SABIC's backward-integrated resin supply. Distribution runs through Durban port terminals into the N3 highway corridor serving Rosslyn and Uitenhage assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compounders should treat formulation support services as the primary attach layer, since reformulation cycles for recycled content compliance now outpace base resin volume growth. Technical service contracts tied to National Regulator for Compulsory Specifications validation timelines represent the fastest-expanding recurring revenue stream.
For Market Incumbents:Pre-empt emerging natural fiber hybrid competition by locking long-term sisal supply contracts with KwaZulu-Natal agricultural cooperatives. Deepen backward integration into post-industrial polypropylene stream collection across Western Cape manufacturing corridors to defend margin position against recycled content mandates.
For New Entrants and Emerging Players:Build out underutilized compounding capacity near Richards Bay industrial zone to capture EU-SADC duty-advantaged export contracts. The KwaZulu-Natal manufacturing corridor offers the most penetrable geographic white space, with port infrastructure enabling both resin import and compound export positioning. A technical partnership route with established tier-one molders accelerates platform qualification without capital-intensive OEM direct sales investment.
For Investors and Strategic Acquirers:National Regulator for Compulsory Specifications recycled content disclosure mandates reshape the acquisition landscape toward compounders with verified mass balance infrastructure. Long-term viability across the projection horizon favors targets with in-house long-fiber direct compounding capability and established OEM technical center relationships. Monitor EU-SADC rules of origin renegotiation progress as the signal indicating export platform qualification value inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Fiber Direct Compounding Capacity Expansion | In-line extrusion exceeding 25 millimeters compresses logistics costs for Rosslyn tier-one suppliers. |
| Post-Industrial Polypropylene Stream Integration | Mass balance documentation satisfies National Regulator for Compulsory Specifications disclosure mandates ahead of EU alignment. |
| Hybrid Natural Fiber Blend Development | Sisal and hemp reinforcement reduces glass fiber dependence while addressing OEM sustainability protocols. |
| EU-SADC Rules of Origin Alignment Investment | Composite material qualification unlocks duty-advantaged supply contracts for Port Elizabeth export platforms. |
| Robotic Injection Molding Cell Automation | Cycle time compression below 60 seconds enables high-volume interior component economics at Uitenhage supplier parks. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, compounder technical directors, and National Regulator for Compulsory Specifications compliance officers, and refined through secondary validation against vehicle production databases, customs and trade flow records, Automotive Production and Development Programme incentive disclosures, and South African Bureau of Standards technical bulletins. Bottom-up volume modeling across resin grades and top-down market sizing triangulated to convergence thresholds.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type chemistry, vehicle propulsion architecture, processing technology capital intensity, and application thermal requirements. CAGRs derived from fitted growth curves applied to platform launch timelines and regulatory compliance phase-in schedules. Battery electric vehicle content-per-vehicle assumptions and injection molding automation penetration curves served as industry-specific forecast inputs.
Stress conditions across propylene feedstock price volatility, EU-SADC trade agreement renegotiation outcomes, and polymer processing technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory phase-in adherence and OEM platform launch execution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Rear Axle Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
RV Battery Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
2 Wheeler Fuel Injection System Market