
 Sheet Molding Compound (SMC) for Automotive Market | 2026-2036
Sheet Molding Compound (SMC) for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Molding Compound (SMC) for Automotive Market Insights
Modular SMC preform kits is rebalancing procurement patterns across OEM and Tier-1 supply chains. BASF leverages its resin chemistry portfolio to anchor European supply relationships for high-performance grades. Continental Structural Plastics specializes in Class A body panel formulations that dominate North American truck and SUV programs. Mitsubishi Chemical Advanced Materials extends its Asia-Pacific manufacturing footprint to serve Japanese OEM lightweighting roadmaps.
Sheet Molding Compound for Automotive is a fiber-reinforced thermoset material typically comprising 25-30% glass fiber in an unsaturated polyester or vinyl ester matrix, press-molded at 120-160°C to produce high-strength, low-density components primarily for vehicle weight reduction and corrosion resistance. SMC Sheet formulations occupy the largest volume share across body panel applications where surface finish requirements are most demanding. Structural Parts represents the fastest-expanding application segment as OEMs substitute stamped metal with load-bearing composite designs in electric vehicle platforms. Preforms command premium positioning within the supply chain by reducing cycle times and material waste for complex geometries.
The EPA and NHTSA coordinate fuel-economy and safety standards that directly incentivize mass reduction through advanced materials substitution in light-duty vehicles. REACH and the EU Green Deal impose chemical disclosure and recyclability requirements that reshape resin formulation strategies and supplier qualification protocols across European automotive value chains. Stakeholders must monitor evolving battery enclosure fire-resistance standards and end-of-life composite recovery mandates to anticipate qualification timelines and capital allocation priorities.
Market Dynamics
Electric vehicle platform architectures are compressing material qualification timelines as OEMs redesign body-in-white structures around multi-material load paths. Battery enclosure fire-resistance standards are forcing simultaneous lightweighting and thermal management solutions that thermoset composites uniquely address.
Growth Catalysts
- EPA Fuel-Economy Standards:Corporate Average Fuel Economy mandates tighten vehicle weight targets, accelerating stamped metal substitution in hoods, decklids, and structural reinforcements.
- Carbon Fiber Hybrid SMC:Intermediate-modulus fiber blends penetrate premium EV architectures where specific stiffness requirements exceed conventional glass-reinforced grades.
- German OEM Integration:BMW and Mercedes-Benz multi-material roadmaps anchor European demand concentration for Class A surface-capable formulations.
Market Restraints
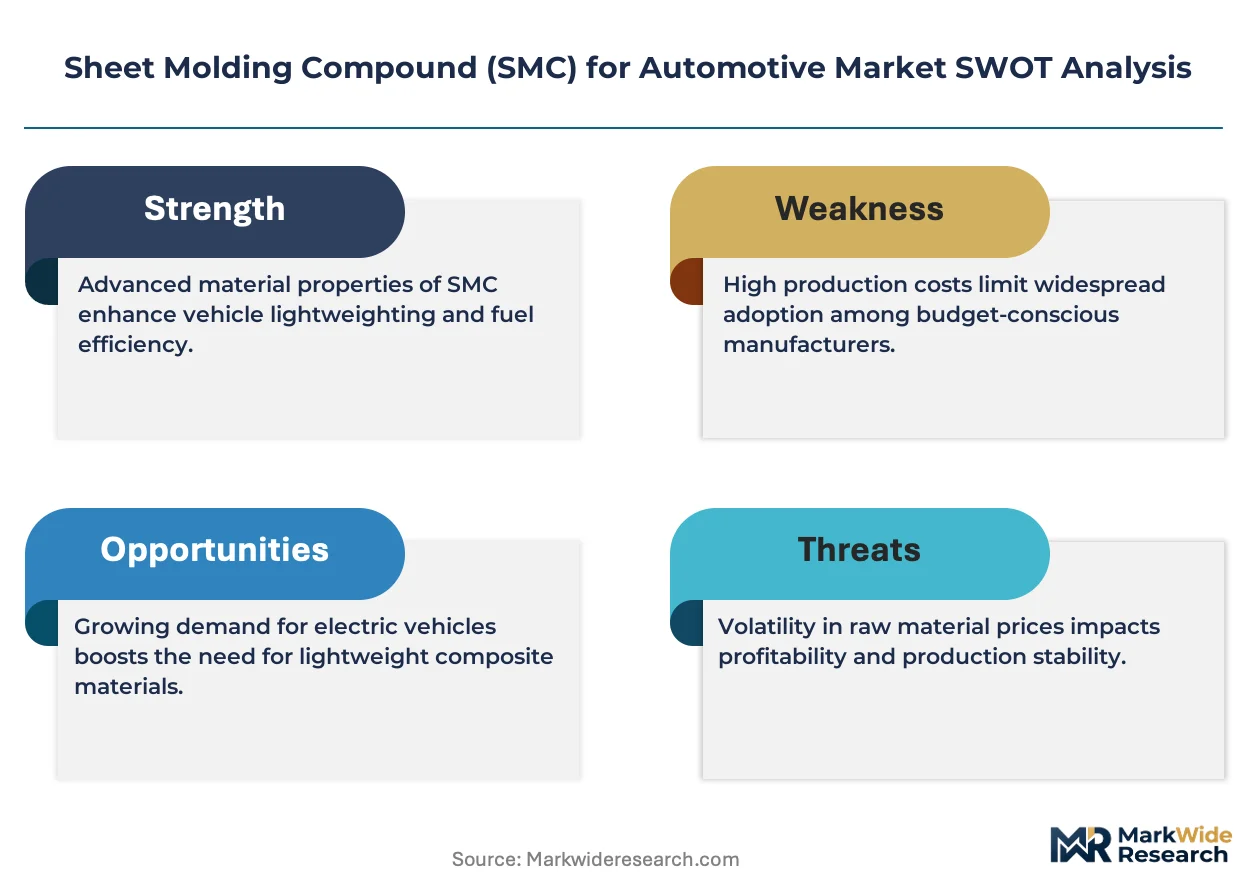
- Petrochemical Input Volatility:Unsaturated polyester resin costs track propylene and styrene monomer spreads, compressing compounder margins during upstream price spikes.
- Tooling Capex Intensity:Compression molds for SMC body panels require hardened steel cavities and heated platens that amortize across 200,000+ unit programs.
- Thermoplastic Substitution:Long-fiber-reinforced polypropylene compounds challenge SMC in non-Class A structural applications with faster cycle times and recyclability.
Strategic Opportunities
- India EV Localization:PLI scheme incentives for advanced chemistry cell manufacturing create adjacent demand for domestic SMC battery enclosure supply.
- EU Green Deal Recyclability Mandates:End-of-life vehicle directives pressure resin formulators toward recyclable thermoset chemistries and fiber recovery processes.
- Direct-to-OEM Preform Supply:Net-shape preform kits bypass Tier-1 compounders, capturing margin through reduced scrap and compressed molding cycle times.
Industry Challenges
- Fire-Resistance Certification Timelines:UL 2596 and UN ECE R100 battery enclosure thermal runaway protocols extend qualification cycles by 18-24 months.
- Multi-Material Joining Expertise:Adhesive selection and process control for SMC-to-aluminum bonding require specialized engineering capabilities scarce in legacy metal-stamping supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Molding Compound (SMC) for Automotive Market |
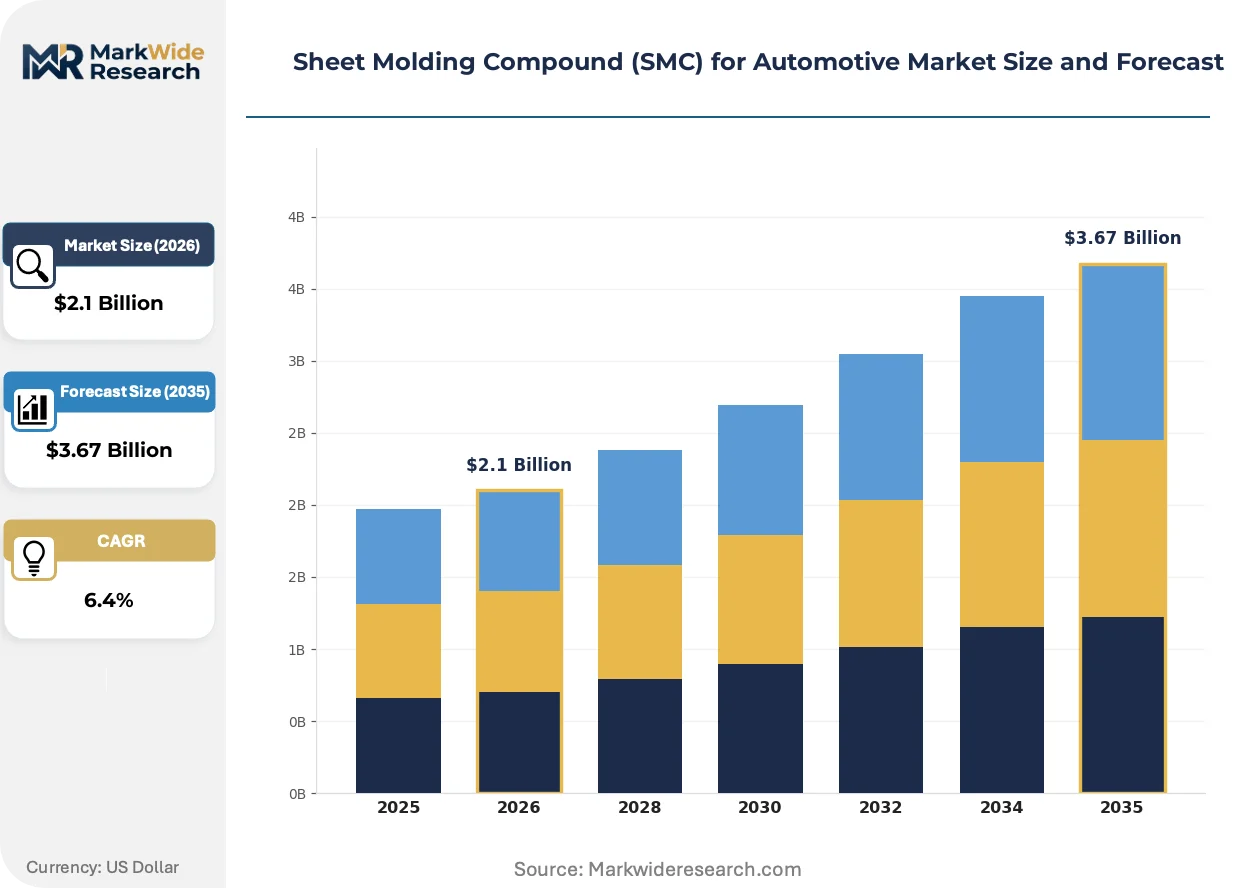
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SMC Sheet, Preforms, Bulk Molding Compound, Custom Molding Compound End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Body Panels, Interior Trim, Underbody Components, Structural Parts Distribution Channel: Direct Sales, Distributors, Online Retail, Manufacturers |
| Companies Covered | Continental Structural Plastics, BASF, IDI Composites International, Core Molding Technologies, Mitsubishi Chemical Advanced Materials, Menzolit Kunststoffwerk GmbH, Polynt Composites, Changzhou RealLand Composite Material Technology Co., Ltd., Union Composites Changzhou Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Molding Compound (SMC) for Automotive Market Trends and Innovations
Material-science convergence with digital manufacturing is redefining how fiber-reinforced thermosets enter vehicle architectures. Three developments dominate current investment priorities.
Low-density SMC formulations with hollow glass microspheres are absorbing structural roles previously reserved for aluminum extrusions. Tier-1 suppliers adopt these grades for battery tray reinforcements and cross-car beams where mass reduction targets exceed 40% versus stamped steel. The technology is compressing the traditional metal-to-composite cost gap in load-bearing applications.
REACH chemical disclosure requirements are reshaping resin formulation strategies across European automotive value chains. ECHA substance of very high concern listings restrict certain cobalt-based cure promoters, forcing compounders toward alternative peroxide initiation systems. German OEM qualification protocols now mandate full supply chain chemical transparency down to raw material suppliers.
Modular preform kit procurement is displacing bulk SMC sheet purchasing in complex geometry programs. Tier-1 molders receive net-shape charges cut to final part轮廓, eliminating trimming waste and reducing press cycle times. This pattern concentrates most visibly in North American truck and SUV body panel programs where annual volumes exceed 100,000 units.
Sheet Molding Compound (SMC) for Automotive Market Segmentation
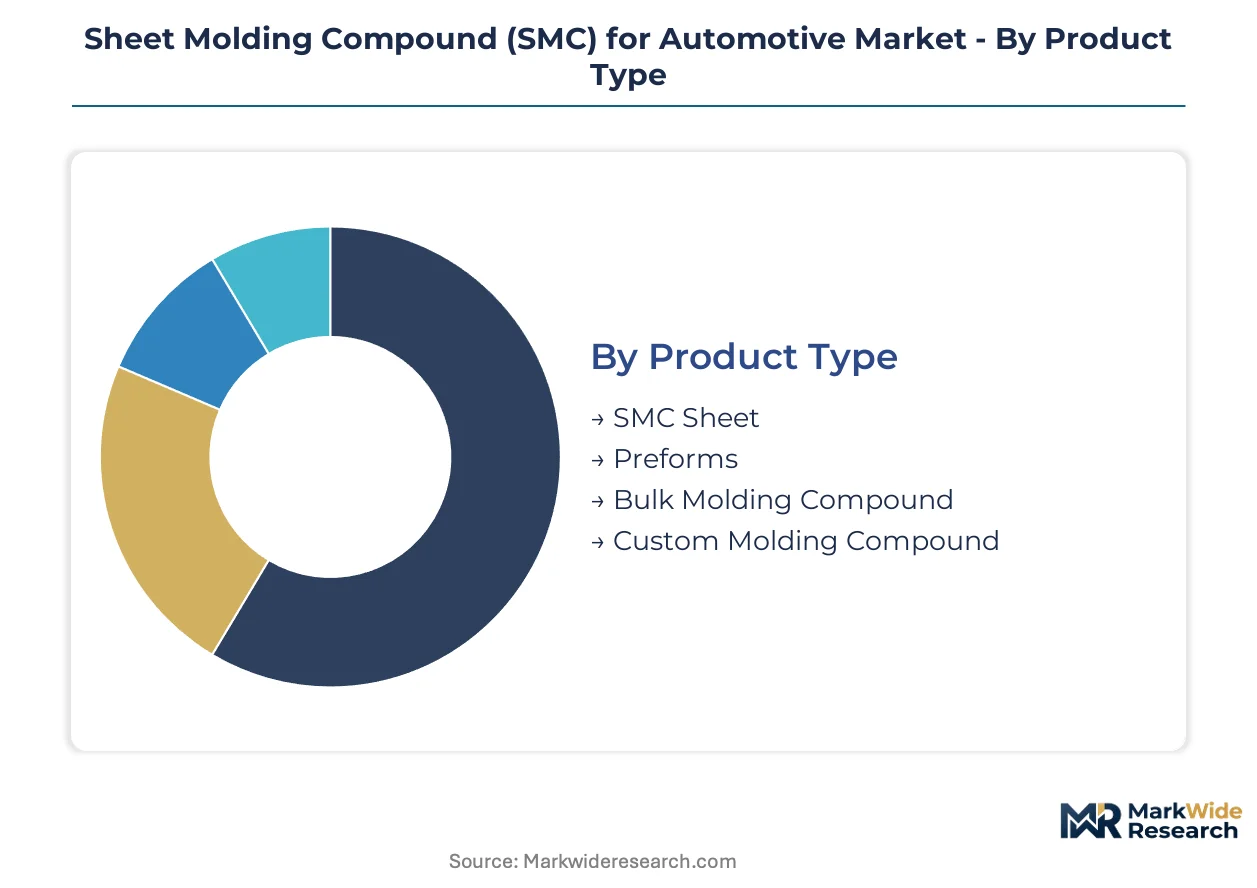
SMC procurement patterns diverge sharply across product formats and customer tiers, with qualification protocols varying by end-use criticality. Understanding these segment boundaries reveals where margin concentrates and where volume scales.
Product Type:
Certification burdens escalate from standard SMC Sheet through engineered Preforms, with UL 2596 fire-resistance protocols and OEM surface-quality audits creating tiered qualification timelines.
- SMC Sheet:Continuous rolls of glass-reinforced unsaturated polyester or vinyl ester compound, typically 25-30% fiber loading, supplied in standard widths for high-volume compression molding. German OEMs anchor demand for Class A surface-capable grades where paint adhesion and gloss retention must pass BMW and Mercedes-Benz specification protocols.
- Preforms:Net-shape charges cut to final part轮廓, eliminating trimming waste and reducing press cycle times by 15-25% versus bulk sheet feeding. North American truck and SUV programs exceeding 100,000 annual units drive procurement concentration as Tier-1 molders seek scrap reduction and throughput gains.
- Bulk Molding Compound:Loose, dough-like material for transfer or injection compression of complex geometries with deep draws and rib structures. Suited for underbody brackets and battery tray fittings where surface finish requirements are secondary to dimensional stability.
- Custom Molding Compound:Formulator-engineered recipes with modified cure systems, filler loadings, or fiber architectures for proprietary OEM specifications. Requires dedicated qualification cycles and captive resin chemistry relationships.
SMC Sheet sits at the top of the volume ranking, with Preforms climbing the fastest as modular kit procurement displaces bulk purchasing in complex geometry programs.
End User:
Customer type determines contract structure, with direct OEM relationships commanding premium positioning through co-development clauses and multi-year volume commitments.
- OEMs:BMW, Mercedes-Benz, and premium EV specialists source directly for battery enclosure and body-in-white programs, embedding SMC specifications into platform architecture decisions during vehicle development phases.
- Tier-1 Suppliers:Continental Structural Plastics and similar molders purchase compound in bulk, adding value through Class A surface finishing and multi-material assembly integration for OEM customers.
- Aftermarket Providers:Collision repair and restoration specialists procure lower volumes of general-purpose grades, with pricing sensitivity higher and qualification requirements minimal.
- Vehicle Assemblers:Contract manufacturers and niche EV startups sourcing SMC for limited-production platforms, often relying on distributor channels rather than direct compounder relationships.
OEM direct procurement captures the steepest expansion trajectory as platform architects embed composites earlier in design cycles, while Tier-1 Suppliers retain the largest volume footprint across legacy programs.
Application:
Performance requirements stratify by structural load and surface exposure, with fire-resistance mandates creating distinct qualification barriers for battery-adjacent applications.
- Body Panels:Hoods, decklids, fenders, and liftgates requiring Class A surface finish, paintability, and dimensional stability across thermal cycles. North American truck and SUV programs dominate volume as OEMs substitute stamped aluminum and steel for mass reduction.
- Structural Parts:Load-bearing components including battery tray reinforcements, cross-car beams, and frame rails where specific stiffness targets exceed 40% mass savings versus steel. Electric vehicle platforms concentrate demand as multi-material architectures redesign load paths around composite performance.
- Interior Trim:Dashboard carriers, door panels, and console structures where surface aesthetics matter but structural loads are moderate. Long-fiber-reinforced thermoplastics challenge SMC in this segment on cycle time and recyclability.
- Underbody Components:Shields, covers, and aerodynamic fairings exposed to road debris and chemical splash. Lower surface finish requirements permit faster-curing, lower-cost formulations.
Body Panels command the largest revenue share, with Structural Parts gaining share fastest as battery enclosure fire-resistance standards force simultaneous lightweighting and thermal management solutions.
Distribution Channel:
Channel selection tracks order scale and technical service intensity, with direct relationships reserved for programs requiring formulation co-development.
- Direct Sales:Compounders supply OEMs and major Tier-1 molders through dedicated account teams, embedding technical service engineers at customer facilities for process optimization and defect resolution.
- Distributors:Regional inventory stocking for mid-volume customers, reducing lead times and minimum order quantities for programs below direct-account economic thresholds.
- Online Retail:Small-lot procurement for aftermarket providers, R&D sampling, and prototype development, with limited technical support and standard-grade availability.
- Manufacturers:Captive compound production by integrated molders, rare in automotive due to resin chemistry expertise requirements and regulatory compliance burdens.
Direct Sales channels handle the highest volume flows, with Distributors expanding most quickly as second-tier EV manufacturers and regional molders enter the supply base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sheet Molding Compound technology originated in German automotive engineering during the 1960s, where Bayer AG pioneered glass-reinforced polyester formulations for mass-produced vehicle panels. This German foundation established the technical standards and processing protocols that now govern global qualification requirements.
Germany
BMW and Mercedes-Benz multi-material architectures anchor European demand concentration for Class A surface-capable SMC grades. REACH chemical disclosure mandates through ECHA force resin formulators toward alternative peroxide initiation systems, eliminating cobalt-based cure promoters from automotive supply chains. The Stuttgart-Munich corridor hosts concentrated Tier-1 molder operations serving premium EV platform development.
United States
EPA fuel-economy standards compress vehicle weight targets, accelerating stamped metal substitution in hoods and decklids for full-size truck programs. NHTSA coordinates safety standards that permit composite structural reinforcements when crash performance meets federal motor vehicle safety criteria. Michigan and Ohio industrial clusters concentrate compression molding capacity for Detroit Three OEM supply.
China
Domestic EV platform architectures from BYD and NIO redesign body-in-white structures around multi-material load paths incorporating fire-resistant battery enclosures. MIIT administers GB standards for new energy vehicle safety that incorporate thermal runaway containment requirements. The Yangtze River Delta manufacturing belt concentrates SMC compounder investments to serve local battery enclosure demand.
Japan
Toyota and Honda lightweighting roadmaps specify SMC for structural reinforcements in hybrid and battery-electric platforms. METI oversees industrial standards that align with UN ECE R100 battery safety protocols for export vehicle certification. The Nagoya industrial corridor maintains specialized compression molding expertise for automotive composite production.
India
PLI scheme incentives for advanced chemistry cell manufacturing create adjacent demand for domestic SMC battery enclosure supply as Tata Motors and Mahindra accelerate EV localization. BIS formulates national standards for electric vehicle safety that reference international thermal management benchmarks. The Tamil Nadu-Gujarat automotive belt attracts compounder investments to serve emerging domestic EV supply chains.
Sheet Molding Compound (SMC) for Automotive Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and qualification depth, with Class A surface-capable grades commanding sustained pricing power against general-purpose structural compounds. The vendor base stratifies into three strategic archetypes: integrated chemical conglomerates with captive resin supply, specialized compounders focused on automotive qualification protocols, and regional molders with captive compounding operations. Dominant competitive moves include backward integration into resin chemistry and geographic expansion through joint ventures with local Tier-1 suppliers.
Among Germany-based formulators, Menzolit Kunststoffwerk GmbH exemplifies the specialized compounder archetype with deep automotive qualification expertise. BASF represents the integrated chemical conglomerate model, leveraging upstream resin chemistry control to anchor European supply relationships. Continental Structural Plastics occupies a position within the North American premium-tier segment, with its corporate name signaling structural plastics specialization. Mitsubishi Chemical Advanced Materials anchors Asia-Pacific supply positioning, its name indicating advanced materials focus beyond commodity grades. Changzhou RealLand Composite Material Technology Co., Ltd. and Union Composites Changzhou Co., Ltd. represent Chinese manufacturing scale, their Changzhou base locating them within the Yangtze River Delta industrial cluster.
| Leading Market Players |
|---|
| Continental Structural Plastics |
| BASF |
| IDI Composites International |
| Core Molding Technologies |
| Mitsubishi Chemical Advanced Materials |
| Menzolit Kunststoffwerk GmbH |
| Polynt Composites |
| Changzhou RealLand Composite Material Technology Co., Ltd. |
| Union Composites Changzhou Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Class A certification tiers split procurement economics between surface-capable premium grades and general-purpose structural compounds, with REACH-mandated chemical disclosure in Germany compressing margins for cobalt-dependent formulators while UL 2596 fire-resistance protocols extend qualification premiums for battery enclosure suppliers. This tiered performance ladder concentrates pricing power with resin chemistry controllers and disperses margin pressure across compounders lacking captive unsaturated polyester supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates, with Class A surface grades commanding sustained premiums over structural formulations and bulk molding compounds tracking styrene monomer spreads. Price differentiation hinges on OEM qualification depth and fire-resistance certification status, with UL 2596 battery enclosure grades capturing margin premiums. Cost compression in standard structural grades is intensifying because long-fiber-reinforced thermoplastics challenge cycle-time economics. Aftermarket providers exhibit highest price sensitivity, while direct OEM relationships for EV platforms show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German resin formulators for REACH-compliant peroxide initiation systems and Chinese glass fiber suppliers for high-volume battery enclosure programs. Manufacturing gravity centers on Germany, China, and the United States, with compound production drawing from propylene derivatives, styrene monomers, and E-glass rovings. Tariff exposure on Chinese glass fiber imports threatens margin stability for North American molders. Distribution runs through direct technical service relationships for qualified Tier-1 suppliers and regional distributors for mid-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA fuel-economy standards and EU fleet CO2 mandates forcing simultaneous lightweighting and fire-resistance solutions that thermoset composites uniquely address.
For Market Incumbents: Cement backward integration into unsaturated polyester resin chemistry to defend against petrochemical input volatility and REACH-driven formulation disruptions. Prioritize captive peroxide initiation system production to eliminate cobalt-based cure promoter dependencies. Lock in multi-year direct OEM contracts for battery enclosure programs before qualification timelines extend further under UL 2596 protocols. For New Entrants and Emerging Players: The mid-tier pricing gap between German Class A specialists and Chinese commodity compounders creates entry space for regional formulators serving India's PLI-driven EV localization. Target domestic battery enclosure supply for Tata Motors and Mahindra platforms in the Tamil Nadu-Gujarat corridor. Pursue joint venture structures with established Tier-1 molders to bypass 18-24 month OEM qualification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and fire-resistance certification investments exceed standalone compounder returns. Long-term viability favors integrated resin-chemistry-to-molding operations with established German OEM relationships. Monitor ECHA substance of very high concern listings as inflection signals for formulation obsolescence risk and acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | BASF leverages captive unsaturated polyester supply to anchor European pricing power against volatile monomer spreads. |
| Fire-Resistance Certification Investment | UL 2596 battery enclosure qualification creates 18-24 month barriers that concentrate margin with pre-certified compounders. |
| Geographic Expansion via Joint Venture | Mitsubishi Chemical Advanced Materials extends Asia-Pacific footprint to serve Japanese OEM lightweighting roadmaps. |
| Modular Preform Kit Development | Net-shape charge supply to North American truck programs reduces scrap and compresses molding cycle times by 15-25%. |
| REACH-Compliant Formulation Transition | ECHA cobalt promoter restrictions force peroxide initiation system shifts that reshape supplier qualification protocols. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, resin formulator R&D directors, and automotive regulatory affairs specialists grounded qualitative insights. Primary interview findings triangulated against customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed compounders, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing and top-down market validation converged on volume and value estimates.
Segment-level outputs across product type, end user, application, and distribution channel dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from regression analysis against EPA fuel-economy trajectory, EU fleet CO2 mandate compliance curves, and EV platform production schedules. Modeled inputs included glass fiber loading ratios, press cycle time improvements from preform adoption, and REACH chemical substitution cost curves.
Caveats apply where battery thermal runaway protocol revisions, petrochemical price spikes, or thermoplastic substitution breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about OEM platform architecture decisions and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Automotive Door Module Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
US Automotive Composites Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Air Intake Manifold Market