
 Europe Automotive Interior Materials Market | 2026-2036
Europe Automotive Interior Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Interior Materials Market Analytics
OEM procurement channels is tilting toward direct material partnerships that bypass traditional Tier-1 intermediaries. FORVIA (Faurecia) leverages its seating and cockpit integration capabilities to sustain long-term contracts with major European vehicle manufacturers. Lear Corporation anchors its position through vertical control over electrical distribution systems embedded within interior architectures. DRÄXLMAIER GROUP differentiates via specialized wiring and interior electronics manufacturing concentrated in German and Eastern European plants.
Europe automotive interior materials encompass surface and structural components engineered from polymers, textiles, leathers, and engineered composites, typically specified to meet flammability standards, VOC emission limits, and tactile performance criteria for cabin environments. These materials serve to enhance occupant comfort, aesthetic differentiation, and functional integration of controls and displays within vehicle passenger compartments. Upholstery and dashboard segments command the dominant share of value, with leather and composite materials capturing expanding share as premium electrified vehicles proliferate across European fleets. Fabric and vinyl categories retain cost-sensitive volume, though margin pools increasingly migrate toward sustainable material certifications and closed-loop recycling compliance.
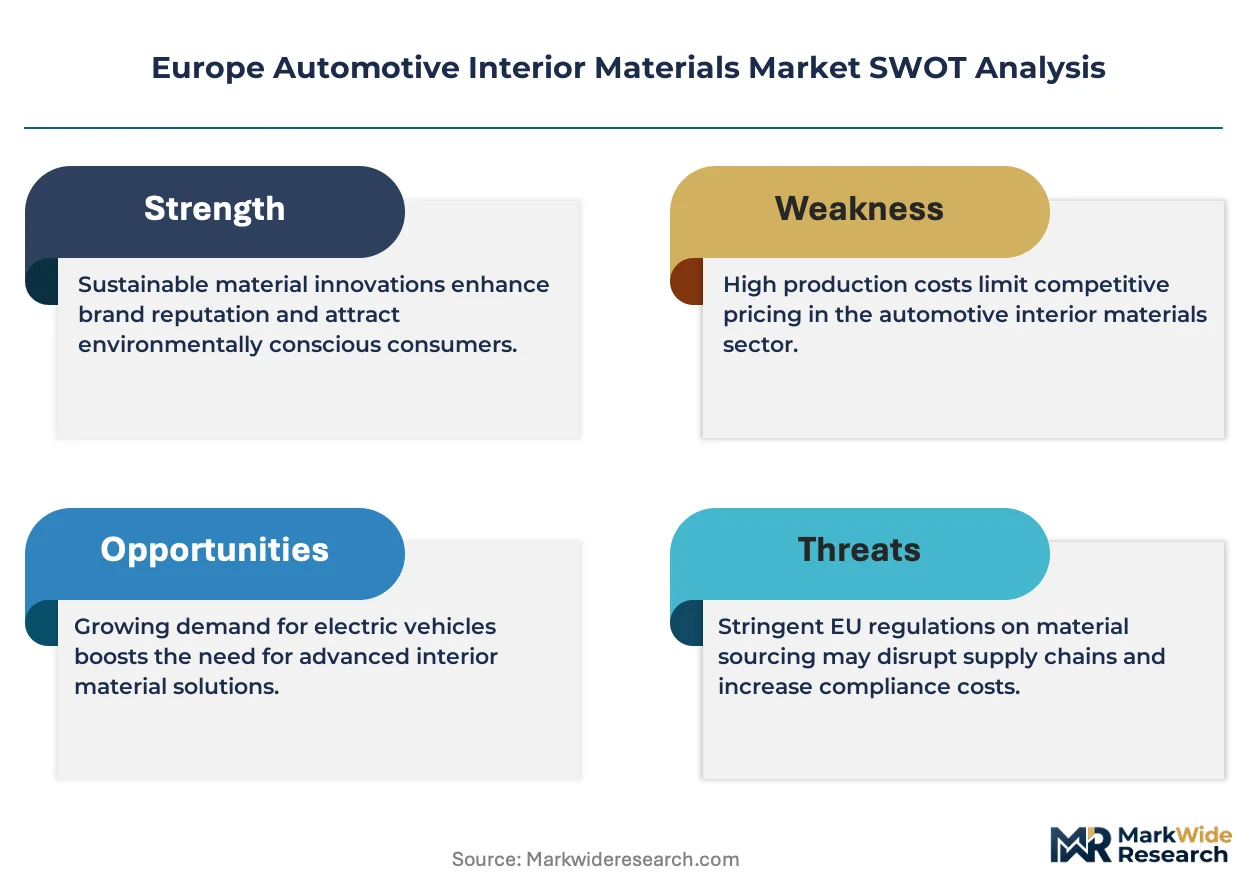
REACH regulations and the EU Green Deal framework constrain permissible substances while mandating recycled content thresholds, compelling reformulation of polyurethane foams, synthetic leathers, and adhesive systems throughout the supply chain. ECHA substance evaluations and CE marking requirements for automotive components create parallel compliance obligations that filter material qualification down to sub-supplier tiers. Stakeholders must monitor evolving EU taxonomy criteria and battery-electric vehicle interior weight targets to align material portfolios with next-generation platform specifications.
Market Dynamics
EU Green Deal mandates and REACH chemical restrictions are compressing formulation cycles for polyurethane foams and synthetic leathers, forcing suppliers to rebuild material portfolios around bio-sourced feedstocks and closed-loop recycling infrastructure before 2030 platform deadlines.
Growth Catalysts
- Electric vehicle interior weight targets:Battery-electric platforms from Stuttgart to Wolfsburg specify lighter dashboard substrates and seat structures to maximize range. Material suppliers reformulate composite densities to capture these specification windows.
- REACH substance restrictions:ECHA evaluations on isocyanates and plasticizers accelerate substitution timelines. Suppliers qualifying bio-polyols and waterborne adhesives gain preferred supplier status with German OEMs.
- Premium electrified vehicle proliferation:Leather and Alcantara demand concentrates in Bavarian and Baden-Württemberg assembly plants. Tanneries and textile coaters expand finishing capacity to serve these programs.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with naphtha and propylene pricing. Foam molders absorb margin compression or pass through via index-linked contracts.
- German supplier concentration:Seating and cockpit integration capability clusters around Lower Saxony and Bavaria. Tier-2 textile and adhesive specialists face qualification barriers without proximity to these engineering centers.
- Technical limitation of bio-sourced materials:Natural fiber composites exhibit dimensional instability under cabin thermal cycling. OEMs specify hybrid constructions that retain petroleum-based binders, limiting full substitution.
Strategic Opportunities
- Eastern European manufacturing expansion:Czech and Slovak assembly plants source interior components from regional suppliers. Polish and Hungarian material processors invest in automated cutting and sewing to serve these volumes.
- CE marking for recycled content:EU taxonomy alignment creates certification premiums. Suppliers documenting post-industrial and post-consumer feedstock capture price premiums in Scandinavian markets.
- Sensor-integrated surface convergence:Capacitive touch and haptic feedback migrate into door panels and steering wheels. Material suppliers partnering with electronics integrators capture value from functional surface specification.
Industry Challenges
- Cross-functional material engineering talent:Polymer chemists with automotive VOC and flammability testing experience command premium compensation. Suppliers compete with battery and powertrain sectors for this limited pool.
- Qualification timeline compression:OEM platform cycles now demand 18-month material validation versus historical 36-month windows. Sub-suppliers invest in parallel track testing to meet these gates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Interior Materials Market |
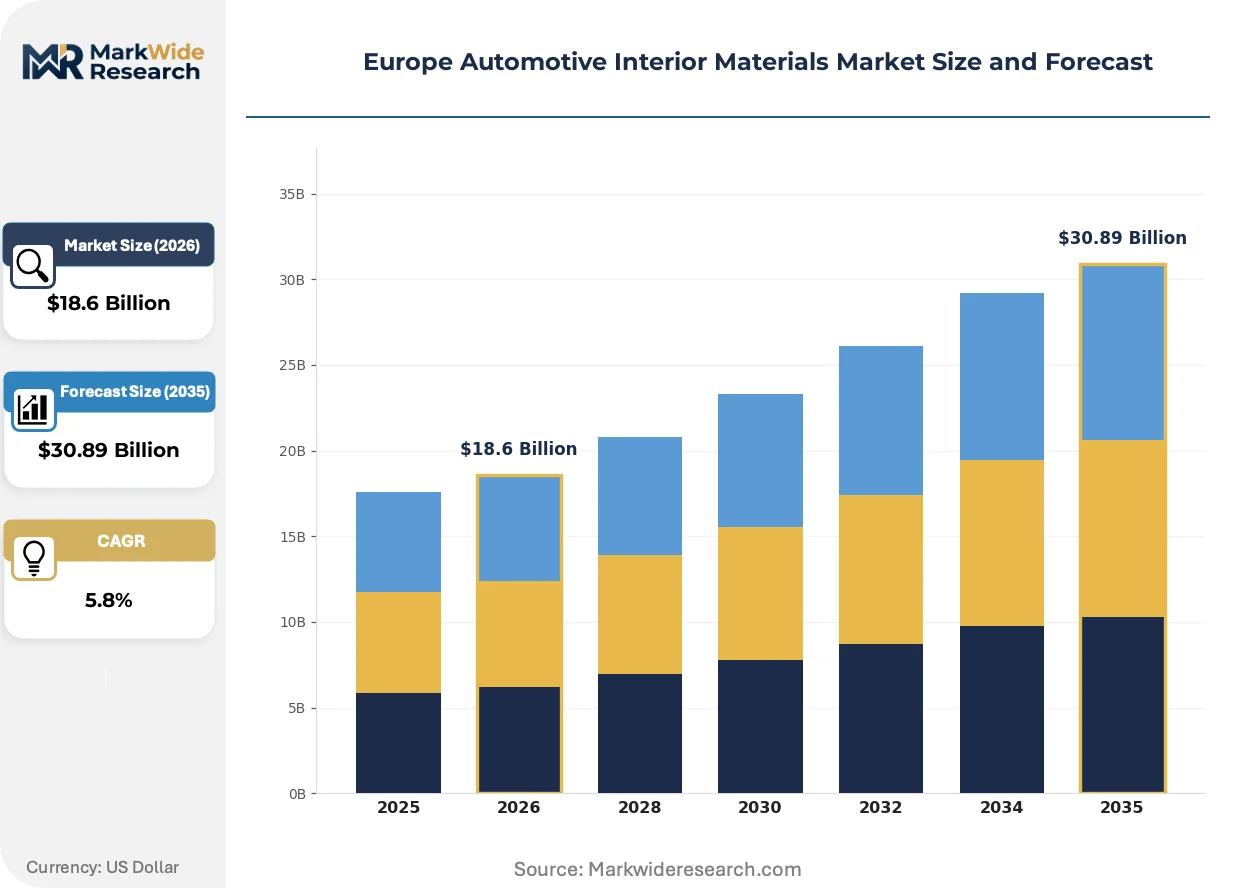
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upholstery, Dashboard, Carpet, Headliner Material: Fabric, Leather, Vinyl, Composite End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Deployment: In-house, Outsourced, Hybrid, Custom Solutions |
| Companies Covered | FORVIA (Faurecia), Adient plc., Lear Corporation, DRÄXLMAIER GROUP, Toyota Boshoku Corporation, Grupo Antolin, Johnson Controls, ZF Friedrichshafen AG, Magna International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Interior Materials Market Evolving Landscape
Interior material specification is bifurcating between mass-market cost optimization and premium functional integration, with sustainability certification becoming a non-negotiable qualifier rather than a differentiator across both tiers.
Natural fiber-reinforced thermoplastics are migrating from concept demonstrators to series production in door panels and package trays. BMW and Mercedes-Benz programs specify flax and hemp composites for weight reduction and lifecycle carbon claims. This migration from petroleum-based substrates is compressing conventional PP compound margins while rewarding agricultural fiber processors with automotive qualification capability.
EU Green Deal framework and delegated acts under the Sustainable Products Regulation mandate digital product passports for automotive components. ECHA substance database integration requires granular material composition disclosure down to the 0.1% threshold. Upholstery and foam suppliers serving Swedish and Dutch OEMs invest in blockchain-traceable supply chain documentation to preempt compliance gaps.
Fleet procurement departments now specify interior durability standards directly rather than delegating to Tier-1 integrators. Rental and mobility-service operators in Germany and France demand accelerated wear testing protocols. Direct material qualification by these buyers is disintermediating traditional specification channels and rewarding suppliers with in-house testing and certification laboratories.
Europe Automotive Interior Materials Market Segmentation
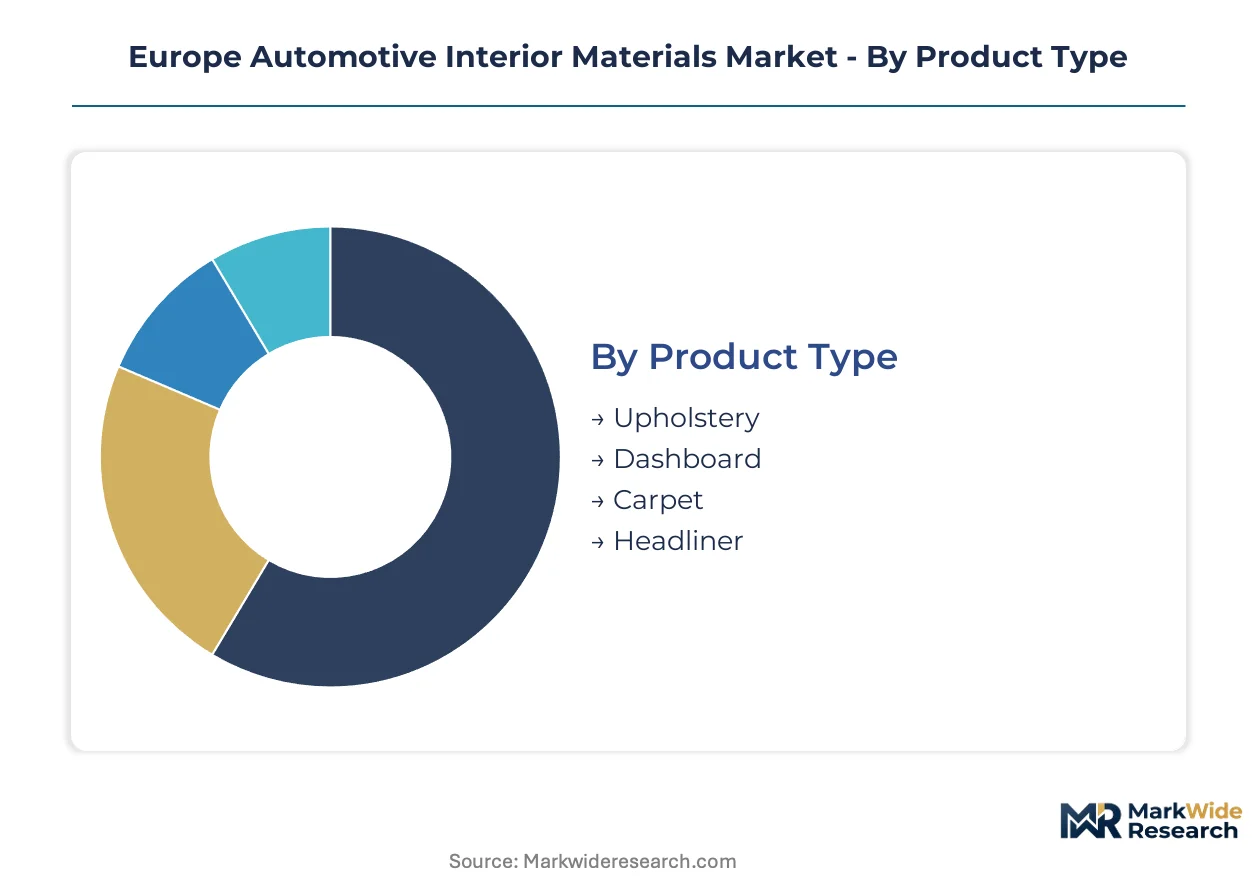
Interior material specification in Europe fragments across product function, material chemistry, supply chain position, and manufacturing control models. Each segmentation axis reveals distinct margin pools and qualification barriers that reshape supplier competitive positioning.
Product Type:
Surface and structural components span a use-case spectrum from high-touch occupant interfaces to hidden acoustic and thermal management layers.
- Upholstery:Seat covers, door inserts, and console wraps engineered from layered textiles, foams, and backings to meet abrasion resistance and VOC emission thresholds. German premium OEMs in Bavaria and Baden-Württemberg specify leather and Alcantara variants for electrified flagship programs, compressing qualification timelines for tanneries and textile coaters.
- Dashboard:Molded substrate assemblies integrating structural frames, soft-touch skins, and decorative trim elements. Battery-electric platforms from Stuttgart to Wolfsburg demand lighter composite substrates to offset battery mass, redirecting specification toward glass-mat thermoplastic and natural fiber-reinforced alternatives.
- Carpet:Tufted or needle-punched floor coverings with bitumen or thermoplastic backing systems for acoustic damping. Eastern European assembly plants in Czechia and Slovakia source these from regional processors to minimize logistics exposure.
- Headliner:Multi-layer composite panels combining fabric facing, foam core, and rigid substrate for cabin acoustics and overhead component mounting. REACH substance restrictions on adhesive systems force reformulation of bonding chemistries across Spanish and Italian supply bases.
The dominant share belongs to Upholstery, while Dashboard is closing the gap fastest as electrification rewrites substrate specifications.
Material:
Cost tier stratification separates certified sustainable feedstocks from conventional petroleum-based formulations.
- Leather:Chrome-tanned or vegetable-tanned hides specified for premium cabin differentiation. Italian tanneries in Arzignano and Santa Croce sull'Arno anchor European finishing capacity, though REACH restrictions on chromium VI accelerate waterborne tanning chemistry adoption.
- Fabric:Woven, knitted, or non-woven textiles from polyester, polyamide, or wool blends serving volume production. Bio-sourced alternatives from recycled PET and ocean plastics gain specification in Scandinavian OEM programs driven by EU Green Deal procurement mandates.
- Vinyl:Calendered or cast polyvinyl chloride skins with plasticizer systems for cost-optimized surface coverage. ECHA evaluations on phthalate plasticizers force migration to non-phthalate and bio-based plasticizer portfolios.
- Composite:Glass fiber, carbon fiber, or natural fiber-reinforced thermoplastics and thermosets for structural and semi-structural interior elements. BMW and Mercedes-Benz programs specify flax and hemp fiber composites for lifecycle carbon claims, compressing margins for conventional PP compounders.
Leather commands premium positioning, though Composite is expanding most quickly as natural fiber qualification accelerates.
End User:
Supply chain position determines specification authority and contract duration across the value chain.
- OEMs:Vehicle manufacturers with direct material qualification teams bypassing traditional Tier-1 intermediaries. Volkswagen Group and Mercedes-Benz AG now specify interior substrates directly, disintermediating historical seating and cockpit integrators.
- Tier-1 Suppliers:Seating, cockpit, and interior module integrators consolidating material procurement across multiple OEM programs. FORVIA and Lear Corporation anchor this channel through vertical control over electrical distribution and foam molding capabilities.
- Aftermarket Providers:Independent refinishers and customization shops serving vehicle personalization and fleet renewal demand. German and French rental operators now specify durability standards directly, bypassing Tier-1 specification channels.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities with localized sourcing mandates. Magna Steyr in Graz and Valmet Automotive in Finland source interior components from regional supplier clusters to meet just-in-sequence delivery requirements.
Tier-1 Suppliers retain volume concentration, while OEMs are capturing specification authority fastest through direct material partnerships.
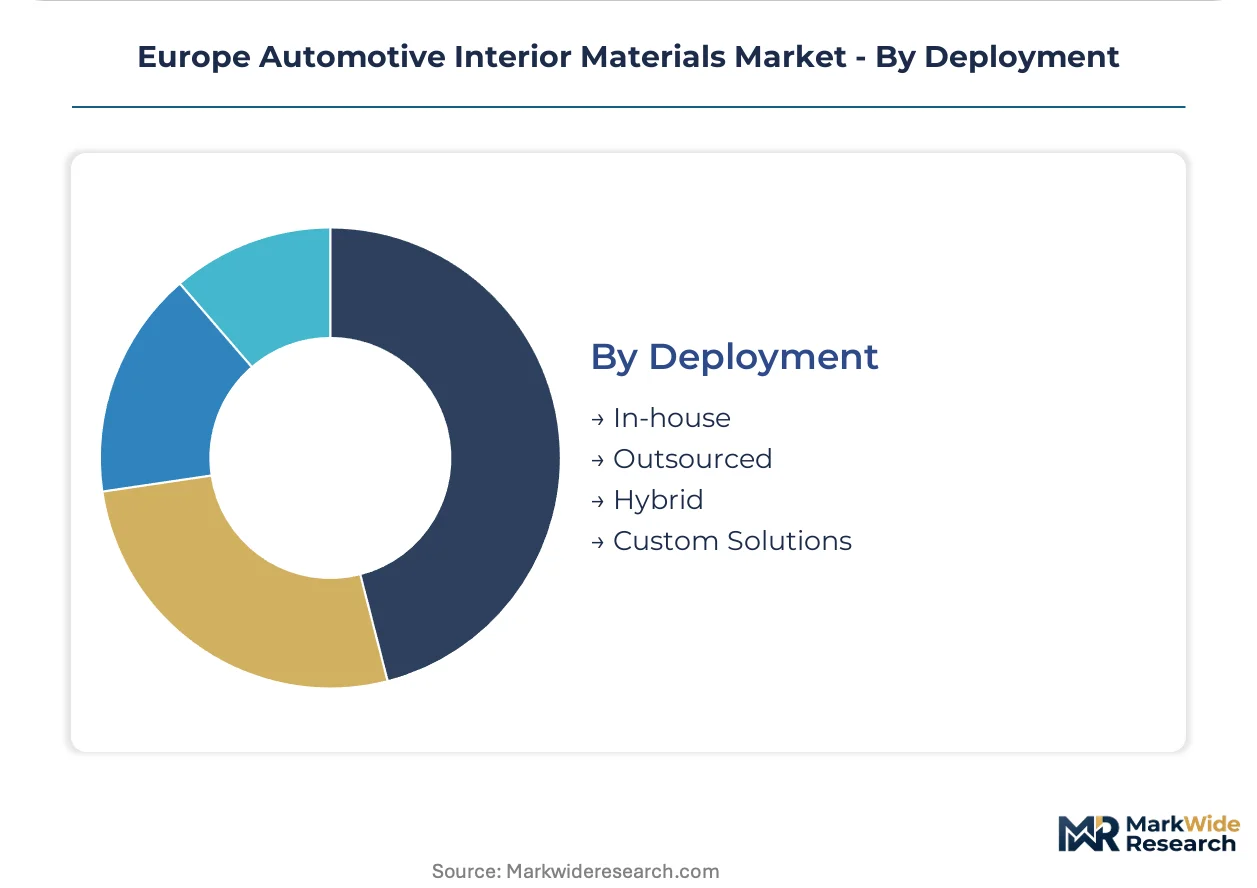
Deployment:
Manufacturing control models reflect capital intensity, intellectual property protection, and flexibility requirements.
- In-house:Captive manufacturing of proprietary foam formulations, leather finishing, or composite molding within supplier or OEM facilities. BMW's Landshut plant produces natural fiber composites for i-series programs, protecting process knowledge.
- Outsourced:Contract manufacturing arrangements with specialized processors for cutting, sewing, or molding operations. Polish and Hungarian textile processors invest in automated cutting to serve Czech and Slovak assembly volumes.
- Hybrid:Blended models combining captive core production with outsourced capacity for volume flexibility or regional proximity. Tier-1 seating suppliers maintain European foam molding while sourcing Asian textile finishing for cost-optimized programs.
- Custom Solutions:Bespoke development partnerships for limited-series, prototype, or architectural showcase vehicles. Italian design houses in Turin and Milan collaborate directly with material innovators for concept-to-production translation.
Hybrid deployment dominates program economics, while In-house is gaining share fastest as OEMs protect electrification-era material innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight network anchors material flows between German industrial clusters and Mediterranean assembly plants, underwriting Europe's interior materials trade density.
Germany
Bavarian and Baden-Württemberg assembly plants specify leather and Alcantara for electrified flagship programs. REACH restrictions on chromium VI accelerate waterborne tanning chemistry adoption across Arzignano-linked supply chains. Stuttgart and Wolfsburg engineering centers compress qualification timelines for natural fiber composite substrates.
France
Île-de-France fleet operators now specify interior durability standards directly for rental and mobility-service vehicles. EU Green Deal procurement mandates drive bio-sourced textile adoption in Scandinavian-bound export programs. Auvergne-Rhône-Alpes hosts specialized foam molding capacity serving Lyon-Turin logistics corridors.
Italy
Arzignano and Santa Croce sull'Arno tanneries anchor European leather finishing capacity for premium German OEMs. ECHA substance evaluations force migration from chromium-based tanning to vegetable-tanned alternatives. Turin and Milan design houses collaborate directly with material innovators for concept-to-production translation.
Czechia
Assembly plants in Mladá Boleslav and Nošovice source carpet and headliner components from regional Polish and Hungarian processors. CE marking requirements for recycled content create certification premiums in export-bound production. Automated cutting and sewing investments in Lower Silesia serve just-in-sequence delivery requirements.
Spain
Martorell and Pamplona vehicle plants specify REACH-compliant adhesive systems for dashboard and headliner assembly. EU taxonomy alignment pressures suppliers to document post-industrial feedstock for Scandinavian market access. Basque Country composite molders supply natural fiber-reinforced door panels to French and German OEMs.
Europe Automotive Interior Materials Market Competitive Landscape
On the supply side, the industry is consolidating around seating and cockpit integrators with captive electrical distribution capabilities. Three archetypes dominate: full-system integrators controlling foam-to-electronics verticality, specialized textile and leather finishers with tannery proximity, and regional processors serving Eastern European assembly proximity. M&A activity concentrates on adhesive and composite specialists, while German OEMs bypass Tier-1 intermediaries through direct material partnerships.
Among full-system integrators, FORVIA (Faurecia) and Lear Corporation exemplify the vertical-control archetype, anchoring long-term contracts through seating and cockpit integration capabilities. DRÄXLMAIER GROUP occupies a position within the specialized wiring and electronics tier, concentrated in German and Eastern European manufacturing footprints.
| Leading Market Players |
|---|
| FORVIA (Faurecia) |
| Adient plc. |
| Lear Corporation |
| DRÄXLMAIER GROUP |
| Toyota Boshoku Corporation |
| Grupo Antolin |
| Johnson Controls |
| ZF Friedrichshafen AG |
| Magna International |
| Others |
Value Network & Pricing Analysis
Italian tannery concentration in Arzignano and Santa Croce sull'Arno anchors premium leather pricing power, while German foam molders in Lower Saxony capture margin pools through captive polyurethane formulation. This upstream clustering compresses Tier-2 textile processors in Poland and Hungary into price-taking positions on standardized fabric and vinyl categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs material procurement, with certification grade and volume scale as primary differentiation drivers. REACH-compliant bio-sourced alternatives command 15-25% premiums over conventional petroleum-based formulations in Scandinavian markets. Pricing pressure stems from petrochemical feedstock volatility forcing index-linked contract renegotiations annually. Fleet procurement departments exhibit highest price sensitivity, while Bavarian premium OEMs prioritize lifecycle carbon claims over unit cost.
Supply Chain Analysis
Polyurethane precursor supply draws from German, Belgian, and Dutch petrochemical complexes, with naphtha and propylene derivatives feeding foam molding operations across Central Europe. Natural fiber composite production sources flax and hemp from French and Dutch agricultural processors. Single-source vulnerability concentrates in specialized waterborne adhesive formulations qualified for REACH compliance. Distribution runs through just-in-sequence delivery networks serving Stuttgart, Wolfsburg, and Munich assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material-as-a-service contracts for closed-loop recycling and digital product passport compliance are expanding faster than hardware-only supply arrangements. This recurring-revenue layer rewards suppliers with blockchain-traceable supply chain infrastructure.
For Market Incumbents: Build certification moats around EU taxonomy alignment and ECHA substance database integration. Deepen backward integration into bio-polyol production to secure feedstock against petrochemical volatility. Defensive positioning requires parallel-track material validation laboratories to compress 18-month OEM qualification windows. For New Entrants and Emerging Players: Build out automated cutting and sewing capacity in Lower Silesia and Hungary to serve Czech and Slovak assembly plants. Target carpet and headliner categories where regional proximity outweighs brand equity barriers. Go-to-market leverage rests on CE marking documentation for recycled content premiums in Scandinavian-bound production. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across natural fiber composite molding as BMW and Mercedes-Benz expand flax and hemp specification. Long-term viability favors adhesive specialists with waterborne chemistry portfolios and composite molders with automotive qualification capability. Watch for ECHA substance evaluation announcements as inflection signals for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Production | Secures feedstock against REACH-driven petroleum substitution in German OEM supply chains. |
| CE Marking for Recycled Content | Captures certification premiums in Scandinavian markets under EU taxonomy alignment. |
| Parallel-Track Material Validation Investment | Compresses qualification timelines to meet 18-month OEM platform gates. |
| Regional Manufacturing Footprint Expansion | Positions automated textile processing in Poland and Hungary for Czech-Slovak assembly volumes. |
| Digital Product Passport Infrastructure | Enables blockchain-traceable compliance for ECHA substance disclosure thresholds. |
Research Methodology
Operator-level perspectives from Tier-1 procurement directors, OEM platform engineers, tannery technical managers, and foam molding plant supervisors anchored the qualitative base. Primary fieldwork combined with secondary validation against ECHA substance databases, EU Green Deal delegated acts, vehicle production registries, and customs trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European automotive supply chain.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning material chemistry, product function, supply chain position, and manufacturing control model. CAGRs derived from production volume elasticity to electrification penetration rates and regulatory compliance cost curves. Forecast inputs incorporated REACH substance restriction timelines and battery-electric platform weight reduction targets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese bio-polyol suppliers or accelerated EU taxonomy enforcement would shift outcomes. Cross-checking against IHS Markit vehicle registration data and Cefic chemical production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market