
 Automotive Plastic Interior Trims Market | 2026-2036
Automotive Plastic Interior Trims Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Plastic Interior Trims Market Outlook
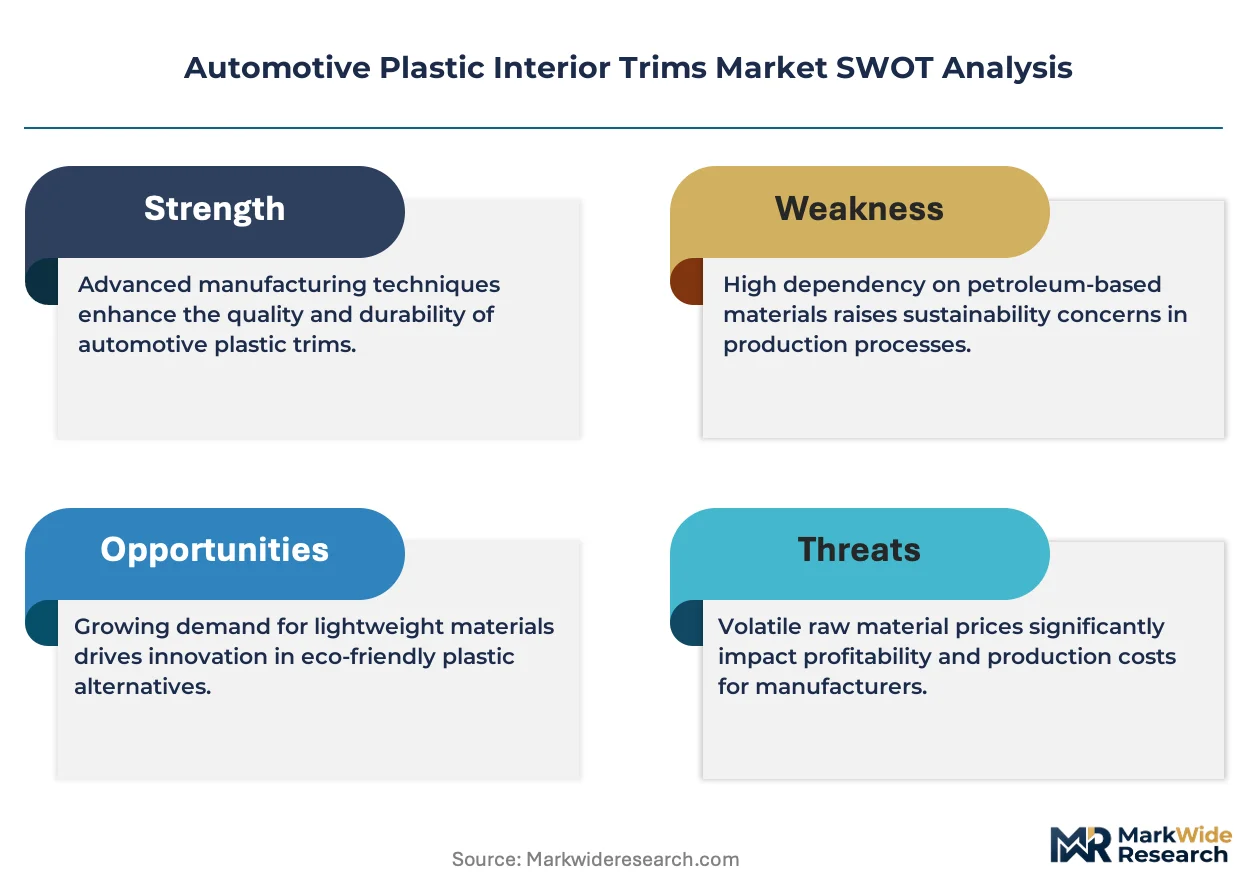
REACH is realigning the cost-of-entry calculus for European suppliers of automotive plastic interior trims by mandating traceable recycled content thresholds in cabin components. Yanfeng leverages its integrated design-to-manufacture footprint to absorb compliance costs across dashboard and door panel programs. Draexlmaier Group anchors its competitive position through specialized surface finishing capabilities that meet OEM haptic and emissions specifications simultaneously.
Automotive plastic interior trims encompass molded polymer components—typically polypropylene, ABS, or polycarbonate blends between 1.5–4.0 mm wall thickness—that form the visible and tactile surfaces of vehicle passenger compartments, providing structural integration for controls, storage, and safety systems while managing cabin acoustics and thermal insulation. Dashboard assemblies and door panels represent the most mature product segments with established margin pools, while center console architectures are capturing disproportionate engineering attention as vehicle electrification relocates shift mechanisms and expands storage requirements. Polypropylene dominates material consumption by volume due to its favorable density-to-stiffness ratio and compatibility with talc-filled reinforcement grades, though polycarbonate is gaining specification share in transparent and backlit decorative elements.
EMA and ECHA frameworks govern substance restrictions and end-of-life obligations for cabin plastics across European vehicle production, while EPA regulations in the United States set volatile organic compound limits for interior air quality that directly influence adhesive and coating selections. OEMs and tier-1 suppliers must monitor regulatory divergence between these jurisdictions when designing common global platforms. Stakeholders should evaluate how upcoming revisions to recyclability certification standards will redistribute qualification burdens across the material supply base.
Market Dynamics
Electric vehicle platform architectures are compressing development cycles for cabin systems while simultaneously demanding lighter polymer formulations that maintain acoustic performance. This dual pressure is restructuring supplier qualification protocols across dashboard, door panel, and console programs.
Growth Catalysts
- REACH recycled content mandates:European OEMs now require traceable post-consumer polymer feedstocks in visible interior components, creating qualified demand pools for suppliers with certified recycling partnerships.
- Polypropylene density optimization:Talc-filled PP grades achieving 1.05-1.15 g/cm³ with maintained stiffness are displacing ABS in non-critical touch surfaces, opening specification wins in mass-market vehicle lines.
- Germany's premium OEM cluster:Stuttgart and Munich headquarters operations concentrate engineering validation resources, accelerating supplier approval timelines for adjacent tier-1 manufacturing sites.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics tie PP resin pricing to regional refinery utilization rates, compressing margin predictability for long-term supply contracts.
- Tooling amortization concentration:Dashboard and door panel injection molds exceeding 2 million euro capital requirements concentrate production among three European toolmaking specialists, creating queue bottlenecks.
- Acoustic textile substitution:Natural fiber composites from flax and hemp are capturing non-structural trim applications where haptic requirements permit matte surface finishes.
Strategic Opportunities
- India's PLI scheme for auto components:Tier-1 suppliers establishing localized compounding and molding operations can access 4-6% incentive-linked cost advantages for export-qualified production.
- Backlit polycarbonate decorative elements:Ambient lighting integration in center consoles and IP surfaces is expanding optical-grade PC specifications beyond traditional gauge cluster applications.
- Direct OEM procurement platforms:Volkswagen's Industrial Cloud and similar digital sourcing systems are disintermediating traditional tier-2 material distributors for specified polymer grades.
Industry Challenges
- Surface finishing chemistry expertise:Low-VOC coating formulations meeting EPA indoor air quality limits require specialized application engineering that outpaces current technical training pipelines.
- Multi-material bonding validation:Dashboard assemblies integrating PP structural substrates with TPU soft-touch skins and PC decorative inserts demand extended thermal cycling certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Plastic Interior Trims Market |
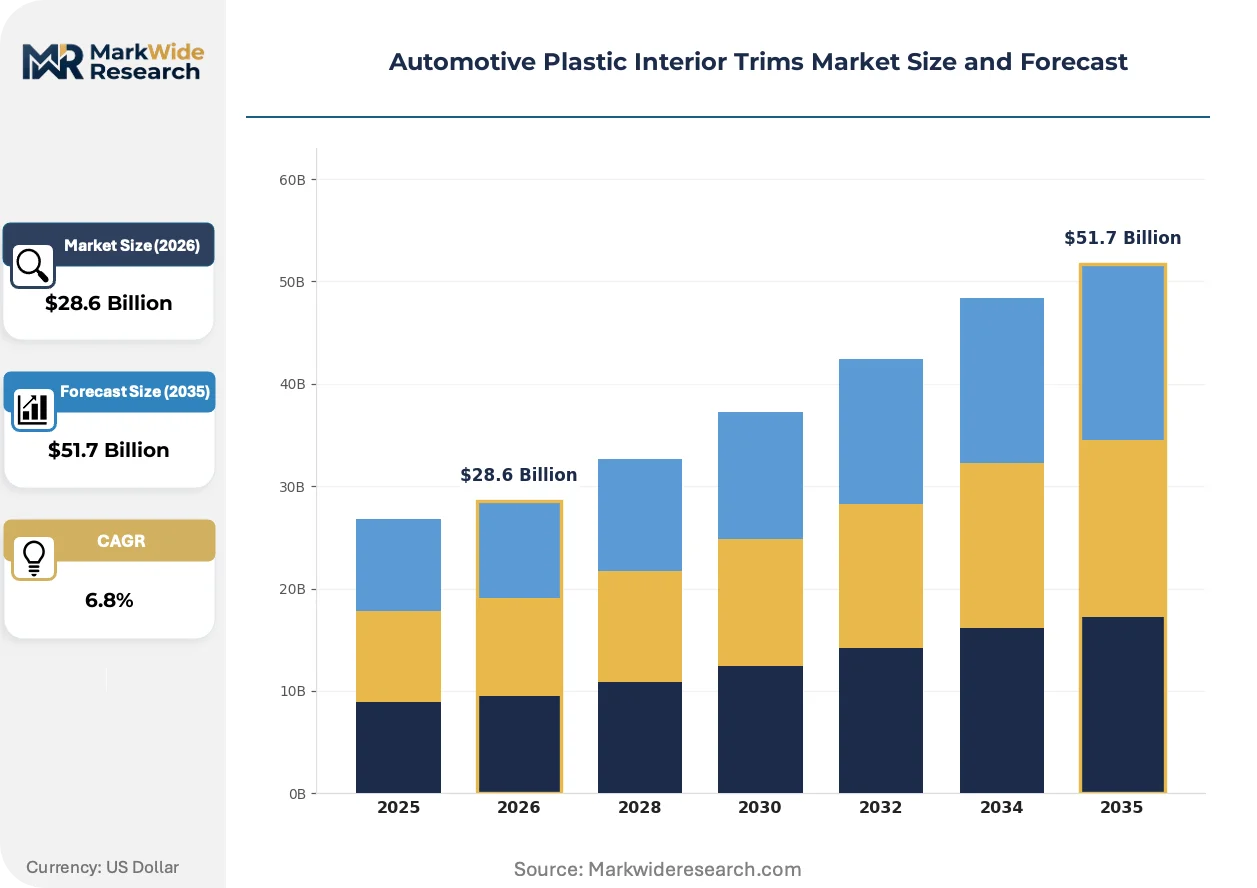
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Door Panel, Center Console, Armrest Material: Polypropylene, ABS, PVC, Polycarbonate Manufacturing Process: Injection Molding, Vacuum Forming, Blow Molding, 3D Printing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | IAC Group, Draexlmaier Group, Yanfeng, Adient, Toyota Boshoku, Forvia, Samvardhana Motherson, Magna International, Grupo Antolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Plastic Interior Trims Market Strategic Shifts
Physical vapor deposition and laser-etched surface texturing are displacing conventional painted finishes across premium vehicle interior programs. These processes eliminate solvent-based coating steps while enabling customizable aesthetic differentiation.
In-mold film insert technology is rewriting decorative surface production by embedding pre-printed polyester films directly into injection molding cycles. Tier-1 suppliers in Germany and Japan are adopting this approach for dashboard and door panel programs, compressing finishing station requirements from three process steps to one integrated operation. The structural consequence is a halving of capital footprint for new trim manufacturing lines.
REACH substance restriction updates through ECHA's SVHC candidate list are forcing reformulation of flame-retardant additives in PP compounds. Suppliers must validate alternative phosphorus-based systems against OEM smoke density specifications, with dashboard applications facing the most stringent retesting obligations. The response has concentrated around collaborative pre-competitive testing consortia in the EU.
Fleet procurement departments at ride-hailing operators are imposing durability specifications that exceed traditional retail consumer vehicle standards. These buyers prioritize scuff-resistant surface chemistries and modular replaceability over aesthetic refinement, reshaping R&D allocation at suppliers serving both channels. The shift is most visible in North American and Chinese electric vehicle fleet deployments.
Automotive Plastic Interior Trims Market Segmentation
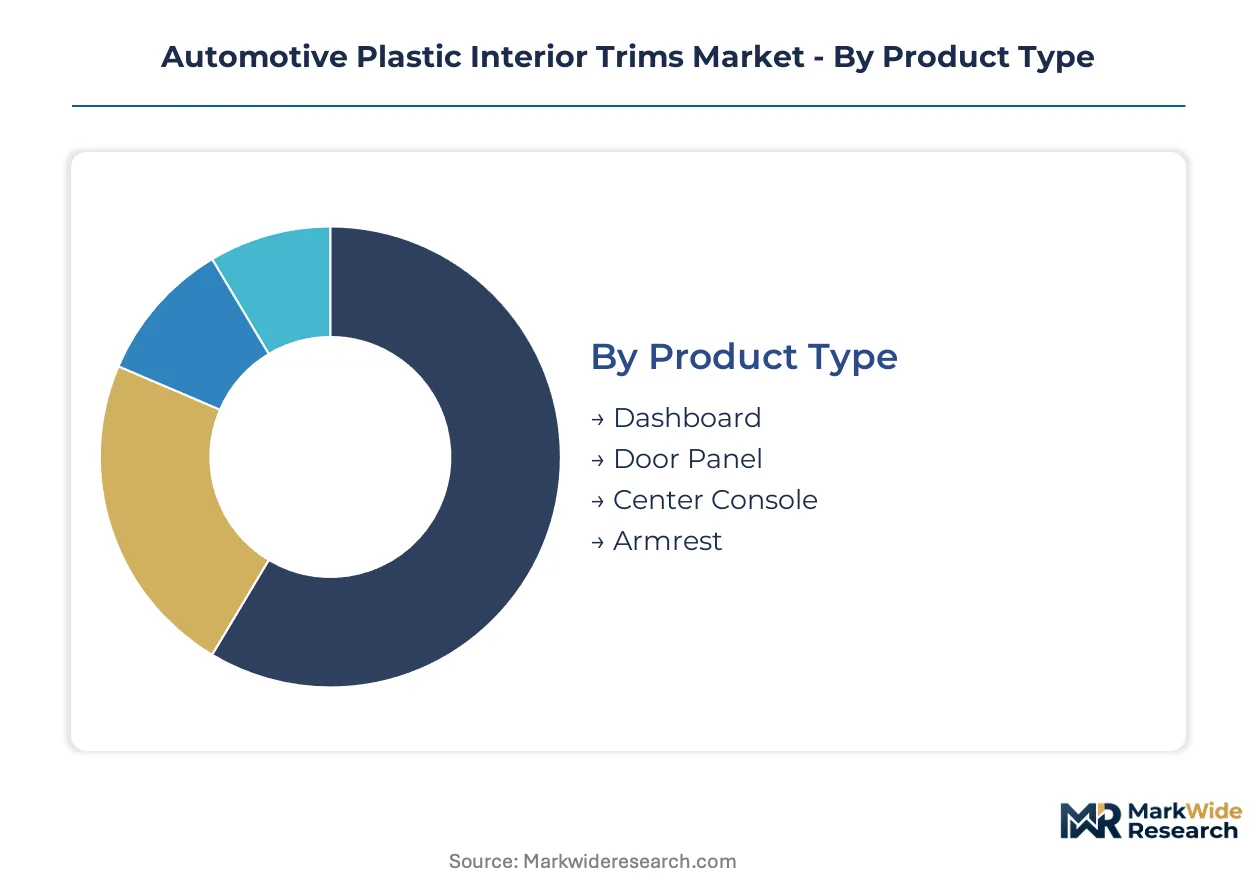
Automotive plastic interior trims demand fragments across four distinct category axes. Each dimension governs supplier qualification protocols, capital intensity requirements, and margin capture potential differently.
Product Type:
Dashboard programs command the highest engineering validation standards among cabin trim categories. Center console architectures reward suppliers with fastest design cycle adaptation.
- Dashboard:Molded assemblies integrating structural substrates, soft-touch skins, and decorative inserts across 1.5–4.0 mm wall thickness specifications. German premium OEMs concentrate validation resources in Stuttgart and Munich, compressing approval timelines for adjacent tier-1 manufacturing sites.
- Door Panel:Multi-component systems combining map pockets, armrest substrates, and window switch bezels into modular assemblies. Demand concentrates in mass-market vehicle lines where talc-filled polypropylene grades displace ABS in non-critical touch surfaces.
- Center Console:Rapidly evolving architectures accommodating relocated shift mechanisms and expanded storage requirements under electrification. Specifications are climbing fastest here.
- Armrest:Smaller-format molded components with lower tooling capital thresholds. Applications span both front-row and second-row seating configurations.
Dashboard leads volumes today; center console is gaining share fastest.
Material:
Material selection governs density-to-stiffness ratios, surface finish compatibility, and regulatory compliance pathways simultaneously.
- Polypropylene:Talc-filled grades achieving 1.05–1.15 g/cm³ dominate volume consumption due to favorable mechanical properties and cost positioning. REACH recycled content mandates are redirecting sourcing strategies toward traceable post-consumer feedstocks.
- ABS:Acrylonitrile-butadiene-styrene retains specification in high-gloss decorative elements requiring superior surface aesthetics. ECHA SVHC candidate list updates are forcing flame-retardant additive reformulations.
- PVC:Leather-grain surface skins and soft-touch applications leverage plasticizer flexibility. EPA volatile organic compound limits constrain adhesive and coating selections in US-bound production.
- Polycarbonate:Optical-grade specifications are expanding beyond traditional gauge clusters into backlit center console and IP decorative elements under ambient lighting integration trends.
Polypropylene dominates tonnage; polycarbonate is climbing the fastest specification trajectory.
Manufacturing Process:
Process technology determines capital footprint, cycle efficiency, and surface finishing integration depth.
- Injection Molding:High-pressure tooling exceeding 2 million euro capital requirements concentrates production among European toolmaking specialists. In-mold film insert technology is compressing finishing stations from three process steps to one integrated operation.
- Vacuum Forming:Lower-pressure thermoforming suits large-format panels with moderate dimensional tolerances. Tooling amortization spreads across shorter production runs.
- Blow Molding:Hollow-section components including ducting and structural tubes leverage this process.
- 3D Printing:Additive manufacturing addresses prototyping and low-volume customization for fleet procurement channels imposing modular replaceability specifications.
Injection molding anchors installed capacity; 3D printing is expanding most quickly in application scope.
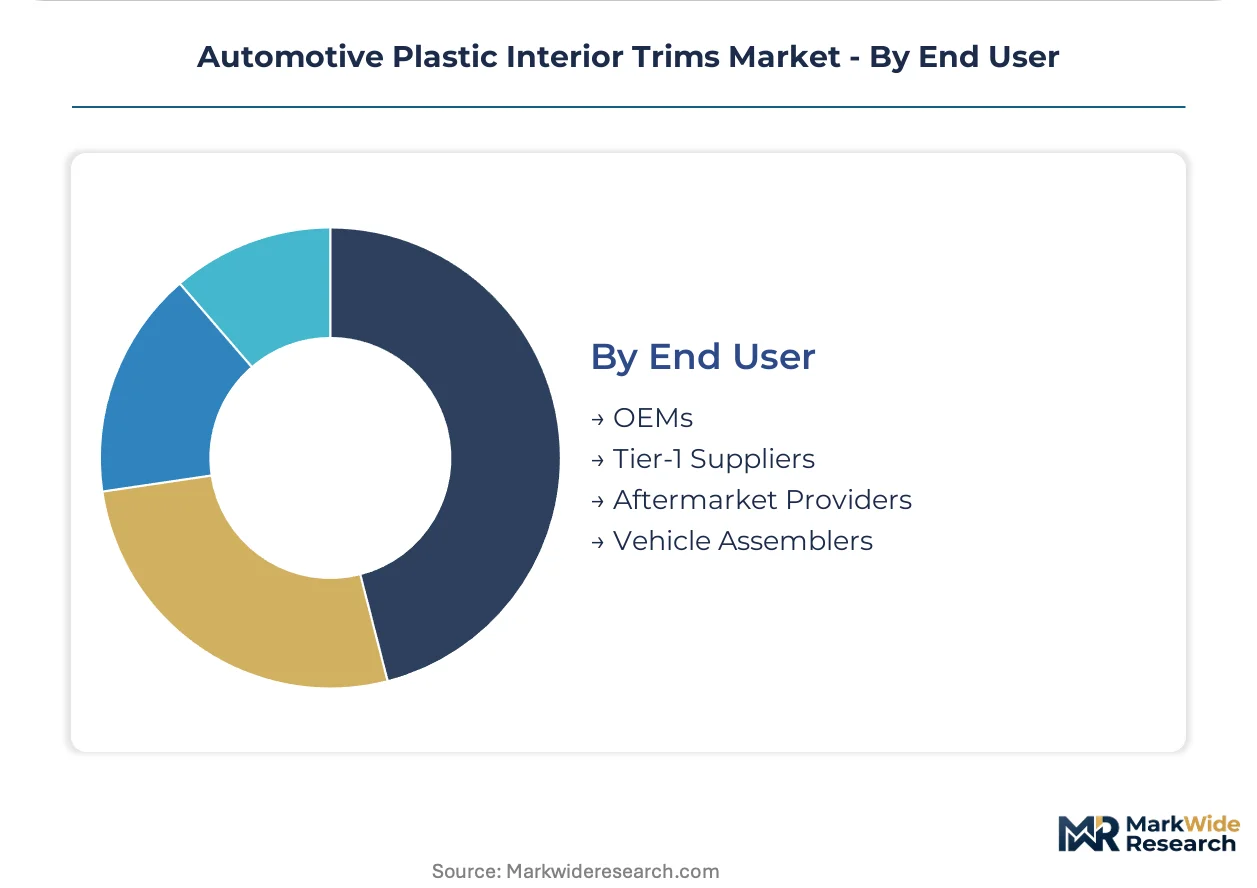
End User:
Customer type structures pricing power, technical collaboration depth, and contract duration profiles.
- OEMs:Direct procurement platforms including Volkswagen's Industrial Cloud are disintermediating traditional tier-2 material distributors. OEMs impose the most stringent haptic and emissions specifications simultaneously.
- Tier-1 Suppliers:Yanfeng and Draexlmaier Group anchor competitive positions through integrated design-to-manufacture footprints and specialized surface finishing capabilities. These entities absorb REACH compliance costs across program portfolios.
- Aftermarket Providers:Modular replaceability priorities from ride-hailing fleet operators reshape R&D allocation toward scuff-resistant surface chemistries.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging EV platforms compress development cycles while demanding lighter polymer formulations.
Tier-1 suppliers capture the largest contract volumes; direct OEM procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tooling engineers and polymer compounders concentrate in Germany's automotive corridor, anchoring European validation protocols for cabin trim specifications. China's Yangtze Delta hosts the densest concentration of injection molding capacity serving domestic EV platforms. India's component manufacturing workforce is expanding fastest under production-linked incentive frameworks.
Germany
Stuttgart and Munich headquarters operations compress supplier approval timelines for dashboard and door panel programs. ECHA's SVHC candidate list updates force flame-retardant additive reformulations across PP compounds. The Baden-Württemberg tooling cluster concentrates 2-million-euro mold capital requirements among three European specialists, creating queue bottlenecks for tier-1 manufacturing sites.
China
Domestic EV platforms demand lighter polymer formulations that maintain acoustic performance across center console architectures. MIIT's dual carbon goals redirect material sourcing toward traceable recycled content pathways. The Yangtze River Delta injection molding base serves BYD, NIO, and Li Auto with compressed development cycles for cabin systems.
United States
Fleet procurement departments at ride-hailing operators impose durability specifications exceeding traditional retail vehicle standards. EPA volatile organic compound limits constrain adhesive and coating selections for interior air quality compliance. Southeast manufacturing corridors in Tennessee and South Carolina anchor transplant OEM supply chains for North American vehicle programs.
India
Tier-1 suppliers establishing localized compounding operations access PLI scheme incentive-linked cost advantages for export-qualified production. BIS certification requirements govern polymer grade specifications for domestic vehicle assembly. Tamil Nadu and Maharashtra clusters concentrate molding capacity serving Maruti Suzuki and Hyundai Motor India programs.
Japan
Tokyo and Nagoya engineering centers validate in-mold film insert technology for dashboard decorative surfaces. METI's resource efficiency guidelines accelerate adoption of physical vapor deposition finishes eliminating solvent-based coating steps. Kanto-based fabricators supply Toyota and Honda with integrated soft-touch skin and structural substrate assemblies.
Automotive Plastic Interior Trims Market Competitive Environment
The competitive structure tilts toward tier-1 integrated design-to-manufacture specialists with captive tooling partnerships. Three archetypes dominate: full-service cabin system integrators, surface finishing specialists, and regional molding scale players. Consolidation pressure concentrates among European toolmaking partnerships and digital procurement platform integration. Geographic expansion and technology licensing represent the dominant competitive moves reshaping supplier positioning.
Within the integrated cabin system tier, Yanfeng and Draexlmaier Group exemplify archetypes absorbing REACH compliance costs across program portfolios. Magna International occupies a position bridging North American OEM relationships with global platform engineering. These entities represent the scale-driven end where design validation resources concentrate engineering approval timelines.
| Leading Market Players |
|---|
| IAC Group |
| Draexlmaier Group |
| Yanfeng |
| Adient |
| Toyota Boshoku |
| Forvia |
| Samvardhana Motherson |
| Magna International |
| Grupo Antolin |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement departments at ride-hailing operators are consolidating purchase volumes and demanding modular replaceability over aesthetic refinement, forcing tier-1 suppliers to unbundle finishing services from structural molding and compressing margin capture on standardized dashboard programs.
Pricing Analysis
Component-plus-service bundling dominates dashboard and door panel contracts, while center console programs increasingly separate decorative finishing from structural substrate supply. Price differentiation hinges on REACH certification tier and talc-filled PP grade density, with premium optical-grade polycarbonate specifications commanding substantial premiums over mass-market talc-filled PP. Cost compression in non-critical touch surfaces is intensifying because ABS displacement by optimized PP grades eliminates coating steps. Mass-market vehicle lines exhibit highest price sensitivity; German premium OEMs demonstrate lowest sensitivity due to haptic specification rigidity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through Volkswagen's Industrial Cloud and similar digital procurement platforms, disintermediating traditional tier-2 polymer distributors. Manufacturing gravity centers on Germany, China, and Japan, with the Baden-Württemberg tooling cluster and Yangtze River Delta injection molding base anchoring regional supply. Feedstock draws from naphtha-cracking economics and regional refinery utilization rates, with propylene resin pricing tethered to volatile energy markets. Single-source vulnerability concentrates in European toolmaking specialists where 2-million-euro mold capital requirements create queue bottlenecks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in surface finishing specialization and REACH-compliant recycled content integration, with cost-down drivers from in-mold film insert technology adoption compressing finishing station capital by half.
For Market Incumbents: Acquire specialized surface finishing capabilities and certified recycling partnerships to absorb REACH compliance costs across program portfolios. Natural fiber composite substitution from flax and hemp threatens non-structural trim applications; preemptive investment in low-VOC coating chemistry expertise defends specification share against emerging biocomposite entrants. Backward integration into compounding operations secures traceable post-consumer feedstock access. For New Entrants and Emerging Players: Fleet procurement departments at North American and Chinese ride-hailing operators represent an underserved buyer archetype prioritizing durability over aesthetic refinement. White-space opportunity exists in scuff-resistant surface chemistries and modular replaceability specifications exceeding traditional retail vehicle standards. India's PLI scheme offers incentive-linked cost advantages for localized compounding and molding operations serving export-qualified production. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-1 suppliers possessing integrated design-to-manufacture footprints and captive tooling partnerships. Long-term viability over the projection horizon favors entities with demonstrated REACH compliance absorption and specialized finishing capabilities. The signal to watch is ECHA SVHC candidate list expansion forcing flame-retardant additive reformulations and concentrating validation burdens among collaborative testing consortia participants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding | Secures traceable post-consumer PP feedstocks for REACH compliance in German OEM programs. |
| In-Mold Film Insert Technology Adoption | Halves finishing station capital footprint for dashboard manufacturing lines in Japan and Germany. |
| Specialized Surface Finishing Acquisition | Absorbs EPA VOC compliance costs while meeting premium OEM haptic specifications simultaneously. |
| India PLI Scheme Manufacturing Footprint | Delivers 4-6% incentive-linked cost advantages for export-qualified trim production. |
| Collaborative Pre-Competitive Testing Consortium | Distributes ECHA SVHC retesting obligations across PP compound suppliers in the EU. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, polymer compounders, and tooling specialists across Germany, China, and the United States. Secondary validation drew from vehicle production databases, IHS Markit registration data, ECHA SVHC candidate list updates, and SEC filings from listed automotive suppliers. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Segment-weighting approaches modeled dashboard, door panel, center console, and armrest categories separately across material, manufacturing process, and end-user dimensions. Vehicle class, propulsion architecture, and content-per-vehicle metrics shaped volume assumptions across the projection horizon. CAGRs derived from production-weighted segment trajectories incorporating MIIT dual carbon goals, EPA VOC regulatory stringency, and fleet procurement specification shifts.
Inputs from OEM platform engineers and tier-1 supplier procurement were available through the study window; gaps in real-time tooling queue data and propylene feedstock contract terms introduce uncertainty bands around capacity expansion assumptions. Forecasts reflect documented assumptions regarding REACH recycled content mandate implementation timelines and ECHA SVHC list expansion scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
LED Fog Lamp Market