
 Global Wood Gas Generator Market | 2026-2036
Global Wood Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Gas Generator Market Analysis
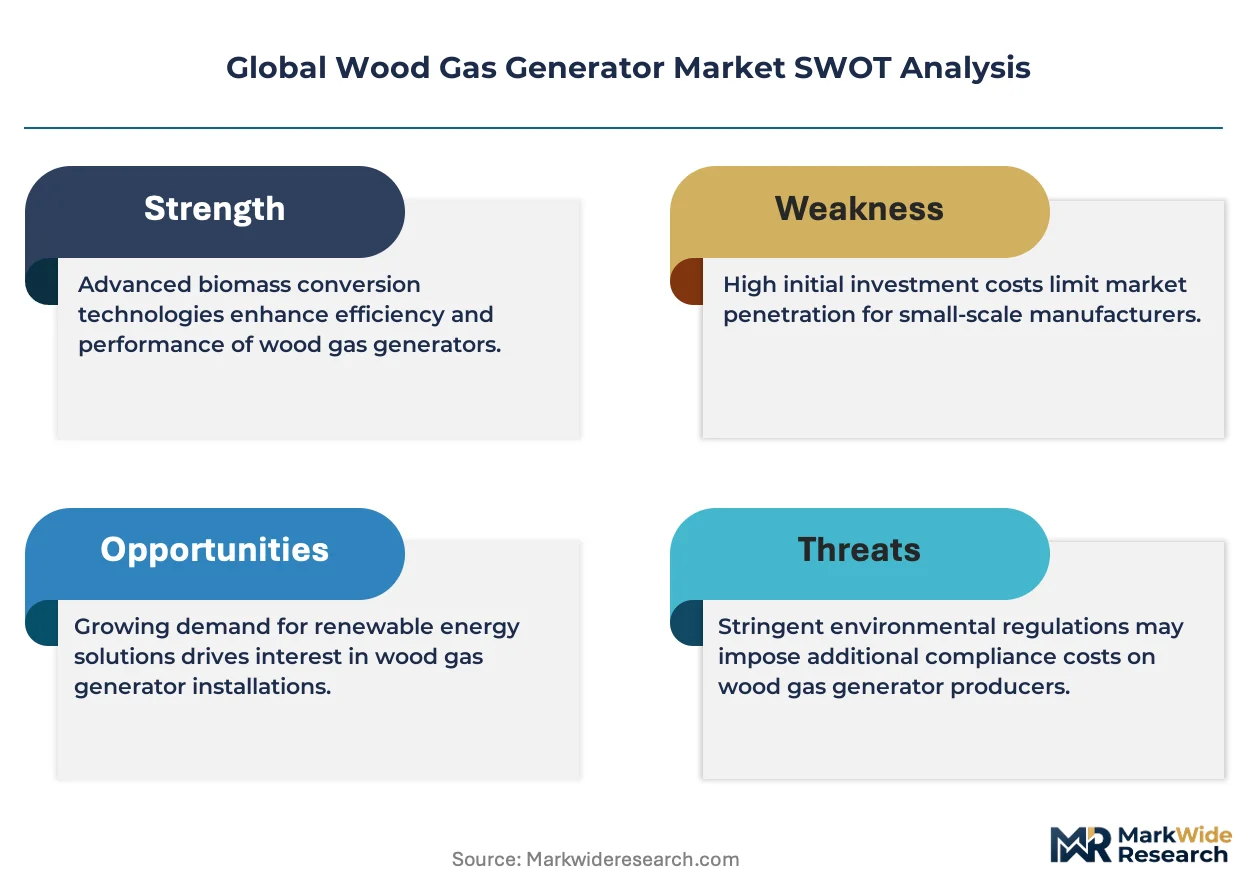
The gap between premium European-engineered systems and commodity Asian-manufactured units is expanding across power output bands and automation levels. SynCraft Engineering GmbH dominates the premium stationary segment through Austrian fabrication standards and integrated heat-recovery architecture. Zhengzhou Fubang Machinery Co. Ltd. competes on cost-optimized portable designs for emerging markets. All Power Labs anchors the open-source hardware niche with modular GEK Gasifier kits that sustain maker-community loyalty.
Wood gas generators convert lignocellulosic biomass into combustible syngas through controlled partial oxidation, typically operating at 800–1,200°C with tar cracking thresholds dictating engine compatibility. Stationary generators lead the product mix where continuous agricultural and industrial heat-power cogeneration justifies capital investment. Gasification technology outperforms direct combustion in thermal efficiency, though pyrolysis variants are gaining traction for biochar co-production in regenerative farming applications. Utility providers represent the fastest-growing end-user channel as grid-stabilization contracts reward dispatchable renewable capacity.
The EPA enforces New Source Performance Standards on biomass combustion systems above 25 MW thermal input, while the EU Green Deal's revised Renewable Energy Directive certifies sustainable feedstock sourcing for tariff eligibility. India's MNRE biomass power program mandates gasifier-specific efficiency benchmarks under its off-grid rural electrification mandate. Stakeholders must monitor how carbon border adjustment mechanisms treat imported gasifier equipment versus domestically manufactured units.
Market Dynamics
The EU Green Deal's tightening emission thresholds for decentralized power systems are forcing equipment manufacturers to redesign gasification architectures around real-time tar monitoring and automated air-ratio controls. This regulatory pressure is compressing the performance gap between European-engineered premium units and cost-optimized Asian alternatives.
Growth Catalysts
- India's MNRE biomass power program:Gasifier-specific efficiency benchmarks under rural electrification mandates are pulling capital into woody biomass feedstock systems across Maharashtra and Karnataka.
- Off-grid agricultural operations:Southeast Asian palm oil and rubber plantations are deploying skid-mounted gasifiers to displace diesel irrigation pumps and drying kilns.
- Pyrolysis-gasification hybrids:Regenerative farming operations in Brazil are purchasing systems that co-produce biochar for soil carbon credits alongside dispatchable power.
Market Restraints
- Feedstock supply concentration:Sustainable woody biomass certification under EU Renewable Energy Directive rules limits eligible feedstock to specific forestry residues and energy crop categories, constraining project siting.
- Technical limitation:Tar cracking thresholds above 1,000°C remain necessary for spark-ignition engine compatibility, adding refractory cost and thermal management complexity.
- Substitution threat:Containerized solar-plus-battery microgrids are capturing rural electrification tenders in East Africa and island Southeast Asia where gasification had been the incumbent technology.
Strategic Opportunities
- Grid-stabilization contracts:German utility providers are procuring dispatchable renewable capacity from agricultural gasifier operators under 15-year power purchase agreements.
- Carbon border adjustment mechanisms:The EU's CBAM treatment of imported gasifier equipment versus domestically manufactured units creates localization incentives for European fabrication.
- Maker-community distribution:Open-source hardware channels are penetrating hobbyist and smallholder segments in Australia and North America through modular kit assembly models.
Industry Challenges
- Tar analysis technician shortage:Gasifier commissioning and maintenance requires specialized skills in chromatographic tar sampling that vocational programs in emerging markets have not scaled.
- Refractory replacement cycles:High-temperature reactor linings require capital-intensive rebuilds every 8,000-12,000 operating hours, complicating project finance structures.
- Engine warranty voiding:Syngas fuel quality variance outside OEM specifications risks voiding spark-ignition engine warranties, creating liability disputes between gasifier suppliers and genset manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Gas Generator Market |
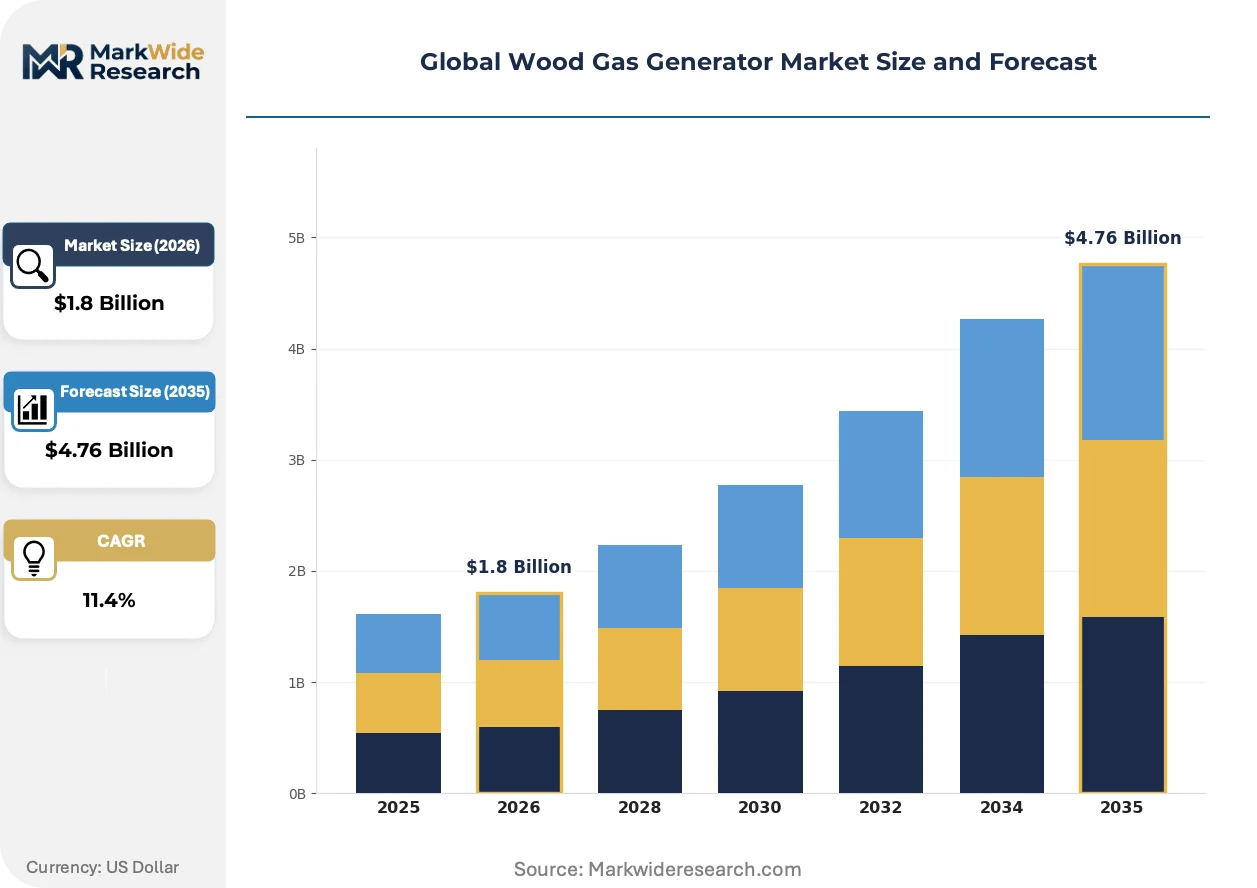
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Stationary Generators, Hybrid Models, Industrial Generators Technology: Gasification, Pyrolysis, Anaerobic Digestion, Direct Combustion End User: Residential Users, Small Businesses, Agriculture Sector, Utility Providers Application: Power Generation, Heating Solutions, Backup Energy, Waste Management |
| Companies Covered | SynCraft Engineering GmbH, Tactical Wood Gas Inc., Trillion Gasifiers, Vulcan Gasifier LLC, Zhengzhou Fubang Machinery Co. Ltd., All Power Labs, Biomass Energy Systems, Inc., GEK Gasifier, Ankur Scientific Energy Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Gas Generator Market Emerging Trajectories
Automation and real-time sensor integration are transforming gasifier operation from batch-fed manual systems to continuous processes with minimal operator intervention. Three developments are compressing operational cost structures and expanding addressable end-use segments.
Lambda sensor arrays paired with variable-speed blower controls are automating air-fuel ratio adjustments that previously required hourly operator intervention. German agricultural cooperatives are retrofitting existing fixed-bed units with these systems to achieve 24-hour unattended operation during harvest-season peak loads. This automation is compressing labor cost differentials between European and Asian equipment, narrowing the total-cost-of-ownership gap.
The EPA's New Source Performance Standards for biomass combustion systems above 25 MW thermal input are mandating continuous emissions monitoring systems that integrate with state air quality databases. Industrial heat-power cogeneration facilities in the US Midwest are selecting gasification over direct combustion specifically to meet these thresholds through inherent thermal efficiency advantages. Equipment suppliers are responding by pre-certifying reactor packages with integrated CEMS architectures.
Utility procurement departments are unbundling after-sales service contracts from equipment supply, selecting third-party O&M specialists through competitive tender rather than accepting captive service terms from original manufacturers. This pattern is most visible in Brazil's rural electrification concessions, where state-owned distributors now specify multi-vendor maintenance pools. The shift is forcing gasifier OEMs to publish open diagnostic protocols and standardize spare part geometries.
Global Wood Gas Generator Market Segmentation
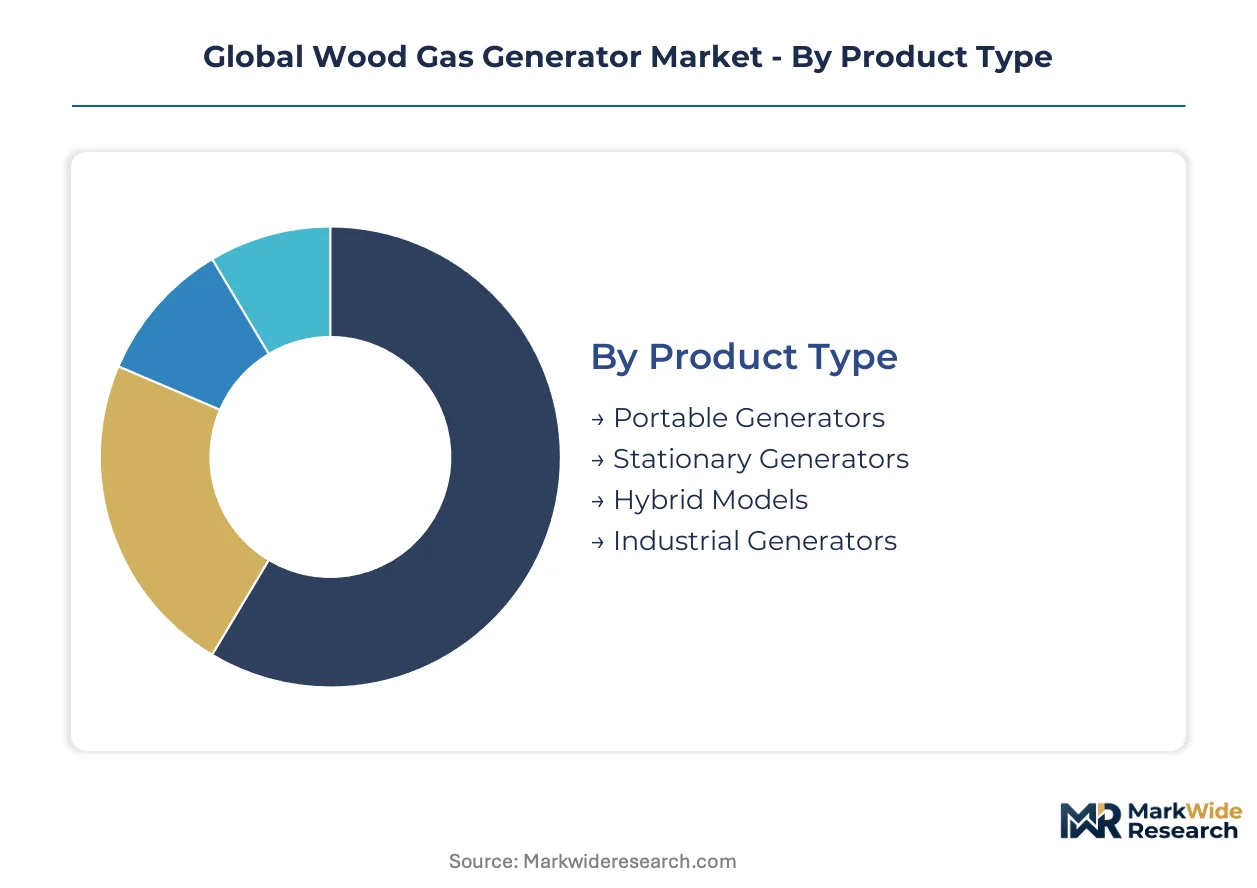
Wood gas generator configurations vary sharply in capital requirements, automation levels, and feedstock handling capabilities. Equipment buyers align product selection with duty cycles, grid access, and thermal integration needs across agricultural, industrial, and utility applications.
Product Type:
Capital intensity escalates from portable field units through permanently installed industrial systems requiring civil works and grid interconnection infrastructure.
- Portable Generators:Skid-mounted or trailer-towed systems with sub-50kW output dominate Southeast Asian palm oil plantations displacing diesel irrigation pumps. Operators prioritize rapid relocation between harvest blocks and minimal foundation requirements over thermal efficiency.
- Stationary Generators:Fixed-bed downdraft reactors with integrated heat recovery architecture anchor German agricultural cooperatives pursuing 24-hour unattended operation. These systems command premium pricing through Austrian fabrication standards and automated air-ratio controls that satisfy EU Green Deal emission thresholds.
- Hybrid Models:Dual-fuel configurations blending syngas with propane or natural gas buffer against feedstock moisture variability.
- Industrial Generators:Multi-megawatt fluidized bed systems serve US Midwest cogeneration facilities subject to EPA New Source Performance Standards above 25 MW thermal input.
Stationary generators absorb the bulk of installed capacity; portable units are expanding most quickly across emerging market agricultural electrification programs.
Technology:
Process selection determines tar burden, thermal efficiency, and co-product revenue streams that reshape project economics across feedstock categories.
- Gasification:Partial oxidation at 800–1,200°C with controlled air injection yields combustible syngas for spark-ignition engines. German utilities procure dispatchable renewable capacity from agricultural gasifier operators under 15-year power purchase agreements that reward grid stabilization services.
- Pyrolysis:Oxygen-starved thermal decomposition produces biochar alongside syngas, capturing Brazilian regenerative farming operations seeking soil carbon credit revenue. Systems operate at lower temperatures than gasification, reducing refractory maintenance cycles.
- Anaerobic Digestion:Microbial breakdown of wet organic feedstocks complements woody biomass handling in mixed-waste applications.
- Direct Combustion:Simplest capital outlay but inferior thermal efficiency drives selection only where syngas cleanup costs exceed fuel savings.
Gasification claims dominant share in power-focused installations; pyrolysis configurations show steepest expansion trajectory where carbon credit markets reward biochar co-production.
End User:
Customer scale and technical sophistication dictate automation requirements, service contract structures, and financing instrument availability.
- Utility Providers:Grid operators in Brazil and Germany unbundle equipment supply from third-party O&M contracts, forcing OEMs to publish open diagnostic protocols. Procurement departments specify multi-vendor maintenance pools and standardized spare part geometries under 15-year concession agreements.
- Agriculture Sector:Cooperatives and plantation operators across Maharashtra and Karnataka deploy skid-mounted units under India's MNRE biomass power program. These customers prioritize diesel displacement in irrigation and drying operations over grid export revenue.
- Small Businesses:Sawmills and food processors seek combined heat-power applications with payback periods under five years.
- Residential Users:Hobbyist and smallholder segments in Australia and North America assemble modular open-source kits with minimal professional commissioning.
Utility providers command the largest unit scale per installation; agricultural deployment is gaining share fastest as rural electrification programs prioritize woody biomass systems.
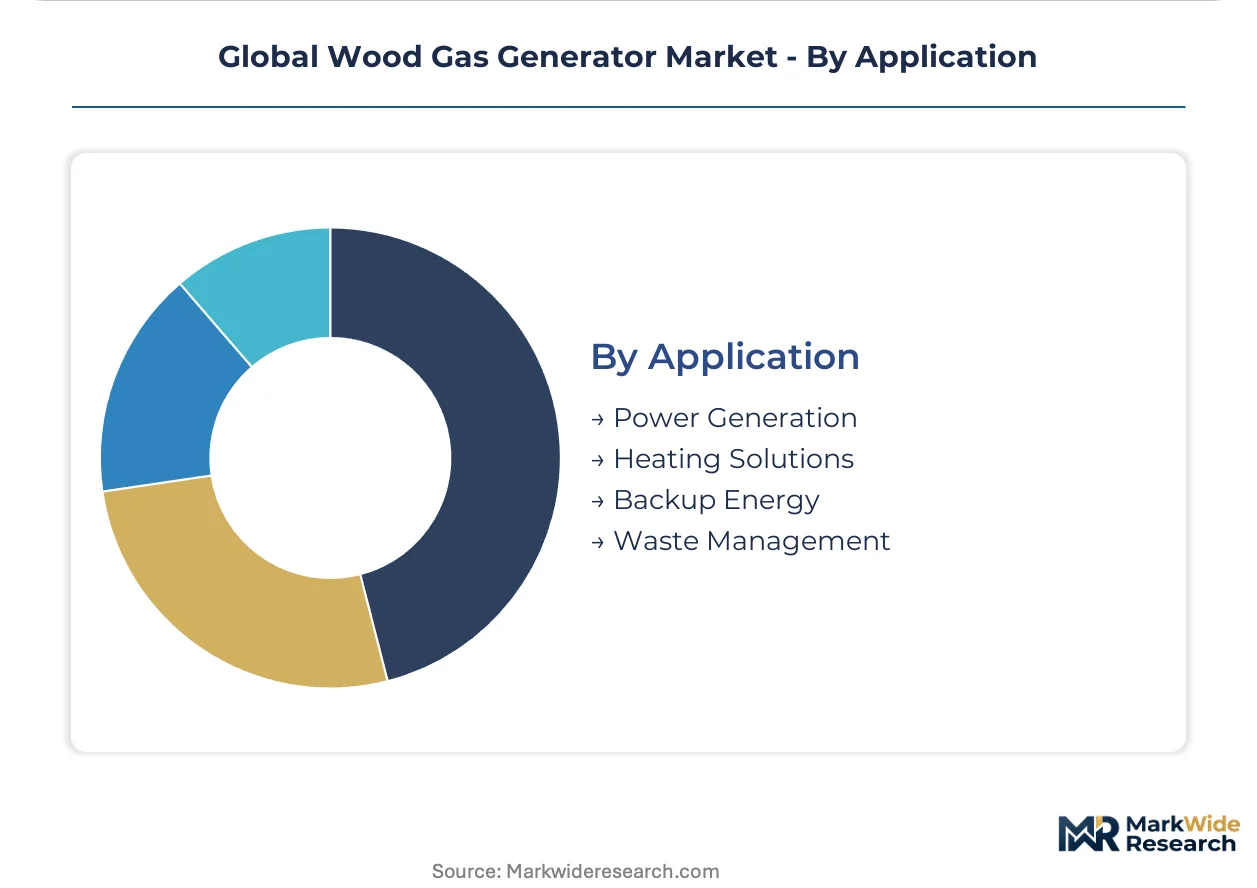
Application:
Revenue model and duty cycle requirements segment equipment specifications between continuous baseload, seasonal peak shaving, and emergency reserve functions.
- Power Generation:Continuous operation demands automated feedstock handling, real-time tar monitoring, and lambda sensor arrays for air-fuel ratio control. German agricultural cooperatives retrofit fixed-bed units to achieve unattended operation during harvest-season peak loads.
- Heating Solutions:Combined heat-power cogeneration justifies premium stationary systems where thermal demand anchors year-round capacity factors. US Midwest industrial facilities select gasification over direct combustion specifically to meet EPA emission thresholds through inherent thermal efficiency advantages.
- Backup Energy:Intermittent duty cycles tolerate higher manual intervention and simpler tar cracking architectures.
- Waste Management:Forestry residue and energy crop conversion addresses EU Renewable Energy Directive sustainable feedstock certification requirements.
Power generation applications absorb dominant capital deployment; heating solutions are climbing fastest as industrial heat decarbonization tightens emission regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's sugarcane belt anchors woody biomass gasification deployment through cooperative-owned irrigation systems and distillery cogeneration plants. Rural electrification corridors in Karnataka and Telangana are replicating this model with state-backed capital subsidies.
Germany
Agricultural cooperatives in Bavaria and Lower Saxony deploy automated downdraft systems for 24-hour unattended operation during harvest peaks. The EU Green Deal's revised Renewable Energy Directive certifies sustainable feedstock sourcing for tariff eligibility, tightening emission thresholds for decentralized power. E.ON and regional utilities in Baden-Württemberg procure dispatchable renewable capacity from biogas and gasifier operators under 15-year power purchase agreements.
India
Maharashtra and Karnataka plantation operators deploy skid-mounted units to displace diesel irrigation pumps under MNRE biomass power program mandates. The Central Electricity Authority specifies gasifier-specific efficiency benchmarks for off-grid rural electrification. Tamil Nadu's textile belt is adopting combined heat-power systems for drying operations, with state nodal agencies channeling priority sector lending toward woody biomass feedstock projects.
Brazil
São Paulo state's sugarcane processing clusters integrate gasification for bagasse and forestry residue conversion, with regenerative farming operations in Minas Gerais purchasing pyrolysis-gasification hybrids for biochar co-production. ANVISA's environmental licensing framework governs industrial emissions, while state-owned distributors unbundle equipment supply from third-party O&M contracts under rural electrification concessions.
United States
Midwest industrial facilities in Ohio and Illinois select gasification over direct combustion to meet EPA New Source Performance Standards above 25 MW thermal input. The Inflation Reduction Act's clean energy tax credits reward dispatchable renewable capacity in agricultural processing corridors. Iowa's ethanol plants and Wisconsin's paper mills are retrofitting existing biomass boilers with integrated gasification architecture for combined heat-power applications.
Australia
Victoria's timber processing regions and Queensland's sugar milling districts deploy containerized systems for grid-stabilization services. The Clean Energy Regulator's biomass certification protocols align with EU sustainable feedstock standards, enabling export-oriented biochar producers to access European carbon credit markets. Western Australia's wheat belt is piloting open-source hardware kits for smallholder irrigation through state agricultural extension programs.
Global Wood Gas Generator Market Vendor Landscape
Premium-margin players sit above commodity-margin players across automation levels and fabrication standards, with Austrian and German engineering commanding 40-60% price premiums over Asian-manufactured equivalents. The vendor base stratifies into three tiers: integrated heat-recovery specialists, cost-optimized portable fabricators, and open-source hardware distributors. Consolidation pressure is mounting as utility procurement departments unbundle after-sales service contracts from equipment supply, forcing OEMs to publish open diagnostic protocols and standardize spare part geometries.
Among European-engineered specialists, SynCraft Engineering GmbH exemplifies the premium stationary segment through Austrian fabrication standards. Zhengzhou Fubang Machinery Co. Ltd. represents Chinese cost-optimized portable designs for emerging market agricultural electrification. All Power Labs occupies the open-source hardware niche with modular kit distribution sustaining maker-community penetration in Australia and North America.
| Leading Market Players |
|---|
| SynCraft Engineering GmbH |
| Tactical Wood Gas Inc. |
| Trillion Gasifiers |
| Vulcan Gasifier LLC |
| Zhengzhou Fubang Machinery Co. Ltd. |
| All Power Labs |
| Biomass Energy Systems, Inc. |
| GEK Gasifier |
| Ankur Scientific Energy Technologies |
| Others |
Supply Flow & Price Mechanics
German utility procurement departments concentrate purchasing power through unbundled equipment supply and third-party O&M contracts, anchoring the market around value-based pricing tied to dispatchable capacity guarantees and grid-stabilization performance rather than capital cost alone.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and grid-stabilization service contracts separates premium Austrian-engineered stationary systems from cost-optimized Asian portable units. Price differentiation rests on automation levels and EU Green Deal emission certification tiers, with automated air-ratio controls commanding substantial premiums over manual batch-fed alternatives. Cost compression in the portable segment is intensifying as Zhengzhou Fubang Machinery and comparable Chinese fabricators scale output for Southeast Asian agricultural electrification tenders. Agricultural cooperatives in India and Brazil exhibit highest price sensitivity, prioritizing diesel displacement payback periods over long-term efficiency metrics.
Supply Chain Analysis
Freight costs for refractory-lined reactor vessels and precision-engineered gas cleanup trains concentrate supply chain leverage with Austrian and German fabricators serving premium stationary markets, while containerized portable units from Chinese manufacturers exploit lower logistics intensity for emerging market distribution. Manufacturing concentration centers on Austria, Germany, and China, with reactor fabrication and automation system integration drawing from specialized steel foundries and sensor electronics clusters. Supply chain risk hinges on single-source dependency for high-temperature ceramic linings and lambda sensor arrays. Distribution runs through direct OEM sales for utility-scale projects, regional distributors for agricultural segments, and open-source hardware channels for hobbyist markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refractory technician scarcity and extended replacement cycles constrain installed capacity expansion, propping pricing power for OEMs with captive service networks and standardized spare part geometries.
For Market Incumbents: Acquire specialized tar analysis and refractory maintenance capabilities to lock in aftermarket revenue streams. Defensive consolidation should target Brazilian and Indian regional service providers before utility procurement departments complete vendor pool standardization. Containerized solar-plus-battery substitution in East African rural electrification tenders threatens gasification's incumbent position in irrigation pumping applications. For New Entrants and Emerging Players: Open-source hardware distribution channels offer the lowest customer acquisition cost path into Australian and North American smallholder segments. White-space concentration sits with pyrolysis-gasification hybrid systems for Brazilian regenerative farming operations seeking biochar co-production revenue. Maker-community assembly models bypass capital-intensive fabrication infrastructure while building brand recognition for eventual utility channel entry. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive refractory supply and automated control system IP. Long-term viability hinges on carbon border adjustment mechanism localization incentives and EU Green Deal tariff eligibility certification. Watch German utility PPA procurement volumes as the inflection signal for dispatchable renewable capacity investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Supply | Captive ceramic lining production compresses replacement cycle costs and accelerates service response times for agricultural cooperatives. |
| Automation System Certification | EU Green Deal emission threshold compliance unlocks tariff eligibility for German and Austrian engineered systems under revised Renewable Energy Directive rules. |
| Open-Source Hardware Expansion | Modular GEK Gasifier kit distribution penetrates Australian and North American hobbyist segments with minimal capital deployment. |
| Third-Party O&M Contract Capture | Brazilian and German utility unbundling of service from equipment supply creates multi-vendor maintenance pool opportunities for independent specialists. |
| Pyrolysis-Gasification Hybrid Development | Biochar co-production capability captures Brazilian regenerative farming demand and European carbon credit market access. |
Methodological Framework
Document review covered EPA New Source Performance Standards filings, EU Renewable Energy Directive implementation guidance, and India MNRE biomass power program specifications, complemented by interviews with gasifier OEM technical directors, agricultural cooperative energy managers, utility procurement officers, and refractory supply chain specialists. Secondary validation drew from customs trade data for gasifier equipment, FERC interconnection queue filings for biomass cogeneration projects, and IEA bioenergy deployment databases. Bottom-up unit deployment estimates across Maharashtra, Karnataka, Bavaria, and São Paulo state were triangulated against top-down market value projections.
Historical deployment trajectories in German agricultural cooperatives and Indian rural electrification corridors were cross-referenced against expert panel inputs from EPC contractors and project finance lenders. The analytical framework segmented modeled output by product type (portable, stationary, industrial), technology configuration (gasification, pyrolysis, hybrid), and end-user channel (utility, agriculture, small business, residential) across the projection horizon. CAGRs were derived from regression analysis of installed capacity growth correlated with diesel price spreads and carbon credit market development. Forecast inputs incorporated EU Green Deal emission threshold implementation timelines and EPA enforcement patterns for biomass combustion systems.
Inputs from MNRE program administrators and German utility planning departments were available through the study window; gaps in real-time operating data from Southeast Asian palm oil plantation deployments introduce uncertainty bands around portable unit utilization assumptions. Forecasts reflect documented regulatory implementation schedules and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Fuel Conditioning System Market
Fuels
Gas Hydrates Market
Fuels
Mobile Gas Pumping System Market
Fuels
Marine Fuel Filter Market
Fuels
North America LNG Bunkering Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Renewable Heating Fuels Market
Fuels
Oil Dispensing Stations Market
Fuels
Diesel Fuel Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
Iso-Octane Market
Fuels
Bunker Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
India Bunker Fuel Market
Fuels
Italy Chemical Logistics Market
Fuels
LPG Gas Cylinder Market