
 Diesel Fuel Market | 2026-2036
Diesel Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Fuel Market Analysis
The buyer base for diesel fuel is broadening beyond traditional fleet operators to encompass data-center backup power contractors, remote mining ventures, and agricultural cooperatives seeking bulk supply contracts. Shell plc leverages its integrated refining network to sustain cost-advantaged positions across multiple continents. Exxon Mobil Corporation anchors its competitive stance through proprietary hydroprocessing technology that yields higher cetane grades. Saudi Aramco dominates Middle Eastern export volumes with direct crude-to-product integration.
Diesel fuel denotes a middle-distillate petroleum product composed of hydrocarbon chains ranging from C10 to C22, manufactured via fractional distillation and hydrocracking, with a minimum cetane index of 40 and sulfur content regulated below 10-15 ppm for on-road applications in most jurisdictions; it serves primarily as compression-ignition engine fuel for heavy-duty transport, stationary power generation, and off-road machinery. Ultra-low sulfur diesel occupies the largest value share given its universal mandate for on-road vehicles across OECD economies, while renewable diesel commands expanding capacity investments as refiners retrofit facilities to process biomass feedstocks. The marine end-user segment presents concentrated margin pools as IMO sulfur caps drive vessel operators toward premium low-sulfur distillates or exhaust treatment systems.
The EPA enforces Tier 3 and upcoming Tier 4 standards for non-road diesel engines, compressing allowable particulate and NOx emissions and forcing reformulation investments by domestic blenders. The EU Green Deal and REACH framework impose carbon-intensity reporting on fuel imports, reshaping trade flows toward certified lower-carbon supply sources. India's BIS specifications for automotive diesel align with Bharat Stage VI norms, tightening national access for unverified foreign cargoes. Stakeholders must monitor regulatory divergence between sulfur-content mandates and carbon-accounting rules to anticipate which product grades will retain offtake priority.
Market Dynamics
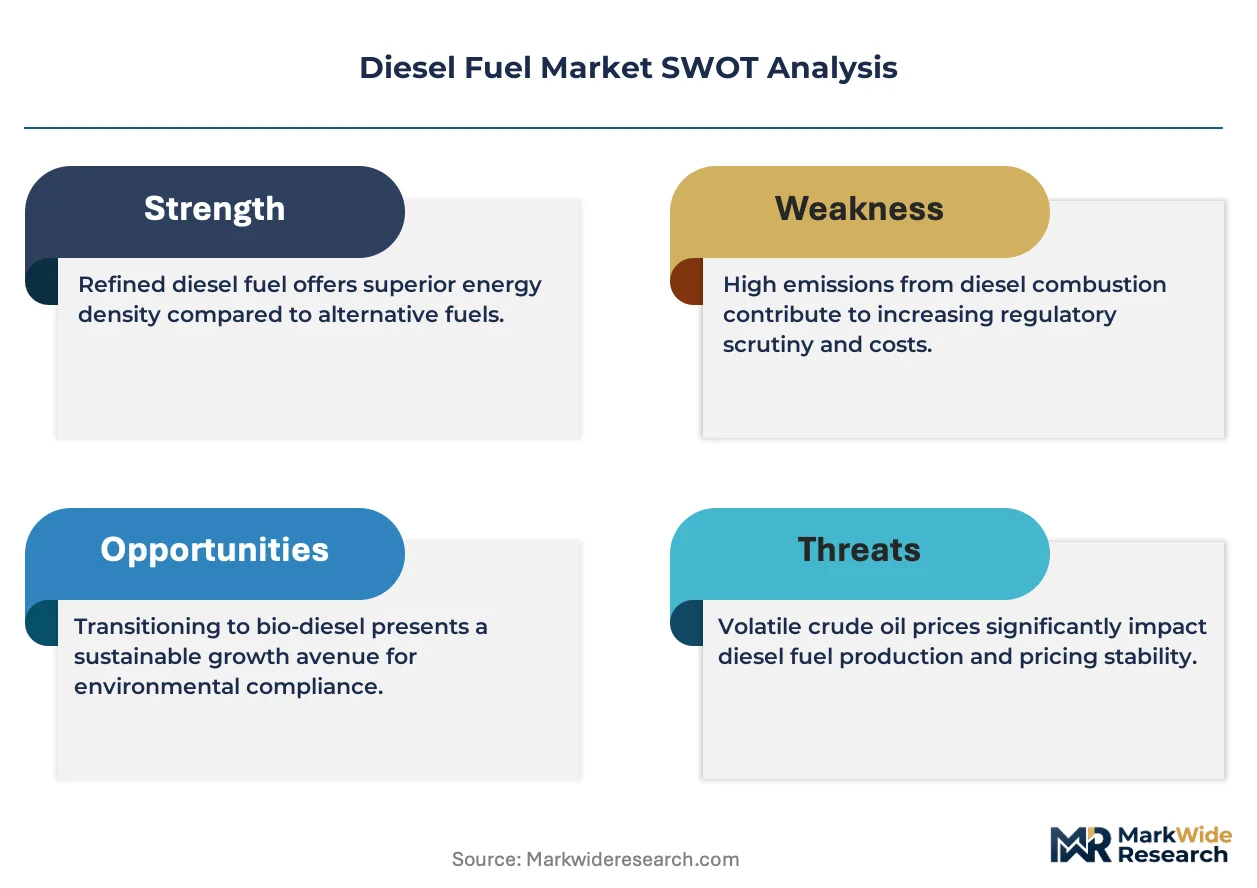
Ultra-low sulfur diesel mandates are compressing refinery margins while forcing capital redeployment toward hydrotreating capacity, as marine bunker fuel specifications tighten under IMO enforcement and on-road standards converge across major economies.
Growth Catalysts
- BIS Stage VI norms:India's sulfur caps at 10 ppm are accelerating domestic refinery upgrades and import substitution for compliant diesel grades.
- Data center backup power:Hyperscale facility operators are contracting for dedicated diesel reserves to bridge grid reliability gaps during peak demand.
- Renewable diesel retrofitting:Hydroprocessed esters and fatty acids capacity is expanding as refiners process used cooking oil and tallow alongside crude streams.
Market Restraints
- Crude price volatility:Middle distillate crack spreads fluctuate with Brent benchmark swings, compressing blender margins during upstream cost spikes.
- Refinery concentration:The US Gulf Coast and Rotterdam-Antwerp-Amsterdam cluster control disproportionate hydroprocessing capacity, creating geographic supply vulnerability.
- Electrification substitution:Battery-electric trucks and rail electrification projects are displacing diesel offtake in freight corridors with grid reliability.
Strategic Opportunities
- Brazilian agribusiness:Remote soybean and corn operations lack grid access, creating captive demand for bulk diesel logistics contracts.
- EU Green Deal certification:Carbon-intensity labeling for fuel imports is opening premium positioning for renewable diesel and certified lower-carbon supply chains.
- Marine scrubber economics:Vessel operators are arbitraging between high-sulfur fuel oil with exhaust treatment and premium low-sulfur distillates based on route-specific compliance costs.
Industry Challenges
- Hydrotreater catalyst expertise:Specialized knowledge for sulfur removal and cetane enhancement is concentrated among retiring refinery engineering cohorts.
- Multi-jurisdiction certification:Blendstock approvals must satisfy divergent EPA, REACH, and BIS testing protocols, extending product launch timelines.
- Legacy tank farm compatibility:Existing storage infrastructure requires metallurgical assessment before handling fatty acid methyl ester blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Fuel Market |
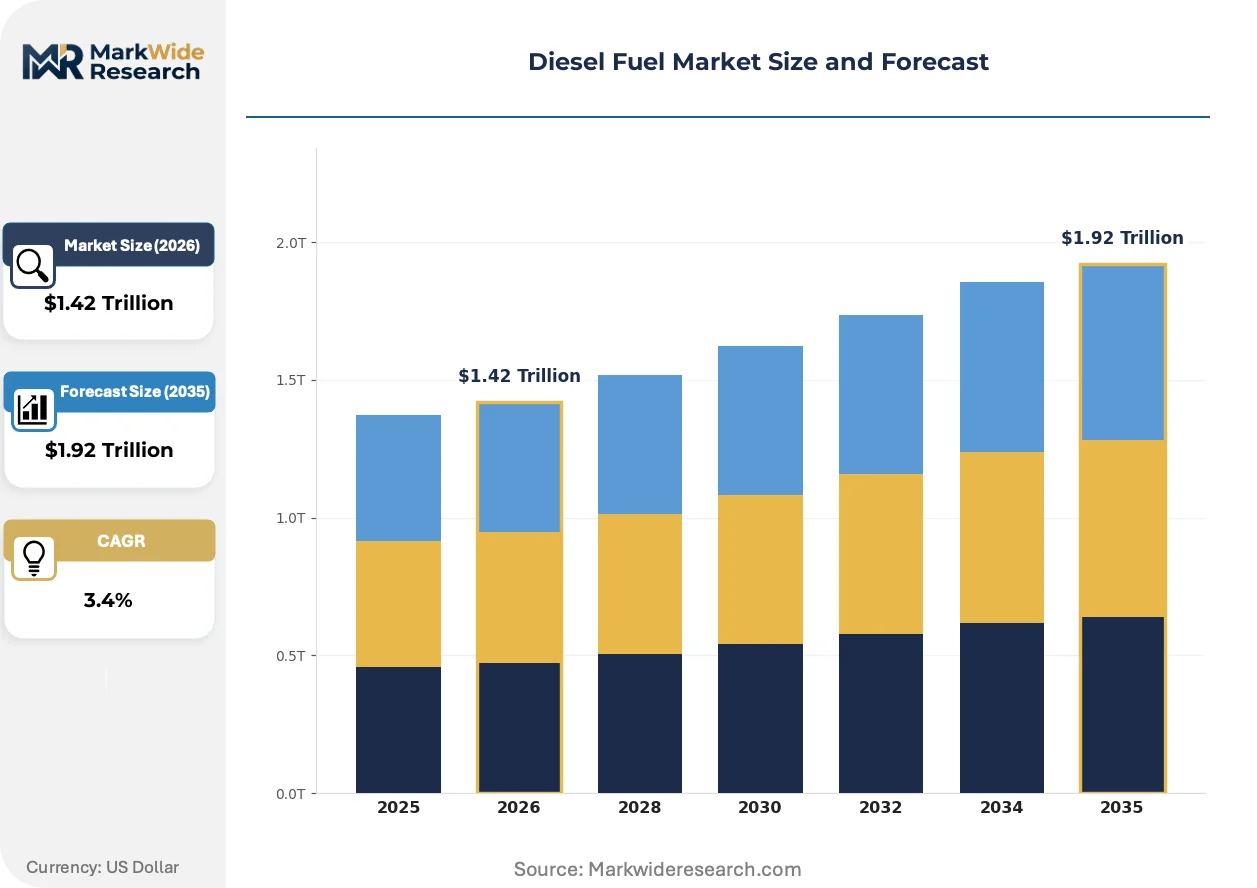
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $1.92 Trillion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-Low Sulfur Diesel, Biodiesel, Renewable Diesel, Diesel Oil End User: Transport Sector, Agriculture, Construction, Marine Distribution Channel: Retail Outlet, Bulk Supply, Online Sales, Fuel Terminal Application: On-Road Vehicles, Off-Road Vehicles, Generators, Industrial Equipment |
| Companies Covered | Shell plc, Exxon Mobil Corporation, Chevron Corporation, Saudi Aramco, PetroChina Company Limited, BP p.l.c., China Petroleum & Chemical Corporation (Sinopec), Reliance Industries Limited, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Fuel Market Emerging Trajectories
Refining technology and fuel specifications are advancing in parallel, with hydrotreating investments, renewable feedstock integration, and bunker fuel compliance creating overlapping transformation pressures across the value chain.
Co-processing technology is converging with conventional fluid catalytic cracking units to handle lipid-based feedstocks without dedicated standalone renewable diesel facilities. European refiners led by Neste's technology licensing are retrofitting existing assets to process 20-30% renewable content. This convergence is compressing capital requirements for low-carbon fuel entry and blurring product category boundaries between fossil and bio-based diesel.
REACH carbon-intensity reporting obligations now extend to fuel importers, requiring lifecycle emissions documentation from wellhead to combustion. The EU Green Deal framework is forcing traders to source certified lower-carbon cargoes or face margin penalties in regulated markets. Marine fuel suppliers serving Rotterdam and Hamburg are restructuring procurement to secure verifiable supply chains ahead of 2026 disclosure deadlines.
Long-term contracting is displacing spot market purchases among data center operators seeking price stability for backup generator fuel. Amazon Web Services and Microsoft Azure infrastructure teams are negotiating three-to-five-year supply agreements directly with refiners, bypassing traditional distributor networks. This pattern is most visible in Virginia's Loudoun County and Singapore's Tuas data center clusters where facility concentration enables direct supplier relationships.
Diesel Fuel Market Segmentation
Diesel fuel segmentation reveals how regulatory mandates and end-use economics split procurement patterns across incompatible specification tiers. Understanding these divides exposes where capital redeploys and margins concentrate.
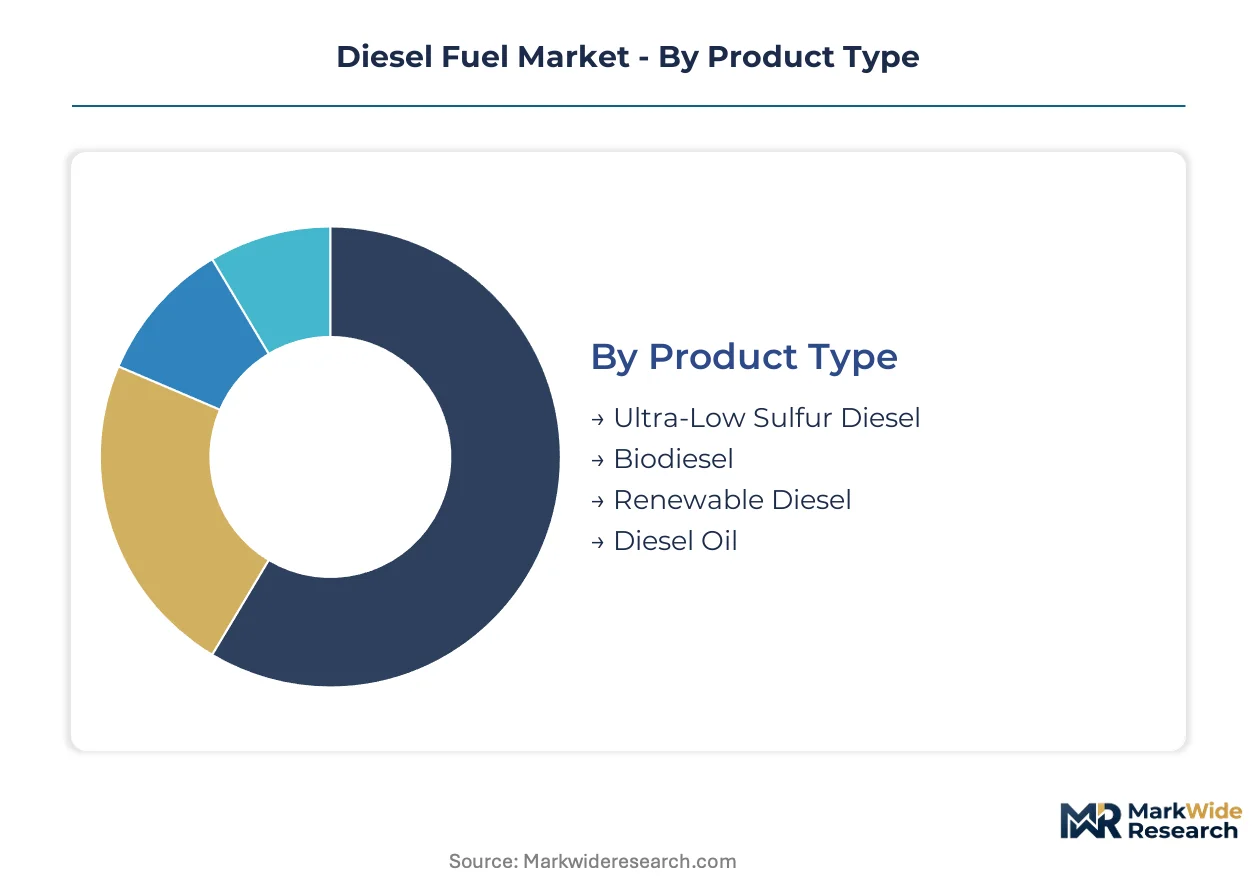
Product Type:
Ultra-low sulfur grades dominate volume flows while renewable variants capture premium positioning.
- Ultra-Low Sulfur Diesel:Hydrotreated middle distillate meeting 10-15 ppm sulfur caps for on-road compliance. Fleet operators in India and the United States anchor procurement volumes as BIS Stage VI and EPA Tier 3 enforcement harden. Refinery hydrotreater utilization rates determine regional availability.
- Renewable Diesel:Hydroprocessed esters and fatty acids derived from biomass feedstocks with identical molecular structure to fossil diesel. EU Green Deal certification schemes in Rotterdam and Hamburg are redirecting import flows toward verifiable lower-carbon supply chains. Neste's technology licensing enables refinery retrofitting without standalone facilities.
- Biodiesel:Fatty acid methyl ester blends requiring separate handling infrastructure and cold-flow additives.
- Diesel Oil:Higher-sulfur distillate grades relegated to off-road and stationary applications with relaxed emission limits.
Today's leader: Ultra-Low Sulfur Diesel. Tomorrow's challenger: Renewable Diesel.
End User:
Transport absorbs the largest volume share while marine commands the steepest specification premiums.
- Transport Sector:Heavy-duty trucking, rail freight, and bus fleets operating under mandatory sulfur caps. Long-haul corridors in China and India sustain bulk contracting as electrification progresses slowly on intercity routes.
- Marine:Bunker fuel procurement for container vessels and bulk carriers navigating IMO sulfur enforcement. Ship operators arbitrage between scrubber-equipped high-sulfur fuel oil and premium low-sulfur distillates based on route-specific compliance costs.
- Agriculture:Remote farming operations lacking grid access for machinery and irrigation pumps.
- Construction:Off-road equipment fleets subject to EPA Tier 4 non-road engine standards.
Transport Sector retains volume dominance. Marine captures expanding margin pools.
Distribution Channel:
Direct refinery relationships are displacing traditional intermediaries for large-volume consumers.
- Bulk Supply:Dedicated pipeline and tanker deliveries to mining ventures, agricultural cooperatives, and data center operators. Amazon Web Services and Microsoft Azure infrastructure teams in Virginia's Loudoun County negotiate multi-year agreements bypassing distributor networks.
- Fuel Terminal:Wholesale storage and blending facilities serving regional distributor networks with specification flexibility.
- Retail Outlet:Branded and unbranded service stations for fragmented fleet and consumer demand.
- Online Sales:Digital procurement platforms for small-scale agricultural and construction customers.
Bulk Supply deepens direct relationships. Fuel Terminal retains intermediary relevance.
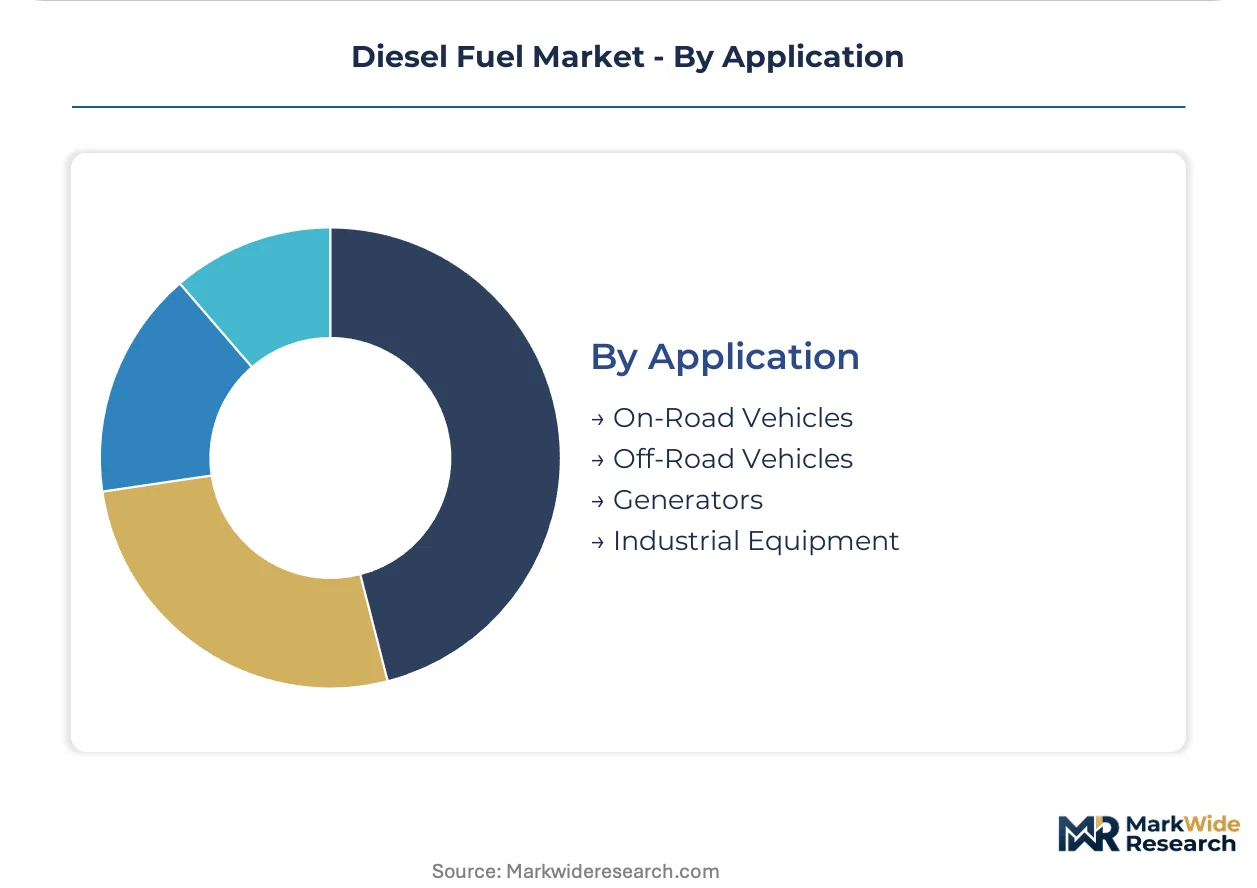
Application:
On-road compliance requirements fragment product flows from off-road and stationary uses.
- On-Road Vehicles:Compression-ignition engines for trucks and buses mandating ultra-low sulfur grades. India's freight corridors and US interstate networks concentrate demand as Bharat Stage VI and EPA standards converge.
- Generators:Stationary backup power for data centers, hospitals, and telecommunications. Hyperscale facility operators in Singapore's Tuas cluster contract dedicated reserves bridging grid reliability gaps.
- Off-Road Vehicles:Construction and agricultural machinery operating under relaxed sulfur limits.
- Industrial Equipment:Material handling and process machinery with variable specification tolerance.
On-Road Vehicles anchor specification investment. Generators drive contracting innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's freight corridors sustain heavier diesel procurement than China's electrifying truck routes, while the United States maintains bulk contracting for long-haul corridors where battery infrastructure remains sparse.
United States
Data center operators in Virginia's Loudoun County negotiate multi-year diesel reserves for backup generators as grid reliability concerns mount. EPA Tier 3 and upcoming Tier 4 standards compress particulate and NOx limits for non-road engines. The US Gulf Coast refining cluster controls disproportionate hydroprocessing capacity, creating geographic supply concentration.
India
Bharat Stage VI enforcement tightens national access for unverified foreign diesel cargoes as domestic refineries upgrade. BIS specifications mandate 10 ppm sulfur caps, accelerating import substitution for compliant grades. Freight corridors connecting Delhi to Mumbai sustain bulk contracting volumes as electrification progresses slowly on intercity routes.
China
Dual carbon goals and MEE emissions frameworks pressure refiners to balance diesel output against cleaner fuel mandates. State-owned processors dominate middle-distillate production with direct crude-to-product integration. The Yangtze River Delta industrial belt concentrates demand from manufacturing and port logistics operations.
Germany
REACH carbon-intensity reporting obligations force fuel importers to document lifecycle emissions from wellhead to combustion. The EU Green Deal framework redirects procurement toward certified lower-carbon supply chains. The Hamburg marine fuel hub restructures sourcing to secure verifiable supply chains ahead of disclosure deadlines.
Brazil
Remote soybean and corn operations in Mato Grosso lack grid access, creating captive demand for bulk diesel logistics contracts. ANVISA and environmental licensing frameworks govern fuel storage and distribution infrastructure. The São Paulo industrial corridor anchors distribution networks serving agricultural machinery and off-road equipment fleets.
Diesel Fuel Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the diesel fuel value chain. Integrated majors leverage captive crude supplies and refining networks to sustain cost-advantaged positions. Three archetypes dominate: state-backed national champions with upstream-downstream control, multinational integrated oil companies with proprietary hydroprocessing technology, and regional refiners specializing in specification-grade blending. Competitive moves concentrate on renewable diesel retrofitting and direct contracting relationships with large-volume consumers.
Among the integrated majors, Shell plc, Exxon Mobil Corporation, and Saudi Aramco exemplify distinct strategic positions. Shell occupies a role defined by geographic diversification across multiple continents. Exxon Mobil represents the technology-licensing archetype through proprietary hydroprocessing capabilities. Saudi Aramco anchors the state-backed model with direct crude-to-product integration and Middle Eastern export dominance.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| Saudi Aramco |
| PetroChina Company Limited |
| BP p.l.c. |
| China Petroleum & Chemical Corporation (Sinopec) |
| Reliance Industries Limited |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-intensity certification gates both qualified supply access and premium-tier pricing positioning for diesel importers serving Rotterdam and Hamburg. Traders lacking verifiable lower-carbon documentation face margin compression against certified competitors, while refiners with renewable diesel retrofitting capabilities capture structural price premiums.
Pricing Analysis
Capacity additions in the US Gulf Coast are reshaping price floors for ultra-low sulfur diesel as hydroprocessing utilization rates determine regional availability. Pricing stratifies across renewable diesel, ultra-low sulfur, and higher-sulfur off-road grades based on certification tier and sulfur content compliance. Cost compression in standard-grade distillates is intensifying because of crude price volatility compressing middle-distillate crack spreads. Fleet operators in India's freight corridors demonstrate highest price sensitivity, while data center operators in Virginia's Loudoun County accept premium long-term contract rates for supply security.
Supply Chain Analysis
IMO sulfur cap compliance certification gates marine bunker fuel supply access, forcing vessel operators toward verifiable low-sulfur distillate sourcing. Production concentrates in the United States, India, and Saudi Arabia as state-owned and integrated majors control disproportionate hydroprocessing capacity. Feedstock supply draws from Brent-linked crude benchmarks, biomass feedstocks including used cooking oil and tallow, and refinery intermediate streams. Single-source vulnerability concentrates in the Rotterdam-Antwerp-Amsterdam cluster for European marine fuel supply. Distribution runs through bulk pipeline and tanker deliveries to mining ventures, agricultural cooperatives, and hyperscale facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Marine bunker fuel specifications and data center backup power contracting are shifting procurement toward premium-certified diesel grades with verifiable carbon documentation.
For Market Incumbents: Acquire hydrotreater catalyst expertise and renewable diesel retrofitting capabilities to defend against electrification substitution in freight corridors. Shell plc and Exxon Mobil Corporation anchor positions through proprietary hydroprocessing technology and geographic diversification. Capacity additions in India and the Middle East threaten margin compression for undifferentiated standard-grade supply. For New Entrants and Emerging Players: Remote agricultural cooperatives in Brazil's Mato Grosso soybean belt represent an underserved buyer archetype lacking grid access and captive to bulk diesel logistics contracts. Direct contracting relationships with hyperscale data center operators in Singapore's Tuas cluster bypass entrenched distributor networks. Go-to-market positioning should emphasize dedicated reserve supply agreements with price stability guarantees. For Investors and Strategic Acquirers: Roll-up economics work for regional refiners specializing in specification-grade blending because certification complexity fragments the mid-tier supply base. Five-to-ten year viability hinges on renewable diesel retrofitting capex deployment and IMO compliance technology licensing. Watch marine scrubber adoption rates as the inflection signal determining high-sulfur fuel oil versus low-sulfur distillate demand split.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Retrofitting | Neste's technology licensing enables refiners to process biomass without standalone facilities. |
| Long-term Supply Agreement | Amazon Web Services negotiates multi-year diesel reserves bypassing traditional distributor networks. |
| Backward Integration | Saudi Aramco's crude-to-product integration sustains cost-advantaged export positions. |
| Green Certification Program | EU Green Deal documentation requirements redirect Rotterdam procurement toward verifiable supply chains. |
| Capacity Expansion | Indian refineries upgrade hydrotreating to meet BIS Stage VI sulfur caps and displace imports. |
Methodological Framework
Direct dialogue with refinery operations managers, marine fuel procurement officers at container lines, data center infrastructure directors, and agricultural cooperative supply heads grounded qualitative assessment. Secondary validation drew from EPA Tier 3 enforcement documentation, BIS Stage VI specification filings, IMO sulfur cap compliance reports, and EU Green Deal carbon-intensity disclosure frameworks. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the projection horizon.
Segment-level outputs reflect modeling across product type tiers, end-user verticals, distribution channel structures, and geographic regulatory clusters. CAGRs were derived from elasticity-adjusted demand projections incorporating electrification substitution rates and marine compliance technology adoption curves. Forecast inputs included refinery hydroprocessing utilization data, biomass feedstock availability indices, and bunker fuel scrubber installation tracking.
Underlying measurement precision varies by segment; renewable diesel capacity and marine bunker fuel flows carry tighter precision than fragmented agricultural procurement. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and crude price corridor stability. Deviation in battery-electric truck adoption rates or IMO sulfur cap waiver extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Pyrolysis Gas Market
Fuels
United States Bunker Fuel Market
Fuels
Turbine Drip Oil Market
Fuels
Marine Fuel Filter Market
Fuels
Gas Feed System Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Oil Dispenser Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Wood Pellet Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Europe Aviation Fuel Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Gasoline Octane Improvers Market
Fuels
Solid Fuel Tablet Market
Fuels
City Gas Distribution Market