
 India Bunker Fuel Market | 2026-2036
India Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
India Bunker Fuel Market Foresight
Container shipping is pivoting toward low-sulfur fuel oils as India's major ports tighten sulfur caps for vessels at berth. Indian Oil Corporation Limited anchors national supply through its coastal storage network, while Reliance Industries leverages its Jamnagar refining complex to dominate very low sulfur fuel oil output. Shell India competes on differentiated marine lubricant bundling at Mumbai and Chennai anchorages.
Bunker fuel denotes residual and distillate marine fuels combusted in two-stroke and four-stroke marine diesel engines, with sulfur content specifications ranging from 0.50% m/m under IMO 2020 to 0.10% m/m in designated emission control areas, serving propulsion and auxiliary power generation for commercial vessels. LSFO commands structural prominence as refiners optimize coker and hydrocracker yields to meet marine demand, while marine gas oil retains premium positioning among cruise ships and offshore support vessels requiring operational flexibility. Biofuel blends occupy an emergent niche as trial volumes scale at select Indian ports, though supply chain certification complexity constrains near-term margin pools.
The Directorate General of Shipping enforces MARPOL Annex VI compliance through port state control inspections, while the Central Pollution Control Board monitors coastal air quality standards that indirectly tighten vessel fuel specifications at Indian harbors. BIS certification requirements for marine fuel quality create entry barriers for unorganized resellers, channeling procurement toward integrated suppliers with laboratory testing capabilities. Stakeholders must track how India's proposed green hydrogen and ammonia bunkering roadmaps reshape long-term fuel infrastructure investments at Deendayal and Visakhapatnam port zones.
Market Dynamics
The India Bunker Fuel Market is undergoing structural recalibration as the Directorate General of Shipping enforces MARPOL Annex VI sulfur caps at major ports. Refiners and bunker suppliers are reconfiguring storage and blending infrastructure to serve container lines and bulk carriers navigating compliance deadlines.
Growth Catalysts
- IMO 2020 Sulfur Regulations:The 0.50% m/m global sulfur cap has triggered wholesale fuel-switching across Indian coastal shipping, forcing vessel operators into compliant fuel procurement contracts.
- Jawaharlal Nehru Port Trust Expansion:Container throughput growth at India's largest container gateway is generating concentrated bunker demand from deep-sea shipping lines.
- Coker Unit Upgrades:Refiners along Gujarat's refining corridor have installed residue upgrading capacity to produce very low sulfur fuel oil at scale.
Market Restraints
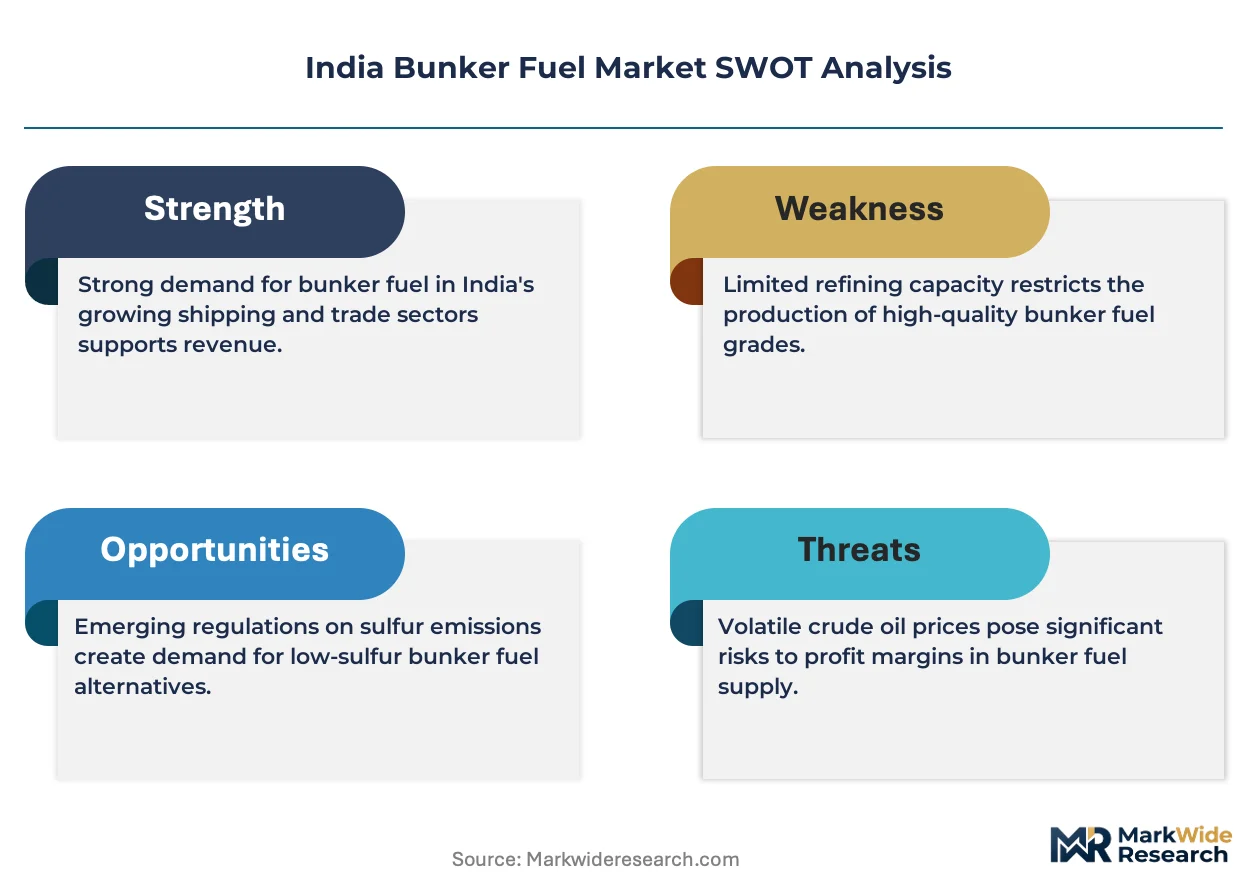
- Crude Oil Price Volatility:Residual fuel oil pricing tracks Dubai crude differentials, compressing blender margins when feedstock costs spike without corresponding bunker price recovery.
- Storage Infrastructure Concentration:Deepwater storage terminals cluster at Mundra, Hazira, and Mumbai, creating geographic supply bottlenecks for vessels calling eastern ports.
- LNG Bunkering Substitution:LNG-fueled newbuilds on order at Korean and Chinese yards threaten long-term residual fuel demand in coastal trades.
Strategic Opportunities
- Visakhapatnam Port Zone:Eastern India's underdeveloped bunkering infrastructure offers first-mover advantages for suppliers establishing floating storage and bunkering operations.
- Biofuel Blend Certification:The International Sustainability and Carbon Certification framework creates pathways for FAME and HVO marine blends at select Indian anchorages.
- Digital Bunker Delivery Notes:Blockchain-verified fuel quality documentation streamlines port state control inspections and reduces disputes over sulfur content verification.
Industry Challenges
- Marine Chemist Talent Scarcity:Laboratory testing facilities face shortages of technicians certified under BIS ISO 8217 fuel quality standards.
- Legacy Storage Tank Retrofitting:Converting high-sulfur fuel oil tanks to segregated low-sulfur product service requires significant capital outlay and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bunker Fuel Market |
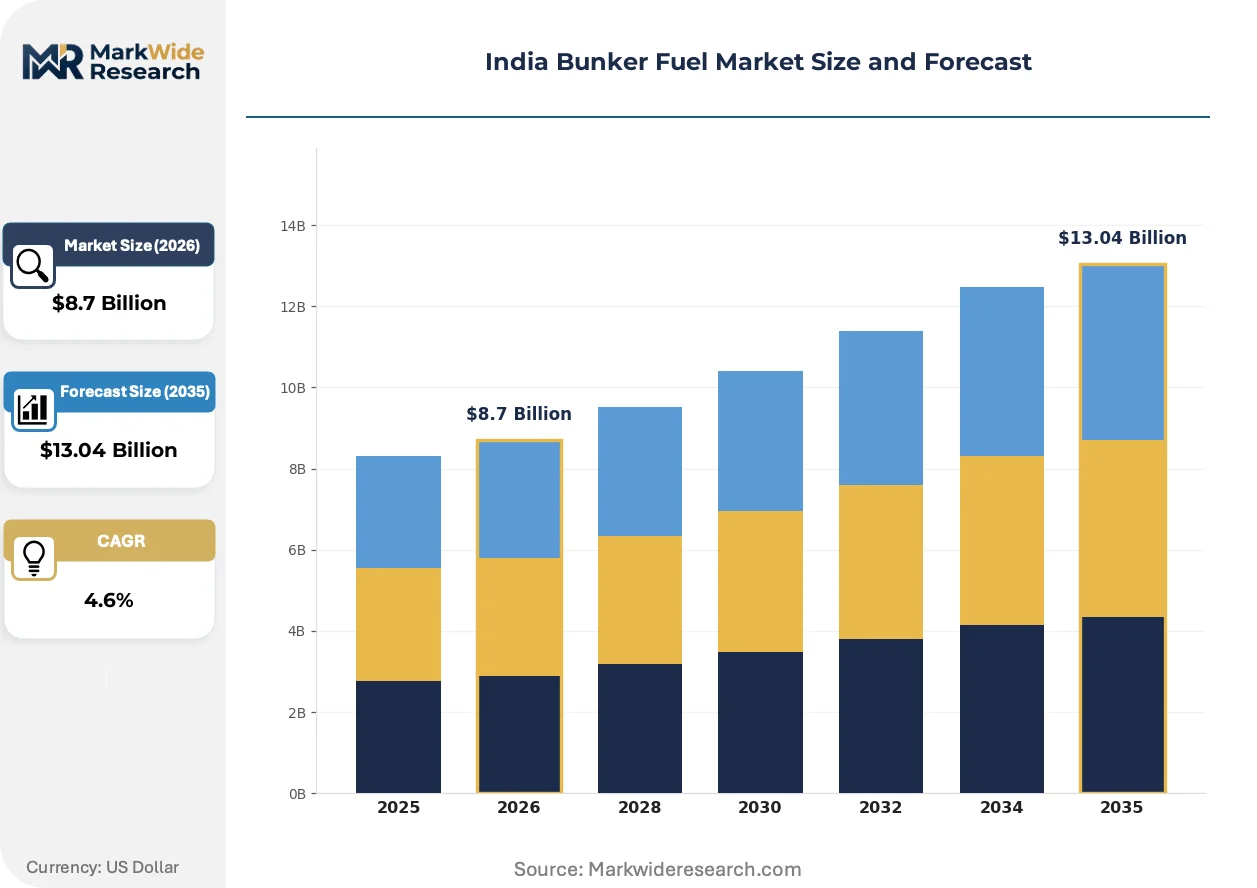
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: HSFO, LSFO, Marine Gas Oil, Biofuel End User: Shipping Industry, Offshore Vessels, Fishing Boats, Leisure Yachts Distribution Channel: Direct Supply, Bunker Barges, Retail Outlets, Resellers Application: Commercial Shipping, Cargo Transport, Oil Tankers, Cruise Ships |
| Companies Covered | Reliance Industries Limited, Mangalore Refinery and Petrochemicals Ltd, Indian Oil Corporation Limited, ExxonMobil India, Shell India, Bharat Petroleum Corporation Limited, Adani Bunkering Private Limited, TotalEnergies Marketing India Ltd., Hindustan Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bunker Fuel Market Shifts & Advancements
Marine fuel supply chains in India are digitizing quality assurance and delivery verification. Refiners, port authorities, and vessel operators are deploying sensor networks and distributed ledger systems to compress transaction friction and sulfur compliance verification timelines.
Very low sulfur fuel oil is consolidating as the dominant marine fuel grade at Indian ports. Container shipping lines operating through Mundra and JNPT have locked in annual procurement contracts for 0.50% m/m product. This technology shift is compressing demand for high-sulfur residual fuel oil and forcing independent storage terminals into product tank reconfiguration.
The Central Pollution Control Board's coastal air quality monitoring program is tightening de facto vessel fuel specifications at Indian harbors. Port state control inspections now cross-reference fuel delivery notes against continuous emissions monitoring data. Bulk carrier segments calling Paradip and Visakhapatnam are responding by pre-positioning compliant bunkers ahead of coastal transit.
Container lines are unbundling fuel procurement from vessel chartering agreements. Major operators now contract directly with integrated refiners for delivered bunkers, displacing traditional bunker traders at Mumbai and Chennai anchorages. This behavioral shift is most visible among Asia-Europe strings where fuel cost transparency has become a competitive procurement priority.
India Bunker Fuel Market Segmentation
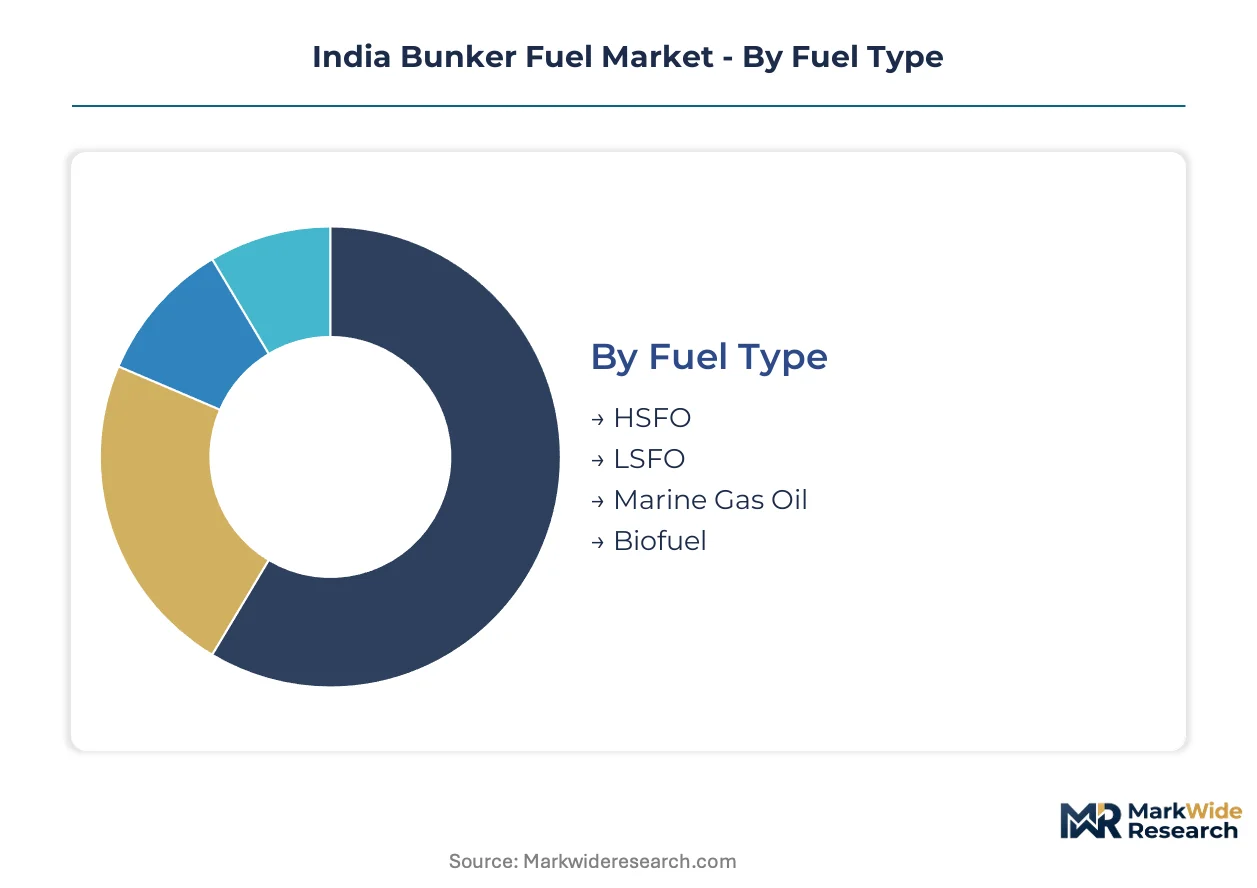
India's bunker fuel segmentation reveals how refinery configuration, port infrastructure, and vessel compliance requirements fragment procurement patterns across the maritime supply chain. Understanding these divisions exposes where integrated suppliers capture margin and where independent operators face displacement.
Fuel Type:
Supply concentration along Gujarat's refining corridor directly shapes which fuel grades dominate Indian port inventories and which remain import-dependent.
- HSFO:High-sulfur fuel oil retains residual demand among vessels equipped with scrubber systems, particularly bulk carriers operating on long-haul routes where capital recovery justifies exhaust gas cleaning installation. Demand clusters at Mundra Port where scrubber-fitted Capesize vessels bunker before Australia-India iron ore runs.
- LSFO:Low-sulfur fuel oil commands the largest volume share as the default compliance fuel for the majority of India's container fleet calling JNPT and Chennai. Refiners at Jamnagar and Vadinar have reconfigured coker output to prioritize this grade, creating domestic supply security that displaces previous Singapore-sourced volumes.
- Marine Gas Oil:Distillate marine fuel serves cruise ships and offshore support vessels requiring operational flexibility and rapid load-following capability; supply depends on coastal storage terminals with segregated distillate tanks.
- Biofuel:Fatty acid methyl ester and hydrotreated vegetable oil blends occupy trial volumes at select anchorages, constrained by ISCC certification complexity and limited domestic feedstock aggregation infrastructure.
Today's leader: LSFO. Tomorrow's challenger: Biofuel.
End User:
Cost tier differentiation separates vessel operators by fuel procurement sophistication and contract scale.
- Shipping Industry:Deep-sea container lines and bulk operators negotiate annual offtake agreements with integrated refiners, locking in delivered bunker prices at major Indian anchorages. These contracts now specify 0.50% m/m sulfur maximum with BIS ISO 8217 quality certification.
- Offshore Vessels:Platform supply vessels and anchor handlers operating from Mumbai High and KG-D6 fields require marine gas oil for engine responsiveness during dynamic positioning operations. Procurement concentrates through Oil and Natural Gas Corporation tender processes.
- Fishing Boats:Artisanal and mechanized fishing fleets along Tamil Nadu and Gujarat coasts source residual fuel through informal reseller networks with limited quality verification.
- Leisure Yachts:Marina-based recreational vessels at Mumbai, Goa, and Kochi represent minimal volume but pay premium pricing for certified distillate delivered in small parcels.
Volume concentrates with shipping lines. Margin concentrates with offshore operators.
Distribution Channel:
Application-specific delivery requirements determine which channel configuration serves each vessel type.
- Direct Supply:Integrated refiners deliver ex-pipe or via company-operated coastal tankers to container lines with dedicated berth agreements at Mundra and Hazira, eliminating intermediary margins.
- Bunker Barges:Floating delivery vessels serve vessels at anchorage across JNPT, Chennai, and Visakhapatnam, with barge fleet ownership concentrating among port-affiliated logistics operators.
- Retail Outlets:Coastal fuel stations at fishing harbors and minor ports dispense small-batch residual fuel to local vessel operators.
- Resellers:Independent traders aggregate volumes for spot procurement by tramp shipping and minor coastal operators, facing margin compression as direct supply expands.
Direct supply gains share fastest. Reseller margins face sustained compression.
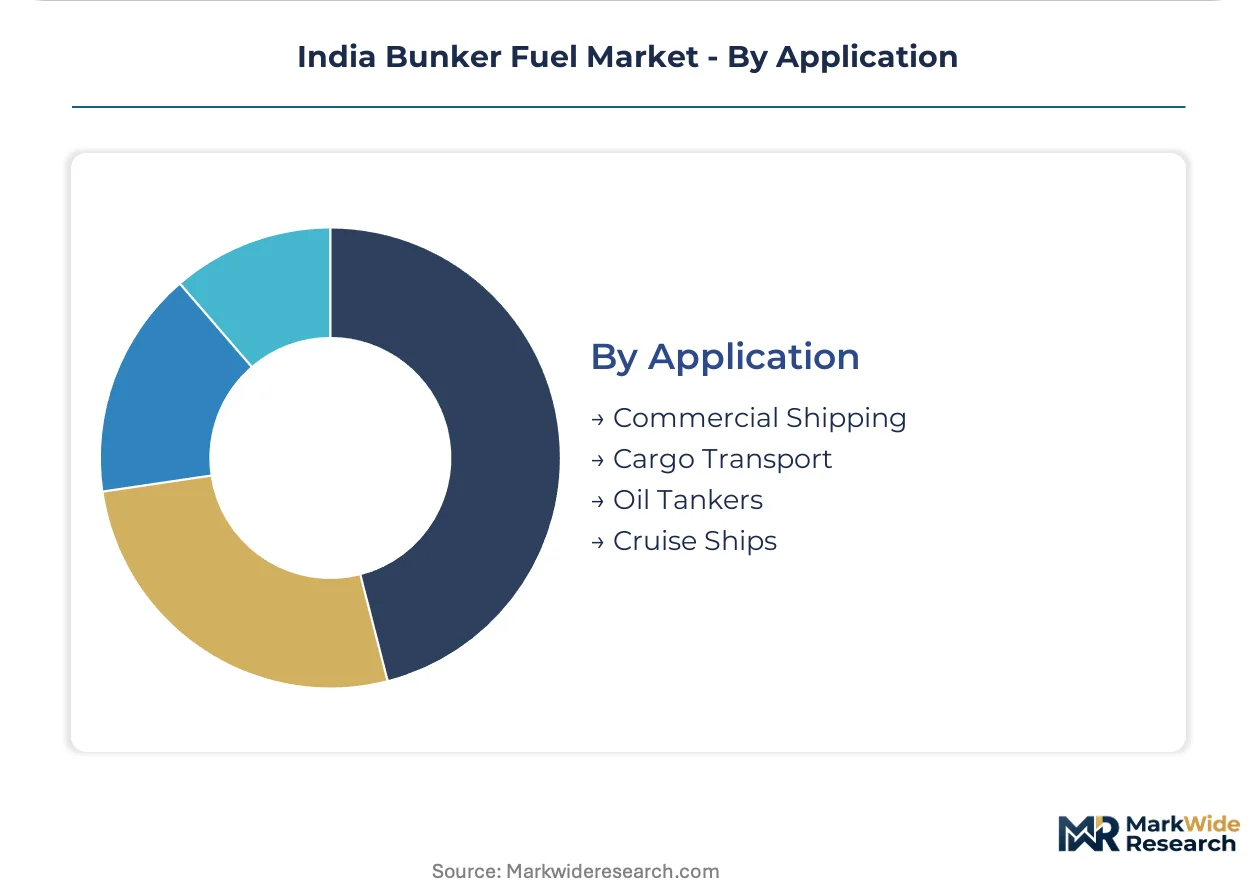
Application:
Customer type and voyage pattern dictate fuel grade selection and procurement contract structure.
- Commercial Shipping:Container lines and general cargo operators dominate bunker offtake, with procurement centralized through Singapore trading desks that source Indian-delivered volumes.
- Cargo Transport:Dry bulk and breakbulk vessels exhibit spot procurement patterns, purchasing bunkers based on port rotation optimization rather than annual contracts.
- Oil Tankers:Crude and product tankers calling Paradip and Vadinar often lift partial bunkers during cargo operations, requiring synchronized delivery scheduling.
- Cruise Ships:Seasonal cruise calls at Mumbai and Mangalore generate concentrated demand for low-sulfur distillate with strict quality documentation for flag-state compliance.
Commercial shipping anchors volume. Cruise ships anchor quality premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refiners in India exploit a cost-of-compliance arbitrage against Singapore and Middle Eastern suppliers, capturing container line volumes as MARPOL enforcement tightens across South Asian anchorages. The Directorate General of Shipping's port state control inspections have compressed non-compliant fuel availability, redirecting procurement toward domestic suppliers with BIS-certified laboratory networks.
Gujarat
Jamnagar and Vadinar host India's densest refining cluster, where Reliance Industries and Nayara Energy operate coker units optimized for very low sulfur fuel oil output. The Gujarat Maritime Board enforces sulfur caps at Mundra and Hazira ports ahead of national deadlines. Kandla Special Economic Zone anchors integrated storage terminals serving scrubber-fitted bulk carriers on Australia-India iron ore routes.
Maharashtra
Jawaharlal Nehru Port Trust generates concentrated bunker demand from Asia-Europe container strings, with annual throughput growth forcing shipping lines into long-term procurement contracts. The Maharashtra Pollution Control Board coordinates with the Central Pollution Control Board on coastal air quality monitoring that tightens de facto fuel specifications. Mumbai High offshore fields sustain marine gas oil demand from platform supply vessels operating under Oil and Natural Gas Corporation tender processes.
Tamil Nadu
Chennai Port anchors southern India's largest container gateway, with Ennore and Kamarajar ports adding deepwater berthing capacity for post-Panamax vessels. The Tamil Nadu Pollution Control Board implements harbor emission standards that exceed federal MARPOL baselines. Manali and Ennore industrial corridors concentrate coastal storage terminals with segregated low-sulfur product tanks.
Andhra Pradesh
Visakhapatnam Port offers underdeveloped bunkering infrastructure with first-mover potential for floating storage and bunkering operations. The Andhra Pradesh Maritime Board promotes port modernization through public-private partnerships targeting emission control area readiness. Gangavaram Port's deepwater draft advantages attract Capesize bulk carriers requiring compliant bunkers before coastal transit.
Karnataka
New Mangalore Port serves crude oil imports and refined product exports, with limited but growing bunker call volumes from coastal shipping. The Karnataka State Pollution Control Board enforces harbor air quality standards aligned with Central Pollution Control Board directives. Mangalore Refinery and Petrochemicals Ltd maintains coastal storage capacity that could expand into dedicated marine fuel service.
India Bunker Fuel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated refiners commanding container line contracts while independent resellers serve spot tramp markets. The market structures around three tiers: national oil companies with coastal storage networks, private refiners with residue upgrading capability, and international traders with floating inventory. Strategic moves concentrate on backward integration into captive storage terminals and product tank segregation for low-sulfur fuel oil service.
Within the integrated refiner tier, Reliance Industries Limited and Indian Oil Corporation Limited anchor domestic supply security through Jamnagar and coastal terminal networks respectively. Shell India occupies a position among international marketers competing on marine lubricant bundling and digital delivery verification at Mumbai and Chennai anchorages.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| Mangalore Refinery and Petrochemicals Ltd |
| Indian Oil Corporation Limited |
| ExxonMobil India |
| Shell India |
| Bharat Petroleum Corporation Limited |
| Adani Bunkering Private Limited |
| TotalEnergies Marketing India Ltd. |
| Hindustan Petroleum Corporation Limited |
| Others |
Supply & Pricing Matrix
Container shipping lines operating Asia-Europe strings through Jawaharlal Nehru Port Trust and Mundra Port anchor pricing power for integrated refiners, locking in annual offtake contracts that displace spot-market intermediaries and compress reseller margins across Indian anchorages.
Pricing Analysis
Direct supply contracts between integrated refiners and container lines eliminate distributor margins entirely, while independent resellers face spot-price volatility without volume guarantees. Price differentiation hinges on BIS ISO 8217 certification tier and sulfur content grade, with 0.10% m/m product commanding premiums over 0.50% m/m baseline. Cost compression in the reseller tier is intensifying because Reliance Industries and Indian Oil Corporation Limited are backward integrating into captive coastal storage terminals. Bulk carriers and tramp shipping operators exhibit highest price sensitivity due to irregular voyage patterns, whereas cruise lines and offshore support vessels prioritize quality documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Gujarat's refining corridor, where Jamnagar and Vadinar facilities process over half of India's marine fuel output. Geographic supply concentration centers on India, Singapore, and the United Arab Emirates as residual fuel oil sources, with feedstock drawn from Middle Eastern crude streams. Raw material dependencies rest on Dubai crude differentials, vacuum gas oil feedstocks, and hydrogen supply for hydrocracker units. Tariff exposure on imported blending components creates structural risk for eastern port suppliers lacking integrated refining capacity. Distribution runs through company-operated coastal tankers, port-affiliated bunker barges, and floating storage units at Mundra, Hazira, and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's bunker fuel market reads as a late-cycle quality story as MARPOL Annex VI enforcement and Central Pollution Control Board coastal air quality monitoring shift procurement toward certified low-sulfur products with full laboratory documentation.
For Market Incumbents: Acquire floating storage and bunkering vessels to establish eastern India presence ahead of Visakhapatnam port modernization. Integrated refiners must retrofit legacy high-sulfur fuel oil tanks to segregated low-sulfur service, defending against LNG-fueled newbuild substitution threats through marine lubricant bundling and digital bunker delivery verification. For New Entrants and Emerging Players: Blockchain-verified fuel quality documentation offers technology-first entry into dispute-heavy spot procurement segments. White-space targets include Visakhapatnam Port Zone floating storage operations and biofuel blend certification under ISCC frameworks for trial volumes at select anchorages. Partner with port-affiliated logistics operators rather than competing on barge fleet ownership. For Investors and Strategic Acquirers: National oil companies with coastal storage networks are the most active acquirer in this space, consolidating independent terminal operators to secure berth agreements. Long-term viability hinges on hydrogen and ammonia bunkering infrastructure positioning at Deendayal and Visakhapatnam. Monitor Directorate General of Shipping green fuel roadmap announcements as inflection indicator for capital reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Tank Retrofitting | Segregated low-sulfur product service enables BIS certification compliance at JNPT and Mundra berths. |
| Floating Storage Deployment | Visakhapatnam deepwater draft advantages attract Capesize vessels requiring compliant bunkers. |
| Digital Delivery Verification | Blockchain-verified bunker delivery notes streamline port state control inspections at Chennai anchorages. |
| Biofuel Blend Certification | ISCC framework pathways unlock FAME and HVO marine blend margins at select Indian ports. |
| Marine Lubricant Bundling | Differentiated service packages defend integrated refiner share against independent reseller price competition. |
Research Methodology
Multiple input streams — primary interviews with refinery operations managers, bunker procurement executives at container lines, port state control inspectors, and coastal storage terminal operators, plus secondary validation through Directorate General of Shipping enforcement records, Central Pollution Control Board air quality monitoring data, BIS certification registries, and customs trade statistics — were reconciled through bottom-up volume triangulation against top-down refinery output assessments.
Historical throughput patterns at Jawaharlal Nehru Port Trust, Mundra Port, and Visakhapatnam Port were cross-referenced against panel input from shipping line fuel procurement desks to model demand trajectories across the projection horizon. Segmentation dimensions included fuel type tier, end-user vessel category, distribution channel configuration, and regional port cluster. CAGRs were derived from iterative reconciliation of refinery capacity expansion timelines, MARPOL compliance deadline impacts, and LNG substitution elasticity assumptions in coastal trades.
The model holds under sustained MARPOL Annex VI enforcement and stable crude price differentials; deviation in green hydrogen bunkering subsidy announcements or scrubber retrofit acceleration would shift volume projections. Forecasts reflect documented assumptions regarding coker unit upgrade completion schedules and emission control area expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
China Bunker Fuel Market
Fuels
Europe Coal Market
Fuels
Gasoline Octane Improvers Market
Fuels
Brazil Bunker Fuel Market
Fuels
Collapsible Fuel Tank Market
Fuels
Smart Gas Solutions Market
Fuels
Liquefied Helium Tanks Market
Fuels
Coal Liquefaction Market
Fuels
Europe Gas Market
Fuels
Gasoline Market
Fuels
India Retail Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Europe Wood Pellet Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market