

Renewable Heating Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Heating Fuels Market Insights
European biogas upgrading capacity is broadening as agricultural and municipal waste streams convert to grid-quality biomethane. Neste leverages its Singapore and Rotterdam refining complexes to sustain global supply chains for renewable diesel used in heating applications. Drax anchors biomass procurement through its Yorkshire power station and pellet production facilities across the US Southeast. Enviva competes in industrial wood pellet supply, controlling export terminals that link North American fiber to European boiler operators.
Renewable heating fuels encompass processed organic materials and synthetic gases engineered to displace fossil-derived thermal energy in stationary combustion systems, with specifications typically requiring sub-20% moisture content for solid fuels and minimum 96% methane purity for grid-injected biogas. Their primary commercial purpose centers on delivering controllable, dispatchable heat to buildings and industrial processes where electrification faces technical or economic barriers. Biodiesel and wood pellets currently dominate volume flows, reflecting mature supply chains and established burner compatibility, while hydrogen and biogas represent faster-expanding categories where margin pools concentrate around upgrading, distribution, and blending infrastructure. District heating applications command premium positioning due to long-term offtake contracts and centralized procurement scale, whereas residential heating remains fragmented across individual consumer decision points.
The EU Green Deal and F-Gas Regulation shape product standards by mandating progressive carbon intensity reductions in heating fuels and restricting high-global-warming-potential alternatives, while national regulators such as Germany's BAFA administer switching subsidies that directly influence demand timing. The US EPA Renewable Fuel Standard and state-level low-carbon fuel programs create parallel compliance markets that pull imported biofuels toward specific regional hubs. Stakeholders must monitor evolving certification schemes for biomass sustainability and hydrogen origin guarantees, as these standards will increasingly determine market access and premium capture across both European and North American buyer pools.
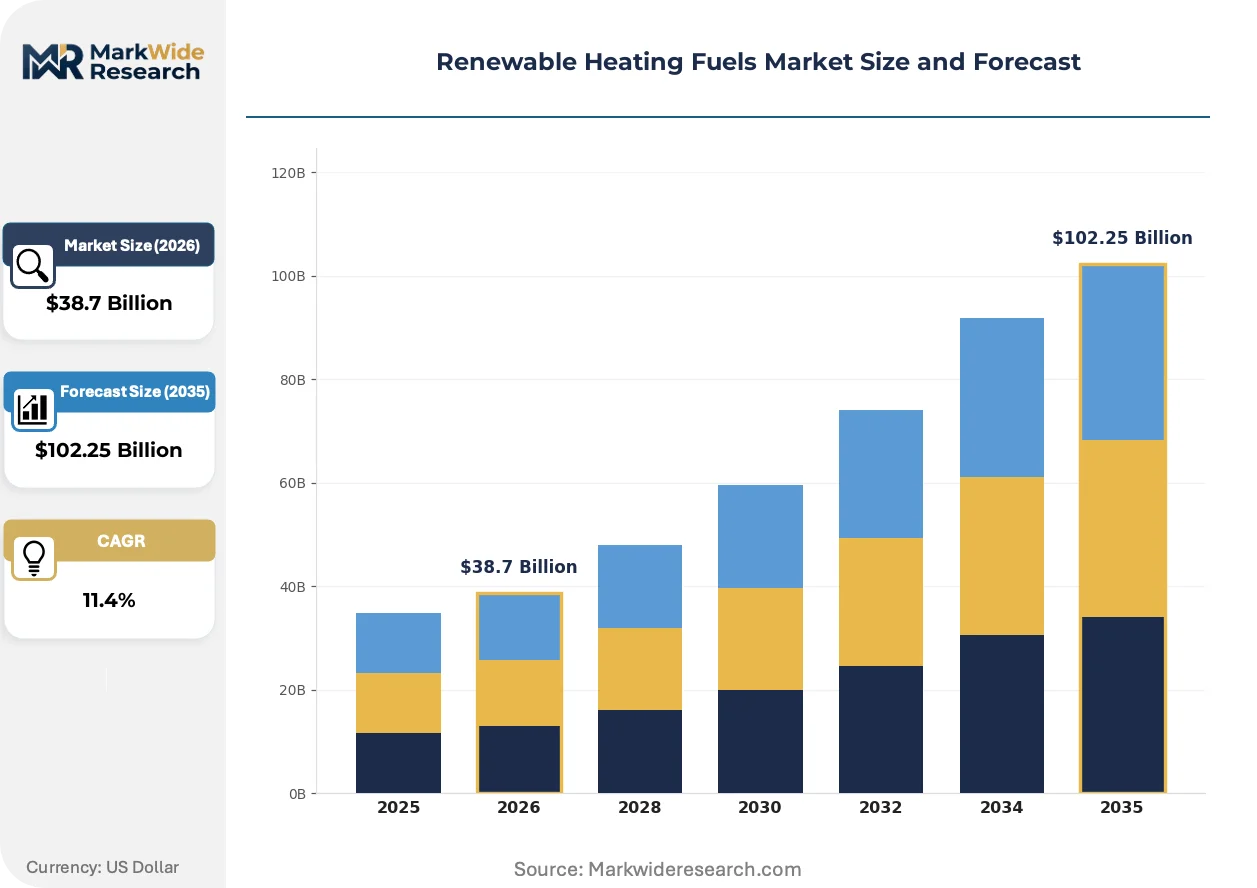
Market Dynamics
District heating procurement in Northern Europe is consolidating around biogas and biomass baseload contracts, compressing spot-market liquidity while locking in decade-long offtake structures that reshape supplier pricing power and capital allocation across the value chain.
Growth Catalysts
- EU Green Deal building mandates:Germany's BAFA switching subsidies and parallel national programs in Sweden and Finland accelerate fuel-switching timelines across residential and commercial building stock, pulling forward replacement cycles for oil and gas boilers.
- Biogas upgrading infrastructure:Agricultural and municipal waste stream conversion to grid-quality biomethane is expanding pipeline-injection capacity, enabling district heating operators to displace natural gas without burner hardware modifications.
- Industrial process heat electrification barriers:Cement, steel, and chemical sectors in high-latitude manufacturing clusters face technical and economic limits to direct electrification, sustaining premium demand for drop-in renewable thermal fuels.
Market Restraints
- Wood pellet supply concentration:North American fiber and export terminal capacity dominates seaborne trade flows, exposing European buyers to trans-Atlantic logistics disruptions and currency exposure.
- Biogas feedstock competition:Agricultural residues face alternative demand from soil amendment and animal bedding markets, constraining waste-to-energy conversion economics during harvest volatility.
- Grid injection technical standards:Minimum 96% methane purity requirements and odorization specifications create upgrading capex barriers for small-scale anaerobic digestion projects.
Strategic Opportunities
- Power-to-X synthetic methane:Electrolysis-derived hydrogen methanation offers pathway to carbon-negative heating fuels when paired with biogenic CO2 capture, attracting utility-scale investment in Denmark and the Netherlands.
- Industrial cluster hydrogen blending:Steel and chemical complexes in Germany's Ruhr region pilot hydrogen admixture in existing natural gas networks, creating anchor demand for renewable hydrogen heating applications.
- Building performance certificate linkage:France's RE2020 regulation and equivalent national schemes tie mortgage availability and property valuations to heating carbon intensity, embedding fuel-switching into real estate transactions.
Industry Challenges
- Biomass sustainability certification complexity:Divergent RED II, SBP, and FSC chain-of-custody requirements create compliance overhead for pellet producers serving multiple European buyer pools with distinct documentation demands.
- Legacy building stock retrofit coordination:Residential fuel-switching requires synchronized boiler replacement, insulation upgrades, and fuel supply contract negotiations across fragmented homeowner decision-making timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Heating Fuels Market Trends and Innovations
Technology maturation and regulatory stringency are compressing the viable technology set for renewable heating, favoring solutions with proven supply chains and certified carbon accounting over experimental alternatives still seeking scale.
Biomethane upgrading via membrane separation and pressure-swing adsorption is consolidating as the dominant biogas purification pathway for grid injection, with district heating operators in Denmark and Sweden standardizing procurement specifications around these technologies to minimize operational variability across supplier portfolios.
REACH and the F-Gas Regulation are tightening permissible fluorinated greenhouse gas content in heating system working fluids, forcing heat pump and hybrid system manufacturers to accelerate hydrocarbon and CO2 refrigerant transitions while retrofitting existing installed bases faces compliance deadlines.
Long-term heat supply contracting is displacing spot procurement for municipal and industrial buyers, with ten-to-fifteen-year indexed agreements now standard for district heating utilities in Finland and Germany seeking to underwrite upstream biogas digester and biomass pellet production investments.
Renewable Heating Fuels Market Segmentation
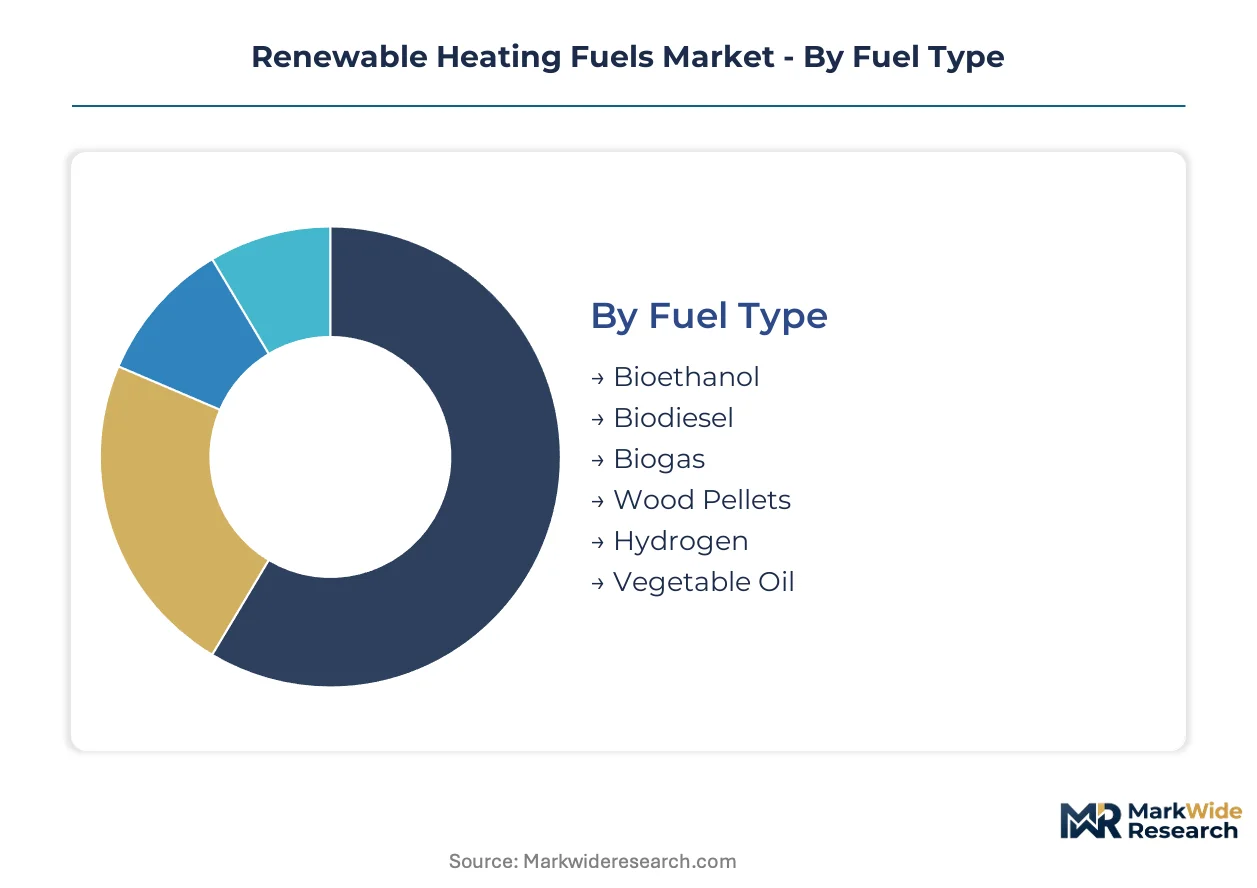
Segmentation in renewable heating fuels reveals where capital deployment concentrates and where technical barriers persist. Fuel chemistry, combustion technology, and end-use thermal requirements create distinct margin pools that suppliers must navigate separately.
Fuel Type:
Standalone drop-in fuels command premium positioning through burner compatibility, while embedded fuel systems require infrastructure co-investment.
- Biodiesel:Fatty acid methyl ester formulations achieve sub-15°C cold-flow properties through winterization, enabling year-round boiler operation in Northern European climates. German district heating operators in Hamburg and Munich anchor procurement volumes through decade-long offtake contracts indexed to fossil diesel spreads.
- Biogas:Grid-quality biomethane requires pressure-swing adsorption upgrading to 96%+ methane purity for pipeline injection. Danish agricultural cooperatives and Swedish municipal waste utilities concentrate production capacity around district heating feed-in tariffs.
- Bioethanol:Hydrous and anhydrous grades serve industrial process heat applications with established Brazilian and US Midwest supply chains.
- Wood Pellets:ENplus-A1 certified material with sub-10% moisture content dominates residential and small commercial boiler markets.
- Hydrogen:Electrolysis-derived and steam-methane-reforming with carbon capture supply pilot blending programs in industrial clusters.
- Vegetable Oil:Straight-use oils and processed esters serve niche agricultural and marine heating segments with limited burner modification requirements.
Volume placements concentrate in biodiesel and wood pellets; the faster expansion belongs to biogas and hydrogen.
Application:
Cost tier separation divides centralized infrastructure plays from fragmented consumer-facing deployments.
- District Heating:Municipal and cooperative-owned networks in Finland, Denmark, and Germany aggregate thermal demand across thousands of buildings, enabling baseload renewable fuel procurement at utility scale. Long-term indexed contracts with 10-15 year tenors lock in supplier margins while insulating operators from spot price volatility.
- Industrial Furnaces:Cement, steel, and chemical process heat requirements exceed 1000°C in many applications, constraining electrification and sustaining premium demand for drop-in liquid and gaseous renewable fuels. German Ruhr region steel complexes and Dutch Rotterdam chemical clusters pilot hydrogen admixture at 20-30% rates.
- Residential Heating:Individual boiler replacement cycles and fragmented fuel supply contract negotiations create customer acquisition cost challenges for renewable fuel marketers.
- Commercial Boilers:Hotels, hospitals, and office buildings in urban centers face building performance certificate mandates driving fuel-switching decisions.
- Agriculture Drying:Seasonal demand patterns and remote locations favor locally sourced solid biomass over transported liquid fuels.
- Marine Heating:IMO 2020 sulfur regulations and port-specific low-emission zones pull renewable diesel into coastal vessel auxiliary heating systems.
Revenue concentration sits with district heating and industrial furnaces; residential heating offers volume potential but margin compression.
Technology:
Maturity gradients separate proven combustion pathways from emerging conversion systems still seeking operational scale.
- Combustion:Grate firing, fluidized bed, and suspension burning of solid biomass and liquid biofuels represent the dominant thermal conversion pathway with decades of operational history. Stoker boilers and pellet burners achieve 85-92% efficiency in modern installations across Swedish and Austrian building stock.
- Anaerobic Digestion:Wet and dry fermentation of agricultural residues, food waste, and sewage sludge produces biogas for direct thermal use or upgrading to biomethane. German agricultural biogas capacity exceeds other European markets through EEG feed-in tariff legacy structures.
- Gasification:Partial oxidation of biomass to syngas enables higher-efficiency power and heat generation but faces tar cracking and feedstock preparation cost challenges.
- Pyrolysis:Fast and slow pyrolysis pathways produce bio-oil and biochar with applications in industrial heat and soil amendment markets.
- Fuel Cells:Solid oxide and molten carbonate systems enable combined heat and power from biogas with electrical efficiencies above 50%, limited by capital cost and stack durability.
- Heat Pumps:Air-source and ground-source electric systems compete indirectly with renewable heating fuels in building applications, with performance coefficients determining cross-fuel economics.
Deployment scale favors combustion and anaerobic digestion; fuel cells and advanced thermochemical conversion claim the steepest expansion trajectory.
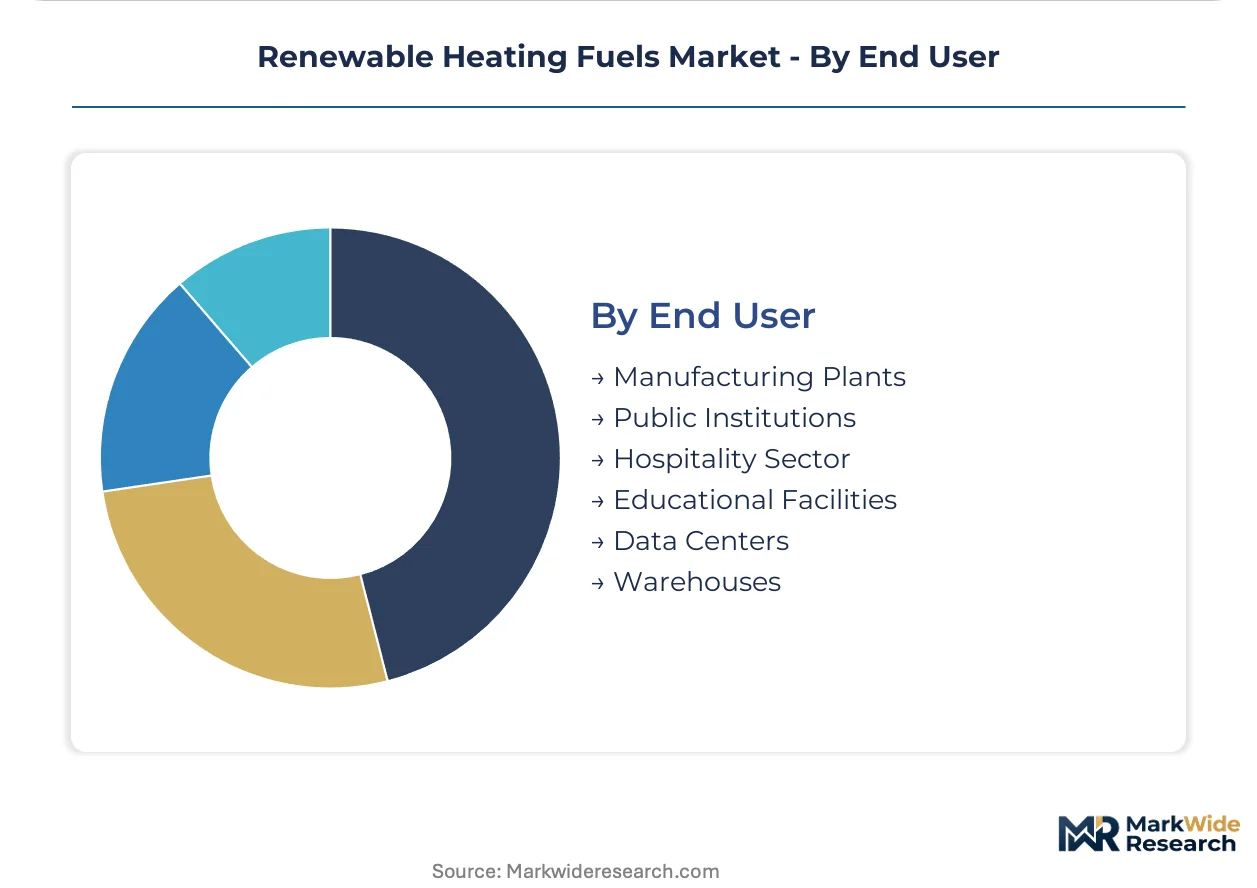
End User:
Customer type fragmentation creates distinct procurement behaviors across public and private balance sheets.
- Manufacturing Plants:Process heat requirements in paper, food processing, and textiles drive continuous baseload demand for renewable thermal fuels. Finnish pulp and paper mills integrate biomass boilers into chemical recovery cycles.
- Public Institutions:Municipal buildings, hospitals, and government facilities face mandated carbon reduction targets with public procurement transparency requirements.
- Hospitality Sector:Hotels and restaurants prioritize operational reliability and space constraints over fuel cost minimization.
- Educational Facilities:Universities and school districts combine renewable heating with sustainability curriculum visibility.
- Data Centers:Waste heat recovery potential and corporate renewable energy commitments drive fuel choice in Nordic and German facilities.
- Warehouses:Large-footprint distribution centers favor district heating connection where available, standalone biomass boilers where grid access is limited.
Contract value concentrates with manufacturing plants and public institutions; data centers represent the fastest-growing customer acquisition target.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forest residues from the US Southeast and agricultural waste streams across Northern European plains anchor feedstock availability for pellet and biogas production respectively. These raw-material geographies shape where upgrading infrastructure and district heating procurement concentrate.
Germany
District heating networks in Hamburg and Munich drive biogas procurement through decade-long offtake contracts indexed to natural gas spreads. BAFA switching subsidies accelerate residential boiler replacements under the Building Energy Act. The Ruhr industrial cluster pilots hydrogen blending in steel and chemical process heat applications.
Sweden
Municipal waste utilities and agricultural cooperatives concentrate biomethane production capacity around Stockholm and Gothenburg district heating feed-in tariffs. The Swedish Energy Agency mandates carbon-neutral heating for public buildings by 2030. Växjö anchors biomass combustion technology deployment across pulp and paper mill integration.
Finland
Pulp and paper mills in the Lakeland region integrate biomass boilers into chemical recovery cycles, sustaining baseload demand for wood chips and pellets. The Ministry of Economic Affairs and Employment administers heat pump and biomass switching grants for detached housing. Helsinki district heating commits to coal phase-out through biomass and waste heat substitution.
United States
Export terminal capacity in Virginia and Louisiana links Southeast fiber supplies to European boiler operators through long-term supply agreements. The EPA Renewable Fuel Standard and state-level low-carbon fuel programs in California and Oregon create compliance demand pull. Industrial pellet production concentrates in Mississippi and Alabama to serve trans-Atlantic logistics.
Denmark
Agricultural cooperatives in Jutland expand anaerobic digestion capacity to supply grid-quality biomethane for Copenhagen district heating networks. The Danish Energy Agency supports power-to-X synthetic methane pilots pairing electrolysis with biogenic CO2 capture. Aalborg anchors industrial process heat demand from cement and pharmaceutical manufacturing clusters.
Renewable Heating Fuels Market Competitive Landscape
Global majors compete with regional champions across fuel upgrading and distribution infrastructure, creating a tiered structure where capital scale separates integrated energy companies from specialized biomass and biogas operators. The vendor base spans petroleum majors diversifying into renewable diesel, dedicated pellet producers controlling fiber supply, and utility-backed biogas developers securing long-term district heating contracts. Three archetypes dominate: integrated energy conglomerates with refining assets, pure-play biomass suppliers with captive fiber, and agricultural cooperative-backed biogas developers. Competitive moves center on backward integration into feedstock supply and ten-to-fifteen-year indexed offtake contracting with municipal utilities.
Within the integrated energy tier, Nestle and TotalEnergies exemplify petroleum-major diversification into renewable diesel and sustainable aviation fuel streams that cross-feed heating applications. Among dedicated biomass operators, Enviva and Drax occupy positions linking North American fiber procurement to European utility procurement desks. Fortum and Ørsted represent utility-backed developers leveraging district heating network ownership to underwrite upstream biogas digester investments.
| Leading Market Players |
|---|
| Neste |
| Enviva |
| Drax |
| TotalEnergies |
| Shell |
| Fortum |
| Ørsted |
| Enel |
| Engie |
| Others |
Pricing and Supply Chain Analysis
Specialized biogas upgrading technicians in Denmark and the Netherlands command wage premiums that compress margin spreads between economy-grade agricultural digesters and premium utility-scale biomethane facilities. Labor-cost differentials across the upgrading technology stack widen pricing-tier spreads as district heating operators in Hamburg and Munich index long-term contracts to natural gas benchmarks while absorbing service-bundling premiums for guaranteed uptime.
Pricing Analysis
Extended warranty and burner-maintenance bundling separates premium biomethane supply contracts from unbundled spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ENplus-A1 certification grade and volume scale, with residential pellet buyers in Sweden showing highest price sensitivity. Cost compression in economy biodiesel tiers is intensifying because of trans-Atlantic logistics exposure. Industrial furnace operators in Germany's Ruhr region demonstrate lowest price sensitivity due to process-heat criticality.
Supply Chain Analysis
Dual-sourcing mandates from Finnish and German district heating utilities require pellet producers to qualify both Drax and Enviva supply streams simultaneously. Geographic supply concentration centers on the US Southeast for wood fiber, Denmark and Sweden for biogas upgrading capacity, and Germany for hydrogen blending infrastructure. Raw material dependencies rest on agricultural residues, forestry slash, and biogenic CO2 capture feedstocks. Single-source vulnerability persists in trans-Atlantic pellet shipping lanes. Distribution runs through long-term indexed offtake contracts rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The renewable heating fuels sector sits in a technology-transition phase where electrolysis-derived hydrogen is displacing legacy natural gas blending in German industrial clusters.
For Market Incumbents: Extend backward integration into North American fiber supply through captive pellet production capacity in Mississippi and Alabama to defend against Enviva and Drax supply concentration. Secure 15-year indexed biomethane offtake contracts with Copenhagen and Hamburg district heating operators before electrolysis-derived synthetic methane achieves cost parity.
For New Entrants and Emerging Players: Begin with agricultural cooperative partnerships in Jutland and Gothenburg hinterlands where feedstock aggregation infrastructure remains underdeveloped. Target small-scale anaerobic digestion projects serving remote Finnish Lakeland pulp mills. Pursue power-to-X synthetic methane pilots paired with existing biogas upgrading facilities to share grid-injection infrastructure.
For Investors and Strategic Acquirers: The window for entry favors utility-backed developers with district heating network ownership in Denmark and Sweden. Long-term viability hinges on securing feed-in tariff structures that outlast the current policy cycle. Watch for hydrogen blending rate increases above 30% in Ruhr steel complexes as the inflection signal for synthetic methane demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biogas Upgrading Capacity Expansion | Pressure-swing adsorption deployment in Denmark enables grid-injection scale for Copenhagen district heating. |
| Long-term Biomass Supply Agreement | Indexed offtake contracts with Hamburg utilities underwrite US Southeast pellet production investments. |
| Power-to-X Synthetic Methane Pilot | Electrolysis-methanation pairing with biogenic CO2 capture creates carbon-negative pathway for Netherlands heating. |
| Hydrogen Blending Infrastructure | 20-30% admixture pilots in Ruhr steel networks anchor demand for renewable hydrogen heating applications. |
| Backward Integration into Fiber Supply | Captive forestry slash procurement in Mississippi reduces trans-Atlantic logistics exposure for European buyers. |
Research Methodology
Multi-period observation of biogas upgrading capacity additions, district heating procurement contract tenors, and pellet export terminal utilization anchored the trend analysis, supplemented by interviews with utility planning officers, anaerobic digestion project developers, EPC contractors specializing in biomethane facilities, and fuel supply specialists at Nordic district heating cooperatives. Secondary validation drew from EIA biomass trade data, IEA renewable heat reports, FERC filings on industrial fuel switching, and EU Green Deal implementation tracking databases. Bottom-up project pipeline assessment triangulated against top-down macro demand modeling.
The input-output matrix framed supply-side capacity buildouts against demand-pull from BAFA subsidy cycles and building performance mandates. Segmentation dimensions modeled across the analysis window encompass fuel chemistry tier, application scale, combustion technology maturity, and end-use carbon intensity requirements. CAGRs were derived through regression-based trajectory fitting against historical switching subsidy disbursement patterns and industrial process heat electrification feasibility assessments.
Underlying measurement precision varies by segment; district heating procurement volumes carry tighter precision than fragmented residential pellet consumption. Forecasts reflect assumptions around EU Green Deal enforcement continuity and natural gas price correlation stability. Deviation in German hydrogen blending regulatory thresholds or trans-Atlantic shipping rate volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.