
 Gas Hydrates Market | 2026-2036
Gas Hydrates Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Hydrates Market Analysis
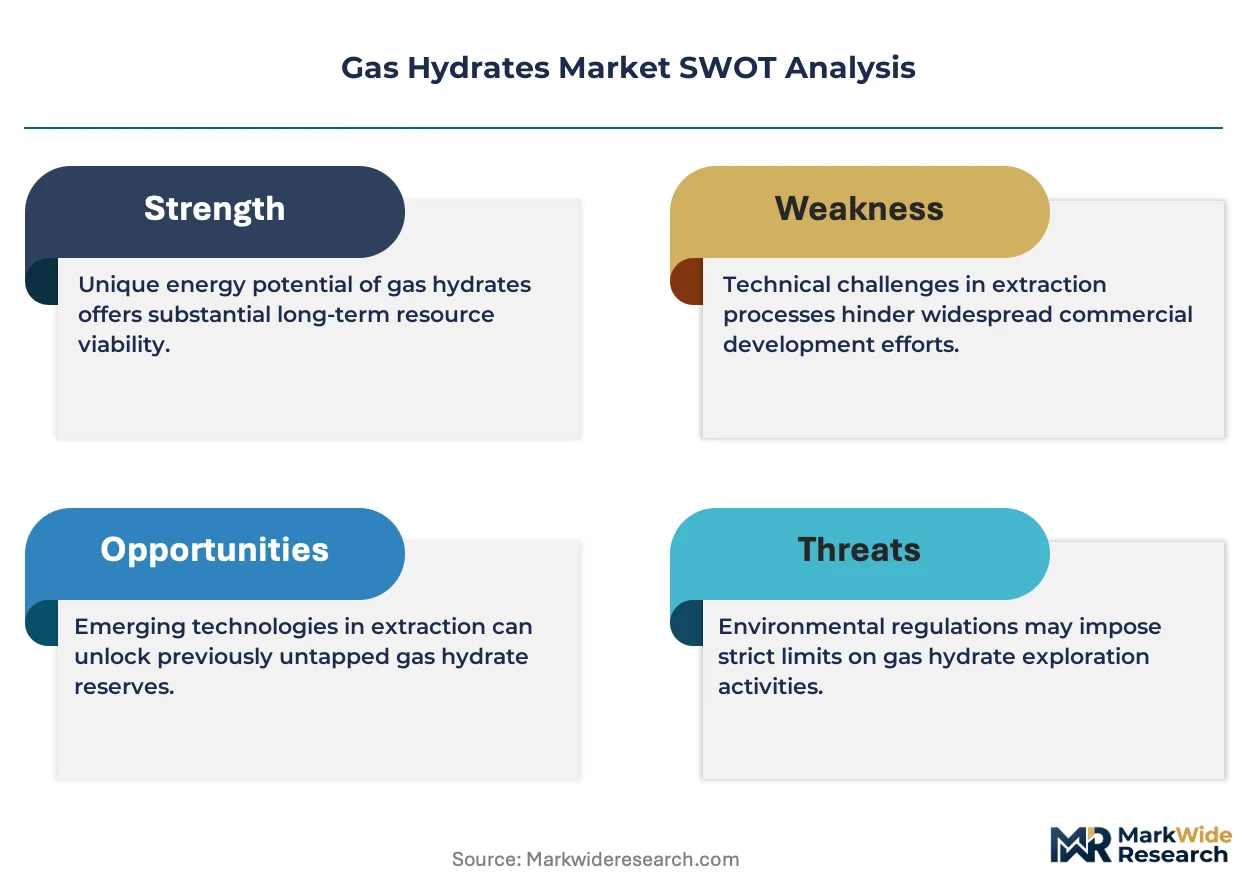
A shortage of deepwater drilling engineers with hydrate-specific expertise is unwinding project timelines across the sector. Schlumberger Limited leverages its reservoir characterization technology to anchor service contracts in frontier basins. Chevron Corporation competes through its Gulf of Mexico operational experience, while Japan Petroleum Exploration Company Limited dominates domestic hydrate research programs with government backing.
Gas hydrates are crystalline inclusion compounds where gas molecules become trapped within hydrogen-bonded water cages under high pressure and low temperature conditions, typically forming at water depths exceeding 500 meters or in permafrost zones. These structures function as both a potential unconventional hydrocarbon resource and a flow assurance challenge in conventional subsea pipelines. Natural gas hydrate deposits represent the leading resource category due to vast marine reservoir estimates, while carbon capture applications emerge as the fastest-growing segment as operators explore hydrate-based CO2 sequestration. Offshore deployment absorbs the majority of capital allocation, though laboratory research programs sustain innovation pipelines for extraction methodology.
The US Bureau of Ocean Energy Management and Japan's Agency for Natural Resources and Energy shape exploration permitting frameworks, while ISO standards govern offshore safety protocols for hydrate drilling operations. China's Ministry of Natural Resources regulates seabed mining claims through its State Oceanic Administration, creating overlapping jurisdictional complexity in the South China Sea. Stakeholders must monitor which regulatory regime achieves de facto standard-setting authority for commercial extraction licensing.
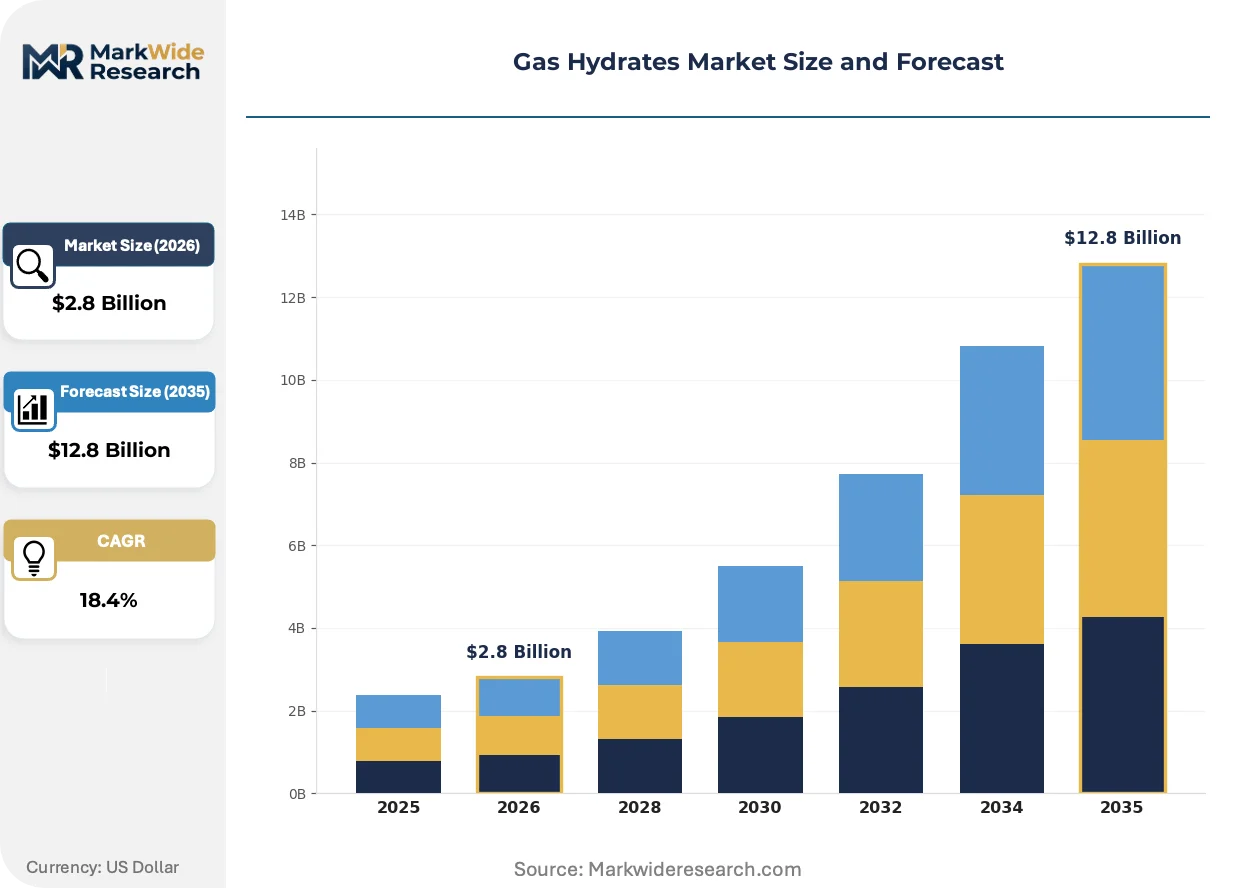
Market Dynamics
Deepwater extraction technology maturation is compressing the timeline between pilot-phase validation and commercial-scale deployment, forcing capital allocation decisions before reservoir economics fully clarify.
Growth Catalysts
- Japan's METI Funding Framework:Direct government subsidies for methane hydrate pilot projects de-risk exploration investments and accelerate seabed drilling permits in the Nankai Trough.
- Offshore Energy Security Mandates:South Korea's national energy diversification targets create guaranteed offtake channels for hydrate-derived natural gas imports.
- Depressurization Extraction Methods:Advances in controlled pressure reduction techniques unlock production from marine hydrate reservoirs previously classified as technically unrecoverable.
Market Restraints
- Deepwater Drilling Cost Structure:Ultra-deepwater rig day rates and specialized hydrate-resistant equipment impose capital intensity that marginalizes smaller exploration consortia.
- Permafrost Zone Access Concentration:Arctic hydrate deposits face concentrated ownership disputes between Russia, Canada, and the United States, freezing cross-border development agreements.
- Flow Assurance Substitution:Thermodynamic hydrate inhibitors and active heating systems in conventional subsea pipelines reduce near-term urgency for hydrate-specific extraction infrastructure.
Strategic Opportunities
- Carbon Capture Integration:CO2 hydrate sequestration in depleted marine reservoirs opens revenue streams from emissions trading schemes and industrial carbon offset procurement.
- China's Seabed Mining Claims:The South China Sea jurisdictional overlap creates first-mover advantage for operators securing extraction licenses before territorial arbitration concludes.
- Laboratory-to-Field Technology Transfer:Research consortium partnerships between national oil companies and university hydrate institutes compress commercialization cycles for new extraction methodologies.
Industry Challenges
- Reservoir Characterization Expertise Gap:The shortage of geoscientists trained in hydrate-specific petrophysical analysis delays resource quantification and production forecasting.
- ISO Safety Protocol Certification Timelines:Extended approval cycles for offshore hydrate drilling standards postpone operational commencement in frontier basins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Hydrates Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural Gas Hydrate, Synthetic Gas Hydrate, Clathrate Compounds, CO2 Hydrates Application: Energy Production, Gas Storage, Transportation, Carbon Capture End User: Oil & Gas, Energy Utilities, Research Institutions, Government Bodies Deployment: Onshore, Offshore, Subsea, Laboratory |
| Companies Covered | PetroChina Company Limited, Schlumberger Limited, Chevron Corporation, TotalEnergies SE, ConocoPhillips, ExxonMobil Corporation, Japan Petroleum Exploration Company Limited, Korea Gas Corporation (KOGAS), Shell Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Hydrates Market Emerging Trajectories
Extraction methodology convergence with carbon management objectives is redirecting R&D investment toward dual-purpose technologies that simultaneously unlock hydrocarbons and enable emissions sequestration.
Electromagnetic seabed surveying combined with advanced seismic imaging is displacing traditional well-logging approaches for hydrate deposit characterization. Japanese and South Korean national oil companies are deploying these integrated systems across the East China Sea at accelerated procurement cycles. The technology is displacing conventional reservoir mapping contracts and compressing exploration timelines by eliminating redundant drilling verification stages.
The EU F-Gas Regulation phase-down mandates for high-global-warming-potential substances are forcing subsea equipment manufacturers to redesign thermal management systems for hydrate prevention. Industrial consequence includes accelerated R&D budgets for CO2-based cooling alternatives in pipeline flow assurance applications. Arctic offshore operators in Norwegian and Greenlandic waters face the steepest compliance cost escalations and are pre-qualifying equipment vendors on fluorinated-gas-free technology roadmaps.
Integrated service contracting is consolidating discrete exploration, extraction, and carbon management procurement decisions into single-source vendor relationships. National oil companies in Japan and China are disintermediating traditional equipment rental brokers in favor of technology-integrated performance contracts. This consolidation is most visible in the Nankai Trough and South China Sea lease blocks where operators bundle reservoir characterization with carbon sequestration liability transfer.
Gas Hydrates Market Segmentation
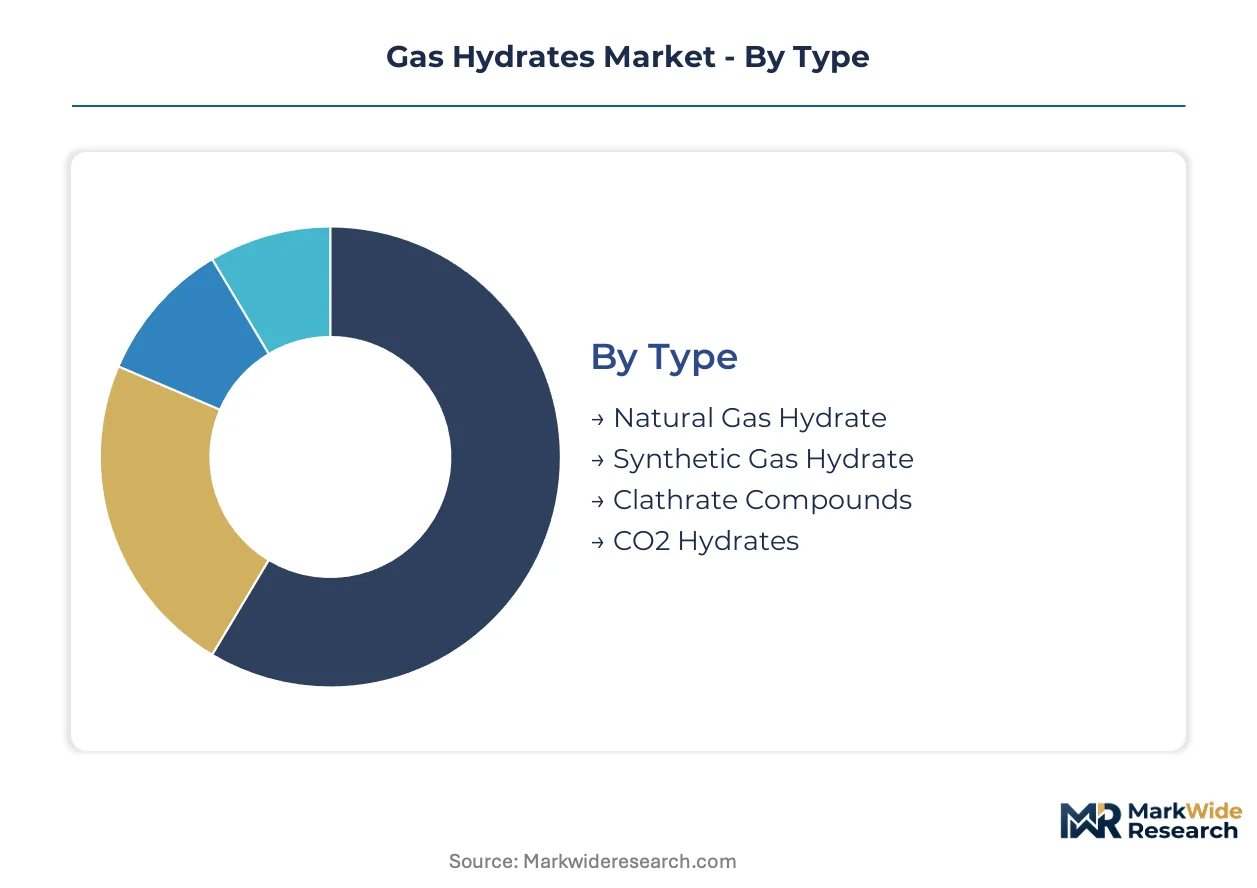
Gas hydrate commercialization pathways diverge sharply based on resource origin, extraction environment, and end-use economics. Segment boundaries determine capital intensity, regulatory exposure, and technology transfer requirements for operators entering this frontier market.
Type:
Domestic consumption concentrates in resource-endowed nations, while synthetic and sequestration-grade hydrates travel across borders for specialized industrial applications.
- Natural Gas Hydrate:Crystalline methane-water structures forming in marine sediments and permafrost zones under high-pressure, low-temperature conditions. Japan, China, and South Korea absorb the bulk of pilot-scale production from the Nankai Trough and South China Sea, driven by national energy security mandates that de-risk exploration investments through direct government subsidy.
- CO2 Hydrates:Carbon dioxide molecules trapped within water cages, enabling permanent seabed sequestration in depleted reservoirs. Industrial carbon offset procurement in the European Union and Japan accelerates demand for this segment as emissions trading schemes mature and operators seek dual-purpose extraction technologies.
- Synthetic Gas Hydrate:Laboratory-engineered hydrates produced for controlled research and small-scale gas storage applications.
- Clathrate Compounds:Specialized inclusion complexes with non-hydrocarbon guest molecules for niche industrial and research purposes.
Natural Gas Hydrate holds the largest share; momentum sits with CO2 Hydrates.
Application:
Application selection dictates whether operators pursue revenue from hydrocarbon sales, infrastructure services, or environmental credit generation.
- Energy Production:Controlled dissociation of methane hydrates for grid-connected natural gas supply. Japan Petroleum Exploration Company Limited and METI-funded consortia dominate this segment through depressurization extraction trials in domestic waters, though reservoir characterization expertise gaps delay commercial timelines.
- Carbon Capture:CO2 injection into hydrate-bearing formations for simultaneous sequestration and methane displacement. Offshore lease blocks in the South China Sea and East China Sea attract first-mover licensing activity as jurisdictional disputes remain unresolved, creating arbitrage opportunities for operators securing permits ahead of territorial arbitration.
- Gas Storage:Seasonal storage of conventional natural gas in synthetic hydrate form for peak demand management.
- Transportation:Solid-state gas transport via hydrate carriers for stranded gas monetization.
Energy Production commands current investment; Carbon Capture climbs the fastest as dual-purpose technologies mature.
End User:
Procurement authority separates state-backed strategic buyers from commercially motivated private operators.
- Oil & Gas:Integrated majors and national oil companies funding frontier basin exploration. Chevron Corporation leverages Gulf of Mexico deepwater experience to anchor service contracts, while Schlumberger Limited supplies reservoir characterization technology for hydrate-specific petrophysical analysis.
- Government Bodies:National energy ministries and seabed resource agencies directing subsidy flows and permitting frameworks. Japan's METI, China's Ministry of Natural Resources, and the US Bureau of Ocean Energy Management shape extraction licensing through competing regulatory regimes.
- Energy Utilities:Grid operators securing long-term gas supply contracts for power generation diversification.
- Research Institutions:University hydrate institutes and national laboratories advancing extraction methodology through government-funded programs.
Oil & Gas channels the most capital; Government Bodies determine which segments achieve operational scale through funding allocation.
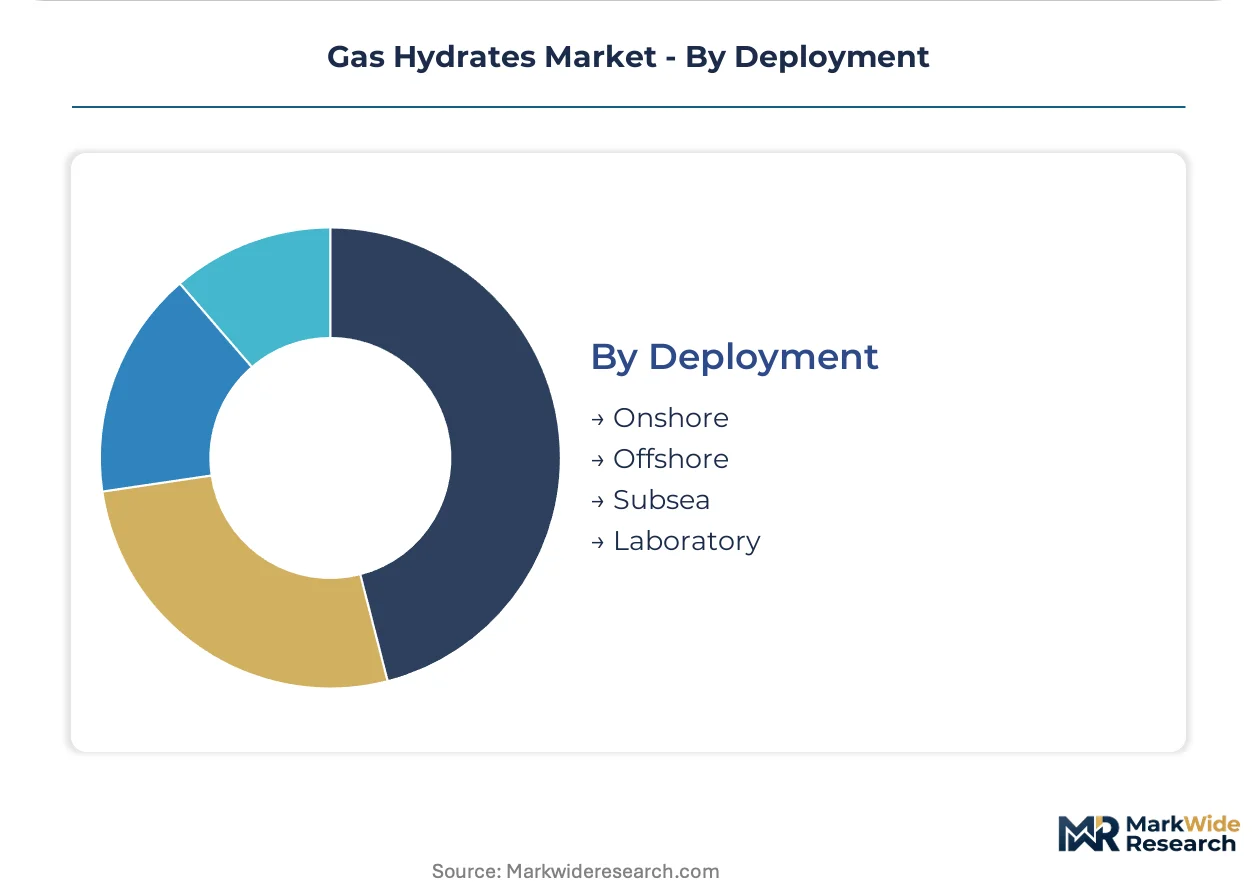
Deployment:
Capital deployment location determines equipment specifications, labor requirements, and regulatory compliance burdens.
- Offshore:Ultra-deepwater extraction from marine hydrate reservoirs exceeding 500-meter depths. Ultra-deepwater rig day rates and specialized hydrate-resistant equipment impose capital intensity that marginalizes smaller exploration consortia, concentrating activity among national oil companies with balance sheet capacity.
- Laboratory:Controlled environment research for extraction methodology validation and carbon sequestration testing. Japanese and South Korean national oil companies compress commercialization cycles through partnerships with university hydrate institutes, transferring technology from controlled conditions to field deployment.
- Onshore:Permafrost zone hydrate extraction in Arctic regions facing concentrated ownership disputes between Russia, Canada, and the United States.
- Subsea:Seabed production systems integrated with existing offshore infrastructure for flow assurance and gas processing.
Offshore absorbs majority capital allocation; Laboratory sustains innovation pipelines that enable future field deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's funding architecture anchors the dominant geography. Japan's national energy security strategy channels subsidy flows toward seabed resource development. Pilot project deployment concentrates in East Asian waters where jurisdictional competition accelerates permitting timelines.
Japan
Domestic energy diversification mandates and methane hydrate research programs drive state-backed exploration investment. METI directs subsidy allocation toward Nankai Trough pilot extraction trials. Tokyo-based research consortia partner with offshore operators to compress laboratory-to-field technology transfer cycles.
China
Seabed mining claims in contested waters and national resource security objectives propel state-owned exploration spending. The Ministry of Natural Resources regulates extraction licensing through overlapping jurisdictional frameworks. South China Sea lease blocks attract first-mover permitting activity ahead of territorial arbitration resolution.
United States
Gulf of Mexico deepwater operational experience and frontier basin access sustain integrated major engagement. The Bureau of Ocean Energy Management shapes exploration permitting frameworks for ultra-deepwater hydrate reservoirs. Houston-headquartered service providers anchor reservoir characterization contracts in domestic waters.
South Korea
National energy diversification targets and guaranteed offtake channels for hydrate-derived gas imports create procurement certainty. KOGAS directs capital toward East China Sea exploration partnerships with Japanese counterparts. Busan-based research institutes advance depressurization extraction methodology for marine reservoir applications.
Norway
Arctic offshore operational expertise and EU F-Gas Regulation compliance mandates drive equipment vendor pre-qualification. Norwegian regulators enforce fluorinated-gas-free technology roadmaps for subsea thermal management systems. Stavanger-clustered engineering firms redesign hydrate prevention systems for Barents Sea deployment.
Gas Hydrates Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the gas hydrates sector. National oil companies with state balance sheet backing dominate capital-intensive offshore pilot projects, while integrated service providers capture recurring revenue through technology-integrated performance contracts. Three archetypes structure competitive positioning: state-backed resource developers, technology-integrated service contractors, and research consortium anchors. Dominant competitive moves include strategic partnerships between national oil companies and university hydrate institutes, plus integrated service contracting that bundles exploration with carbon sequestration liability transfer.
Among Japanese operators, Japan Petroleum Exploration Company Limited exemplifies the state-backed resource developer archetype through domestic hydrate research program dominance. Schlumberger Limited occupies a position representing technology-integrated service contractors leveraging reservoir characterization capabilities. Chevron Corporation anchors the integrated major category through Gulf of Mexico deepwater operational experience.
| Leading Market Players |
|---|
| PetroChina Company Limited |
| Schlumberger Limited |
| Chevron Corporation |
| TotalEnergies SE |
| ConocoPhillips |
| ExxonMobil Corporation |
| Japan Petroleum Exploration Company Limited |
| Korea Gas Corporation (KOGAS) |
| Shell Plc. |
| Others |
Supply Flow & Price Mechanics
CO2-based thermal management systems replacing fluorinated refrigerants in subsea equipment are redrawing procurement geography toward EU F-Gas Regulation-compliant vendors while compressing margins for legacy suppliers locked into high-global-warming-potential substance inventories.
Pricing Analysis
East Asian contract premiums diverge from North American spot benchmarks by the cost of ultra-deepwater rig mobilization and hydrate-specific certification tiers. Project-based long-term offtake agreements dominate, with price differentiation anchored in reservoir characterization depth and carbon sequestration liability bundling. Cost compression in standard exploration services is intensifying as electromagnetic seabed surveying displaces redundant drilling verification. National oil companies exhibit lowest price sensitivity due to state balance sheet backing, while smaller exploration consortia face margin pressure from specialized equipment procurement.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose hydrate extraction equipment shipments to Southeast Asian yards, concentrating supply risk in Singapore and South Korean fabrication hubs. Critical component dependencies include depressurization wellheads, electromagnetic seabed sensors, and CO2 injection systems. Single-source vulnerability in deepwater drilling engineering talent pools threatens project timelines across frontier basins. Distribution runs through integrated service contractors bundling exploration with carbon management procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from conventional shale gas and LNG import infrastructure that offers faster deployment timelines and lower capital intensity for energy security procurement.
For Market Incumbents: Fortify reservoir characterization capabilities through backward integration into electromagnetic seabed surveying technology, neutralizing Schlumberger's service contract dominance. Anchor carbon sequestration liability transfer clauses in Nankai Trough and South China Sea performance contracts to differentiate from pure hydrocarbon extraction competitors facing emissions trading scheme exposure.
For New Entrants and Emerging Players: Laboratory-to-field technology transfer partnerships represent the most penetrable entry vector, as Japanese and South Korean national oil companies seek external hydrate institute collaboration to compress commercialization cycles. Target depressurization extraction methodology licensing to operators facing reservoir characterization expertise gaps, using ISO safety protocol pre-certification as a go-to-market accelerant.
For Investors and Strategic Acquirers: The market sits at a pilot-to-commercial transition phase that favors technology-integrated service contractors with proven frontier basin deployment records. Long-term viability hinges on dual-purpose extraction-carbon-capture technology maturation rather than pure hydrocarbon economics. Monitor METI funding renewal trajectories and South China Sea territorial arbitration timelines as inflection indicators for state-backed capital allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Purpose Technology Licensing | Unlocks revenue from both methane extraction and CO2 sequestration procurement in EU emissions trading schemes. |
| Integrated Service Contracting | Bundles reservoir characterization with carbon liability transfer, displacing traditional equipment rental brokers in East Asian lease blocks. |
| Electromagnetic Seabed Surveying Deployment | Compresses exploration timelines by eliminating redundant drilling verification stages in Nankai Trough operations. |
| Fluorinated-Gas-Free Equipment Pre-Qualification | Secures vendor status for Norwegian and Greenlandic Arctic projects facing EU F-Gas Regulation compliance mandates. |
| Hydrate Institute Partnership Formation | Accelerates laboratory-to-field transfer cycles for depressurization extraction methodology validation. |
Methodological Framework
The analysis maps natural gas hydrate extraction, CO2 sequestration applications, and synthetic hydrate research segments, each validated through primary interviews with deepwater drilling engineers, METI program officers, national oil company project developers, and subsea equipment procurement leads. Secondary sources include Bureau of Ocean Energy Management permitting databases, Japan Agency for Natural Resources and Energy pilot project disclosures, ISO offshore safety protocol documentation, and customs records for hydrate-resistant equipment imports. Bottom-up project economics triangulate against top-down national energy security spending allocations.
Consistency checks against IEA unconventional resource assessments and EIA frontier basin production cost benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include hydrate type, application pathway, deployment environment, and end-user procurement authority. CAGRs derive from depressurization extraction technology maturation curves and carbon offset market development trajectories. Forecast inputs incorporate ultra-deepwater rig day rate volatility and electromagnetic surveying adoption rates.
Underlying assumptions cover METI funding continuity, South China Sea jurisdictional stability, and EU F-Gas Regulation enforcement timelines, with deviation risk concentrated in territorial arbitration outcomes and reservoir characterization expertise pipeline constraints. Practitioners should keep alternative scenarios live as national energy diversification mandates and emissions trading scheme price floors evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Industrial Burner Market
Fuels
Smart Gas Market
Fuels
China LNG Bunkering Market
Fuels
Mobile Fuel Delivery Market
Fuels
Europe Bunker Fuel Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Italy Chemical Logistics Market
Fuels
Mobile Gas Pumping System Market
Fuels
Diesel As Fuel Market
Fuels
South Africa Bunker Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
India Petrol Station Market
Fuels
Aboveground Fuel Storage Market
Fuels
Europe Renewable Aviation Fuel Market