
 United Kingdom Chemical Logistics Market | 2026-2036
United Kingdom Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Chemical Logistics Market Insights
Specialty chemical manufacturers is rotating share away from commodity chemical distributors as the dominant buyer archetype in UK chemical logistics. Suttons Group leverages its dedicated tanker fleet and hazardous materials certification to anchor bulk liquid transport across the Humber and Merseyside corridors. DHL Supply Chain competes through integrated warehousing and compliance management services that sustain pharmaceutical and agrochemical clients under stringent temperature and documentation protocols. Kuehne + Nagel differentiates via digital freight platforms that extend real-time visibility into cross-channel chemical movements.
Chemical logistics encompasses the specialized transportation, storage, and handling of hazardous and non-hazardous chemical substances under controlled temperature, pressure, and containment conditions, typically requiring UN-certified packaging, ADR-compliant road transport, and segregated warehousing with fire suppression and spill containment systems. The primary purpose is to maintain product integrity, ensure regulatory compliance, and prevent environmental or safety incidents throughout multi-modal supply chains. Transport services dominate value capture due to fuel surcharges and driver scarcity, while cold chain solutions within the technology segment represent the fastest-growing margin pool as biologics and temperature-sensitive agrochemicals expand. Warehousing remains structurally mature with limited new greenfield capacity around regulated industrial zones, pushing pricing power toward existing providers with environmental permits.
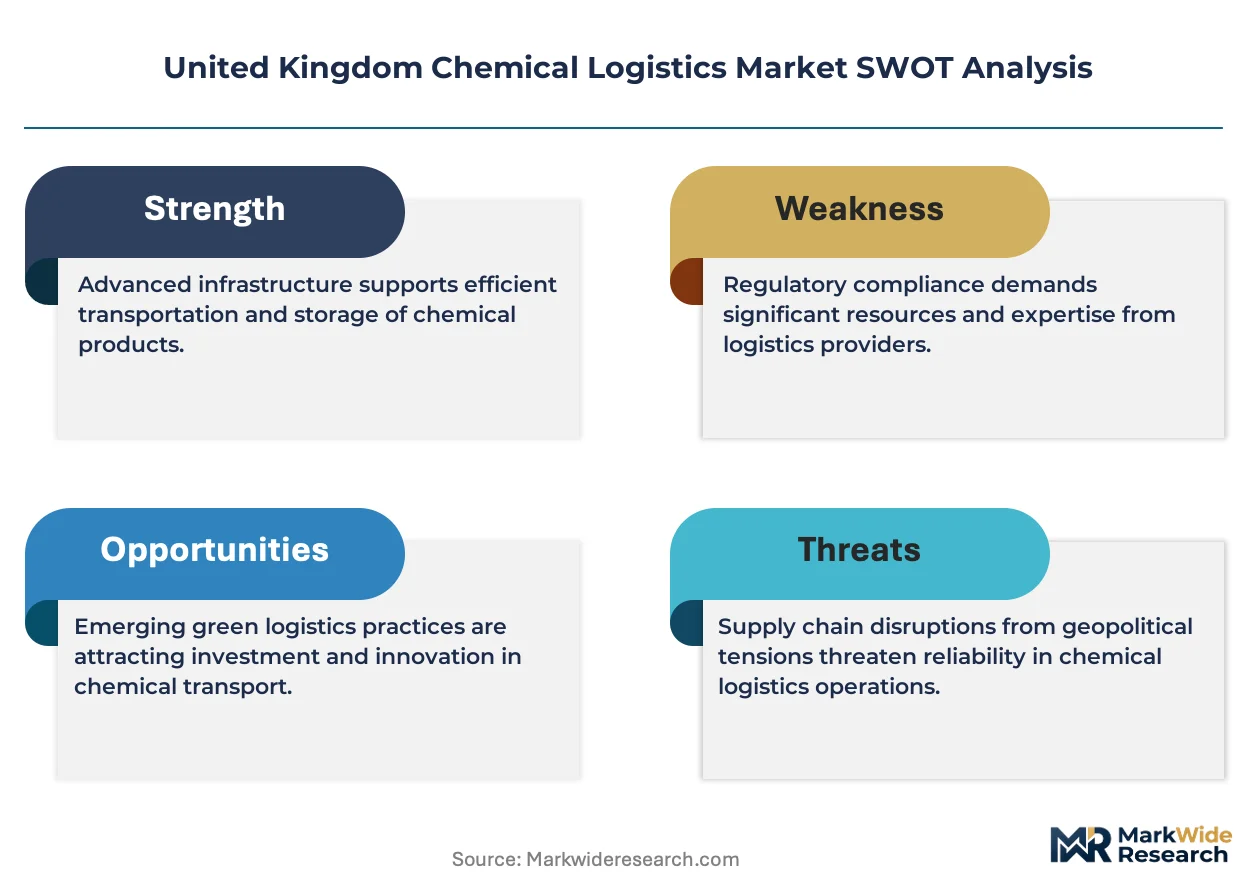
Health and Safety Executive (HSE) enforcement of Control of Major Accident Hazards (COMAH) regulations shapes site selection and operational standards for chemical storage facilities across England, Scotland, and Wales. REACH compliance administered by the Health and Safety Executive and the Environment Agency mandates detailed substance registration and safety data sheet management, directly elevating documentation burdens and third-party logistics outsourcing incentives. Stakeholders must monitor evolving UK REACH divergence from EU frameworks and carbon border adjustment mechanisms that will recalibrate cost structures for imported chemical feedstocks and finished goods.
Market Dynamics
UK REACH divergence from EU chemical registration frameworks is forcing specialty manufacturers to rebuild supply chain documentation from scratch, elevating demand for third-party compliance management and traceable custody systems across the Humber and Teesside industrial corridors.
Growth Catalysts
- COMAH tier upgrades:HSE enforcement of stricter Control of Major Accident Hazards thresholds is mandating facility modernization, creating contract opportunities for logistics providers with certified hazardous materials infrastructure.
- Biologics cold chain expansion:Temperature-sensitive pharmaceutical manufacturing in Oxford and Cambridge biotech clusters is pulling investment into validated cold storage and GDP-compliant distribution networks.
- Carbon border adjustment preparation:UK importers of chemical feedstocks are pre-positioning low-carbon logistics assets to mitigate exposure to imminent carbon tariffs on high-emission supply routes.
Market Restraints
- Driver qualification scarcity:ADR-certified HGV operators command wage premiums exceeding 25% above standard haulage rates, compressing margins on bulk liquid transport contracts.
- Permitted warehouse scarcity:Greenfield development restrictions around COMAH-designated zones in England and Wales limit storage capacity expansion, entrenching incumbent providers with existing environmental licenses.
- Natural gas price volatility:Energy-intensive tank heating and refrigeration operations face input cost swings that resist full pass-through in long-term logistics contracts.
Strategic Opportunities
- Scottish hydrogen corridor:Aberdeen and Grangemouth industrial zones are emerging as hydrogen production hubs requiring specialized high-pressure gas logistics infrastructure.
- Digital twin integration:Convergence of IoT sensor networks with predictive analytics platforms enables real-time inventory optimization for multi-site chemical manufacturers.
- Reverse logistics for packaging:UN-certified intermediate bulk container cleaning and reuse services represent an underdeveloped margin pool as circular economy mandates tighten.
Industry Challenges
- Dangerous goods safety advisor certification:The 18-month qualification timeline for DGSA credentials creates talent bottlenecks for expanding logistics operations.
- Legacy ERP integration:Proprietary warehouse management systems at established chemical storage facilities resist interoperability with customer-side supply chain visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Chemical Logistics Market |
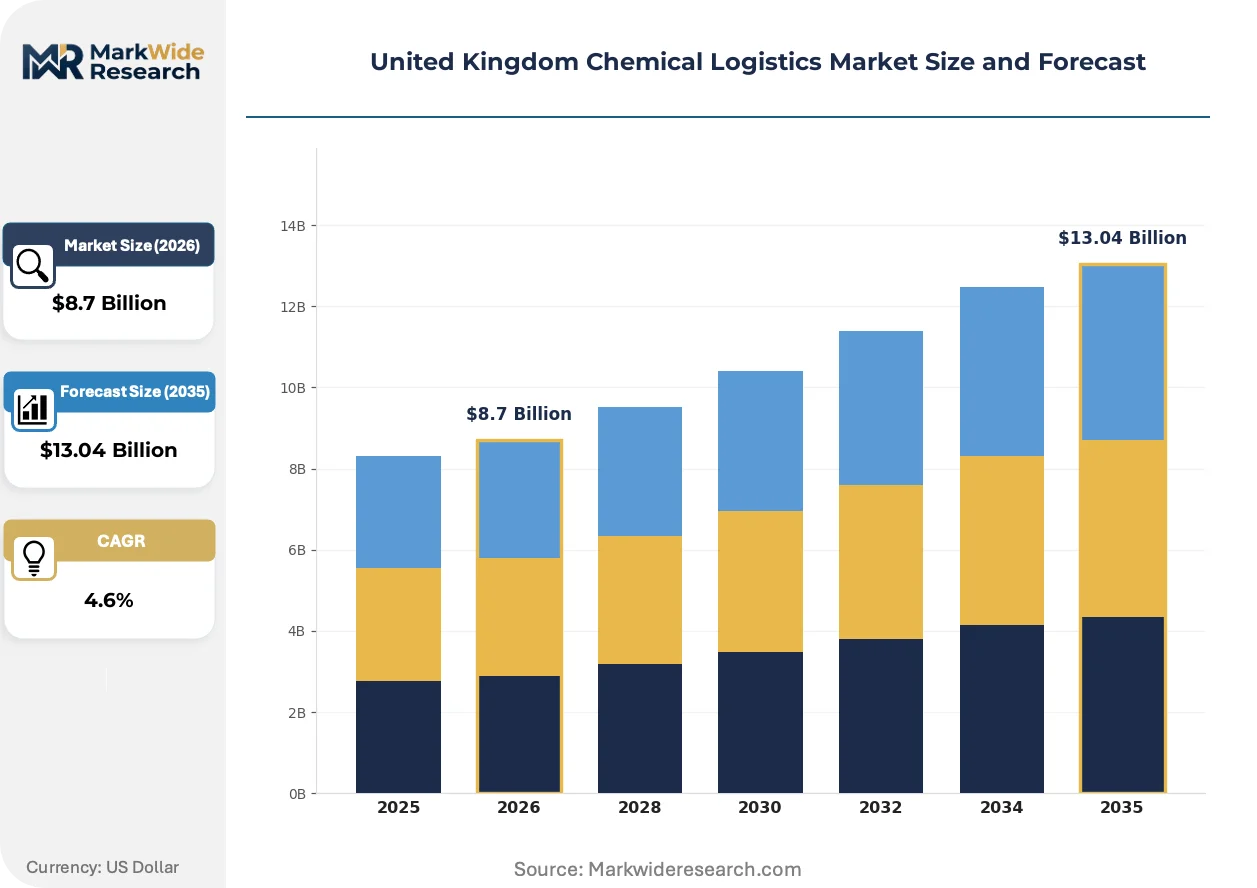
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport, Warehousing, Packaging, Distribution Application: Pharmaceuticals, Agrochemicals, Paints, Specialty Chemicals Technology: Tracking Systems, Automations, Cold Chain Solutions, Safety Equipment End User: Chemical Manufacturers, Retailers, Research Institutions, Distributors |
| Companies Covered | DHL Supply Chain, Suttons Group, CEVA Logistics, DACHSER UK, Hoyer Group, Rhenus Logistics, BDP International, DB Schenker, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Chemical Logistics Market Trends and Innovations
Digital freight platforms and autonomous compliance monitoring tools are compressing information asymmetries between chemical shippers and logistics providers, reshaping how custody documentation and regulatory evidence chains are constructed and verified.
Blockchain-enabled batch traceability is fragmenting traditional document-handling revenue pools among logistics intermediaries. Pharmaceutical and agrochemical manufacturers in the Southeast England corridor are piloting distributed ledger systems for REACH-compliant substance tracking. This technology is fragmenting legacy paper-based audit trails into automated, immutable record architectures that reduce third-party documentation fees.
UK REACH standalone registration requirements are diverging from retained EU law, compelling dual-track compliance systems for cross-channel chemical movements. The Health and Safety Executive's substance database mandates are extending documentation burdens to downstream users previously exempt under EU arrangements. Specialty chemical distributors serving both UK and continental European customers are absorbing the highest adaptation costs, accelerating outsourcing to dedicated compliance service providers.
Consolidated procurement of bundled transport and warehousing services is displacing spot-market contracting among mid-sized chemical manufacturers. Direct agreements with integrated 3PL operators are replacing fragmented relationships with multiple niche hauliers and storage operators. This concentration is most visible in the North West England chemicals cluster, where manufacturers seek single-accountability partners for end-to-end hazardous materials handling.
United Kingdom Chemical Logistics Market Segmentation
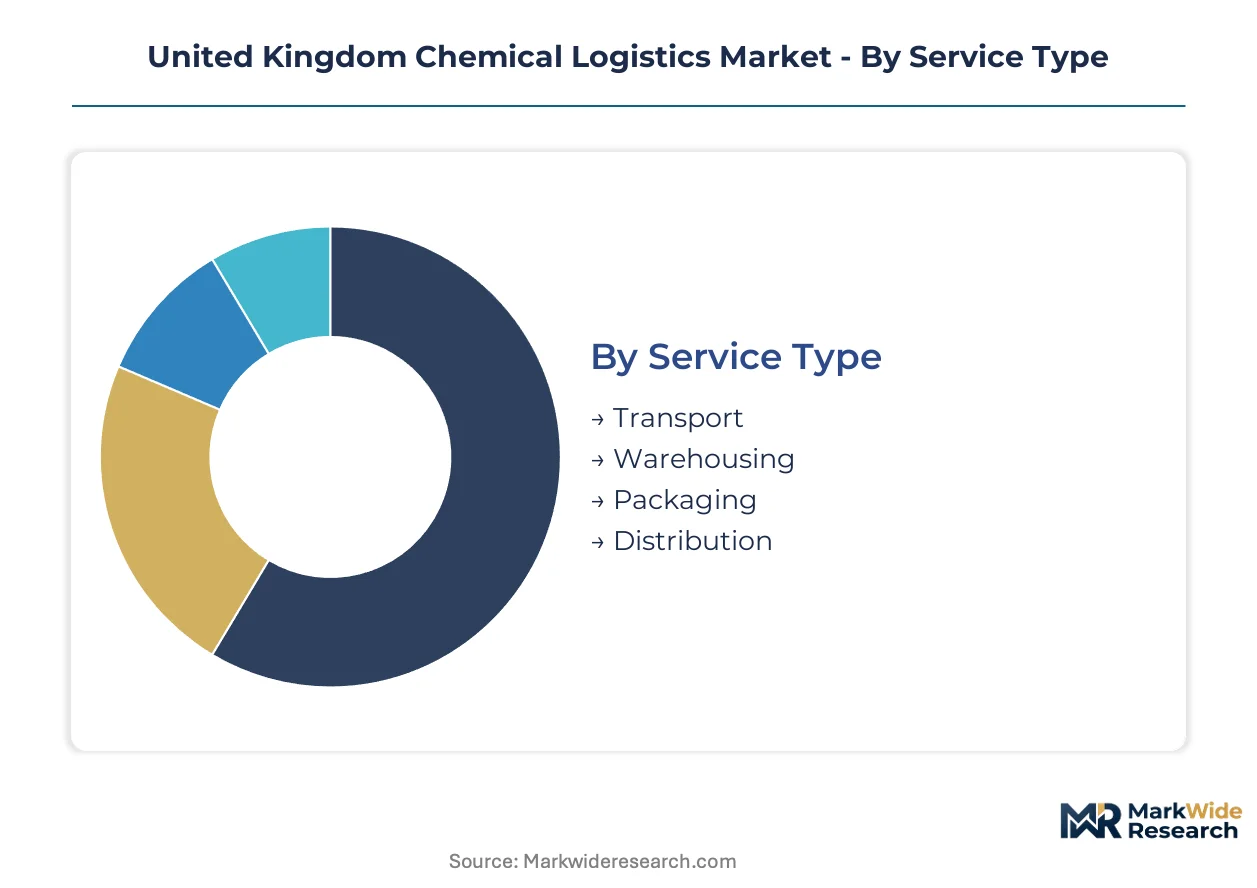
Chemical logistics segmentation in the United Kingdom reflects divergent compliance burdens and infrastructure requirements across service modalities. Each category maps to distinct regulatory thresholds, capital intensity profiles, and customer procurement behaviors that reshape competitive positioning.
Service Type:
Regulatory differentiation separates ADR-certified transport from COMAH-regulated warehousing through enforcement intensity and permit scarcity.
- Transport:ADR-compliant road haulage of bulk liquids and packaged dangerous goods dominates value capture. HSE enforcement of driver certification mandates and fuel surcharge pass-through mechanics concentrate contract awards with fleet-scale operators across the Humber and Teesside corridors.
- Warehousing:COMAH-designated storage facilities with fire suppression, spill containment, and segregated hazardous materials zones command structural scarcity premiums. Greenfield restrictions around regulated industrial zones in England and Wales entrench incumbent providers with existing environmental licenses.
- Packaging:UN-certified intermediate bulk container supply and reuse services support circular economy mandates.
- Distribution:Multimodal coordination spanning road, rail, and short-sea chemical tanker movements.
Established volume favors Transport; emerging adoption favors Warehousing.
Application:
Customer type determines temperature sensitivity, documentation granularity, and custody transfer protocols.
- Pharmaceuticals:GDP-compliant cold chain distribution of active pharmaceutical ingredients and biologics demands validated storage and real-time temperature monitoring. Oxford and Cambridge biotech clusters are pulling investment into specialized infrastructure with 2-8°C and -20°C capability.
- Agrochemicals:Seasonal demand surges for crop protection chemicals require surge storage and flexible fleet deployment. Fertilizer and pesticide distributors in East Anglia face REACH registration burdens for formulated products crossing UK-EU boundaries.
- Paints:Flammable liquid coatings with VOC content restrictions.
- Specialty Chemicals:High-value, low-volume formulations with complex SDS management.
Margin compression concentrates in Paints; premium expansion concentrates in Pharmaceuticals.
Technology:
Capital deployment intensity separates sensor-enabled visibility platforms from passive safety infrastructure.
- Cold Chain Solutions:Refrigerated transport units and validated warehouse chambers with continuous temperature logging and alarm escalation. Biologics manufacturing expansion in the Southeast is accelerating replacement of legacy mechanical refrigeration with redundant compressor architectures.
- Tracking Systems:GPS-enabled fleet telematics and RFID batch traceability for custody documentation. Pharmaceutical manufacturers are mandating real-time location visibility as a contract prerequisite for high-value API movements.
- Automations:Warehouse robotics for hazardous materials handling with ATEX certification.
- Safety Equipment:Personal protective gear and emergency response kits for spill containment.
Deployment scale favors Tracking Systems; steepest expansion trajectory belongs to Cold Chain Solutions.
End User:
Procurement sophistication tiers separate integrated manufacturers from fragmented retail channels.
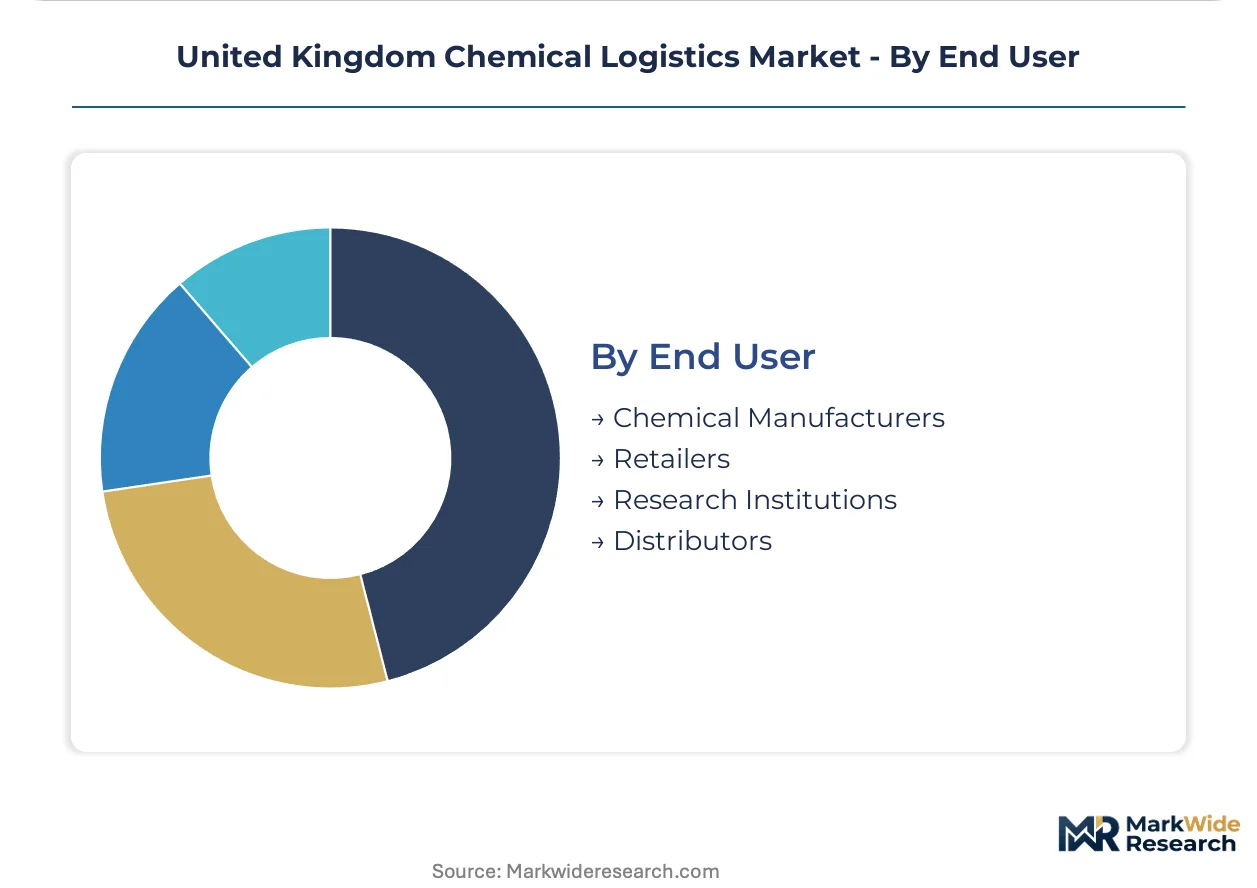
- Chemical Manufacturers:Integrated producers with captive logistics operations and third-party outsourcing for peak capacity. Specialty chemical makers in the North West are consolidating procurement around single-accountability 3PL partners for end-to-end hazardous materials handling.
- Distributors:Independent merchants serving fragmented downstream customers with mixed SKU portfolios. REACH compliance complexity is forcing specialty distributors to rebuild documentation systems from scratch, elevating demand for outsourced compliance management.
- Retailers:Garden centers and trade outlets with limited hazardous materials handling expertise.
- Research Institutions:Universities and contract research organizations with small-quantity exemption shipments.
Contract concentration favors Chemical Manufacturers; service fragmentation favors Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-channel chemical movements from Rotterdam and Antwerp feed UK processing clusters, while North Sea routes connect Teesside and Grangemouth to Scandinavian petrochemical suppliers. This trade geometry shapes logistics infrastructure investment across British industrial corridors.
North England
Teesside's chemical processing corridor generates concentrated demand for bulk liquid storage and multimodal connectivity. HSE COMAH enforcement mandates facility upgrades across Stockton-on-Tees and Middlesbrough sites. The Humber cluster anchors tanker fleet deployment for refineries and polymer manufacturers.
Scotland
Grangemouth's petrochemical complex requires specialized high-pressure gas logistics as hydrogen production scales. The country's environmental regulator imposes stringent emissions controls on chemical storage facilities. Aberdeen's energy transition is pulling investment into hydrogen corridor infrastructure.
Wales
Deeside industrial zones serve pharmaceutical manufacturers with GDP-compliant cold chain requirements. Natural Resources Wales oversees hazardous materials permitting with COMAH-equivalent standards. Newport and Cardiff ports handle agrochemical imports for Welsh agricultural distributors.
North West England
Runcorn and Widnes chemical manufacturers consolidate procurement around integrated 3PL partners for end-to-end hazardous materials handling. The Environment Agency regulates legacy chlor-alkali site remediation affecting logistics routing. Manchester Ship Canal movements connect Merseyside processors to global feedstock suppliers.
South East England
Oxford and Cambridge biotech clusters drive validated cold storage investment for biologics distribution. MHRA GDP inspections enforce temperature documentation standards across pharmaceutical supply chains. Thames corridor ports handle specialty chemical imports for Southeast formulation facilities.
United Kingdom Chemical Logistics Market Competitive Landscape
Listed logistics conglomerates compete with private tanker specialists across certification depth and fleet scale. The market structures around three tiers: integrated global 3PLs with compliance management platforms, regional bulk liquid operators with dedicated hazardous materials fleets, and niche cold chain providers serving pharmaceutical clusters. Consolidation pressure intensifies as manufacturers seek single-accountability partners, while greenfield warehouse scarcity protects incumbent positions.
Within the integrated 3PL tier, DHL Supply Chain and Kuehne + Nagel exemplify archetypes combining warehousing networks with digital freight platforms. Suttons Group anchors the specialist tanker segment with hazardous materials certification concentrated across Humber and Merseyside corridors. These three occupy positions reflecting divergent capital deployment strategies: technology-enabled compliance management versus physical infrastructure ownership.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Suttons Group |
| CEVA Logistics |
| DACHSER UK |
| Hoyer Group |
| Rhenus Logistics |
| BDP International |
| DB Schenker |
| Kuehne + Nagel |
| Others |
Pricing and Supply Chain Analysis
Fleet-scale tanker operators with ADR-certified capacity utilization above 80% command structural premiums across the Humber and Teesside corridors, compressing margins for sub-scale hauliers while entrenching price floors for bulk liquid transport contracts. This concentration dynamic amplifies pricing power for incumbent providers with existing COMAH environmental permits, particularly as greenfield warehouse scarcity eliminates new competitive entry.
Pricing Analysis
Legacy mechanical refrigeration systems trade at 15-20% discounts against redundant compressor architectures with continuous temperature logging, while next-generation IoT-enabled cold chain units capture premium positioning from biologics manufacturers in Oxford and Cambridge. Three-tier pricing structure across premium certified, standard compliant, and economy spot-market levels dominates contract awards, with ADR certification grade and volume scale as primary differentiation drivers. Cost compression in economy spot haulage is intensifying because driver scarcity resists full pass-through, making specialty chemical manufacturers the least price-sensitive segment due to REACH compliance outsourcing premiums, while agrochemical distributors show highest sensitivity to seasonal freight surges.
Supply Chain Analysis
Cross-Channel ferry transit through Dover and Calais underwrites just-in-time feedstock deliveries to Teesside polymer manufacturers, creating vulnerability to customs documentation delays. Chemical feedstock supply concentrates in Rotterdam and Antwerp for Northwest England processors, with Scandinavian methanol and Middle Eastern solvent dependencies feeding Grangemouth and Humber refineries. Raw material inputs draw from Norwegian natural gas liquids, Belgian ethylene derivatives, and German specialty additive formulations. Single-source vulnerability runs through Rotterdam-Rijnmond pipeline terminals for bulk liquid imports. Distribution runs through integrated 3PL partnerships displacing fragmented haulier relationships across North West England chemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital freight platform interoperability is reconfiguring chemical logistics from asset-heavy contracting toward data-layer ecosystem economics, with real-time custody documentation becoming the primary value capture mechanism.
For Market Incumbents: Fortify COMAH-designated warehouse positions through environmental permit renewals and fire suppression infrastructure upgrades before HSE enforcement intensifies. Deepen backward integration into UN-certified intermediate bulk container cleaning and reuse services to capture circular economy mandate premiums. Suttons Group and DHL Supply Chain face emerging threat from digital-native freight platforms that fragment documentation revenue pools through blockchain-enabled batch traceability.
For New Entrants and Emerging Players: Lead with Scottish hydrogen corridor logistics infrastructure as Aberdeen and Grangemouth production scales, targeting high-pressure gas transport white space with specialized fleet investment. The most penetrable segment sits in GDP-compliant cold chain distribution for Cambridge and Oxford biotech clusters, where validated storage capacity shortages persist. A direct go-to-market angle pairs IoT sensor deployment with predictive analytics subscriptions for multi-site chemical manufacturers seeking inventory optimization.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated 3PL operators with compliance management platforms over pure-play tanker fleets facing margin compression from driver wage premiums. Long-term viability rests on carbon border adjustment preparation and low-carbon logistics asset positioning as UK importers pre-position for imminent tariff exposure. Acquisition target archetype: regional bulk liquid operators with ADR certification depth and Teesside corridor density. The signal to watch is UK REACH divergence implementation pace, which will recalibrate compliance service provider valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IBC Reuse Services | Captures circular economy premiums as UN-certified container cleaning mandates tighten under HSE enforcement. |
| Hydrogen Corridor Infrastructure Deployment | Positions operators for Aberdeen and Grangemouth high-pressure gas logistics demand from energy transition investments. |
| Digital Twin Platform Integration | Enables real-time inventory optimization for pharmaceutical manufacturers with MHRA GDP inspection requirements. |
| COMAH Facility Modernization Program | Secures environmental permit renewals before HSE tier upgrade enforcement eliminates substandard storage capacity. |
| Cold Chain Redundant Architecture Upgrade | Addresses biologics manufacturer demand for validated 2-8°C and -20°C storage with continuous alarm escalation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of HSE enforcement databases, UK REACH registration filings, and customs trade data for chemical feedstock movements. Primary interviews engaged logistics procurement directors at specialty chemical manufacturers, ADR-certified fleet operations managers, COMAH facility compliance officers, and pharmaceutical supply chain leads with GDP accountability. Secondary validation drew from Environment Agency permit registers, Health and Safety Executive COMAH tier designations, and SEC filings of listed logistics conglomerates. Bottom-up capacity and utilization estimates triangulated against top-down market value reconstruction.
Segmentation dimensions modeled span service type, application, technology, and end user across the projection horizon, with regional granularity at England sub-region, Scotland, and Wales. CAGRs derived from logistic curve fitting to historical value trajectories, adjusted for regulatory inflection points including UK REACH standalone implementation and carbon border adjustment preparation. Industry-specific forecast inputs incorporated ADR driver certification pipeline constraints and permitted warehouse scarcity elasticities.
The analysis sits within stated boundaries; outcomes outside sustained HSE enforcement intensity and stable cross-Channel trade flows would require recalibration. Forecasts reflect documented assumptions regarding REACH compliance cost pass-through and biologics manufacturing expansion trajectories. Practitioners should keep alternative scenarios live as UK-EU regulatory divergence and hydrogen economy infrastructure commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Coal Market
Fuels
Europe Firewood Market
Fuels
Italy Chemical Logistics Market
Fuels
Carbonizers Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
Chafing Fuel Market
Fuels
Mobile Gas Pumping System Market
Fuels
Smart Gas Market
Fuels
Coal Briquettes Market
Fuels
Smart Gas Solutions Market
Fuels
Anthracite Coal Mining Market
Fuels
Global Wood Gas Generator Market
Fuels
United States Coal Market
Fuels
Compressed Natural Gas Market