
 Marine Fuel Filter Market | 2026-2036
Marine Fuel Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fuel Filter Market Foresight
Asian filter foundries is recalibrating production lines toward high-pressure marine specifications. Parker Hannifin Corporation leverages its fluid systems integration to dominate naval and commercial OEM channels. Donaldson Company competes through advanced media technology for heavy fuel oil applications. Alfa Laval anchors its position with centrifugal-separator hybrid systems that extend filter service intervals.
Marine fuel filters are pressure-rated filtration devices, typically constructed from stainless steel housings with multi-layer synthetic or cellulose media, designed to remove particulate matter, water, and microbial contamination from residual and distillate marine fuels before injection into diesel engines or gas turbines. Cartridge filters command the largest installed base due to retrofit compatibility across aging commercial fleets, while spin-on filters represent the fastest-growing category in recreational and fishing boat segments where maintenance simplicity drives preference. Stainless steel housings sustain premium pricing in deep-sea commercial applications where corrosion resistance and IMO compliance are non-negotiable, whereas plastic and aluminum variants occupy cost-sensitive coastal and inland waterway markets.
The International Maritime Organization enforces MARPOL Annex VI fuel quality standards that mandate sulfur content limits, directly compelling fleet operators to install higher-efficiency filtration to protect engine systems from catalytic fines and acidic byproducts. EPA marine engine regulations in the United States and EU MRV monitoring requirements under the European Commission create parallel compliance pathways that elevate filter performance specifications across export-bound vessel classes. Stakeholders must monitor the pace of alternative fuel adoption, as methanol and ammonia compatibility will determine next-generation filter media formulations and housing material choices.
Market Dynamics
The International Maritime Organization's sulfur cap regulations are compressing filter replacement cycles and forcing fleet operators toward high-efficiency systems capable of handling variable bunker fuel quality across global ports.
Growth Catalysts
- MARPOL Annex VI enforcement:The IMO's sulfur content mandates compel commercial vessel operators to upgrade filtration systems, protecting engines from catalytic fines and acidic byproducts in low-sulfur residual fuels.
- Singapore bunkering hub expansion:The city-state's dominance in marine fuel supply drives concentrated demand for port-side filter service infrastructure and rapid-turnaround cartridge replacement.
- Centrifugal-separator hybrid adoption:Advanced filtration technology extends service intervals for deep-sea operators, reducing downtime costs during extended voyages.
Market Restraints
- Stainless steel input volatility:Premium housing material costs fluctuate with nickel and chromium commodity markets, squeezing margins on deep-sea commercial specifications.
- Asian foundry concentration:High-pressure marine filter production concentrates in a limited geographic corridor, creating vulnerability to regional supply disruptions.
- Alternative fuel compatibility gaps:Methanol and ammonia propulsion systems lack standardized filtration protocols, delaying fleet-wide system redesigns.
Strategic Opportunities
- EU MRV monitoring alignment:The European Commission's emissions verification requirements create demand for integrated filtration-monitoring systems that track fuel quality and engine protection metrics.
- Recreational spin-on penetration:Simplified maintenance designs target fishing boat and yacht segments where owner-operators prioritize ease of replacement over premium specifications.
- EPA marine engine tier compliance:United States export-bound vessel classes require elevated filter performance, opening channels for high-efficiency media technology.
Industry Challenges
- Multi-fuel system integration:Shipyards face complexity installing filtration architectures compatible with both conventional bunkers and emerging alternative fuels within existing engine room footprints.
- Certification timeline compression:Rapidly evolving IMO and EPA standards outpace type-approval processes, delaying product launches for next-generation media formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fuel Filter Market |
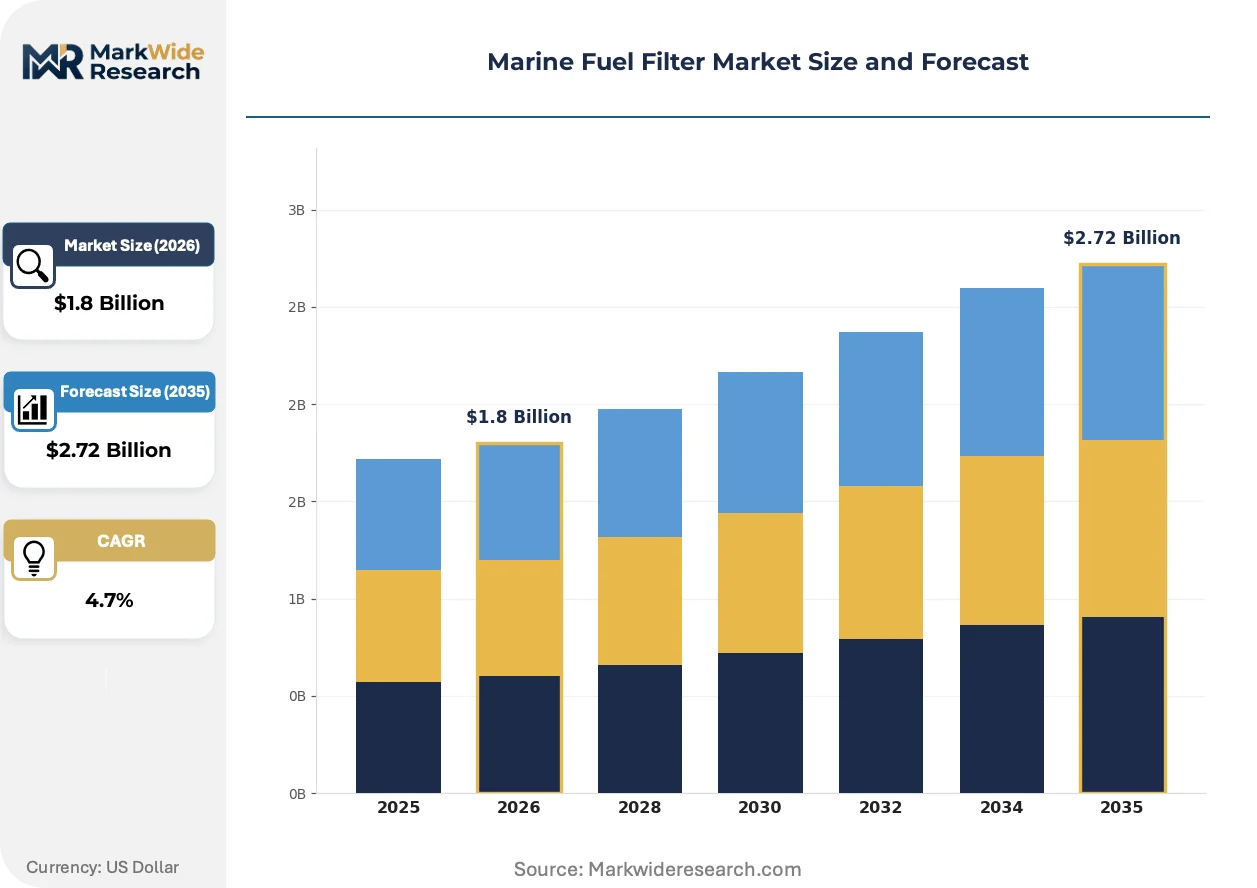
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin-On Filters, Cartridge Filters, Duplex Filters, Bag Filters Material: Stainless Steel, Plastic, Fiberglass, Aluminum End User: Commercial Vessels, Recreational Boats, Fishing Boats, Tugboats Installation Type: In-line Installation, Modular Installation, Portable Systems, Integrated Systems |
| Companies Covered | Parker Hannifin Corporation, Alfa Laval, Donaldson Company, MANN+HUMMEL, Fleetguard, GEA Group, Wärtsilä, Mahle GmbH, Moeller Marine Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fuel Filter Market Shifts & Advancements
Filtration technology is advancing through material science breakthroughs and regulatory pressure, with hybrid systems and smart monitoring reshaping how marine operators manage fuel quality across diverse operational profiles.
Synthetic multi-layer media technology is converging with cellulose substrates to create filtration matrices that capture particulate matter across broader size distributions while maintaining flow rates under high-pressure injection conditions. Deep-sea commercial fleets are adopting these advanced cartridges most aggressively, driven by extended service interval requirements on transoceanic routes. The convergence is compressing demand for single-media legacy designs and elevating performance specifications across OEM supply contracts.
REACH chemical registration requirements in Europe are restricting certain binder chemistries used in traditional filter media manufacturing, forcing reformulation of cellulose-based products. Industrial consequence includes accelerated migration toward fully synthetic media that bypass restricted substance lists while maintaining separation efficiency. Deep-sea commercial applications face the strongest compliance pressure, with European-flagged vessels and export-bound fleets prioritizing REACH-compliant filtration architectures.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance relationships as independent port service providers capture filter replacement revenue. Singapore and Rotterdam harbor networks are seeing the fastest channel disruption, with specialized bunkering service firms offering rapid cartridge exchange independent of engine manufacturer contracts. Coastal and short-sea shipping segments are driving this behavioral shift, prioritizing cost transparency and local availability over integrated warranty coverage.
Marine Fuel Filter Market Segmentation
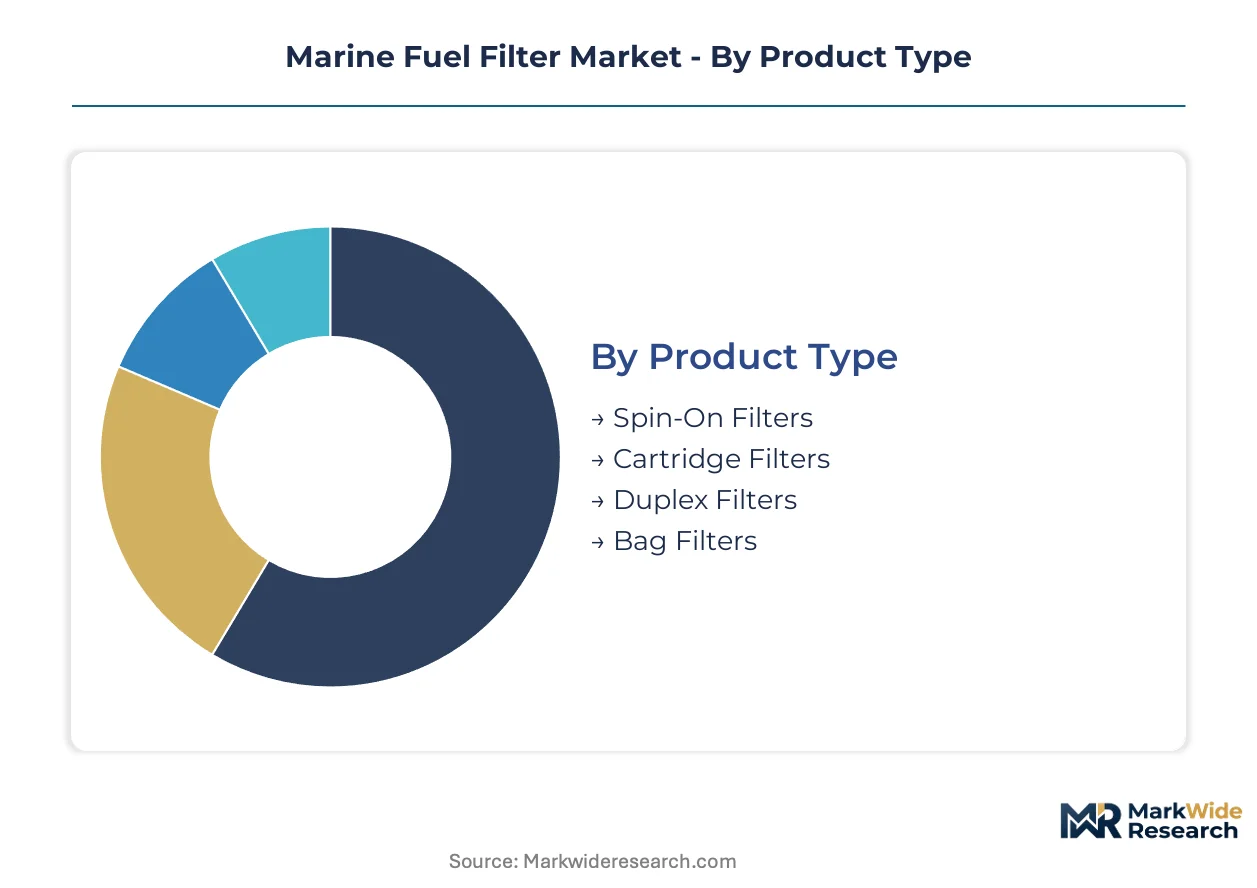
Marine fuel filter segmentation reveals divergent capital requirements across vessel classes and operational profiles. Product architecture, material selection, and installation complexity create distinct investment thresholds that shape procurement behavior among fleet operators and shipyards.
Product Type:
Capital intensity peaks with duplex filtration architectures requiring redundant flow paths and automated switching mechanisms.
- Cartridge Filters:Multi-layer synthetic or cellulose media housed in reusable stainless steel vessels dominate deep-sea commercial retrofit programs. Operators favor these systems in Singapore's bunkering corridors where extended service intervals reduce port downtime during high-frequency fueling cycles.
- Spin-On Filters:Self-contained disposable units with integrated sealing elements command preference among recreational and fishing vessel owner-operators. Demand concentrates in Mediterranean and Caribbean coastal marinas where maintenance simplicity outweighs per-unit cost premiums.
- Duplex Filters:Parallel-flow configurations enable continuous operation during element changeout.
- Bag Filters:Large-surface-area disposable media suit high-volume pre-filtration stages.
Most installed capacity flows through cartridge architectures. Expansion is steepest in spin-on configurations.
Material:
Raw material cost tiers separate deep-sea specifications from coastal alternatives, with nickel-alloy pricing volatility reshaping procurement calendars.
- Stainless Steel:Austenitic grades with molybdenum additions deliver corrosion resistance mandatory for IMO-compliant residual fuel handling. Japanese and South Korean shipyards specify these housings for export-bound LNG carriers and container vessels subject to MARPOL Annex VI enforcement.
- Plastic:Glass-reinforced polyamide and high-density polyethylene variants occupy inland waterway and harbor craft segments. Operators on the Mississippi River system and European canal networks prioritize these lightweight alternatives where pressure ratings remain below 150 psi.
- Fiberglass:Composite housings blend chemical resistance with moderate pressure tolerance.
- Aluminum:Cast and extruded housings serve cost-sensitive coastal fishing fleets.
Stainless steel captures the highest value per unit. Plastic variants are climbing fastest in absolute shipment volume.
End User:
Operational duty cycles and regulatory exposure create divergent filter performance requirements across vessel categories.
- Commercial Vessels:Deep-sea cargo ships, tankers, and bulk carriers operating on residual fuel oils demand high-efficiency media capable of capturing catalytic fines. Fleet managers in the Marshall Islands and Panama registries prioritize centrifugal-separator hybrid systems that extend maintenance windows across trans-Pacific routes.
- Recreational Boats:Yachts and pleasure craft running on distillate marine gas oil favor compact spin-on configurations. Marina service providers in Florida and the French Riviera stock these units for rapid weekend replacement.
- Fishing Boats:Trawlers and longliners balance fuel quality protection with space constraints in cramped engine rooms.
- Tugboats:Harbor assist and escort vessels require robust filtration for intermittent high-load operation.
Commercial vessel specifications absorb the majority of industry R&D investment. Recreational applications are expanding most quickly in emerging Asian marina developments.
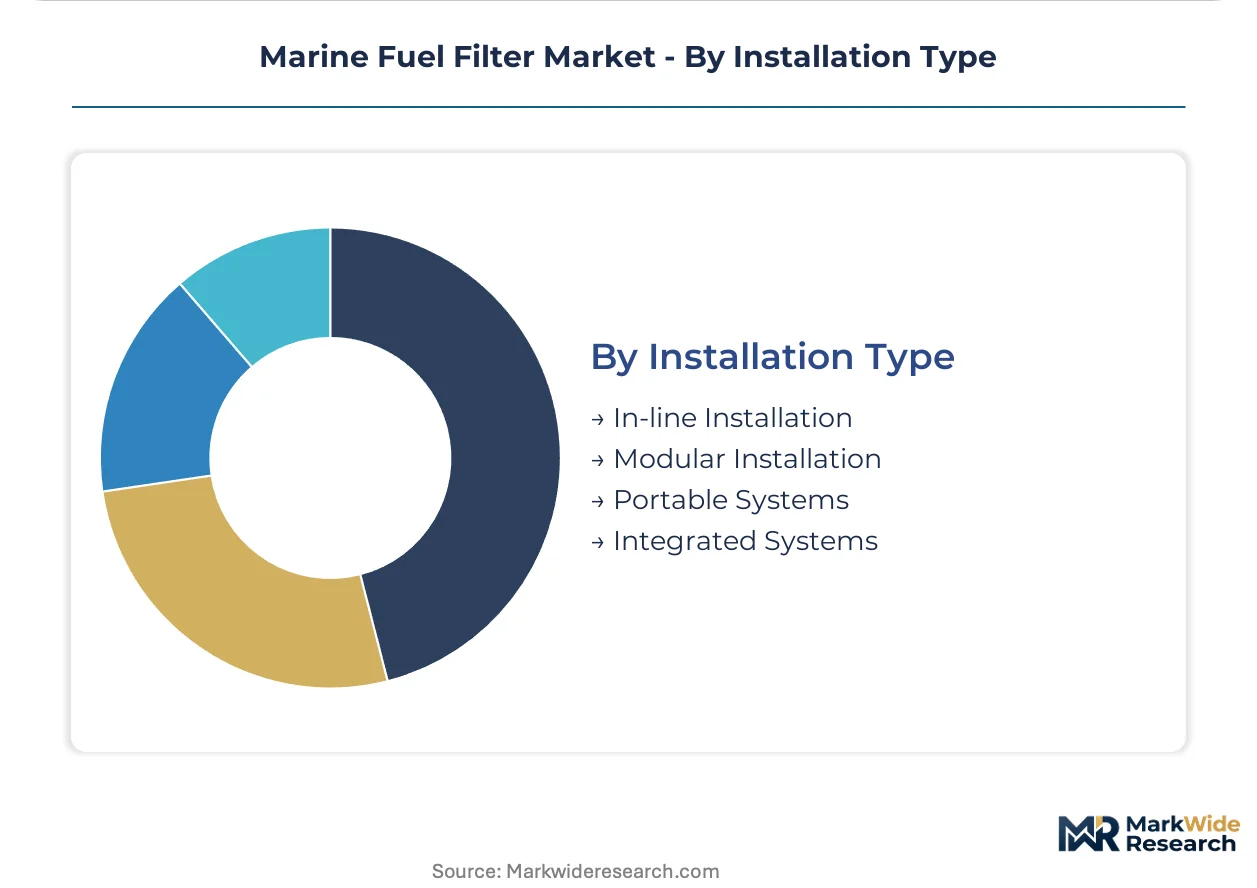
Installation Type:
Shipyard labor economics and engine room spatial constraints drive adoption patterns for mounting configurations.
- Integrated Systems:Factory-installed filtration modules bundled with engine packages dominate newbuild contracts. Wärtsilä and MAN Energy Solutions specify these architectures for two-stroke marine diesel engines delivered to Chinese and Vietnamese shipyards.
- In-line Installation:Straight-run piping configurations suit retrofit applications with minimal structural modification. Independent service firms in Rotterdam and Houston deploy these solutions for aging fleet upgrades.
- Modular Installation:Skid-mounted units enable rapid field configuration.
- Portable Systems:Temporary filtration for bunkering quality verification and emergency bypass.
Integrated systems flow through OEM newbuild channels. Modular alternatives are gaining share fastest among second-hand vessel refit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing marine fuel filter manufacturing toward jurisdictions with lower compliance-cost structures, while bunkering hub concentration in Singapore and Rotterdam drives service infrastructure investment.
Singapore
The city-state's dominance in global marine fuel supply concentrates demand for rapid-turnover cartridge replacement services. Port-side filter infrastructure expansion aligns with MARPOL Annex VI enforcement timelines for vessels transiting Southeast Asian shipping lanes. Jurong Port and Tuas Mega Port clusters host specialized bunkering service firms offering independent filter maintenance.
China
Shanghai and Guangzhou shipyards drive integrated filtration system demand for newbuild LNG carriers and container vessels. The Ministry of Ecology and Environment enforces domestic emission control area standards that parallel IMO sulfur regulations. Yangtze River Delta manufacturing corridors supply stainless steel housings for export-bound commercial specifications.
South Korea
Ulsan and Geoje shipbuilding complexes specify high-pressure marine filtration for residual fuel handling on deep-sea cargo ships. Korean Register certification requirements elevate performance specifications for filtration media in two-stroke marine diesel applications. Busan bunkering terminals support filter service networks for trans-Pacific fleet operators.
Germany
Hamburg and Bremen harbor infrastructure supports EU MRV monitoring compliance through integrated filtration-monitoring systems. REACH chemical registration restricts traditional filter media binders, accelerating synthetic media adoption for European-flagged vessels. Mannheim industrial corridors anchor centrifugal-separator hybrid system development for extended service intervals.
United States
Gulf Coast refining and bunkering operations in Houston and New Orleans drive demand for EPA marine engine tier-compliant filtration. Port of Long Beach and Port of Los Angeles emission reduction programs compel filter upgrades for container vessels serving transpacific routes. Mississippi River inland waterway operators prioritize cost-optimized plastic housing variants below 150 psi ratings.
Marine Fuel Filter Market Competitive Landscape
Asian foundries anchor one tier of supply; European and North American fluid systems specialists hold differentiated positions in OEM-integrated channels. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with marine divisions, pure-play filtration technology developers, and shipyard-captive system integrators. Competitive maneuvering centers on backward integration into media manufacturing and geographic expansion of port-side service networks.
Among diversified industrial groups, Parker Hannifin Corporation and Alfa Laval occupy positions exemplifying fluid systems integration and centrifugal-separator hybrid architectures respectively. Donaldson Company represents the advanced media technology archetype for heavy fuel oil applications. These three anchors illustrate how competitive positioning diverges between systems integration depth and materials science specialization.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Alfa Laval |
| Donaldson Company |
| MANN+HUMMEL |
| Fleetguard |
| GEA Group |
| Wärtsilä |
| Mahle GmbH |
| Moeller Marine Products |
| Others |
Supply & Pricing Matrix
Specialized welders and pressure-vessel technicians concentrated in South Korean shipyard clusters drive labor-cost differentials that widen pricing spreads between premium stainless steel deep-sea specifications and economy-grade coastal alternatives. Nickel-alloy input volatility feeds directly into procurement calendars, compressing margins on IMO-compliant residual fuel handling systems while elevating cost-optimized plastic housing variants below 150 psi ratings.
Pricing Analysis
Distributor margins on cartridge replacement cycles absorb the steepest channel-layer compression as independent port service providers in Singapore and Rotterdam unbundle after-sales relationships from OEM-captive structures. Three-tier pricing structure across premium stainless steel, mid-grade aluminum, and economy plastic levels separates deep-sea commercial fleets from coastal fishing operators and inland waterway barges. Cost compression in standard-grade media is intensifying because REACH-compliant synthetic formulations command raw material premiums over legacy cellulose substrates. Coastal fishing fleets exhibit highest price sensitivity, prioritizing per-unit cost over extended service intervals, while Marshall Islands and Panama registry operators accept premium pricing for centrifugal-separator hybrid architectures that minimize trans-Pacific downtime.
Supply Chain Analysis
Welding certification scarcity in Yangtze River Delta manufacturing corridors constrains throughput for high-pressure marine specifications, forcing lead-time extensions on stainless steel housing orders. Production gravity centers on China, South Korea, and Japan for deep-sea commercial specifications, with German and US facilities anchoring centrifugal-separator hybrid development. Raw material flows draw from Indonesian nickel mining, South African chromium processing, and Saudi petrochemical feedstocks for synthetic media substrates. Single-source vulnerability concentrates in Asian foundry networks for cartridge filter vessels rated above 3000 psi. Distribution runs through shipyard-integrated procurement channels for newbuild contracts, while independent bunkering service firms capture replacement cartridge demand in hub ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in synthetic media formulations as REACH chemical restrictions displace legacy cellulose binders, allowing premium pricing for compliant architectures. Stainless steel input hedging and backward integration into nickel-alloy processing emerge as critical cost-down levers for deep-sea specification manufacturers.
For Market Incumbents: Anticipate centrifugal-separator hybrid displacement of single-media legacy designs by accelerating R&D investment in synthetic multi-layer matrices that capture catalytic fines across broader particle size distributions. Defensive consolidation through captive supply of nickel-alloy housings in South Korean and Chinese manufacturing corridors offsets commodity volatility exposure. Channel control via exclusive service contracts with Singapore bunkering operators protects replacement revenue streams against independent port-side competitors.
For New Entrants and Emerging Players: MARPOL Annex VI enforcement in Southeast Asian shipping lanes opens a window for rapid-turnaround cartridge exchange services unbundled from engine manufacturer warranty structures. The most penetrable segment sits in Mediterranean and Caribbean coastal marinas where recreational spin-on demand concentrates among owner-operators prioritizing maintenance simplicity. Go-to-market execution through marina service provider partnerships, bypassing traditional shipyard procurement channels, captures replacement cycles with minimal upfront capital intensity.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play filtration technology developers lacking integrated fluid systems portfolios, as diversified industrial conglomerates command OEM channel premiums. Long-term viability across the analysis window hinges on methanol and ammonia compatibility certification timelines for next-generation media formulations. Acquisition target archetypes include centrifugal-separator hybrid specialists with European-flagged vessel relationships and synthetic media developers holding REACH-compliant binder chemistries. The signal to watch is IMO type-approval acceleration for alternative fuel filtration protocols, which would trigger fleet-wide system redesign capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Alloy Processing | Captive supply of austenitic steel housings insulates margin compression from commodity volatility in South Korean shipyard supply. |
| Synthetic Media Formulation Certification | REACH-compliant binder chemistry investment unlocks premium pricing tier for European-flagged and export-bound vessel specifications. |
| Port-Side Service Network Expansion | Singapore and Rotterdam hub presence captures unbundled replacement revenue from traditional OEM-captive maintenance relationships. |
| Alternative Fuel Compatibility Development | Methanol and ammonia filtration protocol readiness positions for fleet-wide system redesign as IMO standards crystallize. |
| Centrifugal-Separator Hybrid System Launch | Extended service interval architectures penetrate deep-sea commercial segments where trans-Pacific downtime costs dominate procurement criteria. |
Research Methodology
Coverage spans East Asian manufacturing corridors, European regulatory clusters, and North American inland waterway networks, with primary inputs from each. Fleet engineering directors at Marshall Islands and Panama registry operators, procurement leads at Singapore bunkering service firms, shipyard specification engineers in Ulsan and Geoje, and aftermarket service heads at Rotterdam harbor networks provided operational data. Secondary validation drew from IMO MARPOL Annex VI enforcement documentation, EU REACH chemical registration databases, EPA marine engine tier compliance filings, and Korean Register certification standards. Bottom-up triangulation across vessel-class installation counts and top-down reconciliation against bunkering throughput data anchored volume estimates.
Rate-of-change decomposition separated newbuild specification demand from replacement cycle intensity across the projection horizon. Segmentation dimensions modeled include product architecture, material grade tier, vessel operational profile, installation type, and regional regulatory framework cluster. CAGRs derived from regression analysis against bunker fuel quality mandate implementation timelines and fleet age distribution curves. Industry-specific forecast inputs incorporated stainless steel commodity price volatility indices and alternative fuel propulsion adoption scenario modeling.
Revisions become necessary when IMO alternative fuel filtration protocol standardization accelerates, when nickel-alloy commodity markets experience sustained dislocation, or when Asian foundry concentration triggers regional supply disruptions. Forecasts reflect documented assumptions regarding MARPOL Annex VI enforcement consistency and REACH chemical restriction expansion timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Bituminous Coal Market
Fuels
Liquefied Helium Tanks Market
Fuels
North America Bunker Fuel Market
Fuels
Bunker Fuel Market
Fuels
Liquid Propellants Market
Fuels
Renewable Heating Fuels Market
Fuels
India Bunker Fuel Market
Fuels
Refuse Derived Fuel Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Global Charcoal Market
Fuels
Gasoline Market
Fuels
Canada Coal Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Fuel Grinder Market
Fuels
United States Bunker Fuel Market