
 Sweet Sorghum Ethanol Market | 2026-2036
Sweet Sorghum Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Sorghum Ethanol Market Insights
The US EPA Renewable Fuel Standard is pivoting compliance obligations toward advanced biofuel categories that favor drought-tolerant feedstocks. POET leverages its existing dry-mill infrastructure to evaluate sorghum as a rotational crop input. Valero Energy Corporation sustains multi-feedstock flexibility across its Gulf Coast refining network. Green Plains Renewable Energy anchors its pilot programs in regions where water stress limits corn cultivation.
Sweet sorghum ethanol denotes a fermentation-derived alcohol extracted from the stalk's soluble sugars and grain starch, typically yielding 300-400 gallons per acre with lower irrigation demand than corn. Its primary commercial purpose centers on transportation fuel blending and industrial solvent applications where lifecycle carbon metrics influence procurement decisions. Fuel ethanol dominates current output volumes, reflecting established offtake contracts with petroleum blenders. Biofuels applications are expanding fastest among end-use categories, driven by corporate fleet decarbonization commitments. Fermentation technology leads installed capacity, though distillation efficiency improvements are redirecting capital toward integrated sugar-to-ethanol systems.
The US EPA administers Renewable Identification Number tracking that determines feedstock eligibility for compliance credits. Brazil's ANP regulates ethanol blending mandates that extend market access to sorghum-derived supply competing with sugarcane origin. China's MIIT coordinates GB standard updates for fuel ethanol quality that affect import specifications and domestic production licensing. Stakeholders must monitor how drought-frequency projections and biofuel policy revisions reshape feedstock preference hierarchies across major producing regions.
Market Dynamics
The US EPA Renewable Fuel Standard is redirecting compliance credit eligibility toward drought-tolerant feedstocks, compressing the economic window for corn-dependent ethanol while elevating sorghum-derived supply in procurement hierarchies.
Growth Catalysts
- Advanced Biofuel Mandates:The US EPA Renewable Identification Number framework now weights drought-tolerant inputs more heavily in compliance calculations. Fuel blenders face explicit incentives to diversify beyond corn starch.
- Fleet Decarbonization Commitments:Corporate transportation operators are embedding lifecycle carbon metrics into fuel procurement specifications. Sweet sorghum ethanol delivers lower irrigation-adjusted emissions profiles.
- Brazil:Existing flex-fuel infrastructure and sugarcane ethanol processing expertise create immediate offtake pathways. ANP blending regulations accommodate sorghum-derived supply without infrastructure retrofit.
Market Restraints
- Feedstock Supply Concentration:Sweet sorghum seed genetics and agronomic expertise concentrate among a limited set of breeding programs and extension networks. Geographic concentration of viable cultivation zones limits supply elasticity.
- Processing Capital Requirements:Integrated sugar-to-ethanol distillation systems demand substantial upfront investment. Dry-mill operators face retrofit costs to handle stalk juice extraction alongside grain starch.
- Input Cost Volatility:Fertilizer and diesel prices directly affect sorghum cultivation economics. Input cost spikes compress margins faster than for established corn ethanol with deeper supply contracts.
Strategic Opportunities
- Water-Stressed Regions:Areas where irrigation constraints limit corn cultivation present first-mover expansion potential. Sorghum's lower water demand per gallon of ethanol output opens cultivation frontiers.
- Industrial Solvent Applications:Chemical manufacturers seeking renewable feedstock alternatives to petroleum-derived solvents represent underdeveloped demand. Lifecycle carbon accounting drives specification changes in coatings and pharmaceuticals.
- Technology Convergence:Precision fermentation platforms and cellulosic processing advances may unlock stalk bagasse valorization. Combined sugar-starch-biomass systems could redefine per-acre ethanol yields.
Industry Challenges
- Skill Gap in Dual-Stream Processing:Operations integrating juice extraction with grain fermentation require specialized technician training. Existing corn ethanol workforces need significant reskilling.
- Certification Timeline Compression:China's MIIT GB standard updates and Brazil's ANP feedstock registration create multi-jurisdiction compliance complexity. Producers face sequential approval bottlenecks.
- Supply Chain Reconfiguration:Harvest logistics for stalk-and-grain collection differ materially from corn grain-only systems. Equipment and transport networks require coordinated investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Sorghum Ethanol Market |
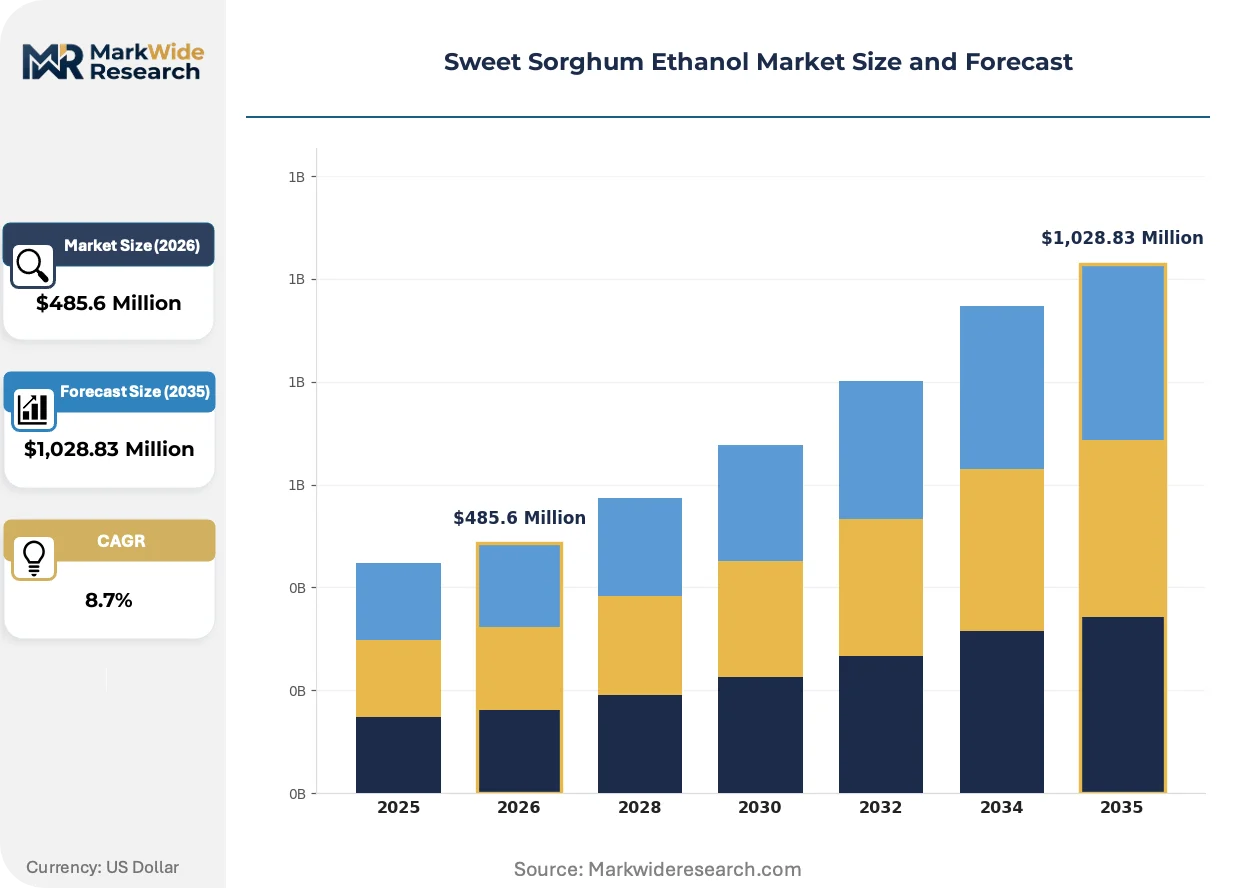
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,028.83 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Ethanol, Industrial Ethanol, Beverage Ethanol, Laboratory Ethanol End User: Automotive, Food and Beverage, Pharmaceutical, Cosmetics Technology: Fermentation, Distillation, Filtration, Concentration Application: Biofuels, Solvents, Additives, Nutraceuticals |
| Companies Covered | POET, Valero Energy Corporation, Green Plains Renewable Energy, Flint Hills Resources, Beijing Sangliang Technology Development Centre, Shrijee Group, Anchor Ethanol, LSU AgCenter, Great Valley Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Sorghum Ethanol Market Trends and Innovations
Technology diffusion and regulatory recalibration are compressing the advantage window for incumbent corn ethanol while opening structural space for drought-tolerant alternatives with superior carbon accounting credentials.
Mobile juice extraction units are decentralizing sweet sorghum processing geography. These systems enable field-side stalk pressing that reduces transport costs and preserves sugar content. Agricultural cooperatives in water-stressed US Plains states are piloting distributed collection networks. The technology is decentralizing ethanol production away from centralized dry-mill hubs toward cultivation-adjacent processing.
The US EPA Renewable Fuel Standard recalibration is tightening lifecycle carbon intensity thresholds for compliance credits. Advanced biofuel category obligations now explicitly favor feedstocks with lower irrigation and fertilizer footprints. Fuel blenders are responding by diversifying procurement contracts beyond corn-origin supply. This regulatory pivot most directly affects compliance strategy for integrated oil companies with refining network exposure.
Fuel buyers are embedding carbon intensity scores directly into procurement specifications. Long-term supply agreements now tie pricing to verified lifecycle emissions rather than commodity benchmarks. This behavioral shift compresses the competitive position of high-input feedstocks. The pattern is most visible among corporate fleet operators with public net-zero commitments and European refining networks subject to EU Green Deal compliance obligations.
Sweet Sorghum Ethanol Market Segmentation
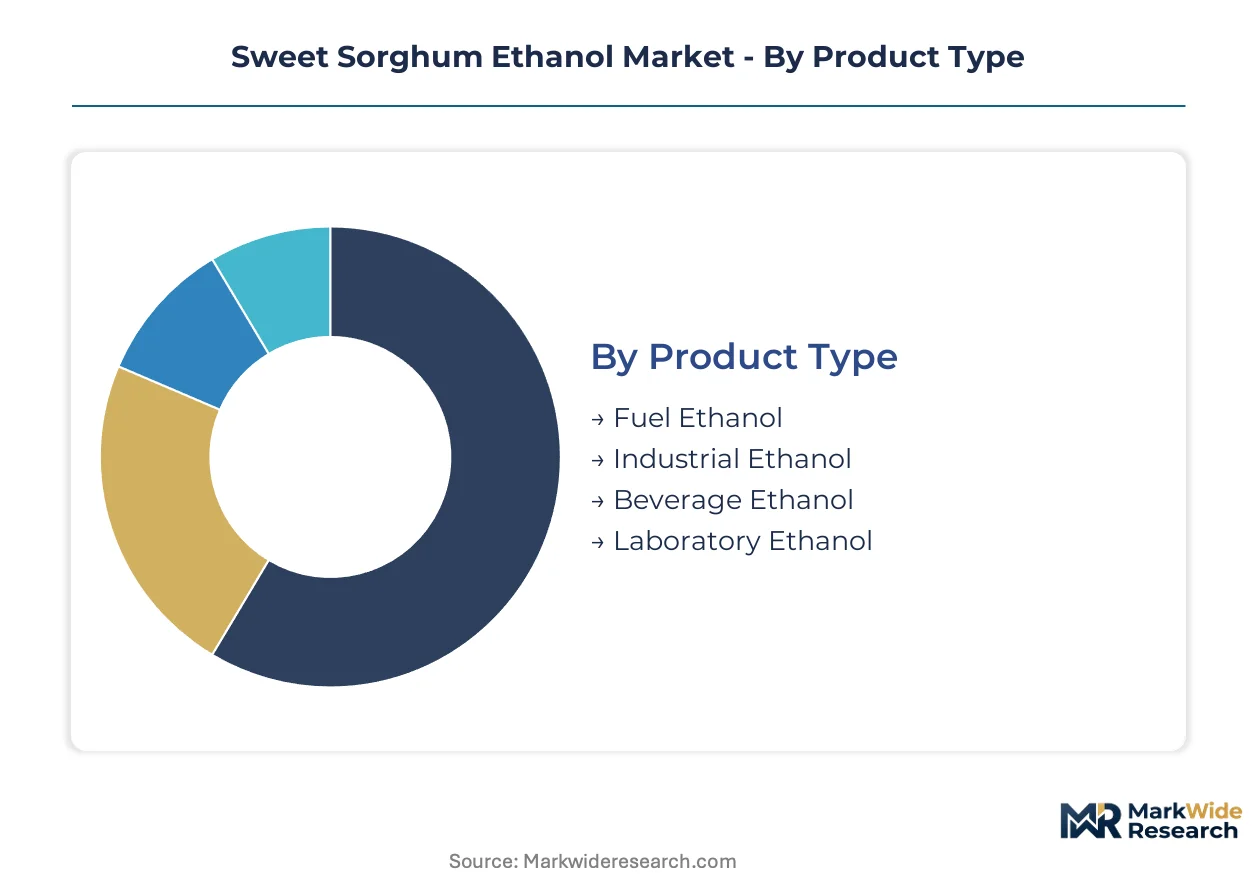
Sweet sorghum ethanol's diverse chemical properties create distinct value pools across fuel, industrial, and specialty applications. Procurement specifications vary sharply by end-use, with transportation fuel buyers prioritizing carbon intensity scores while pharmaceutical and cosmetic customers demand ultra-high purity grades.
Product Type:
Fuel ethanol commands the heaviest capital deployment, requiring integrated distillation systems and RIN-compliance infrastructure that industrial-grade processors can bypass.
- Fuel Ethanol:Hydrous or anhydrous alcohol meeting ASTM D4806 specifications for gasoline blending at E10-E85 ratios. US EPA RIN tracking and Brazil's ANP blending mandates concentrate demand in markets with explicit biofuel obligations.
- Industrial Ethanol:Denatured or undenatured grades for solvent, coating, and chemical synthesis applications. Chemical manufacturers in water-stressed US Plains states are substituting petroleum-derived solvents with lower-carbon alternatives.
- Beverage Ethanol:Neutral spirit meeting potable purity standards for distilled spirits and flavor extraction.
- Laboratory Ethanol:High-purity reagent grades for analytical and research applications.
Fuel ethanol absorbs the bulk of installed capacity; industrial ethanol is expanding most quickly.
End User:
Automotive fuel blenders represent the highest-volume customer category, though pharmaceutical and cosmetic buyers command significant price premiums for certified purity grades.
- Automotive:Flex-fuel vehicle fleets and petroleum refiners purchasing ethanol for gasoline oxygenation. Brazil's existing sugarcane ethanol infrastructure enables immediate offtake without distribution retrofit.
- Pharmaceutical:Drug manufacturers requiring USP-grade ethanol for extraction, formulation, and sterilization. Stringent purity specifications and batch documentation drive supplier qualification timelines.
- Food and Beverage:Flavor extraction, preservation, and distilled spirits production.
- Cosmetics:Personal care formulations utilizing ethanol as solvent, preservative, or astringent base.
Automotive offtake dominates volume flows; pharmaceutical procurement is climbing the fastest on value terms.
Technology:
Distillation and fermentation together determine per-gallon capital intensity, with integrated sugar-starch systems requiring substantially higher upfront investment than standalone grain processing.
- Fermentation:Yeast-mediated conversion of stalk sugars and grain starch to ethanol. Microbial strain optimization and simultaneous saccharification protocols are redirecting R&D investment toward higher-yield biocatalysts.
- Distillation:Multi-column separation systems producing fuel-grade or industrial-grade alcohol. Energy integration with adjacent refining operations improves thermal efficiency and margin capture.
- Filtration:Solid-liquid separation for juice clarification and stillage processing.
- Concentration:Evaporation systems for syrup preservation and co-product recovery.
Distillation holds the largest installed asset base; fermentation technology is gaining share fastest through yield improvements.
Application:
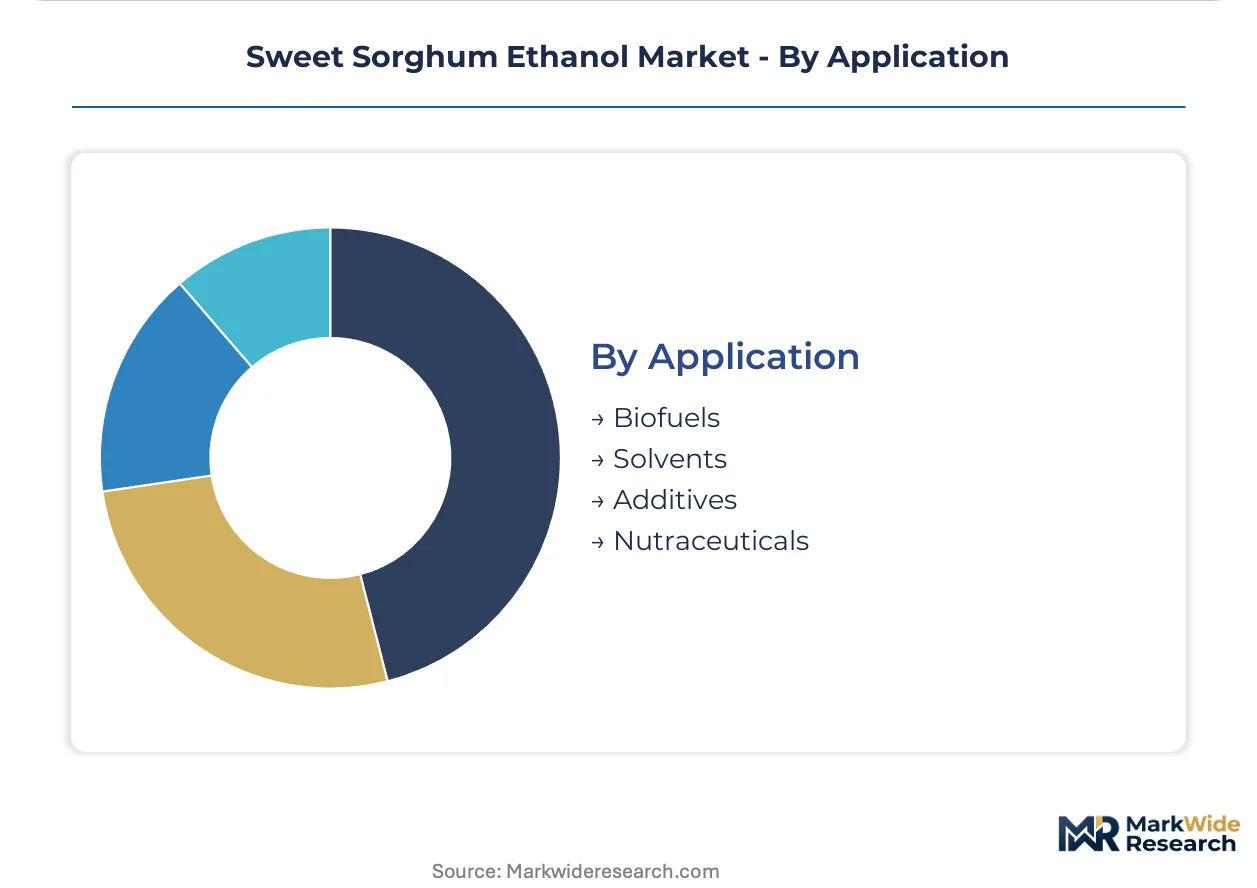
Biofuels applications concentrate procurement volume, while solvents and nutraceuticals command differentiated pricing through technical specifications and certification requirements.
- Biofuels:Transportation fuel blending and renewable diesel feedstock. Corporate fleet decarbonization commitments are embedding lifecycle carbon metrics into long-term supply agreements.
- Solvents:Industrial degreasing, coating formulation, and chemical synthesis. Coatings manufacturers seeking VOC compliance are specifying renewable ethanol in architectural and automotive paint lines.
- Additives:Fuel oxygenates, preservative systems, and chemical intermediates.
- Nutraceuticals:Botanical extraction and dietary supplement processing.
Biofuels claims the dominant share of production volume; solvent applications are expanding most rapidly in industrial end-uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs the heaviest procurement volumes through existing flex-fuel infrastructure, while the United States redirects compliance credit frameworks toward drought-tolerant feedstocks. China and India scale pilot programs in water-stressed agricultural zones.
United States
Corporate fleet decarbonization commitments embed lifecycle carbon metrics into fuel procurement specifications. The EPA Renewable Fuel Standard recalibrates Renewable Identification Number eligibility to weight drought-tolerant inputs more heavily in compliance calculations. POET evaluates sorghum as a rotational crop input across its Plains-state dry-mill network.
Brazil
Petroleum blenders source sorghum-derived supply through established sugarcane ethanol distribution channels without infrastructure retrofit. ANP blending mandates accommodate sorghum-origin ethanol within existing flex-fuel regulatory frameworks. São Paulo-state processors leverage cane-to-ethanol expertise for stalk juice extraction protocols.
China
Provincial governments in water-stressed northern regions promote sorghum cultivation to reduce irrigation demand per unit ethanol output. MIIT coordinates GB standard updates for fuel ethanol quality that affect domestic production licensing and import specifications. Shandong Peninsula pilot clusters test integrated sugar-starch processing systems.
India
State-level ethanol blending programs target 20% integration timelines that expand feedstock diversification requirements. The Ministry of Petroleum and Natural Gas advances biofuel policy frameworks favoring drought-resistant crops in rainfed agricultural zones. Maharashtra and Karnataka ethanol processors trial mobile juice extraction units for decentralized stalk processing.
Germany
Refining networks subject to EU Green Deal compliance obligations specify lower-carbon ethanol grades for gasoline oxygenation. The country's national energy regulator enforces renewable fuel quotas that create procurement incentives for irrigation-adjusted feedstocks. Industrial chemical clusters in North Rhine-Westphalia substitute petroleum-derived solvents with fermentation-based alternatives.
Sweet Sorghum Ethanol Market Competitive Landscape
United States producers anchor one tier; Brazilian and Chinese specialists hold regional procurement relationships with domestic blenders. The vendor base spans integrated oil companies with refining network exposure, agricultural cooperatives with distributed processing infrastructure, and technology developers with precision fermentation platforms. Strategic archetypes include compliance-credit optimizers, water-stress arbitrageurs, and integrated sugar-starch processors. Capacity expansion and strategic partnerships dominate competitive moves as players secure feedstock supply contracts and offtake agreements.
Within the integrated processor tier, POET and Valero Energy Corporation exemplify compliance-credit optimization through multi-feedstock flexibility. Green Plains Renewable Energy anchors the water-stress arbitrageur archetype with pilot programs in irrigation-constrained regions. Beijing Sangliang Technology Development Centre occupies a position within the technology developer cluster focused on stalk processing innovation.
| Leading Market Players |
|---|
| POET |
| Valero Energy Corporation |
| Green Plains Renewable Energy |
| Flint Hills Resources |
| Beijing Sangliang Technology Development Centre |
| Shrijee Group |
| Anchor Ethanol |
| LSU AgCenter |
| Great Valley Energy |
| Others |
Pricing and Supply Chain Analysis
EPA Renewable Identification Number eligibility criteria now gate both qualified supply access and premium-tier pricing for drought-tolerant feedstocks. Fuel blenders seeking compliance credit optimization pay structural premiums for verified low-carbon ethanol, while spot market participants face price compression from undifferentiated corn-origin supply.
Pricing Analysis
Short lead-time procurement commands 15-20% premiums as blenders rush to meet quarterly RIN obligations. Contract-based long-term offtake agreements dominate volume flows, with pricing indexed to carbon intensity scores rather than commodity benchmarks. Price differentiation stems from certification grade (ASTM D4806 compliance tier) and geographic delivery cost to Gulf Coast refining clusters. Cost compression in standard-grade supply is intensifying because fertilizer and diesel input spikes erode cultivation margins faster than for established corn ethanol. Petroleum refiners with integrated network exposure show least price sensitivity; independent fuel distributors operate on thinnest margins.
Supply Chain Analysis
Sweet sorghum seed genetics and mobile processing equipment rest on concentrated US breeding programs and Brazilian sugarcane-to-ethanol engineering expertise. Raw material dependencies include proprietary hybrid seed stocks, specialized stalk pressing machinery, and yeast biocatalyst strains optimized for simultaneous sugar-starch fermentation. Single-source vulnerability runs through the limited set of extension networks with dual-stream processing technician training. Distribution runs through established petroleum blender terminals in Brazil and rail-fed dry-mill hubs in US Plains states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sweet sorghum ethanol sector sits in a technology-transition phase as mobile juice extraction units displace centralized dry-mill processing geography. Integrated sugar-starch fermentation systems are replacing legacy grain-only infrastructure, reshaping capital deployment patterns across the value chain.
For Market Incumbents: Extend multi-feedstock flexibility through backward integration into seed breeding partnerships and distributed collection network investments. POET and Valero Energy Corporation exemplify this posture through rotational crop evaluation and Gulf Coast refining network adaptation. Defend against margin compression from input cost volatility by locking long-term fertilizer supply contracts and co-locating processing with petroleum refining operations to capture thermal efficiency gains.
For New Entrants and Emerging Players: Enter via water-stressed agricultural zones where irrigation constraints exclude corn cultivation, particularly US Plains states and northern China provinces. Target industrial solvent applications for coatings and pharmaceutical manufacturers seeking renewable feedstock alternatives with lifecycle carbon documentation. Pursue agricultural cooperative partnerships as the primary go-to-market angle, leveraging existing farmer relationships for stalk collection logistics.
For Investors and Strategic Acquirers: EPA recalibration of advanced biofuel category obligations is the leading indicator that drought-tolerant feedstock processors will capture structural compliance credit premiums over the next decade. Acquisition candidates include technology developers with precision fermentation platforms and mobile extraction unit engineering capabilities. Watch for sequential approval bottlenecks in China's MIIT GB standard updates and Brazil's ANP feedstock registration as signals of supply constraint inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Juice Extraction Deployment | Decentralizes processing geography toward cultivation-adjacent sites in water-stressed US Plains states. |
| Backward Integration into Seed Genetics | Captures proprietary hybrid development for yield optimization and drought tolerance trait stacking. |
| Long-term Supply Agreement with Petroleum Blenders | Locks offtake volume for integrated oil companies seeking RIN compliance credit diversification. |
| Joint Venture for Dual-Stream Processing | Combines cane-to-ethanol expertise from Brazil with US grain fermentation infrastructure. |
| Green Certification Program for Carbon Intensity | Enables premium pricing to EU refining networks subject to Green Deal compliance obligations. |
Research Methodology
Multi-period observation of EPA RIN credit pricing, ANP blending mandate revisions, and drought-frequency projections anchored the trend analysis, supplemented by interviews with ethanol plant operations managers, petroleum blender procurement leads, agricultural cooperative extension agents, and yeast biocatalyst R&D directors. Secondary validation drew from EPA regulatory filings, Brazil ANP resolution updates, China MIIT GB standard documentation, and customs trade data for ethanol import flows. Bottom-up capacity installation tracking and top-down fuel demand modeling provided cross-verification.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework across the projection horizon. Fuel ethanol, industrial ethanol, beverage ethanol, and laboratory ethanol grades received distinct volume and value treatment. Automotive, pharmaceutical, food and beverage, and cosmetics end-use categories carried differential growth assumptions. Fermentation, distillation, filtration, and concentration technology shares were modeled separately. CAGRs were derived from regression analysis against feedstock cost trajectories and regulatory obligation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt biofuel policy reversals or extreme drought frequency scenarios. Assumptions include sustained EPA advanced biofuel category obligations and gradual MIIT standard harmonization. A small set of named triggers—ANP feedstock registration timeline compression, mobile extraction unit reliability data, and EU carbon border adjustment implementation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Advanced Biofuel Market
Biofuels
Biodiesel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Latin America Biodiesel Market
Biofuels
Biofuels Market
Biofuels
Second Generation Biofuels Market
Biofuels
Bioethanol Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Europe Biofuel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Brazil Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Europe Biodiesel Market
Biofuels
Rotating Machines for Biofuels Market