
 Fuel Conditioning System Market | 2026-2036
Fuel Conditioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Conditioning System Market Analytics
Advanced polymer membrane filtration is expanding its role in marine fuel-water separation, displacing legacy coalescer elements that carry higher replacement costs and disposal liabilities. Parker Hannifin Corporation leverages its aerospace filtration heritage to dominate naval and commercial marine specifications. Donaldson Company, Inc. sustains competitive positioning through backward integration into filter media manufacturing. Alfa Laval anchors its presence in the large two-stroke engine segment with centrifugal separator systems that handle residual fuel viscosities exceeding 700 cSt at 50°C.
A fuel conditioning system comprises integrated mechanical, thermal, and chemical treatment modules designed to purify, heat, filter, and stabilize hydrocarbon fuels prior to injection into combustion equipment, typically achieving particle removal down to 10 microns and water separation below 200 ppm. Filtration systems occupy the largest product category due to mandatory pre-engine protection requirements, while heating systems command premium pricing in cold-climate and high-viscosity residual fuel applications. Mechanical filtration leads technology adoption in road transport and industrial power generation, whereas chemical treatment is displacing thermal methods in aviation where weight reduction and fuel system compatibility are critical.
EPA marine diesel engine standards and IMO MARPOL Annex VI fuel sulfur regulations directly shape product specifications, forcing engine builders to specify conditioning systems capable of handling multiple fuel grades and sulfur levels. The EU F-Gas Regulation and REACH chemical restrictions further constrain refrigerant and additive chemistries used in thermal conditioning modules. Stakeholders must monitor evolving bunker fuel quality variance at key ports and assess whether biological treatment technologies can achieve commercial scale for long-term fuel storage applications.
Market Dynamics
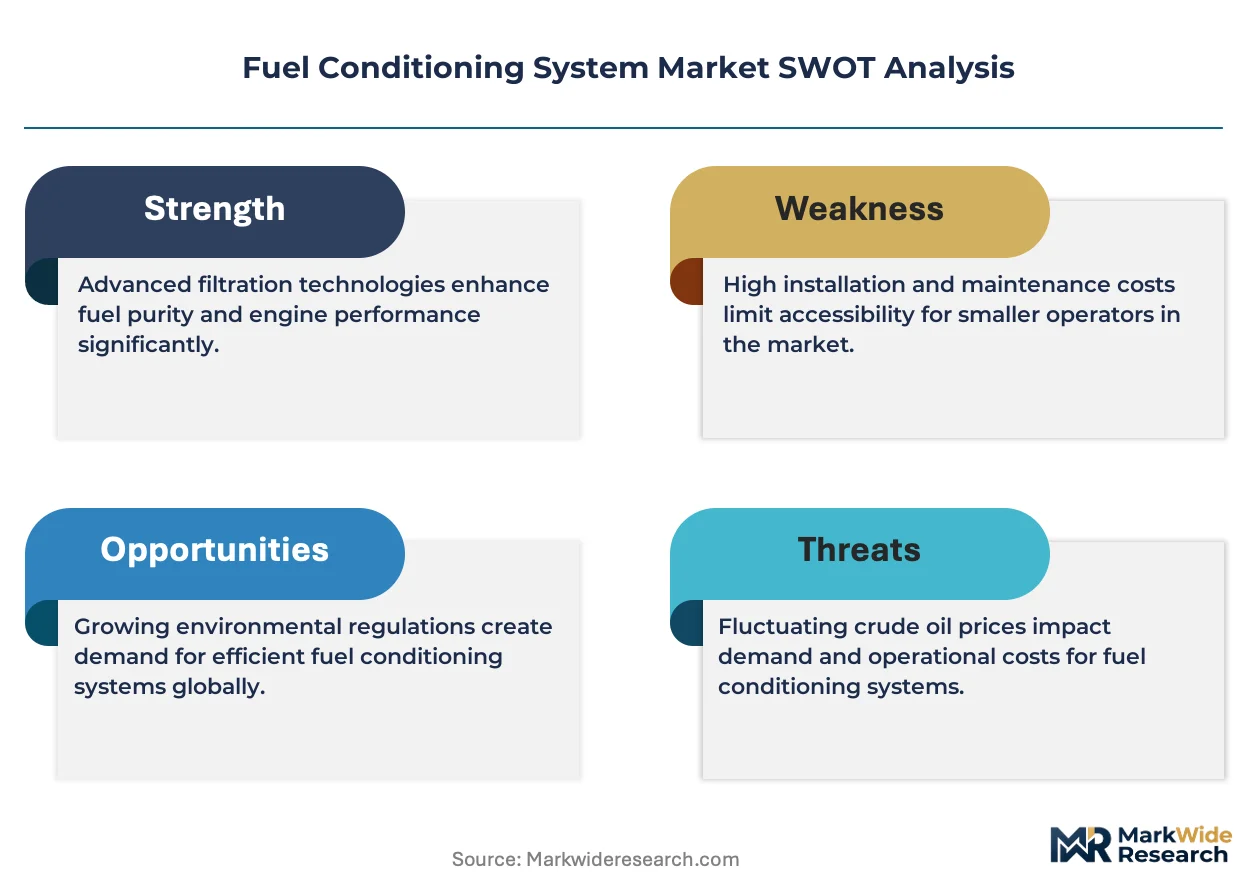
Marine engine OEMs are forcing a platform-level integration of fuel conditioning hardware into factory-delivered propulsion systems, compressing the addressable market for standalone aftermarket suppliers and privileging vendors with captive engine relationships.
Growth Catalysts
- IMO 2020 Sulfur Compliance:Shipping operators must install conditioning systems capable of handling multiple bunker fuel grades, creating mandatory replacement cycles across existing fleets.
- Residual Fuel Viscosity Handling:Two-stroke marine engines burning high-viscosity fuels exceeding 700 cSt require thermal conditioning modules that preheat fuel prior to injection.
- German Shipyard Specifications:Hamburg and Bremen-based yards specify factory-integrated fuel treatment skids for newbuild contracts, pulling demand toward packaged system suppliers.
Market Restraints
- Stainless Steel Input Volatility:Centrifugal separator bowls and filtration housings rely on austenitic grades whose price swings compress fabricator margins unpredictably.
- Filter Media Supply Concentration:Advanced polymer membrane substrates for coalescer elements concentrate among Japanese and German specialty chemical suppliers.
- EU F-Gas Refrigerant Constraints:Thermal conditioning modules using vapor-compression heating face reformulation costs as hydrofluorocarbon refrigerants phase down under European climate regulations.
Strategic Opportunities
- Aviation Chemical Treatment:Weight-sensitive turboprop and regional jet operators present demand for additive-based fuel stabilization that eliminates thermal conditioning hardware entirely.
- Long-Term Storage Biological Treatment:Backup power and military strategic reserves require microbial contamination suppression technologies not yet scaled for commercial fuel depot applications.
- South Korean Shipyard Integration:Ulsan and Geoje construction complexes offer pathways for conditioning system vendors to embed into Hyundai Heavy and Samsung Heavy supply chains.
Industry Challenges
- Marine Certification Timelines:Lloyd's Register and DNV type-approval processes for new filtration media extend 18-24 months, delaying product launches.
- Legacy Separator Retrofit Compatibility:Existing Alfa Laval and Westfalia centrifugal installations use proprietary control architectures that resist third-party automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Conditioning System Market |
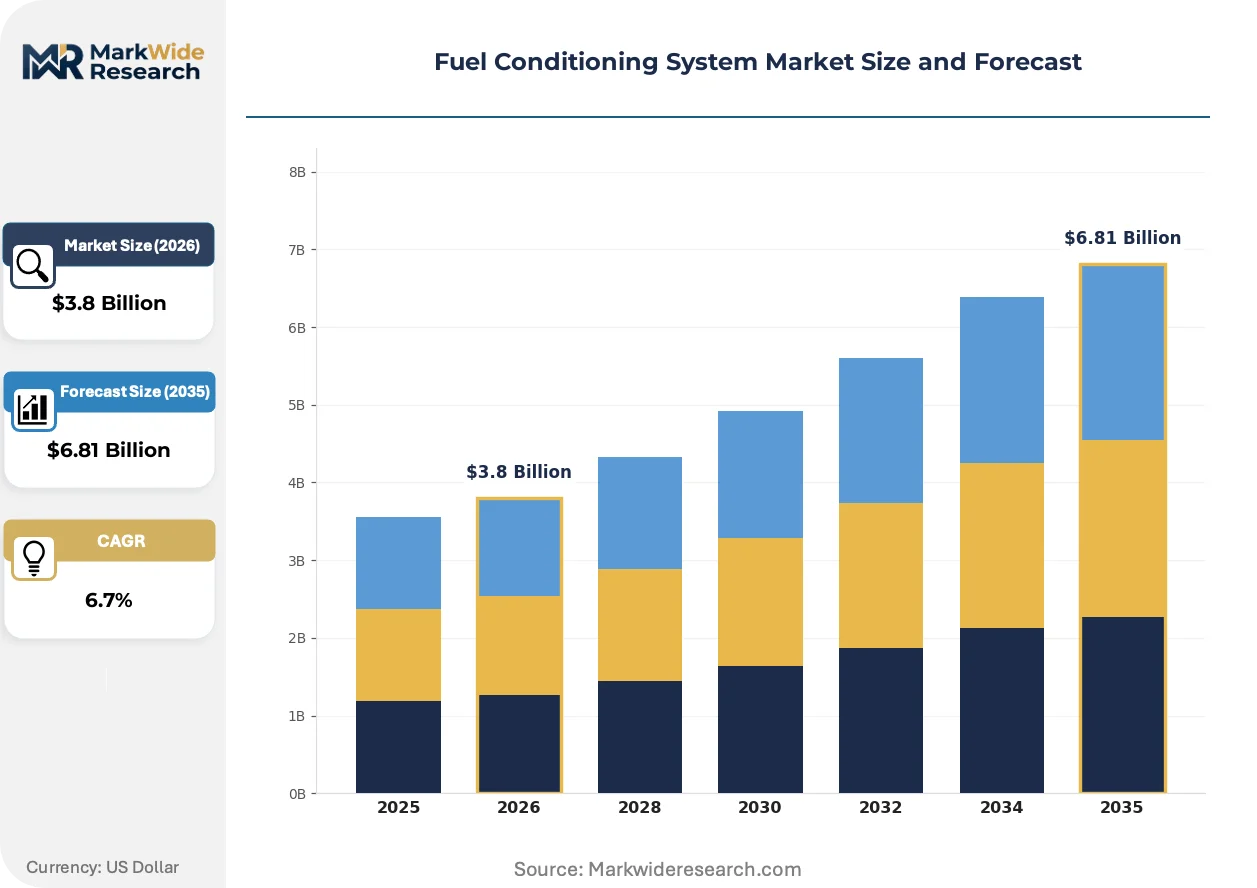
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Additive Systems, Heating Systems, Pumping Systems Application: Marine, Aviation, Road Transport, Industrial End User: Automotive OEMs, Fleet Operators, Logistics Companies, Refineries Technology: Thermal Conditioning, Chemical Treatment, Mechanical Filtration, Biological Treatment |
| Companies Covered | Parker Hannifin Corporation, Donaldson Company, Inc., Alfa Laval, Cummins Inc., Multitex Group, Integrated Flow Solutions, Chromalox, GENERON, Gaumer Process, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Conditioning System Market Evolving Landscape
Electrification of auxiliary systems and digitization of fuel quality monitoring are compressing the traditional separation-heating-filtration sequence into unified smart skids with predictive maintenance capabilities.
Advanced polymer membrane filtration is consolidating its position in marine fuel-water separation by eliminating coalescer element replacement cycles and hazardous waste disposal liabilities. Container shipping lines operating on tight port turnaround schedules favor membrane systems for their extended service intervals. The technology is consolidating supplier margins around media replacement rather than capital equipment sales.
EPA marine diesel engine standards and IMO MARPOL Annex VI fuel sulfur regulations are forcing engine builders to specify conditioning systems with multi-fuel capability across residual and distillate grades. Equipment suppliers must validate performance across sulfur ranges from 0.1% to 3.5% without hardware reconfiguration. The heaviest compliance burden falls on retrofit installations in US-flagged vessels operating in Emission Control Areas.
Ship operators are unbundling after-sales service contracts from original equipment purchases, selecting third-party maintenance providers based on port coverage density rather than manufacturer affiliation. Independent service networks in Singapore, Rotterdam, and Houston are capturing routine filter change-out and separator bowl overhaul work. This shift is most pronounced among Greek and German tanker operators with globally dispersed fleets.
Fuel Conditioning System Market Segmentation
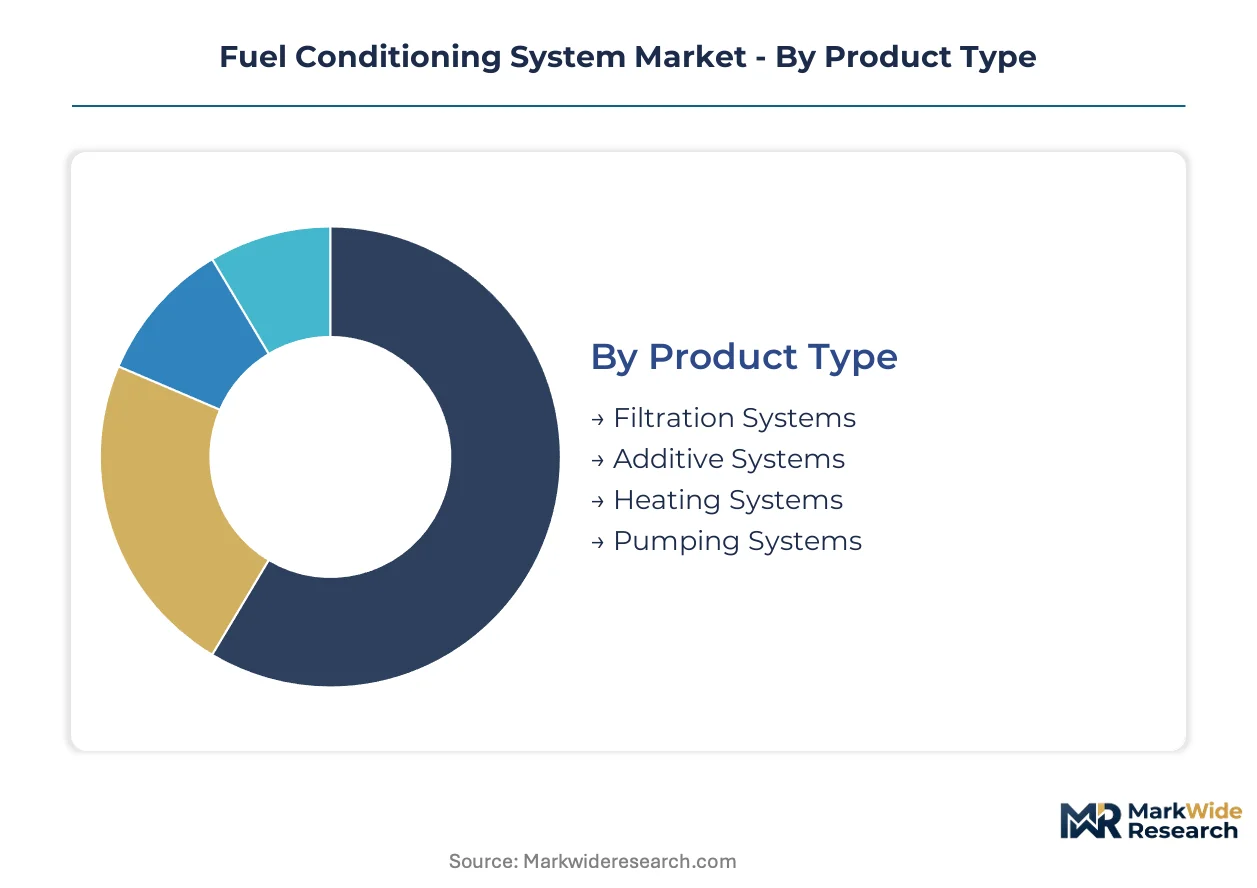
Segmentation reveals how capital deployment and regulatory pressure concentrate across hardware modules, end-use environments, and treatment methodologies. Equipment suppliers configure their manufacturing footprints and service networks around these divisions.
Product Type:
Capital intensity varies sharply across hardware categories, with thermal modules requiring pressure-vessel fabrication and precision control systems that filtration skids do not.
- Filtration Systems:Mechanical and membrane-based separators remove particulates and water to protect injection equipment. Marine operators in Germany and South Korea specify these as mandatory pre-engine protection, driven by OEM warranty requirements and port-state control inspections.
- Heating Systems:Thermal conditioning modules preheat high-viscosity residual fuels using steam, electric, or vapor-compression methods. Cold-climate ports and two-stroke engine installations absorb the bulk of demand, constrained by EU F-Gas refrigerant phase-down costs.
- Additive Systems:Dosing equipment injects stabilizers, biocides, and combustion improvers. Refinery and aviation end-users favor these for weight reduction versus thermal hardware.
- Pumping Systems:Fuel transfer and circulation pumps integrate with conditioning skids. Fleet operators specify these for road transport and backup power applications.
Filtration systems absorb the bulk of installed capacity; heating systems are expanding most quickly in high-viscosity marine applications.
Application:
Application segmentation tracks how sulfur regulations and fuel quality variance create divergent equipment specifications across mobility modes.
- Marine:Deep-sea and coastal vessels require multi-fuel conditioning to switch between residual and distillate grades. IMO MARPOL Annex VI compliance mandates hardware capable of handling sulfur ranges from 0.1% to 3.5% without reconfiguration.
- Aviation:Turboprop and regional jet operators prioritize weight reduction, favoring chemical treatment over thermal conditioning. FAA fuel system compatibility standards shape additive selection and dosing precision requirements.
- Road Transport:Heavy-duty trucks and buses use compact filtration and heating modules. Fleet operators in the United States specify these for cold-start reliability and EPA diesel engine protection.
- Industrial:Power generation and backup systems require biological contamination suppression for long-term fuel storage. This segment trails commercial scale but presents strategic reserve opportunities.
Marine applications command the largest equipment spend; aviation chemical treatment is gaining share fastest as operators shed thermal hardware weight.
End User:
End-user categories reflect procurement authority and lifecycle cost accountability across the fuel supply chain.
- Automotive OEMs:Factory-integrated conditioning packages specified for newbuild engines and vehicles. Engine builders in Germany and South Korea compress aftermarket addressability through platform-level integration.
- Fleet Operators:Road transport and aviation fleets managing total cost of ownership across multiple assets. These buyers unbundle service contracts from equipment purchases, selecting third-party maintenance based on port and depot coverage density.
- Logistics Companies:Third-party transport providers with dispersed geographic footprints. Greek and German tanker operators exemplify this segment's shift toward independent service networks in Singapore, Rotterdam, and Houston.
- Refineries:Fuel production and terminal facilities requiring conditioning for product quality assurance and custody transfer. These buyers emphasize throughput capacity and automation integration.
Automotive OEMs absorb the bulk of factory-integrated capacity; fleet operators are expanding most quickly as they consolidate procurement across globally dispersed assets.
Technology:
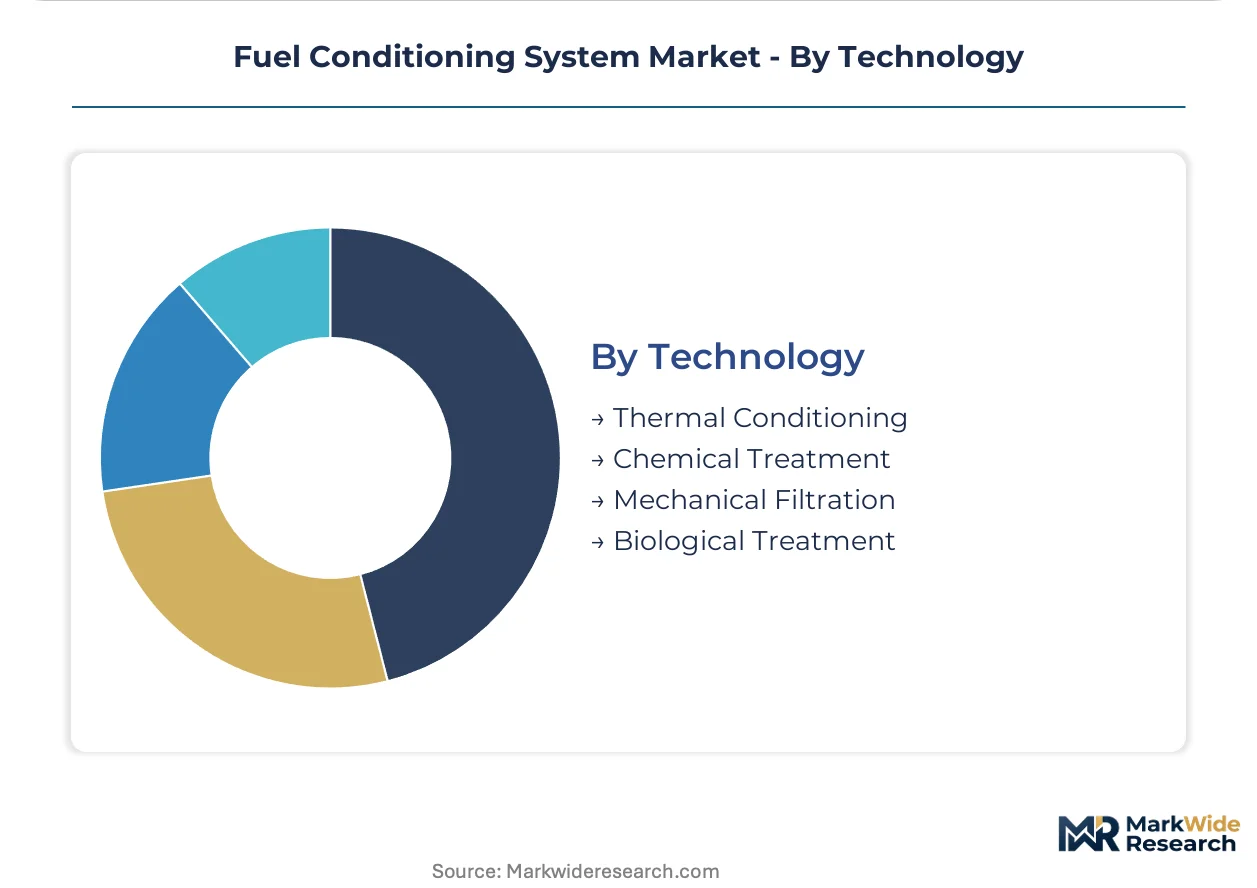
Technology segmentation tracks displacement dynamics as advanced methods challenge legacy thermal and mechanical approaches.
- Thermal Conditioning:Vapor-compression and steam-based heating for high-viscosity fuel handling. EU F-Gas refrigerant constraints force reformulation investments that compress fabricator margins.
- Chemical Treatment:Additive-based stabilization eliminating thermal hardware in weight-sensitive applications. Aviation operators drive adoption as regional jet specifications prioritize fuel system compatibility.
- Mechanical Filtration:Centrifugal separators and coalescer elements for particulate and water removal. Alfa Laval and Westfalia legacy installations resist third-party automation upgrades due to proprietary control architectures.
- Biological Treatment:Microbial contamination suppression for long-term fuel storage. Military strategic reserves and backup power applications pilot these technologies before commercial depot scale.
Mechanical filtration retains the bulk of installed base; chemical treatment is expanding most quickly in aviation and additive-dominant specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in South Korea and Germany's port industrial districts concentrate manufacturing capacity and drive specification authority for marine fuel conditioning systems.
Germany
Hamburg and Bremen shipyards mandate factory-integrated fuel treatment skids for newbuild contracts, pulling demand toward packaged system suppliers. The EU F-Gas Regulation constrains refrigerant chemistries in thermal conditioning modules, forcing reformulation investments. Engine OEMs in Bavaria and Lower Saxony compress aftermarket addressability through platform-level integration of conditioning hardware.
South Korea
Ulsan and Geoje shipyard complexes generate demand for conditioning systems embedded into Hyundai Heavy and Samsung Heavy supply chains. The country's national maritime regulator enforces IMO MARPOL Annex VI compliance timelines that accelerate fleet retrofit cycles. Busan port infrastructure supports independent service networks capturing routine maintenance work from Greek and German tanker operators.
United States
EPA marine diesel engine standards and Emission Control Area requirements force hardware capable of handling sulfur ranges from 0.1% to 3.5% without reconfiguration. Houston and Los Angeles/Long Beach port clusters anchor independent service networks unbundling after-sales contracts from original equipment purchases. Gulf Coast fabricators face stainless steel input volatility compressing margins on centrifugal separator bowls.
Japan
Advanced polymer membrane substrates for coalescer elements concentrate among Japanese specialty chemical suppliers, creating supply-side concentration. METI industrial standards shape filtration media specifications for naval and commercial marine applications. Yokohama and Nagoya industrial corridors host filter media manufacturing clusters serving regional shipbuilding demand.
Singapore
The Port of Singapore's bunker fuel quality variance creates demand for multi-fuel conditioning systems capable of rapid grade switching. The Maritime and Port Authority enforces port-state control inspections that drive pre-engine protection specifications. Independent service networks headquartered in Singapore capture routine filter change-out work from globally dispersed tanker fleets.
Fuel Conditioning System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with marine OEM relationships concentrating authority among integrated system suppliers. The vendor base organizes around three archetypes: diversified filtration conglomerates with aerospace heritage, centrifugal separation specialists with legacy maritime installations, and regional fabricators serving aftermarket retrofit demand. Competitive moves center on backward integration into filter media manufacturing and embedding into engine OEM factory-delivered platforms.
Among filtration-focused conglomerates, Parker Hannifin Corporation and Donaldson Company, Inc. exemplify archetypes built on media manufacturing control and distribution density. Alfa Laval occupies a distinct position representing centrifugal separation heritage in large two-stroke engine specifications. These three anchors illustrate how competitive positioning diverges between membrane filtration technology paths and legacy mechanical separation approaches.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Donaldson Company, Inc. |
| Alfa Laval |
| Cummins Inc. |
| Multitex Group |
| Integrated Flow Solutions |
| Chromalox |
| GENERON |
| Gaumer Process |
| Others |
Value Network & Pricing Analysis
Austenitic stainless steel price volatility propagates from specialty alloy mills through centrifugal separator bowl fabricators to marine OEM procurement desks, compressing margins unpredictably across thermal conditioning module tiers.
Pricing Analysis
Short lead-time premiums for IMO MARPOL Annex VI-compliant filtration skids command pricing premiums against standard delivery schedules. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's Register-certified systems from port-state control baseline configurations. Cost compression in standard-tier thermal modules is intensifying because EU F-Gas refrigerant reformulation expenses concentrate among smaller fabricators. Fleet operators in Greece and Germany exhibit highest price sensitivity, while German and South Korean shipyards absorb premium positioning for factory-integrated packages.
Supply Chain Analysis
Refurbishment flows for Alfa Laval and Westfalia centrifugal separator bowls create reverse logistics channels from Singapore and Rotterdam service depots back to European remanufacturing centers. Advanced polymer membrane substrates concentrate among Japanese and German specialty chemical suppliers, while austenitic stainless steel draws from German and South Korean mills. Single-source vulnerability in coalescer element media creates supply chain risk. Distribution runs through engine OEM captive channels and independent port-based service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer membrane filtration is displacing legacy coalescer technology across marine fuel-water separation, compressing replacement revenue cycles and reshaping supplier economics.
For Market Incumbents: Deepen backward integration into filter media manufacturing to defend against Japanese and German substrate supplier concentration. Secure captive supply of advanced polymer membranes before specialty chemical suppliers extract margin through input pricing power. Invest in Lloyd's Register and DNV certification pipelines to extend type-approval timelines as competitive moats against faster-moving membrane entrants. For New Entrants and Emerging Players: Launch via independent service network partnerships in Singapore, Rotterdam, and Houston to capture filter change-out and separator bowl overhaul work unbundled from OEM contracts. Target biological treatment for long-term fuel storage applications in military strategic reserves and backup power installations, where commercial scale remains unproven. Pursue additive-based chemical treatment specifications for regional aviation operators prioritizing weight reduction over thermal hardware. For Investors and Strategic Acquirers: Hyundai Heavy and Samsung Heavy supply chain embedding announcements are the leading indicator that South Korean shipyard integration will consolidate conditioning system procurement authority. Position for five-to-ten year viability around membrane filtration technology trajectories rather than legacy centrifugal separation installed bases. Monitor EU F-Gas refrigerant phase-down enforcement intensity as signal for thermal module fabricator margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media Manufacturing | Donaldson's captive substrate production insulates margin from Japanese specialty chemical supplier pricing power. |
| IMO MARPOL Annex VI Certification Investment | Lloyd's Register type-approval creates 18-24 month competitive moats against faster membrane technology entrants. |
| South Korean Shipyard Supply Chain Embedding | Ulsan and Geoje complex integration captures Hyundai Heavy and Samsung Heavy factory-delivered platform demand. |
| Independent Service Network Expansion | Singapore and Rotterdam port coverage density captures unbundled after-sales work from Greek tanker operators. |
| Aviation Chemical Treatment Platform Development | FAA fuel system compatibility standards position additive dosing for regional jet weight reduction specifications. |
Research Methodology
Multi-period observation of bunker fuel sulfur variance at Rotterdam, Singapore, and Houston ports anchored the trend analysis, supplemented by interviews with marine chief engineers, shipyard procurement managers, filtration system technical directors, and port-state control inspectors. Secondary validation drew from Lloyd's Register type-approval databases, DNV maritime standards filings, EPA marine diesel engine compliance records, and IMO MARPOL Annex VI implementation reports. Bottom-up equipment shipment tracking and top-down fuel consumption modeling provided triangulation across value chain estimates.
Input-output matrices mapped filtration system, thermal module, and additive equipment flows across marine, aviation, road transport, and industrial end-use segments. Segmentation dimensions modeled include product hardware category, treatment technology methodology, application environment, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and newbuild specification trends. Forecast inputs incorporated stainless steel price indices, refrigerant phase-down timelines, and shipyard orderbook concentrations.
Stainless steel commodity swings, EU F-Gas refrigerant enforcement delays, and biological treatment technology scale-up failures are the dominant revision risks to projection trajectories. Practitioners should monitor bunker fuel quality variance reports, port-state control detention rates, and membrane filtration field failure frequencies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Coal Trading Market
Fuels
Global Gas Treatment Market
Fuels
Solid Recovered Fuel Market
Fuels
North America Bunker Fuel Market
Fuels
China LNG Market
Fuels
Gas Pooling Mechanism Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Bunker Fuel Market
Fuels
India Coal Market
Fuels
Hybrid Propellants Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
CNG Dispenser Market
Fuels
Heavy Fuel Oil Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Gas to Liquid (GTL) Market