
 Ethyl Tertiary Butyl Ether Market | 2026-2036
Ethyl Tertiary Butyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Tertiary Butyl Ether Market Analysis
A shift from single-source to multi-source feedstock procurement is hardening among ETBE producers seeking supply security. LyondellBasell Industries Holdings B.V. leverages its integrated refinery-petrochemical complexes across the US Gulf Coast to secure captive ethanol streams. TotalEnergies SE anchors its European ETBE position through bioethanol partnerships in France and Belgium. Braskem competes in Latin America with sugarcane-derived ethanol feedstock advantages.
Ethyl tertiary butyl ether is an oxygenated fuel additive produced by acid-catalyzed etherification of isobutylene with ethanol, typically blended at 2-15% volume in gasoline to raise octane ratings and reduce carbon monoxide emissions. Its primary industrial purpose centers on enabling refiners to meet reformulated gasoline specifications while incorporating renewable ethanol content into the fuel pool. Fuel additives represent the mature revenue base, while octane boosters capture expanding margin pools as refiners face aromatics restrictions. Chemical intermediates constitute the fastest-growing application segment, driven by specialty ether demand in pharmaceutical and agrochemical synthesis.
The US Environmental Protection Agency enforces renewable fuel volume obligations under the Renewable Fuel Standard that directly shape ETBE blending economics and compliance credit values. The European Chemicals Agency applies REACH registration requirements and classification rules that govern ETBE import specifications and hazard communication protocols. California's Air Resources Board operates the Low Carbon Fuel Standard, creating differentiated demand for lower-carbon-intensity ETBE pathways. Stakeholders must monitor evolving biofuel mandate trajectories and carbon accounting methodologies to position feedstock sourcing and product certification strategies.
Market Dynamics
The Ethyl Tertiary Butyl Ether Market pivots on tightening aromatics restrictions in gasoline formulations, forcing refiners toward oxygenate additives that deliver octane without benzene-toluene-xylene content. This structural pressure reconfigures feedstock sourcing priorities and blending infrastructure investments across fuel supply chains.
Growth Catalysts
- EU Renewable Energy Directive:Biofuel mandates in member states create compliance-driven demand for ETBE as a renewable-ethanol-carrying oxygenate, expanding refinery blending requirements.
- Gasoline pool octane specifications:Rising compression ratios in internal combustion engines require higher-octane fuels, positioning ETBE as a cost-effective blending component versus alkylate or reformate.
- China:Provincial biofuel pilot programs in Shandong and Guangdong accelerate ethanol-to-ETBE conversion facility construction.
Market Restraints
- Isobutylene supply concentration:Steam cracker and refinery FCC unit outputs in the US Gulf Coast and Middle East dominate merchant isobutylene availability, creating feedstock security vulnerabilities for distant ETBE producers.
- Ethanol price volatility:Corn and sugarcane commodity swings transmit directly to ETBE production economics, compressing margin predictability for non-integrated operators.
- Electric vehicle penetration:Battery electric powertrain adoption in passenger segments threatens long-term gasoline demand elasticity in European and Chinese urban markets.
Strategic Opportunities
- Indonesia:The national biodiesel program expansion creates regulatory precedent for oxygenate mandates, with ethanol import infrastructure scaling to support ETBE adoption.
- Pharmaceutical ether synthesis:High-purity ETBE grades for active pharmaceutical ingredient extraction represent an emerging application with pricing premiums over fuel-grade product.
- Carbon intensity accounting:California's Low Carbon Fuel Standard credit mechanisms reward lower-carbon ETBE pathways, incentivizing sugarcane-ethanol feedstock sourcing.
Industry Challenges
- REACH registration compliance:European Chemicals Agency substance data requirements impose documentation burdens and testing costs for ETBE importers seeking EU market access.
- Blending infrastructure retrofit:Existing gasoline storage and distribution systems require material compatibility verification and seal replacement for elevated ETBE concentrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Tertiary Butyl Ether Market |
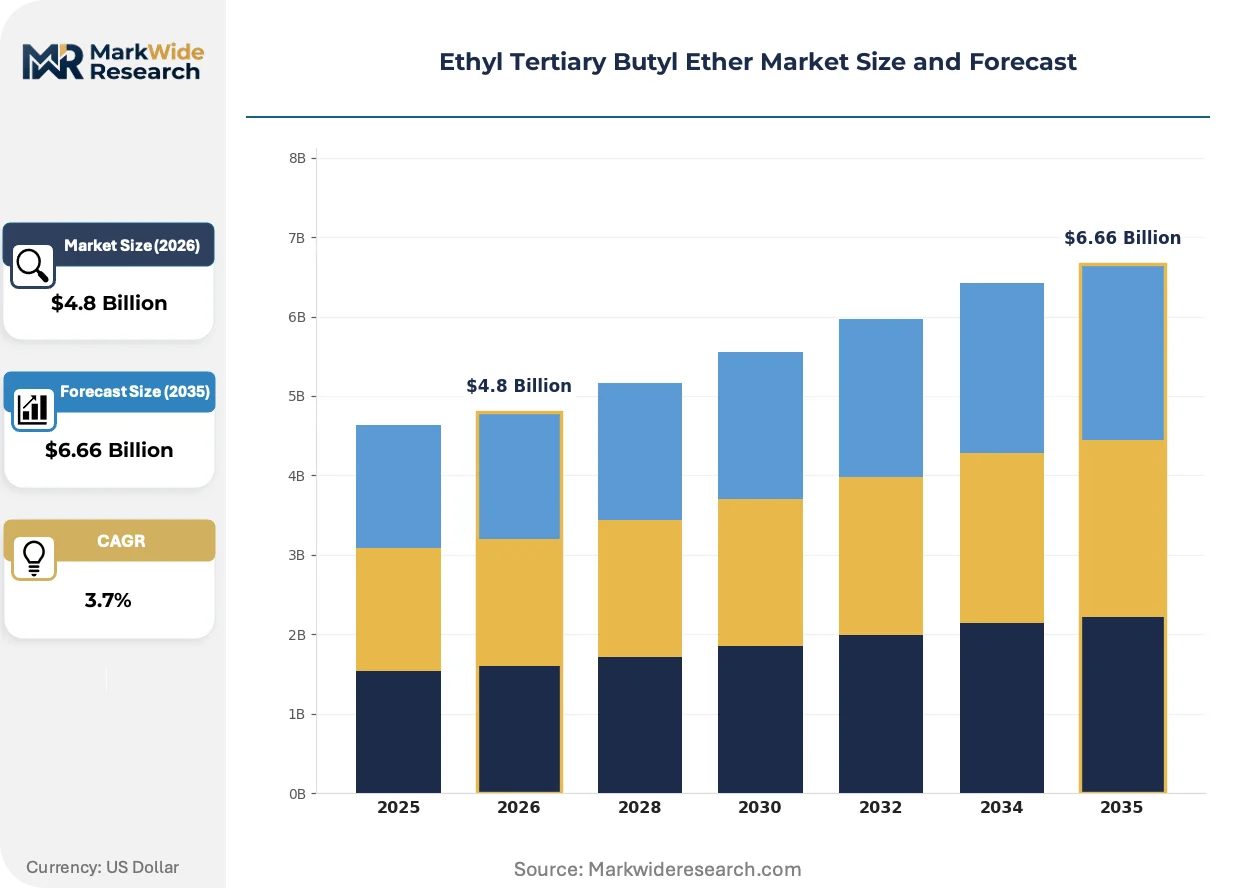
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Additives, Solvents, Octane Boosters, Chemical Intermediates Application: Automotive Fuels, Industrial Solvents, Paints, Coatings Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors End User: Oil Companies, Chemical Manufacturers, Automotive OEMs, Construction Firms |
| Companies Covered | LyondellBasell Industries Holdings B.V., TotalEnergies SE, Braskem, Eni S.p.A., Neste, SABIC, ExxonMobil Corporation, Repsol S.A., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Tertiary Butyl Ether Market Emerging Trajectories
Process intensification and carbon accounting methodologies are restructuring how ETBE producers engineer etherification reactions and validate feedstock provenance. These shifts compress capital deployment timelines while raising certification complexity.
Reactive distillation technology is consolidating conventional two-step etherification processes into single-unit operations. LyondellBasell and TotalEnergies have retrofitted existing MTBE units with ethanol-compatible catalyst systems and modified separation trains. This hardware convergence reduces steam consumption and capital intensity for refiners pivoting from methanol-based to ethanol-based oxygenate production.
REACH classification updates from the European Chemicals Agency are tightening hazard communication requirements for ETBE transport and handling. The 2023 harmonized classification for flammability and aspiration toxicity triggers downstream labeling obligations and safety data sheet revisions. Fuel distributors in Germany and France are accelerating staff training programs and depot equipment upgrades to maintain regulatory compliance.
Refinery procurement teams are consolidating oxygenate supplier relationships from multi-source spot purchasing toward long-term offtake agreements with certified low-carbon producers. This contractual shift displaces merchant market liquidity in favor of vertically integrated ethanol-ETBE chains. The pattern is most pronounced in California, where Low Carbon Fuel Standard credit banking incentives reward supply security over price optimization.
Ethyl Tertiary Butyl Ether Market Segmentation
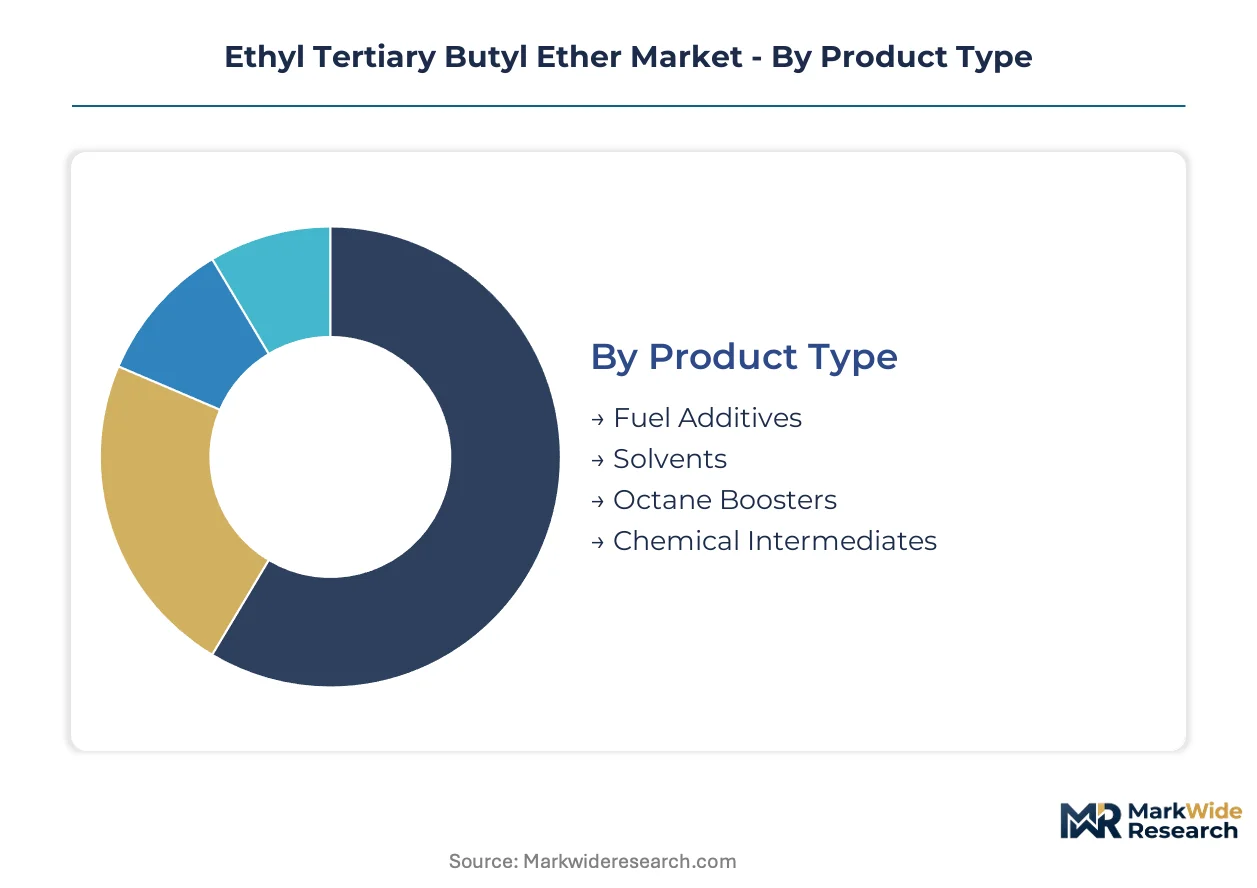
ETBE market segmentation reflects divergent purity specifications and supply chain configurations across fuel versus non-fuel applications. Refiners, chemical processors, and automotive formulators each impose distinct certification requirements that reshape producer priorities and margin structures.
Product Type:
Upgrade cycles in refinery oxygenate systems and specialty chemical synthesis are redefining which ETBE grades command premium positioning.
- Fuel Additives:Standard-grade ETBE blended at 2-15% volume in reformulated gasoline to meet octane specifications and renewable content mandates. Refiners in China, India, and Indonesia are expanding dedicated ETBE storage and blending infrastructure to comply with provincial biofuel pilots.
- Chemical Intermediates:High-purity grades for pharmaceutical extraction and agrochemical synthesis carry specification premiums over fuel-grade material. Demand concentrates in European and North American specialty chemical hubs where REACH registration and FDA pharmaceutical-grade certifications create supply scarcity.
- Solvents:Technical-grade ETBE serves as a medium-boiling-point solvent in industrial cleaning and coating applications.
- Octane Boosters:Concentrated ETBE formulations enable refiners to upgrade sub-par gasoline pools without aromatics expansion.
Fuel Additives sits at the top of the volume ranking, with Chemical Intermediates climbing the fastest.
Application:
Cost-tier differentiation separates commodity fuel blending from specification-intensive industrial uses.
- Automotive Fuels:Oxygenate blending for gasoline pool octane enhancement and emissions reduction represents the foundational demand base. California's Low Carbon Fuel Standard and EU Renewable Energy Directive compliance obligations anchor procurement volumes.
- Industrial Solvents:ETBE replaces traditional hydrocarbon solvents in metal degreasing and precision cleaning where moderate polarity and controlled evaporation rates improve process efficiency.
- Paints:Coating formulators incorporate ETBE as a co-solvent to adjust viscosity and drying characteristics in automotive and industrial finishes.
- Coatings:Protective and decorative coating applications leverage ETBE's solvency profile for resin compatibility and film formation control.
Automotive Fuels dominates absolute volume, with Industrial Solvents gaining share fastest on environmental solvent substitution trends.
Distribution Channel:
Supply concentration around integrated refinery-petrochemical complexes favors direct procurement relationships over spot-market liquidity.
- Direct Sales:Long-term offtake agreements between ETBE producers and oil companies or chemical manufacturers displace merchant market transactions. TotalEnergies and LyondellBasell anchor European and US volumes through captive supply chains.
- Distributors:Regional chemical distributors serve mid-scale solvent and coating customers requiring smaller lot sizes and technical support.
- Wholesale:Bulk terminal operators aggregate fuel-grade ETBE for refinery blending operations.
- Online Retail:E-commerce platforms handle laboratory-scale and specialty-grade orders for research and pilot-scale chemical synthesis.
Direct Sales captures the largest volume share, with Distributors expanding most quickly on specialty chemical fragmentation.
End User:
Customer-type segmentation reveals divergent procurement sophistication and certification burdens across integrated versus merchant demand.
- Oil Companies:Integrated refiners blend ETBE to meet gasoline pool specifications and renewable fuel obligations. EPA Renewable Fuel Standard compliance credit economics shape US procurement timing and volume.
- Chemical Manufacturers:Specialty and commodity chemical producers consume ETBE as feedstock or process solvent, with REACH and FDA registration requirements governing supplier qualification.
- Automotive OEMs:Vehicle manufacturers specify fuel oxygenate compatibility in powertrain calibration and materials testing protocols.
- Construction Firms:Coatings and adhesives applications in building materials create dispersed, price-sensitive demand for solvent-grade material.
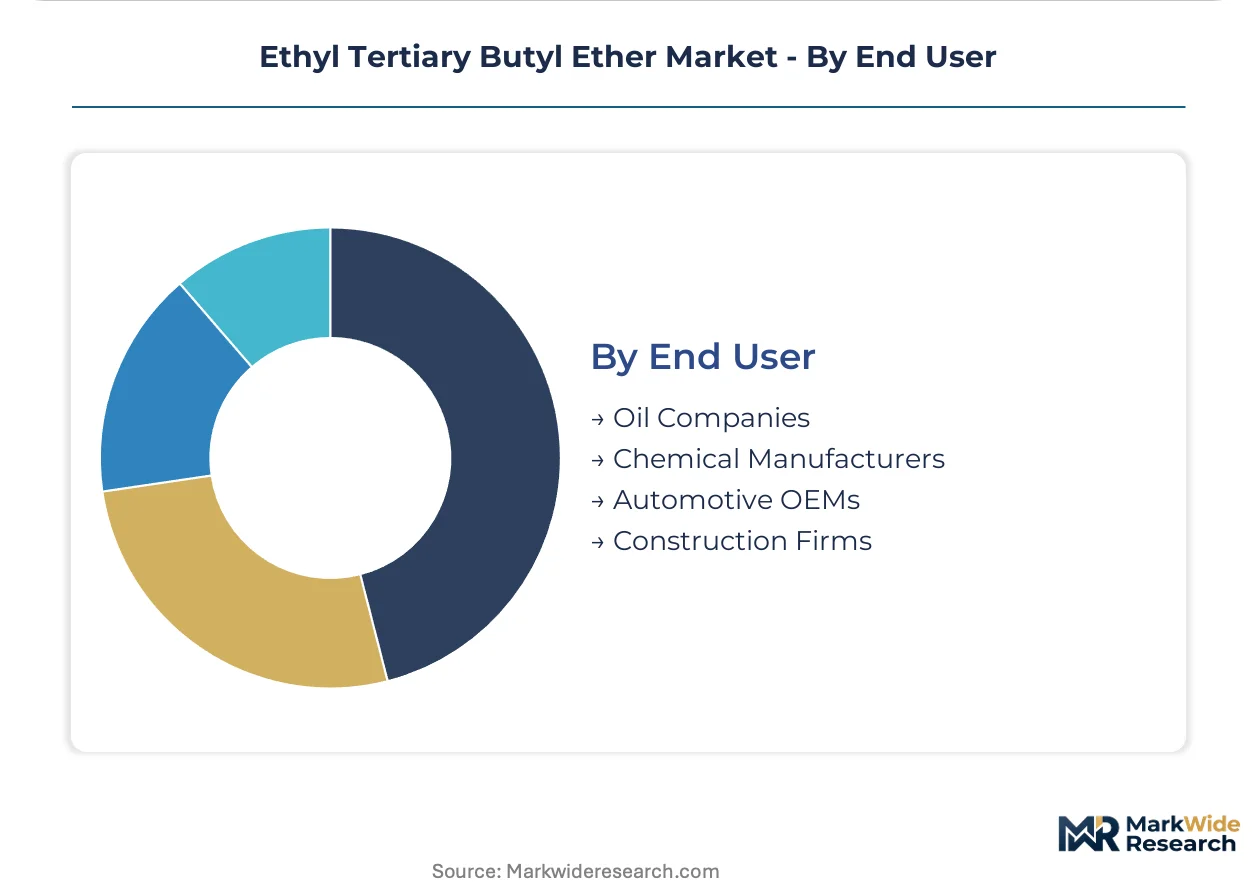
Oil Companies occupy the volume leadership position, with Chemical Manufacturers on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor anchors global ETBE production capacity, with integrated refinery-etherification complexes supplying domestic gasoline blending pools and export markets. Refiners across Texas and Louisiana leverage captive isobutylene from steam crackers and FCC units to maintain feedstock cost advantages. This concentration shapes competitive dynamics for distant producers seeking supply security.
United States
EPA Renewable Fuel Standard compliance obligations drive refinery oxygenate procurement, with California's Air Resources Board Low Carbon Fuel Standard creating differentiated demand for lower-carbon-intensity pathways. The EPA enforces renewable volume obligations that directly shape blending economics. Houston-Galveston-Brazoria petrochemical clusters host retrofitted MTBE-to-ETBE conversion units.
China
Provincial biofuel pilot programs in Shandong and Guangdong accelerate ethanol-to-ETBE infrastructure construction, with state-owned refiners expanding dedicated blending capacity. National biofuel mandates under the 14th Five-Year Plan create compliance-driven procurement volumes. Yangtze River Delta refining hubs in Jiangsu and Zhejiang provinces scale import terminals for ethanol feedstock.
Germany
ECHA REACH registration requirements govern import specifications and hazard communication protocols, tightening documentation burdens for non-EU suppliers. The EU Renewable Energy Directive biofuel mandates anchor refinery blending requirements. Bavarian and North Rhine-Westphalia chemical clusters concentrate specialty-grade ETBE production for pharmaceutical intermediate applications.
Brazil
Sugarcane-derived ethanol feedstock advantages position domestic producers for lower-carbon export pathways, with ANVISA pharmaceutical-grade certifications enabling high-purity segment participation. National biofuel policy under RenovaBio creates credit mechanisms for renewable oxygenate adoption. São Paulo state ethanol-etherification complexes supply Latin American fuel additive markets.
India
Ethanol import infrastructure scaling supports prospective ETBE adoption, with national biofuel blending targets creating regulatory precedent for oxygenate mandates. Ministry of Petroleum and Natural Gas pilot programs in Maharashtra and Gujarat test refinery etherification retrofits. Reliance Industries' Jamnagar complex evaluates captive ethanol-to-ETBE conversion economics.
Ethyl Tertiary Butyl Ether Market Vendor Landscape
Global majors compete with regional champions across feedstock integration and regulatory certification dimensions. The vendor base clusters around three tiers: integrated oil companies with captive refinery-petrochemical complexes, specialized oxygenate producers with merchant market positions, and regional ethanol-etherification joint ventures. Strategic moves concentrate on long-term offtake contracting and carbon intensity certification rather than capacity expansion.
Within the integrated oil company tier, LyondellBasell Industries Holdings B.V. and TotalEnergies SE exemplify archetypes leveraging US Gulf Coast and European refinery-petrochemical integration respectively. Braskem occupies a position representing sugarcane-ethanol feedstock advantages in Latin American supply chains. These three entities anchor the competitive structure through backward integration into ethanol sourcing and forward integration into refinery blending relationships.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| TotalEnergies SE |
| Braskem |
| Eni S.p.A. |
| Neste |
| SABIC |
| ExxonMobil Corporation |
| Repsol S.A. |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Isobutylene feedstock costs transmit directly through ETBE pricing tiers, with US Gulf Coast steam cracker outputs anchoring the low-cost base and distant Asian refiners absorbing freight premiums to secure merchant supply. California's Low Carbon Fuel Standard credit mechanisms create a parallel premium tier for sugarcane-ethanol pathways, splitting the market into carbon-intensity-differentiated contract structures.
Pricing Analysis
Input-cost pass-through from ethanol and isobutylene commodity swings dominates ETBE pricing, with corn and sugarcane harvest volatility compressing margin predictability for non-integrated operators. Three-tier pricing structure across pharmaceutical-grade, fuel-grade, and technical-solvent grades reflects certification burden and volume scale differentiation. Pricing pressure stems from aromatics restrictions tightening gasoline formulation economics, forcing refiners toward cost-competitive oxygenate sourcing. Merchant chemical manufacturers exhibit highest price sensitivity due to spot purchasing exposure, while integrated oil companies with captive ethanol streams maintain lowest sensitivity through backward supply control.
Supply Chain Analysis
Isobutylene supply rests on US Gulf Coast steam cracker and FCC unit outputs, with Middle Eastern refinery complexes and Western European petrochemical hubs providing secondary sourcing. Ethanol feedstock draws from Brazilian sugarcane mills, US corn belt biorefineries, and emerging Indian molasses-based operations. Single-source vulnerability concentrates around merchant isobutylene availability from Texas-Louisiana corridors, exposing Asian ETBE producers to freight cost spikes and cargo scheduling constraints. Distribution runs through long-term offtake agreements between integrated producers and refinery blending terminals, displacing spot-market liquidity in favor of contractual supply security.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ETBE hinges on carbon intensity certification premiums and feedstock integration economics, with sugarcane-ethanol pathways capturing California LCFS credit value and refinery-petrochemical complexes locking in captive isobutylene cost advantages.
For Market Incumbents: Deepen backward integration into ethanol sourcing through Brazilian sugarcane mill partnerships or US corn-belt biorefinery joint ventures to defend against merchant feedstock price volatility. Secure long-term offtake contracts with California and EU refiners under Low Carbon Fuel Standard and Renewable Energy Directive compliance frameworks, anchoring volume against electric vehicle penetration threats in European urban markets. Prioritize REACH registration maintenance and carbon intensity certification investments to preserve premium-tier access. For New Entrants and Emerging Players: Specialty chemical manufacturers seeking pharmaceutical-grade ETBE for active ingredient extraction represent an underserved buyer archetype with specification premiums and lower volume requirements than fuel additive incumbents. Indonesia's expanding biodiesel infrastructure and national biofuel mandate trajectory create regulatory precedent for oxygenate adoption, offering a penetrable geography with scaling ethanol import terminals. Pursue toll-manufacturing arrangements with existing etherification units to bypass capital-intensive refinery-petrochemical complex construction. For Investors and Strategic Acquirers: Roll-up economics work for regional ethanol-etherification joint ventures because fragmented bioethanol sourcing and distributed refinery blending demand favor consolidated supply chains with certification capabilities. Focus acquisition screening on Brazilian and Indian assets with sugarcane or molasses ethanol integration and ANVISA or emerging pharmaceutical-grade certifications. Watch California LCFS credit banking behavior and EU Renewable Energy Directive biofuel mandate trajectory revisions as inflection indicators for premium-tier demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Sourcing | Captive bioethanol supply from Brazilian mills locks in carbon intensity advantages for California LCFS credit capture. |
| MTBE-to-ETBE Unit Retrofit | Reactive distillation catalyst swaps at LyondellBasell and TotalEnergies complexes reduce steam consumption and capital deployment timelines. |
| Pharmaceutical-Grade Certification | ANVISA and FDA high-purity registrations enable pricing premiums in agrochemical synthesis and API extraction segments. |
| Long-Term Refinery Offtake Contracting | California and EU refiners prioritize supply security over spot optimization under compliance credit banking incentives. |
| Indonesia Market Entry Partnership | National biodiesel program expansion creates regulatory precedent for oxygenate mandates with scaling ethanol infrastructure. |
Methodological Framework
Coverage spans the US Gulf Coast, Western Europe, China, Brazil, and India, with primary inputs from each refining and petrochemical corridor. The analysis combines structured interviews with refinery procurement managers, ethanol supply specialists, oxygenate plant engineers, and specialty chemical distributors with secondary validation from EIA fuel pool data, EPA Renewable Fuel Standard compliance reports, EU ETS transaction records, and customs trade flows. Bottom-up capacity and consumption estimates triangulate against top-down regulatory mandate trajectories across the analysis window.
Rate-of-change decomposition separates volume growth into gasoline pool expansion, oxygenate blending ratio shifts, and ethanol-to-ETBE conversion infrastructure additions. Segmentation modeling incorporates fuel additive versus chemical intermediate grade tiers, automotive fuel versus industrial solvent applications, direct sales versus distributor channel structures, and oil company versus chemical manufacturer end-user categories. CAGRs derive from elasticity-adjusted demand projections and capacity utilization assumptions, with carbon intensity credit economics and aromatics restriction timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; fuel additive volumes carry tighter precision through refinery reporting obligations than emerging pharmaceutical intermediate demand. Forecasts reflect documented assumptions regarding biofuel mandate enforcement, ethanol import infrastructure completion, and electric vehicle penetration rates. Regulatory revision risk, feedstock commodity volatility, and REACH classification updates constitute the primary forecast revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Industrial Burner Market
Fuels
Compressed Natural Gas Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
Canada Coal Market
Fuels
Fuel Oxygenate Market
Fuels
LPG Gas Cylinder Market
Fuels
China Coal Market
Fuels
Bituminous Coal Market
Fuels
Fuel Quality Testing Market
Fuels
Anthracite Coal Mining Market
Fuels
Chafing Fuel Market
Fuels
Fuel Oil Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
China LNG Market
Fuels
LNG Fueling Station Market
Fuels
Europe Wood Pellet Market