
 Hydrogen Tube Trailer Market | 2026-2036
Hydrogen Tube Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Tube Trailer Market Analytics
Type-IV composite certification is bifurcating the competitive landscape into high-pressure specialists and legacy steel operators. Hexagon Purus ASA leverages its filament-winding expertise to dominate lightweight cylinder production. Linde plc anchors European hydrogen logistics through captive fleet deployment. Calvera Hydrogen specializes in modular trailer configurations for decentralized refueling stations.
Hydrogen tube trailers are mobile pressure vessels mounted on road chassis, designed to transport compressed hydrogen gas at ratings from 2,500 psi to 7,000 psi using steel or carbon-fiber-reinforced cylinders. Their primary purpose is bridging the gap between centralized production sites and dispersed industrial or mobility consumers lacking pipeline access. High-pressure tube trailers command premium positioning as refinery and ammonia plant operators seek maximum payload efficiency per haul cycle. The energy sector end user segment leads order volumes, though transportation companies represent the fastest-expanding demand pool as heavy-duty fuel cell truck corridors multiply. Custom tube trailers capture concentrated margin pools where site-specific manifold configurations and regional weight limits require engineered solutions.
DOT regulations in the United States govern cylinder requalification intervals and material traceability, directly shaping fleet replacement cycles and manufacturer certification costs. The EU's F-Gas Regulation and CE marking requirements for pressure equipment impose design-validation protocols that filter out non-compliant suppliers. Stakeholders must monitor evolving hydrogen purity standards from ISO committees, as fuel cell applications impose stricter contamination thresholds than legacy industrial off-take.
Market Dynamics
Type-IV composite certification is fragmenting supplier tiers into high-pressure specialists versus legacy steel operators, forcing capital reallocation across manufacturing footprints and requalification schedules.
Growth Catalysts
- DOT hazmat certification upgrades:Fleet operators in Texas and California face compressed replacement cycles as requalification intervals tighten, accelerating orders for certified composite cylinder systems.
- Industrial hydrogen corridors:Chemical producers in Germany's Ruhr region seek dedicated tube trailer fleets to bypass pipeline bottlenecks for ammonia and refinery feedstock supply.
- Carbon-fiber winding automation:Advances in filament-winding robotics reduce Type-IV cylinder production costs, expanding addressable demand from premium mobility into standard industrial haulage.
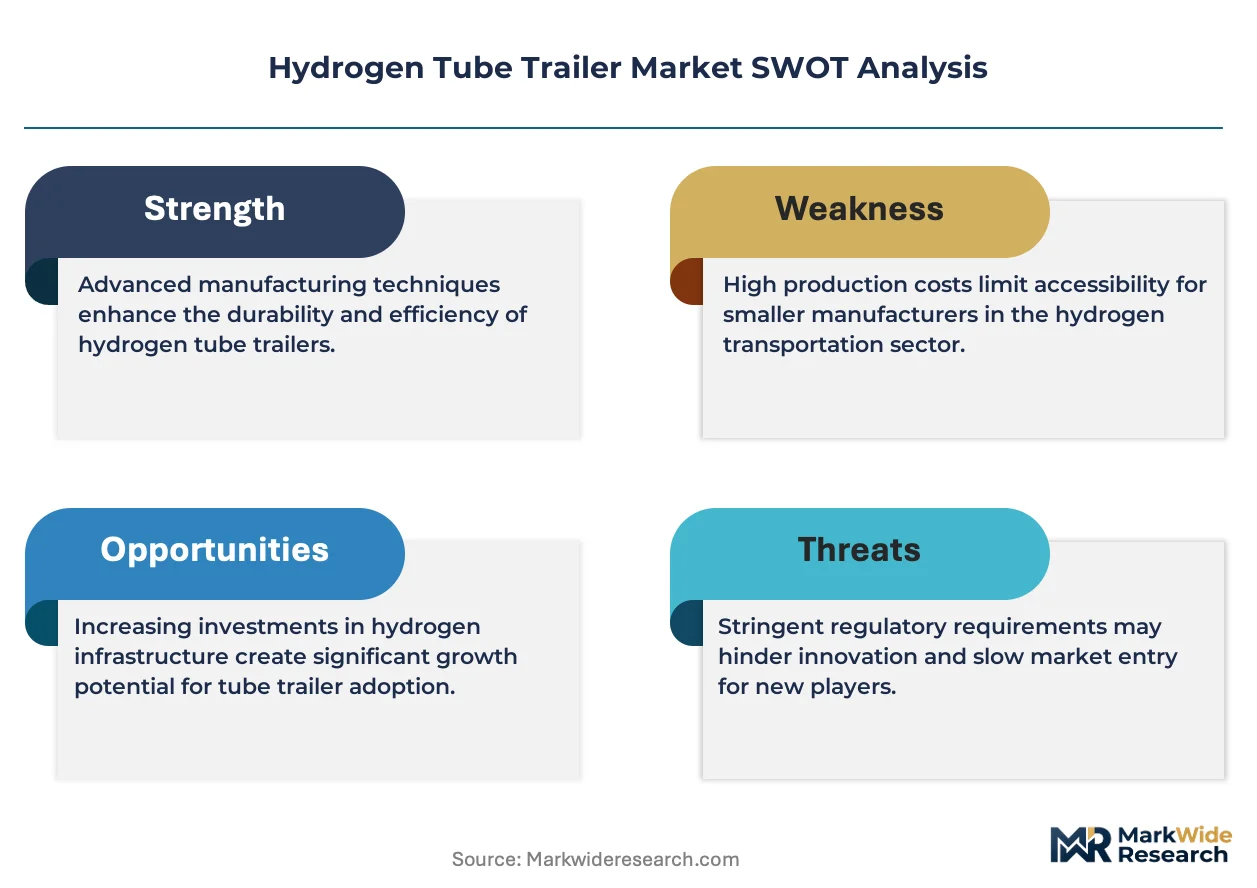
Market Restraints
- Carbon fiber supply concentration:Toray Industries and Hexcel Corporation control aerospace-grade precursor supply, exposing trailer manufacturers to input cost volatility and allocation rationing.
- Steel cylinder path dependency:Refinery operators in the US Gulf Coast maintain substantial sunk investment in 2,500-psi steel fleets, slowing composite adoption despite payload efficiency gains.
- ISO 19881 purity thresholds:Fuel cell applications impose contamination limits below legacy industrial standards, requiring trailer manifold redesigns and stainless-steel plumbing upgrades that extend certification timelines.
Strategic Opportunities
- Decentralized refueling infrastructure:Modular trailer configurations serve hydrogen stations lacking pipeline connectivity, particularly in California's Central Valley trucking corridors.
- EU Green Deal hydrogen import hubs:Rotterdam and Hamburg port operators seek mobile buffer storage to manage supply-demand mismatches from North African and Middle Eastern production.
- CE marking acceleration:The EU's streamlined pressure equipment directive reduces third-party validation costs for qualified manufacturers, lowering barriers to continental fleet deployment.
Industry Challenges
- Filament-winding technician scarcity:Type-IV cylinder production requires specialized composite layup expertise concentrated in aerospace supply chains, creating recruitment bottlenecks for trailer OEMs scaling capacity.
- Multi-standard certification burden:Manufacturers serving both North American and European markets must maintain parallel DOT and PED compliance documentation, duplicating engineering validation costs.
- Legacy manifold integration:Site-specific hydrogen dispensing protocols at ammonia plants and semiconductor fabs demand custom engineering that compresses margin on standardized trailer platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Tube Trailer Market |
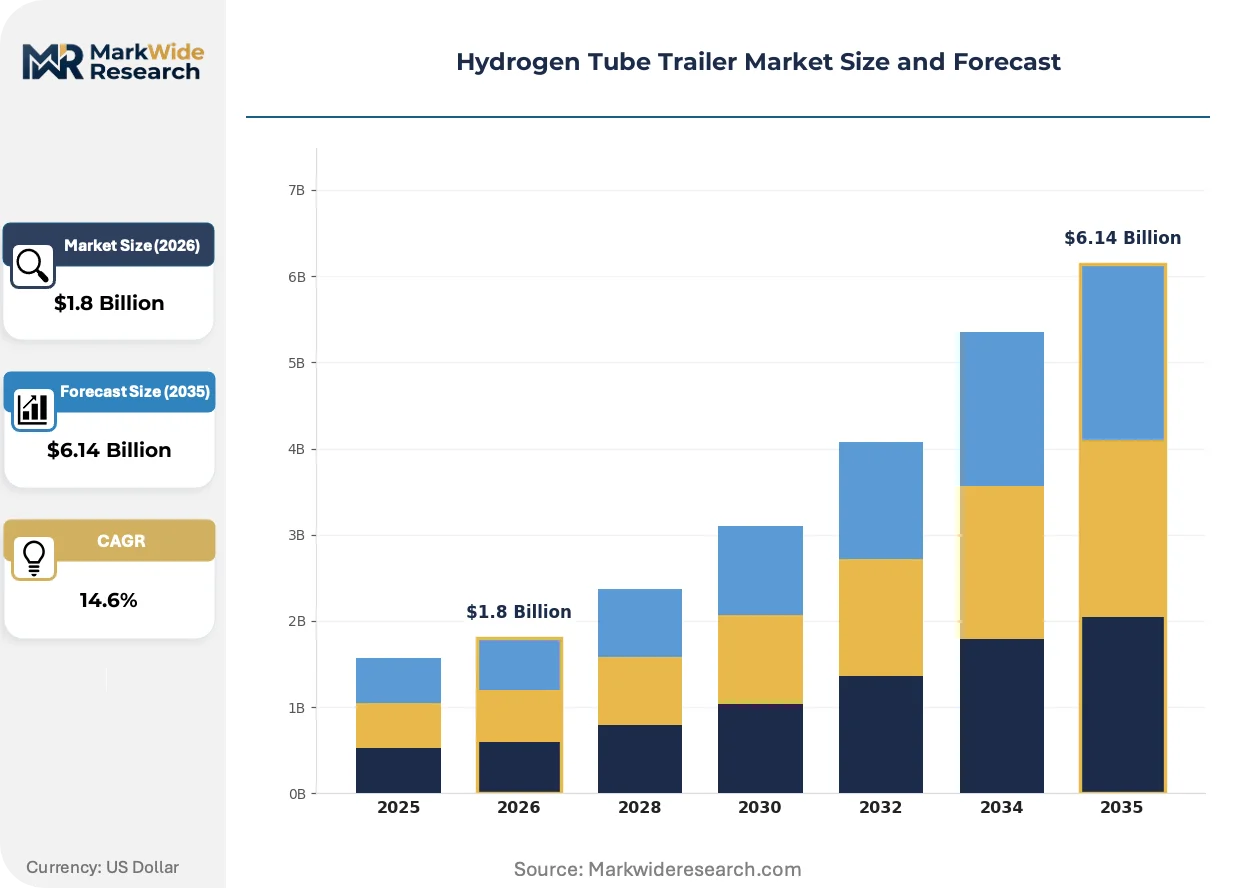
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tube Trailers, High-Pressure Tube Trailers, Custom Tube Trailers, Dual-Purpose Trailers End User: Energy Sector, Industrial Manufacturers, Research Institutions, Transportation Companies Capacity: 1000-2000 psi, 2001-3000 psi, 3001-4000 psi, Above 4000 psi Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Outlets |
| Companies Covered | FIBA Technologies Inc., Calvera Hydrogen, Air Liquide, Composite Advanced Technologies LLC, Weldship Corporation, Linde plc, Hexagon Purus ASA, Roberts Oxygen Company Inc., Air Products and Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Tube Trailer Market Evolving Landscape
Material substitution and regulatory harmonization are compressing product lifecycles while expanding the addressable market for high-pressure hydrogen logistics. Three developments dominate the transition.
Filament-wound Type-IV composite cylinders are fragmenting the traditional steel-dominated supplier base. Refinery operators seeking 700-bar payloads for maximum transport efficiency now specify carbon-fiber construction, compressing order lead times for qualified manufacturers while marginalizing legacy steel tube producers.
REACH and the EU F-Gas Regulation are tightening material traceability requirements for pressure equipment imported into European industrial corridors. Trailer OEMs must now document carbon-fiber precursor origins and resin chemistry through the supply chain, extending design-validation protocols but filtering out non-compliant competitors.
Industrial off-takers are unbundling trailer procurement from long-term hydrogen supply contracts. Chemical producers in Germany and the Netherlands now lease dedicated fleets through third-party logistics operators, shifting capital burden from balance sheets while demanding real-time telemetry on cylinder pressure and location.
Hydrogen Tube Trailer Market Segmentation
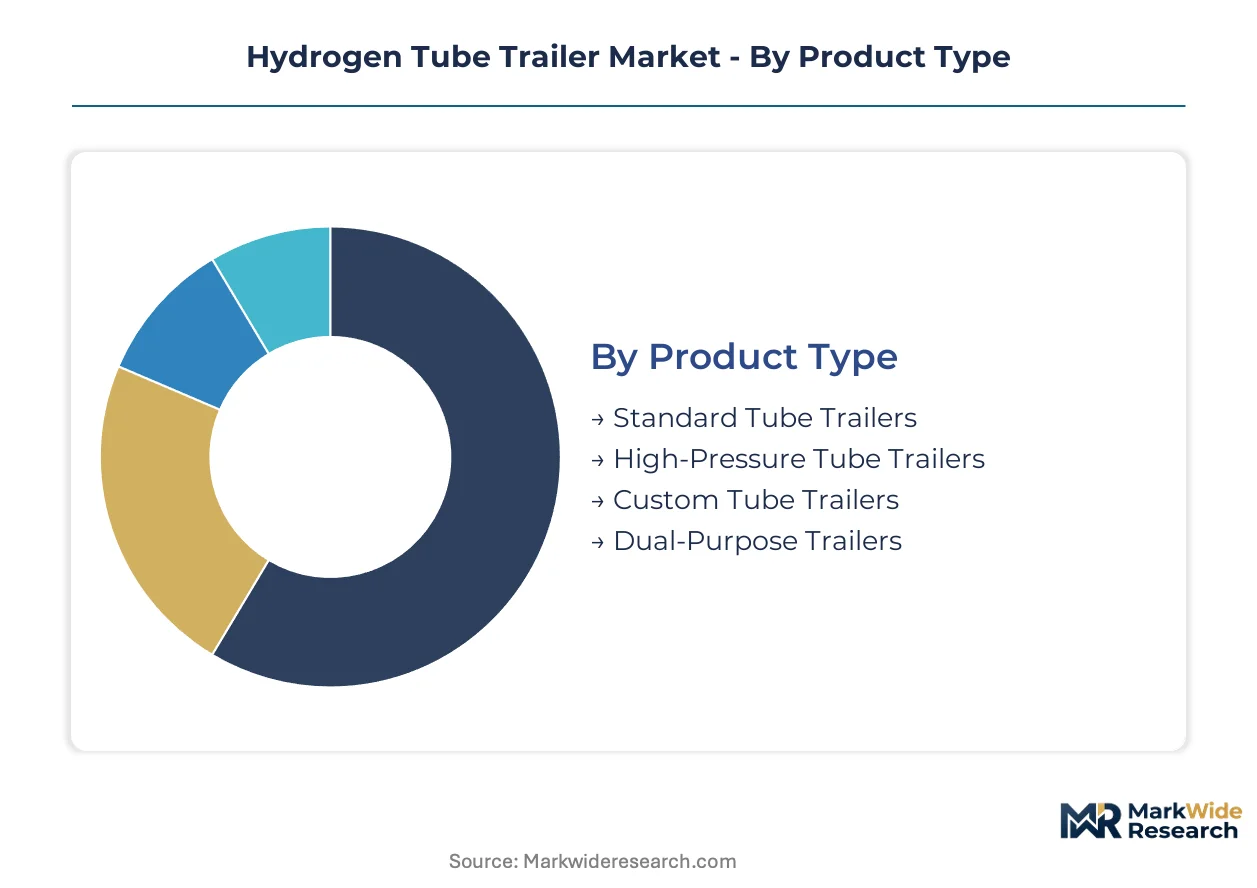
Tube trailer segmentation determines payload economics and regulatory compliance pathways. Pressure ratings, cylinder materials, and end-use specifications create distinct procurement channels with diverging margin structures and certification requirements.
Product Type:
Substitution pressure from pipeline infrastructure and on-site electrolysis varies sharply across product categories, with standardized platforms facing the most severe displacement risk.
- Standard Tube Trailers:Steel-cylinder platforms rated at 2,500 psi serve refinery hydrogen supply chains in Texas and California. Fleet operators in the US Gulf Coast maintain substantial installed bases, though compressed replacement cycles from DOT hazmat certification upgrades are accelerating composite migration.
- High-Pressure Tube Trailers:Type-IV carbon-fiber composite construction achieves 5,000-7,000 psi ratings for maximum hydrogen payload per haul cycle. Chemical producers in Germany's Ruhr region specify these systems to bypass pipeline bottlenecks for ammonia feedstock delivery.
- Custom Tube Trailers:Site-specific manifold configurations address regional weight limits and dispensing protocols at semiconductor fabrication facilities.
- Dual-Purpose Trailers:Modular chassis accommodate cylinder swaps between industrial gas and hydrogen service for logistics operators serving mixed fleets.
Standard tube trailers anchor the volume base while high-pressure tube trailers gain share at the steepest rate.
End User:
Application maturity separates established industrial off-takers from emerging mobility demand pools with diverging purity and pressure specifications.
- Energy Sector:Refinery operators and power generators constitute the largest existing demand pool, sourcing hydrogen for desulfurization and grid-scale storage buffer applications.
- Industrial Manufacturers:Ammonia plants and steel producers in Germany's industrial corridor seek dedicated tube trailer fleets to secure feedstock supply independent of pipeline constraints.
- Research Institutions:National laboratories and university facilities require small-batch deliveries with ultra-high purity certification for fuel cell development programs.
- Transportation Companies:Heavy-duty fuel cell truck operators along California's Central Valley corridors represent the most rapidly expanding demand segment, requiring 700-bar dispensing compatibility.
Energy sector procurement dominates current fleet deployment while transportation companies expand most quickly.
Capacity:
Pressure tier selection directly determines cylinder material economics and transport radius feasibility for hydrogen logistics networks.
- 1000-2000 psi:Legacy steel construction persists in short-haul industrial applications where payload efficiency matters less than capital cost minimization.
- 2001-3000 psi:Transitional rating band where composite adoption accelerates as DOT requalification intervals tighten for steel alternatives.
- 3001-4000 psi:Intermediate composite platforms serve regional hydrogen hubs lacking pipeline connectivity.
- Above 4000 psi:Premium carbon-fiber systems achieve maximum transport efficiency for long-distance hydrogen corridors and fuel cell vehicle refueling infrastructure.
Mid-pressure tiers retain the largest installed base while above-4000 psi systems command the fastest expansion trajectory.
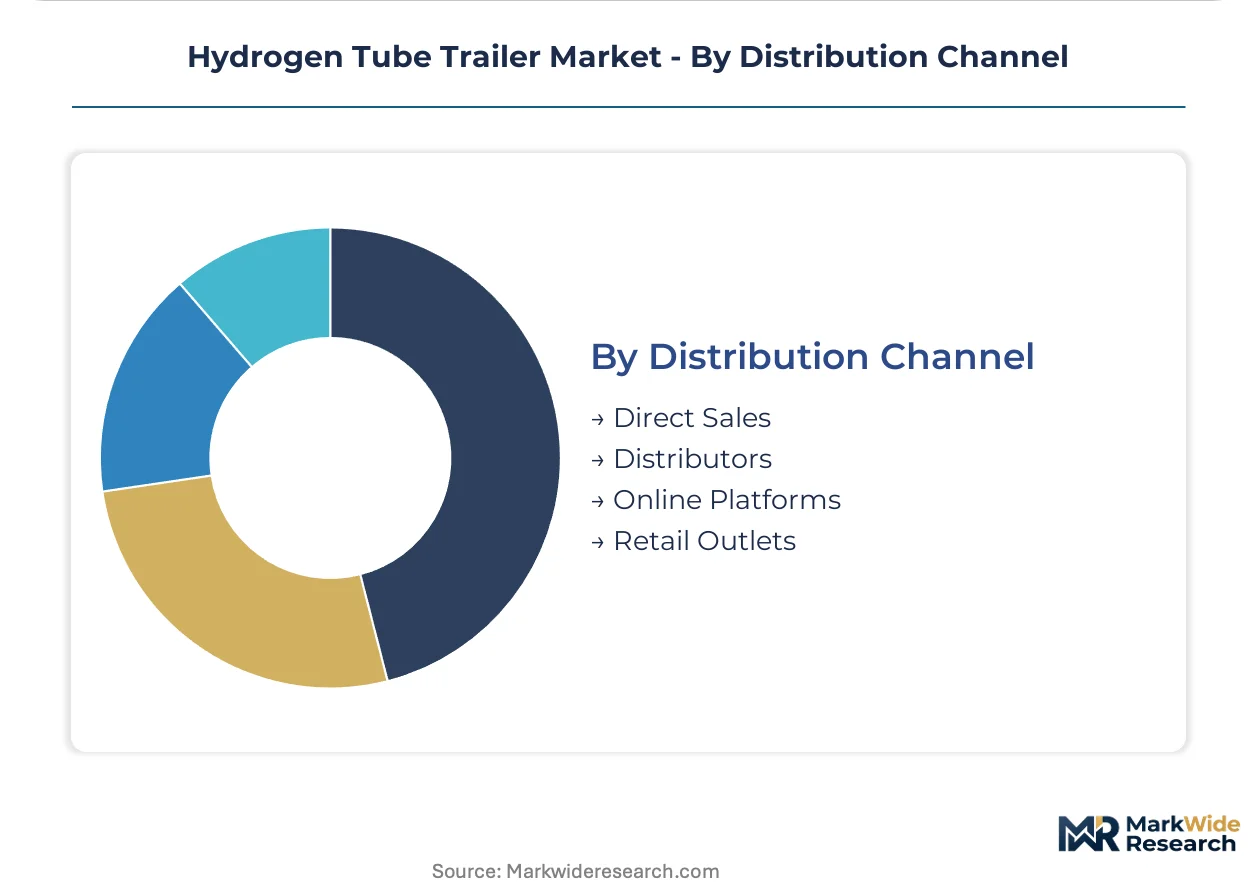
Distribution Channel:
Channel selection reflects capital intensity preferences and technical support requirements across end-user sophistication levels.
- Direct Sales:OEM relationships dominate for chemical producers and refinery operators specifying custom manifold configurations and fleet telemetry integration.
- Distributors:Regional industrial gas specialists serve research institutions and smaller manufacturers requiring flexible delivery scheduling.
- Online Platforms:Digital procurement channels emerge for standardized trailer components and replacement cylinder procurement.
- Retail Outlets:Limited applicability given specialized certification and installation requirements for pressure equipment.
Direct sales capture the highest value contracts while distributor networks broaden geographic penetration most effectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany accept substantial price premiums for certified composite systems, while Gulf Coast refiners in the United States resist replacement cycles until regulatory deadlines force compliance. This elasticity gap shapes regional deployment timelines and manufacturer prioritization.
United States
Texas and California anchor fleet renewal demand as DOT hazmat certification upgrades compress requalification intervals for legacy steel cylinders. The EPA's evolving hydrogen hub designations channel federal infrastructure investment toward Gulf Coast production clusters. Houston-area refiners maintain substantial 2,500-psi steel installations, though California's Central Valley trucking corridors accelerate composite adoption for 700-bar fuel cell logistics.
Germany
Chemical producers in the Ruhr region seek dedicated tube trailer fleets to bypass pipeline bottlenecks for ammonia feedstock delivery. The EU F-Gas Regulation and REACH impose stringent material traceability requirements that filter non-compliant suppliers from industrial procurement. Hamburg port operators position mobile buffer storage systems to manage supply-demand mismatches from anticipated North African hydrogen imports.
China
MIIT's hydrogen energy industry development guidelines prioritize high-pressure transport infrastructure for fuel cell vehicle corridors in the Yangtze River Delta. Provincial governments in Guangdong and Shanghai subsidize tube trailer procurement for demonstration zones. Sinopec's refinery network in Shandong province generates substantial captive demand for industrial hydrogen logistics.
Japan
METI's hydrogen roadmap targets import hub development at Kobe and Yokohama ports, requiring mobile storage for maritime supply chain integration. Domestic automotive manufacturers in Aichi prefecture specify ultra-high purity certification for fuel cell development programs. JIS pressure equipment standards create parallel certification burdens for foreign OEMs seeking market entry.
Netherlands
Rotterdam port authorities seek tube trailer fleets for buffer storage at emerging hydrogen import terminals. The EU Green Deal's REPowerEU framework accelerates CE marking demand for continental fleet deployment. Eindhoven-region chemical clusters contract dedicated logistics operators to secure feedstock supply independent of pipeline constraints.
Hydrogen Tube Trailer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with composite specialists commanding premium positioning while steel fabricators defend installed base relationships. The supplier base fragments across three tiers: multinational industrial gas conglomerates with captive fleet deployment, dedicated cylinder OEMs with filament-winding expertise, and regional fabricators serving legacy refinery maintenance. Dominant competitive moves include capacity expansion in Type-IV manufacturing and strategic partnerships between trailer OEMs and carbon fiber suppliers to secure precursor allocation.
Within the composite specialization tier, Hexagon Purus ASA and Composite Advanced Technologies LLC exemplify technology-forward positioning through carbon-fiber cylinder expertise. Linde plc and Air Liquide occupy the industrial gas conglomerate archetype, leveraging captive hydrogen production to anchor fleet deployment decisions. Calvera Hydrogen represents the modular configuration specialist segment, serving decentralized refueling infrastructure with site-adaptable trailer designs. FIBA Technologies Inc. and Weldship Corporation sit within the established fabrication tier, maintaining legacy steel cylinder competencies while navigating composite transition pressures.
| Leading Market Players |
|---|
| FIBA Technologies Inc. |
| Calvera Hydrogen |
| Air Liquide |
| Composite Advanced Technologies LLC |
| Weldship Corporation |
| Linde plc |
| Hexagon Purus ASA |
| Roberts Oxygen Company Inc. |
| Air Products and Chemicals Inc. |
| Others |
Value Network & Pricing Analysis
Carbon-fiber precursor substitution for aerospace-grade steel simultaneously redraws procurement geography toward Japanese and American suppliers while compressing margin structures for European fabricators facing REACH documentation burdens. This materials transition concentrates pricing power with Toray Industries and Hexcel Corporation, forcing trailer OEMs to absorb volatility or pass through indexed resin costs to refinery operators.
Pricing Analysis
After-sales service contracts and cylinder requalification revenue now exceed hardware margins for fleet operators managing DOT-mandated replacement cycles. Three-tier pricing structure across premium Type-IV composite, transitional hybrid systems, and legacy steel platforms reflects certification grade and pressure rating differentiation. Pricing pressure stems from carbon fiber allocation rationing that constrains qualified cylinder supply. Chemical producers in Germany's Ruhr region exhibit lowest price sensitivity, prioritizing payload efficiency and material traceability over capital cost minimization.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Japanese and South Korean carbon-fiber precursor shipments to geopolitical disruption risks. Manufacturing concentrates in Germany, the United States, and China, with filament-winding automation drawing from aerospace-qualified technician pools. Raw material dependencies center on PAN precursor from Toray Industries, epoxy resin systems from Huntsman Corporation, and aluminum liner forgings from specialty metals suppliers. Single-source vulnerability in aerospace-grade carbon fiber allocation creates supply chain risk. Distribution runs through direct OEM relationships for refinery operators and third-party logistics leasing platforms for chemical producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from telemetry-enabled fleet management and predictive maintenance contracts expands faster than trailer hardware sales as chemical producers shift from ownership to operational leasing models.
For Market Incumbents: Shield installed base relationships by embedding cylinder requalification services into long-term hydrogen supply contracts before composite specialists capture replacement cycles. Invest in backward integration into filament-winding capacity to reduce carbon fiber precursor exposure. Prioritize DOT certification maintenance as regulatory tightening accelerates fleet turnover decisions. For New Entrants and Emerging Players: Lead with modular trailer configurations targeting California's Central Valley fuel cell trucking corridors where pipeline infrastructure remains underdeveloped. Penetrate the decentralized refueling segment through site-adaptable manifold designs that incumbent steel fabricators cannot engineer profitably. Pursue partnerships with regional hydrogen station developers as anchor customers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors composite manufacturing specialists with established aerospace supply chain credentials. Long-term viability hinges on securing precursor allocation agreements before capacity constraints harden. Acquisition targets should demonstrate CE marking completion and DOT certification parallel-track capability. Watch carbon fiber spot pricing volatility as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Secures allocation from Toray Industries and Hexcel Corporation against aerospace competition. |
| Type-IV Composite Certification Acceleration | Captures replacement demand from DOT hazmat requalification tightening in Texas and California. |
| Telemetry-Enabled Fleet Leasing Platform | Converts capital expenditure burden for German chemical producers into recurring service revenue. |
| CE Marking Parallel-Track Development | Opens EU Green Deal hydrogen import hub opportunities at Rotterdam and Hamburg ports. |
| Filament-Winding Automation Scale-Up | Reduces per-cylinder production costs to compete with legacy steel on total cost of ownership. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DOT hazmat certification databases, EU pressure equipment directive filings, and SEC disclosures from industrial gas conglomerates. Interviews with fleet operations managers at Gulf Coast refineries, procurement leads at German chemical producers, filament-winding technicians at composite cylinder OEMs, and aftermarket service directors at trailer leasing operators inform demand-side validation. Trade data from customs authorities, IEA hydrogen project tracking, and FERC infrastructure filings provide supply-side triangulation. Bottom-up cylinder shipment counts and top-down hydrogen logistics expenditure estimates converge through iterative reconciliation.
Segmentation dimensions modeled include pressure rating tier, cylinder material construction, end-use application, and geographic regulatory cluster across the projection horizon. CAGRs derive from installed base replacement cycle analysis, pipeline bypass demand elasticity, and fuel cell vehicle corridor development timelines. Forecast inputs incorporate DOT requalification interval revision scenarios, carbon fiber precursor capacity expansion announcements, and EU F-Gas Regulation enforcement intensity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained hydrogen hub funding authorization and carbon fiber supply normalization would require recalibration. Forecasts reflect documented assumptions regarding certification timeline acceleration and refinery operator composite adoption willingness. Revision becomes warranted when aerospace carbon fiber allocation rationing crosses thresholds that strand Type-IV manufacturing capacity expansion plans.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Coal Briquette Box Market
Fuels
Solid Recovered Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Collapsible Fuel Tank Market
Fuels
Europe Coal Market
Fuels
CNG Dispenser Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Multifuel Gas Turbine Market
Fuels
Oil & Gas Lubricants Market
Fuels
Tire Derived Fuel Market
Fuels
Fuel Oil Market
Fuels
Diesel Fuel Water Separator Market
Fuels
Carbonizers Market
Fuels
Coal Gasification Market