
 Mobile Gas Pumping System Market | 2026-2036
Mobile Gas Pumping System Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Gas Pumping System Market Foresight
North American equipment fabricators is pivoting toward modular, truck-mounted dispensing platforms that cut deployment times for fleet customers. Booster Fuels leverages proprietary routing algorithms to optimize fuel delivery density in suburban commercial zones. Yoshi sustains a subscription-based model that anchors recurring revenue from individual vehicle owners. Gilbarco Veeder-Root dominates conventional retail fueling infrastructure but competes through portable product extensions aimed at remote industrial sites.
A mobile gas pumping system comprises self-contained fuel transfer and metering equipment mounted on vehicle platforms or portable skids, typically incorporating explosion-proof electric motors, flow meters accurate to within 0.3 percent, and vapor recovery hardware for regulatory compliance. Electric pumps lead product type demand due to quieter operation and compatibility with grid-tied depot charging infrastructure, while truck-mounted installations capture the fastest growth as logistics fleets reject fixed-site dependency. Diesel end users command the largest volume share given construction and agricultural equipment refueling patterns, though biofuel configurations are gaining traction where state-level low-carbon mandates apply.
EPA underground storage tank regulations and DOT hazardous materials transport standards shape equipment certification requirements for mobile fueling operators across the United States. CARB vapor recovery mandates in California enforce stricter hardware specifications than federal baselines, creating a dual-compliance burden for interstate service providers. OSHA workplace safety protocols further constrain hose handling procedures and spill containment protocols at customer sites. Stakeholders must monitor how state-level clean fuel standards fragment equipment specifications and whether federal infrastructure spending redirects fleet procurement toward electrification alternatives.
Market Dynamics
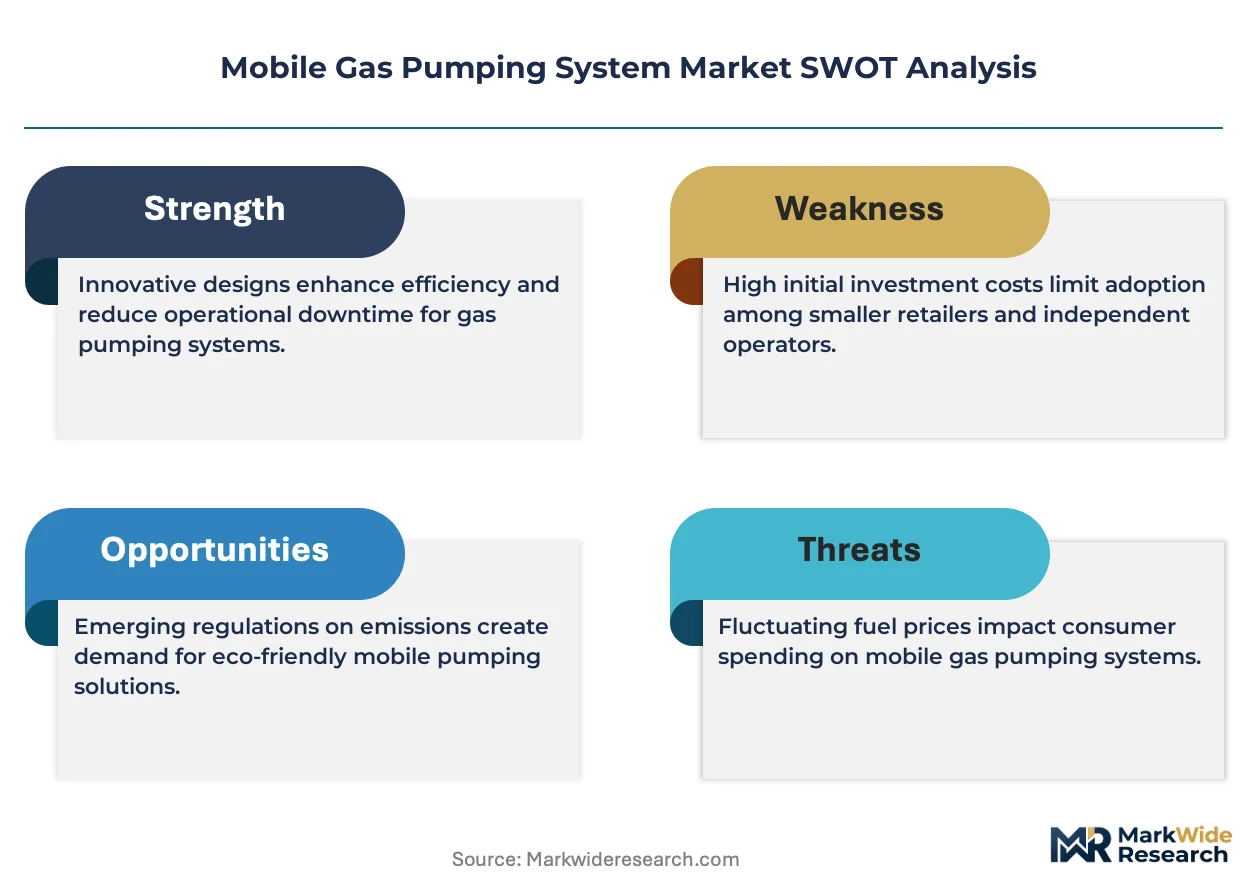
Fleet operators in the United States are abandoning fixed-site fueling infrastructure in favor of truck-mounted dispensing platforms that compress deployment timelines and eliminate capital-intensive underground storage investments.
Growth Catalysts
- EPA Tier 4 Emissions Standards:Stricter particulate limits for off-road diesel engines are extending refueling windows for construction and agricultural equipment, expanding addressable demand for on-site mobile fueling services.
- Last-Mile Logistics Concentration:E-commerce fulfillment networks in Texas and California are consolidating vehicle fleets at suburban distribution nodes, creating density economics for scheduled mobile dispensing routes.
- Electric Pump Technology:Explosion-proof electric motors with sub-0.3% flow meter accuracy are replacing pneumatic systems, enabling quieter nighttime refueling operations in noise-restricted commercial zones.
Market Restraints
- CARB Dual-Compliance Burden:California's vapor recovery mandates impose hardware specifications exceeding federal EPA baselines, fragmenting equipment inventories for interstate operators and inflating certification costs.
- Steel and Aluminum Input Volatility:Skid-mounted tank fabricators face margin compression from commodity price swings in high-grade stainless steel for corrosion-resistant fuel containment systems.
- Electrification Substitution Threat:Battery-electric medium-duty trucks with depot fast-charging infrastructure are displacing diesel refueling demand among early-adopter municipal and corporate fleets.
Strategic Opportunities
- Biofuel Configuration Expansion:State-level low-carbon fuel standards in California and Oregon are creating certified demand for B20 and renewable diesel-compatible dispensing hardware.
- Rural Industrial Cluster Penetration:Remote mining and forestry operations in Montana and Wyoming remain underserved by conventional retail fueling infrastructure, presenting white-space territory for skid-mounted deployment.
- Telematics-Routing Convergence:Integration of real-time vehicle location data with fuel-level sensors is enabling predictive dispatch models that optimize tanker utilization rates.
Industry Challenges
- Hazmat Certification Pipeline:DOT hazardous materials transport licensing creates a 90-120 day onboarding bottleneck for driver recruitment, constraining fleet expansion velocity.
- Legacy UST Liability Transfer:Customers migrating from fixed-site tanks require environmental liability documentation that delays contract execution and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Gas Pumping System Market |
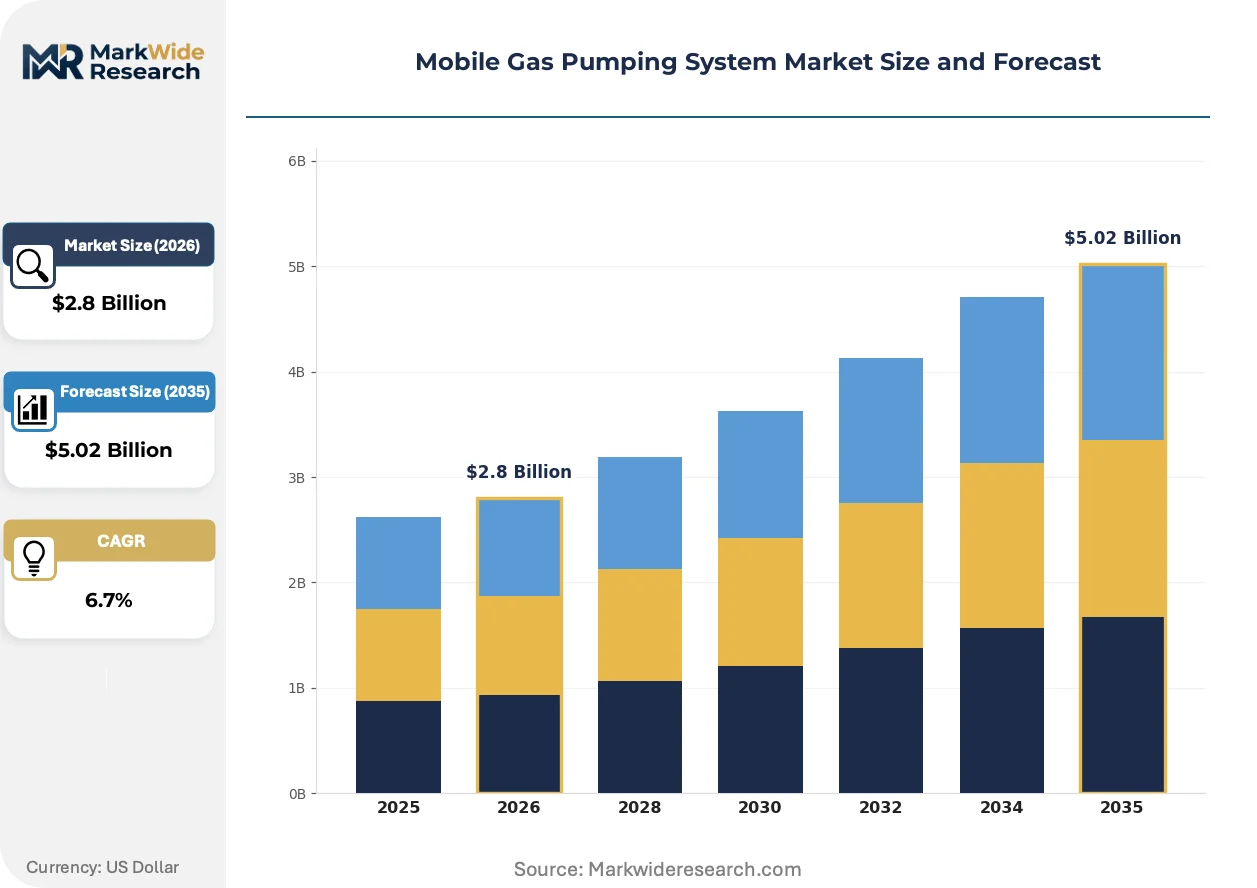
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
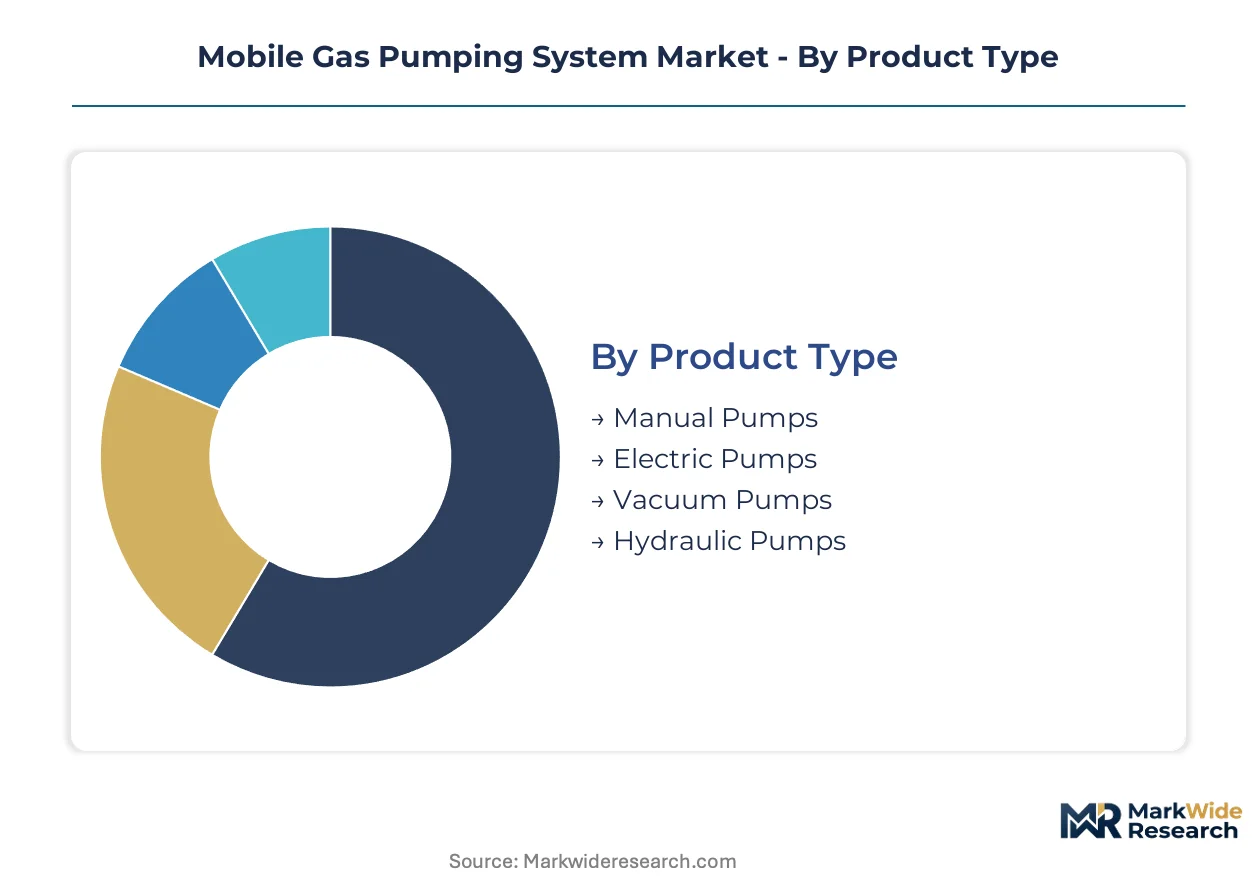
| Segmentation | Product Type: Manual Pumps, Electric Pumps, Vacuum Pumps, Hydraulic Pumps End User: Agriculture, Construction, Transportation, Emergency Services Installation: Portable Units, Fixed Units, Skid-Mounted, Truck-Mounted Fuel Type: Gasoline, Diesel, Biofuel, Alternative Fuels |
| Companies Covered | Booster Fuels, Yoshi, Gilbarco Veeder-Root, Dover Fueling Solutions, Piusi, Filld, WeFuel, FuelGenie, EzFill Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Gas Pumping System Market Shifts & Advancements
Equipment architecture is pivoting from permanent installation toward reconfigurable platforms that accommodate shifting fleet footprints and evolving fuel specifications without full asset replacement.
Self-contained skid-mounted dispensing units with standardized connection interfaces are modularizing field deployment for temporary construction sites and seasonal agricultural operations. Contractors in North Dakota and Kansas are adopting these systems on 18-24 month lease structures rather than capital purchases. The shift is compressing equipment payback periods and expanding the addressable customer base to mid-size operators previously excluded by upfront investment barriers.
OSHA workplace safety protocols are tightening hose handling and spill containment requirements at customer delivery points, mandating secondary containment systems and automated shutoff valves. Fabricators must now engineer portable containment solutions that satisfy both federal standards and site-specific corporate environmental policies. California-based operators face the steepest compliance costs due to overlapping state and federal inspection regimes.
Subscription-based fueling contracts are displacing per-gallon transactional pricing among last-mile delivery fleets seeking predictable operating expenditures. Third-party logistics providers in the Dallas-Fort Worth corridor are consolidating vendor relationships under multi-year agreements with guaranteed price bands. The model transfers inventory risk to mobile fueling operators while locking in volume commitments that justify dedicated tanker allocation.
Mobile Gas Pumping System Market Segmentation
Fleet procurement patterns and regulatory compliance requirements fragment demand across equipment specifications and deployment models. Understanding these divisions reveals where capital concentrates and which configurations capture emerging contract flows.
Product Type:
Standalone pumping systems dominate depot-based operations, while embedded electric configurations integrate with broader fleet management infrastructure.
- Electric Pumps:Explosion-proof motors with sub-0.3% flow meter accuracy enable nighttime refueling in noise-restricted zones. Fleet operators in California logistics corridors specify these for compatibility with grid-tied depot infrastructure and CARB vapor recovery mandates.
- Manual Pumps:Mechanical displacement systems without electrical ignition sources serve remote agricultural operations lacking reliable power access. Demand clusters in Montana and Wyoming where field refueling of seasonal equipment occurs beyond grid reach.
- Vacuum Pumps:Negative-pressure transfer systems handle volatile fuel vapors in enclosed storage scenarios.
- Hydraulic Pumps:PTO-driven configurations mount on existing fleet vehicles for auxiliary power takeoff.
Volume placements concentrate in Electric Pumps; the faster expansion belongs to Hydraulic Pumps.
End User:
Cost tier separation runs from capital-intensive infrastructure projects to subscription-based fleet services with predictable expenditure profiles.
- Transportation:Last-mile delivery networks in Texas and California anchor subscription contract volumes. E-commerce fulfillment nodes generate density economics that justify dedicated tanker allocation and multi-year pricing agreements.
- Construction:EPA Tier 4 emissions standards extend refueling windows for off-road diesel equipment. Contractors in North Dakota and Kansas lease skid-mounted systems on 18-24 month structures rather than capital purchase.
- Agriculture:Seasonal harvest operations drive temporary deployment of portable dispensing equipment.
- Emergency Services:Municipal fleets require rapid-deployment redundancy for disaster response scenarios.
Transportation commands the largest contract values; Agriculture shows the steepest expansion trajectory from mechanization trends.
Installation:
Application context determines mobility requirements, from permanent depot infrastructure to rapidly redeployable field assets.
- Truck-Mounted:Self-contained dispensing platforms eliminate fixed-site dependency for logistics fleets. Routing algorithms optimize delivery density across suburban commercial zones in Dallas-Fort Worth and similar corridors.
- Skid-Mounted:Modular units with standardized interfaces serve temporary construction sites and seasonal operations. Leasing structures compress payback periods and expand access to mid-size operators previously excluded by upfront barriers.
- Portable Units:Hand-carried or wheeled configurations address emergency refueling and small-scale agricultural needs.
- Fixed Units:Permanent installation at fleet depots with integrated vapor recovery and spill containment systems.
Truck-Mounted systems gain share fastest; Skid-Mounted placements lead in absolute unit volume.
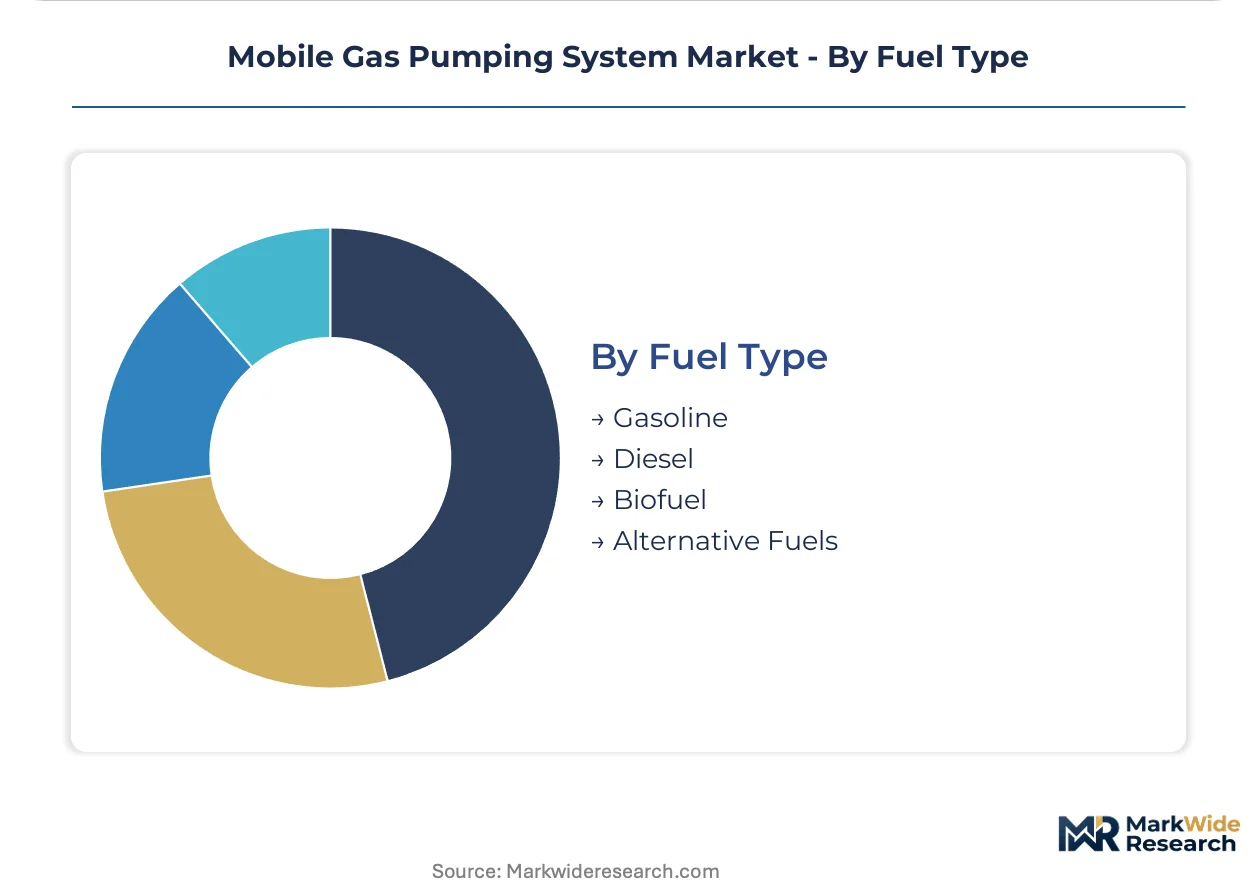
Fuel Type:
Margin structure varies sharply across fuel categories, with conventional products facing price pressure and certified alternatives commanding hardware premiums.
- Diesel:Construction and agricultural equipment refueling patterns sustain the largest volume flows. Off-road engine specifications and extended operational hours create predictable demand density for scheduled mobile routes.
- Biofuel:B20 and renewable diesel-compatible dispensing hardware carries certification requirements in California and Oregon. State-level low-carbon fuel standards create verified demand for compatible pumping configurations.
- Gasoline:Light-duty fleet and consumer vehicle refueling with established vapor recovery protocols.
- Alternative Fuels:Hydrogen, compressed natural gas, and emerging synthetic fuel handling equipment.
Diesel retains the deepest volume base; Biofuel climbs fastest from regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in the American Midwest and precision engineering centers in Northern Italy anchor equipment manufacturing for mobile fueling infrastructure. These localities supply corrosion-resistant tank assemblies and explosion-proof pump housings to regional assembly plants.
United States
Last-mile delivery density in Dallas-Fort Worth and California logistics corridors sustains subscription contract volumes for truck-mounted dispensing platforms. EPA Tier 4 emissions standards and CARB vapor recovery mandates create dual-compliance hardware specifications that fragment interstate operator inventories. Houston-based fabricators supply skid-mounted systems to Permian Basin oilfield contractors on 18-24 month lease structures.
Germany
Industrial machinery OEMs in Baden-Württemberg specify precision flow meters for integration with European fleet telematics platforms. REACH chemical safety regulations and ATEX explosion protection directives govern portable fuel transfer equipment certification. Munich-area engineering firms develop modular dispensing skids for construction sites across the Alpine region.
China
Domestic logistics fleet electrification is displacing diesel refueling demand in Yangtze River Delta distribution hubs. GB standards for hazardous materials transport and MIIT industrial equipment certifications shape mobile pumping system specifications. Shenzhen-based fabricators export cost-optimized electric pump assemblies to Southeast Asian mining operations.
Canada
Remote resource extraction in Alberta oil sands and British Columbia forestry operations sustains demand for skid-mounted dispensing units beyond grid infrastructure. Transport Canada TDG regulations and provincial workplace safety codes constrain hose handling protocols at customer sites. Calgary-based service providers deploy portable systems to seasonal agricultural operations across Prairie Provinces.
Mobile Gas Pumping System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fleet-specific service contracts and telematics integration. The vendor base stratifies across three maturity levels: legacy infrastructure manufacturers with portable product extensions, venture-backed fuel delivery platforms with proprietary routing algorithms, and regional fabrication shops with modular lease offerings. Three strategic archetypes dominate: equipment fabricators competing on certification breadth, service operators competing on delivery density, and hybrid providers bundling hardware with fuel supply. Consolidation pressure is accelerating through strategic partnerships between tank manufacturers and fleet management software providers.
Within the venture-funded service tier, Booster Fuels and Yoshi exemplify platform-based models that displace per-gallon transactional pricing with subscription structures. Gilbarco Veeder-Root occupies a position representing legacy infrastructure incumbents extending into portable equipment for remote industrial applications. These three anchors illustrate the competitive tension between asset-light service innovation and manufacturing-scale certification capabilities.
| Leading Market Players |
|---|
| Booster Fuels |
| Yoshi |
| Gilbarco Veeder-Root |
| Dover Fueling Solutions |
| Piusi |
| Filld |
| WeFuel |
| FuelGenie |
| EzFill Holdings |
| Others |
Supply & Pricing Matrix
Certified welders and explosion-proof electrical engineers in the American Midwest and Northern Italy anchor labor-cost differentials that spread pricing tiers between premium-certified fabricators and regional assembly shops. These skill concentrations compress margins at the standard tier while sustaining hardware premiums for CARB-compliant and ATEX-certified configurations.
Pricing Analysis
Warranty bundling and field-service contracts separate premium offerings from unbundled equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales coverage depth. Cost compression in the economy tier is intensifying because commodity volatility in stainless steel inputs squeezes skid-mounted fabricators. Mid-size fleet operators in the Dallas-Fort Worth corridor exhibit the highest price sensitivity, while municipal emergency services procurement shows the least.
Supply Chain Analysis
Domestic-content mandates in the United States and European Union are reshaping sourcing patterns for tank assemblies and pump housings. Supply concentrates in the United States, Germany, and China for corrosion-resistant fabrication and precision flow-meter engineering. Raw material dependencies include high-grade stainless steel, explosion-proof electric motors, and certified vapor-recovery hardware. Single-source vulnerability runs through specialty steel mills serving ATEX-certified fabricators. Distribution runs through OEM-direct channels for large fleet contracts and regional equipment distributors for mid-market construction and agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile gas pumping system market sits in a technology-transition phase as electric pump architectures displace pneumatic systems and battery-electric trucks threaten diesel refueling demand.
For Market Incumbents: Anticipate electrification substitution by securing backward integration into electric pump motor supply and expanding certification breadth for biofuel-compatible hardware. Fleet telematics integration represents a critical defensive lever against venture-backed service platforms. CARB dual-compliance burdens will consolidate interstate operators unable to absorb fragmented inventory costs. For New Entrants and Emerging Players: Proprietary routing algorithms offer a technology-first wedge into last-mile logistics density in underserved suburban corridors. White-space targets include rural industrial clusters in Montana and Wyoming lacking conventional retail fueling infrastructure. A subscription-based go-to-market model transfers inventory risk while locking multi-year volume commitments. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid providers bundling hardware with fuel supply given telematics-routing convergence and fleet management software integration. Long-term viability favors asset-light service platforms with recurring revenue structures over pure equipment fabricators facing electrification headwinds. Monitor state-level clean fuel standard expansion as the inflection signal for biofuel configuration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Routing Integration | Booster Fuels demonstrates how proprietary algorithms optimize tanker utilization in suburban commercial zones. |
| Biofuel Hardware Certification | California CARB mandates create verified demand for B20-compatible dispensing configurations. |
| Modular Skid Leasing Programs | North Dakota contractors adopt 18-24 month lease structures rather than capital purchases. |
| Explosion-Proof Electric Pump Development | Quieter nighttime refueling operations unlock noise-restricted commercial zone access. |
| Strategic Fleet Management Partnership | Third-party logistics providers in Texas consolidate vendor relationships under guaranteed price bands. |
Research Methodology
Trade association filings, EPA certification databases, and equipment manufacturer technical specifications formed the secondary backbone for market sizing and competitive mapping. Primary interviews with fleet operations directors, mobile fueling service executives, and tank fabrication plant managers provided demand-side validation. SEC disclosures and customs records supplemented bottom-up triangulation against top-down macroeconomic indicators.
Historical trendline analysis across equipment shipment records and fleet contract announcements established baseline growth patterns. The analytical framework modeled demand across product type, end user, installation configuration, and fuel specification dimensions throughout the forecast period. CAGRs were derived from regression analysis of segment-level volume trajectories, incorporating EPA regulatory phase-in schedules and state-level low-carbon fuel adoption curves as exogenous inputs.
Several conditions sit outside the modeled scope, including breakthrough battery-electric truck penetration rates beyond baseline assumptions and federal infrastructure spending reallocation toward charging networks. Forecasts reflect documented assumptions about fleet electrification timelines and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gasoline As a Fuel Market
Fuels
LNG Fueling Station Market
Fuels
Diesel Fuel Market
Fuels
Turbine Drip Oil Market
Fuels
Hydrogen Cylinder Market
Fuels
Coal Gasification Market
Fuels
North America Wood Pellet Market
Fuels
Singapore Bunker Fuel Market
Fuels
Renewable Heating Fuels Market
Fuels
Carbonizers Market
Fuels
Oil & Gas Lubricants Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Canada Bunker Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market